
 Air Duct Cleaning Chemicals Market | 2026-2036
Air Duct Cleaning Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Air Duct Cleaning Chemicals Market Outlook
North American specialty chemical producers is decoupling from generic janitorial supply chains as duct-specific formulations gain technical legitimacy. Abatement Technologies leverages its remediation heritage to anchor credibility in containment-grade cleaning protocols. Bio-Cide International sustains competitive differentiation through EPA-registered antimicrobial chemistries. W.W. Grainger controls distribution breadth, occupying a pivotal channel position between manufacturers and facility maintenance buyers.
Air duct cleaning chemicals comprise formulated solutions engineered to dissolve organic deposits, neutralize microbial colonization, and restore HVAC airflow efficiency without compromising polymer or metallic duct substrates; these products typically incorporate surfactant packages, quaternary ammonium compounds, or enzymatic active ingredients balanced for compatibility with galvanized steel, aluminum, and fiberglass ductboard. Their primary commercial purpose centers on maintaining thermal efficiency, preventing allergen recirculation, and extending mechanical system service life in climate-controlled environments. Biological cleaners and enzymatic formulations represent the fastest-expanding product category as facility managers prioritize non-corrosive, low-VOC maintenance protocols. The commercial application segment dominates current value generation, though residential retrofit activity is accelerating fastest where aging duct infrastructure coincides with heightened indoor air quality awareness.
EPA registration requirements govern antimicrobial claims and product labeling, compelling manufacturers to substantiate efficacy data through prescribed test protocols before interstate commerce. OSHA ventilation standards and the US Green Building Council's LEED v4.1 criteria further shape procurement specifications, particularly for federal and institutional contracts. State-level VOC regulations in California and the Northeast corridor add layered compliance complexity for multi-jurisdictional suppliers. Stakeholders must monitor evolving state adoption of EPA Safer Choice criteria and emerging ASHRAE guidance on chemical intervention frequency to anticipate procurement specification shifts.
Market Dynamics
EPA registration tightening for antimicrobial duct treatments is forcing specialty chemical producers to abandon generic janitorial formulations and invest in substrate-specific efficacy testing. This regulatory compression is reshaping competitive positioning toward technical legitimacy rather than commodity volume.
Growth Catalysts
- LEED v4.1 Criteria:Federal and institutional procurement specifications now mandate low-VOC cleaning protocols, accelerating specification upgrades in commercial building maintenance contracts.
- Enzymatic Formulation Chemistry:Biological cleaners with targeted enzymatic activity dissolve organic deposits without corroding galvanized steel or fiberglass ductboard substrates.
- Sun Belt HVAC Utilization:Heavy cooling demand across Arizona, Texas, and Florida concentrates duct cleaning frequency and chemical consumption in climate-stressed infrastructure.
Market Restraints
- Quaternary Ammonium Compound Input Costs:Petrochemical feedstock volatility compresses margin stability for antimicrobial formulation producers.
- California VOC Regulations:State-level emission limits in the CARB regulatory zone force multi-jurisdictional suppliers to maintain separate product SKUs.
- Mechanical Agitation Substitution:Dry ice blasting and robotic duct cleaning systems displace chemical-dependent maintenance in high-value commercial installations.
Strategic Opportunities
- Residential Retrofit Channel:Aging duct infrastructure in 1970s-1990s housing stock coincides with heightened indoor air quality awareness among homeowners.
- ASHRAE Chemical Intervention Guidance:Emerging standards on cleaning frequency create specification pull-through for registered treatment protocols.
- EPA Safer Choice Adoption:State procurement offices are integrating federal safer chemistry criteria into multi-year facilities maintenance contracts.
Industry Challenges
- Substrate Compatibility Certification:Formulators must validate non-corrosive performance across galvanized steel, aluminum, and fiberglass ductboard variants.
- Application Technician Training Gap:Proper dilution ratios and dwell times for enzymatic cleaners require skilled deployment absent in generic janitorial workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air Duct Cleaning Chemicals Market |
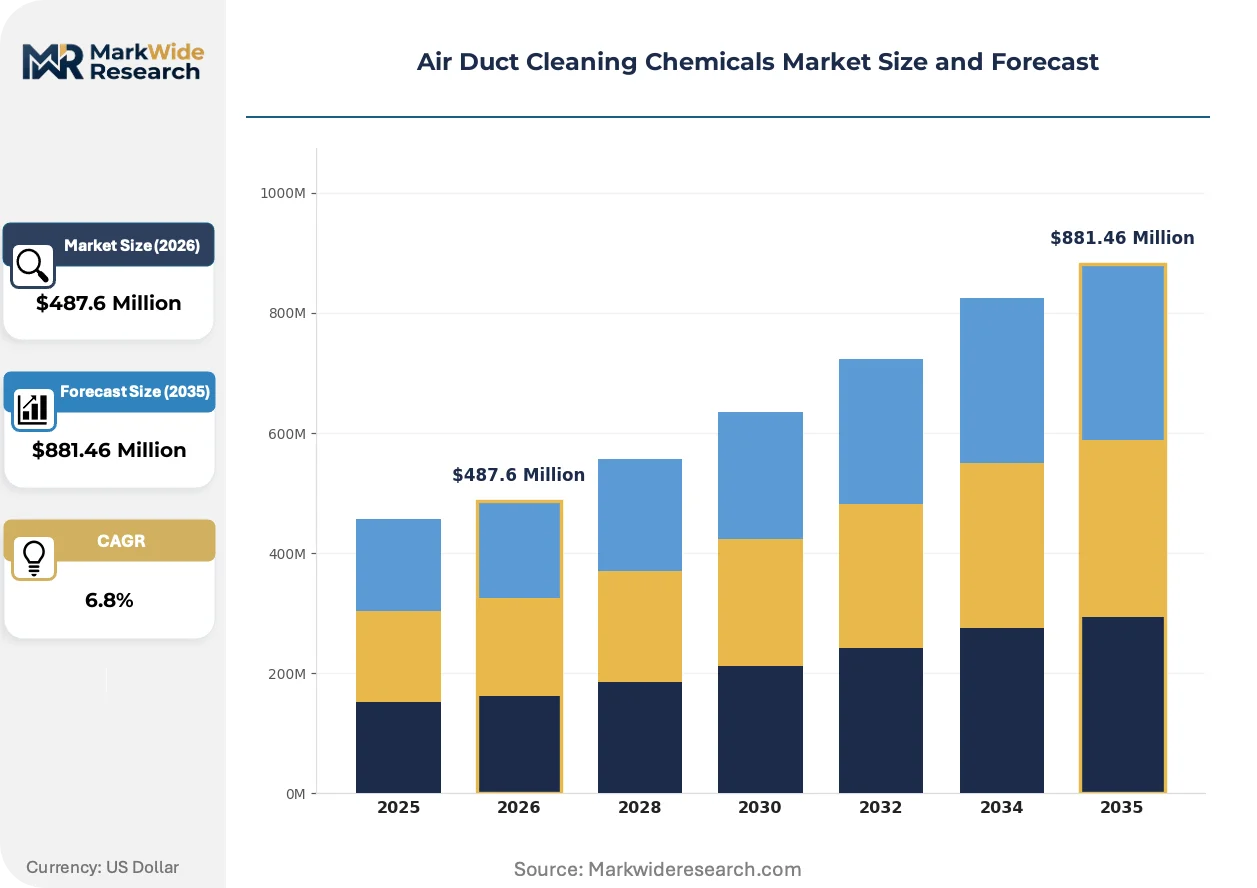
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biological Cleaners, Solvents, Foaming Agents, Enzymatic Cleaners Application: Commercial, Residential, Industrial, HVAC Systems Form: Liquid, Gel, Powder, Spray Certification: EPA Registered, Eco-Friendly, VOC Compliant, Biodegradable |
| Companies Covered | Abatement Technologies, W.W. Grainger, Bio-Cide International, Rotobrush International, Ductworks, Water Treatment Products, ComStar International, OdorX, Heat Seal Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Duct Cleaning Chemicals Market Strategic Shifts
Formulation science is modularizing around substrate-specific compatibility matrices rather than universal cleaning claims. Technical differentiation now centers on polymer-safe enzymatic packages and metallic corrosion inhibition.
Encapsulated enzyme delivery systems are modularizing application protocols for facility maintenance teams. Property management firms operating multi-site portfolios are adopting pre-measured dosing formats to standardize technician deployment. This modularization is compressing the service window between chemical application and system restart, reducing HVAC downtime penalties in commercial environments.
REACH authorization requirements for biocidal active substances are filtering duct treatment chemistries available to EU commercial building operators. Formulators must now submit comprehensive dossiers on human toxicity and environmental fate. German and French facility managers are prioritizing suppliers with pre-registered substance portfolios to avoid supply interruption.
Building engineers are consolidating vendor relationships around single-source chemical and equipment providers. W.W. Grainger's channel position between manufacturers and maintenance buyers is capturing specification influence previously held by regional distributors. This concentration is most visible in federal and institutional contracts where procurement compliance complexity favors integrated supply arrangements.
Air Duct Cleaning Chemicals Market Segmentation
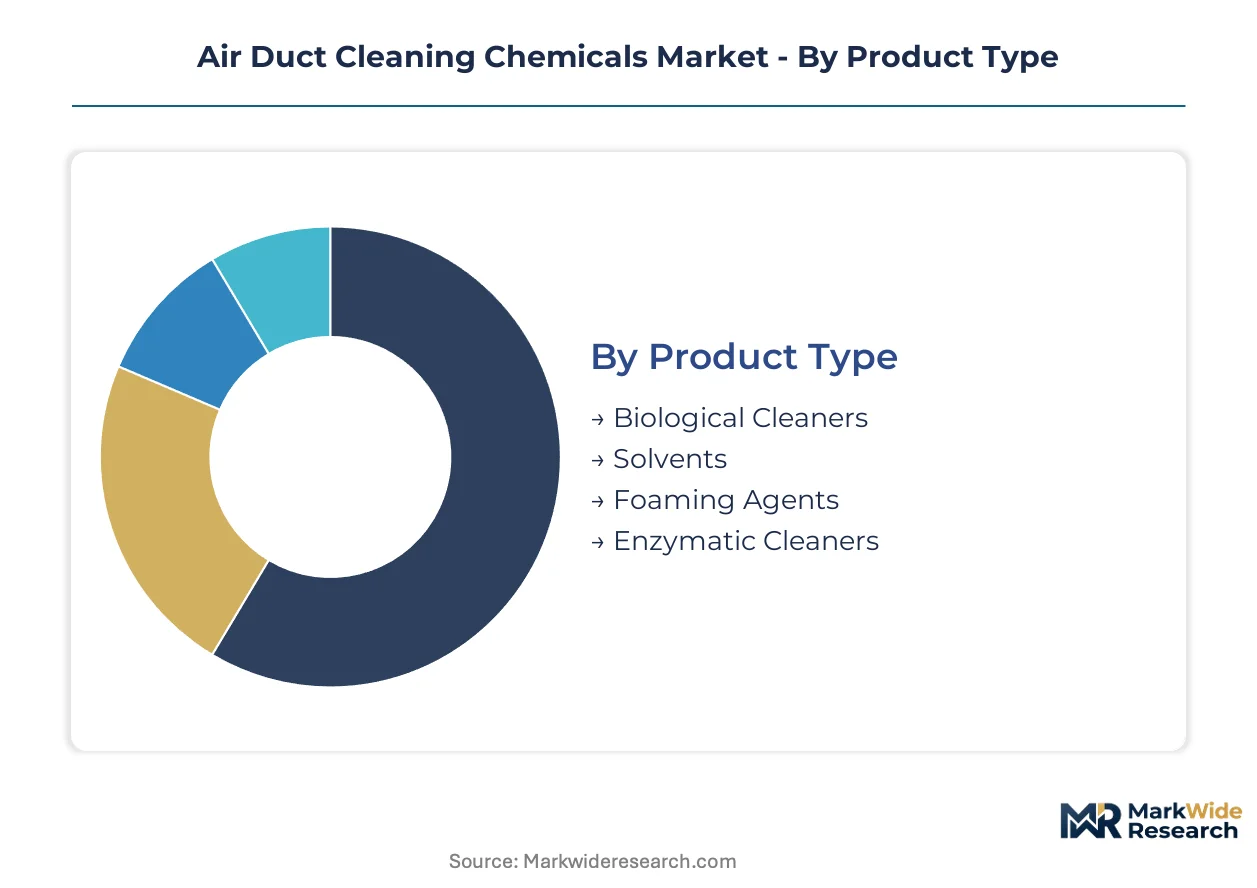
Air duct cleaning chemicals segment across formulation chemistry, deployment setting, physical state, and regulatory compliance tier. Procurement specifications vary sharply between federal institutional contracts and residential retrofit channels.
Product Type:
Volume concentrates in commodity formulations while premium pricing attaches to EPA-validated specialty chemistries.
- Biological Cleaners:Formulations leverage bacterial cultures and bio-surfactants to digest organic deposits without mechanical agitation. Demand clusters in LEED-certified commercial buildings across California and the Northeast corridor where VOC restrictions are strictest.
- Enzymatic Cleaners:Targeted protease and lipase enzymes break down protein-based contaminants and grease accumulations in fiberglass ductboard. Arizona and Texas facility managers specify these for high-velocity cooling systems where corrosion inhibition is critical.
- Solvents:Petrochemical-derived formulations dissolve heavy hydrocarbon deposits in industrial ventilation.
- Foaming Agents:Expandable chemical carriers maximize contact time on vertical duct surfaces.
Mature deployment sits with Solvents. Newer deployment is concentrated in Enzymatic Cleaners.
Application:
Customer type separates scheduled maintenance contracts from reactive remediation engagements.
- Commercial:Office complexes, healthcare facilities, and educational institutions drive recurring procurement through multi-year facilities management contracts. Federal building operators mandate EPA-registered treatments under procurement specifications tied to LEED v4.1 criteria.
- Residential:Single-family retrofits target aging duct infrastructure in 1970s-1990s housing stock. Florida and Arizona homeowners accelerate adoption following heightened indoor air quality awareness post-respiratory health events.
- Industrial:Manufacturing ventilation and process exhaust systems require heavy-duty deposit removal.
- HVAC Systems:Dedicated heating, ventilation, and air conditioning infrastructure spans all building categories.
Established revenue sits with Commercial. Steepest expansion trajectory is concentrated in Residential.
Form:
Physical state determines application equipment requirements and technician skill thresholds.
- Liquid:Pump-spray and injection-applied solutions dominate commercial service workflows. Standardized dilution protocols suit high-volume deployment across multi-site property portfolios.
- Spray:Aerosolized and trigger-spray formats accelerate residential technician productivity. Pre-measured dosing reduces training burden for independent contractors.
- Gel:Thickened formulations cling to overhead surfaces without runoff.
- Powder:Concentrated dry blends require on-site reconstitution.
Operational scale sits with Liquid. Technician convenience is driving Spray adoption.
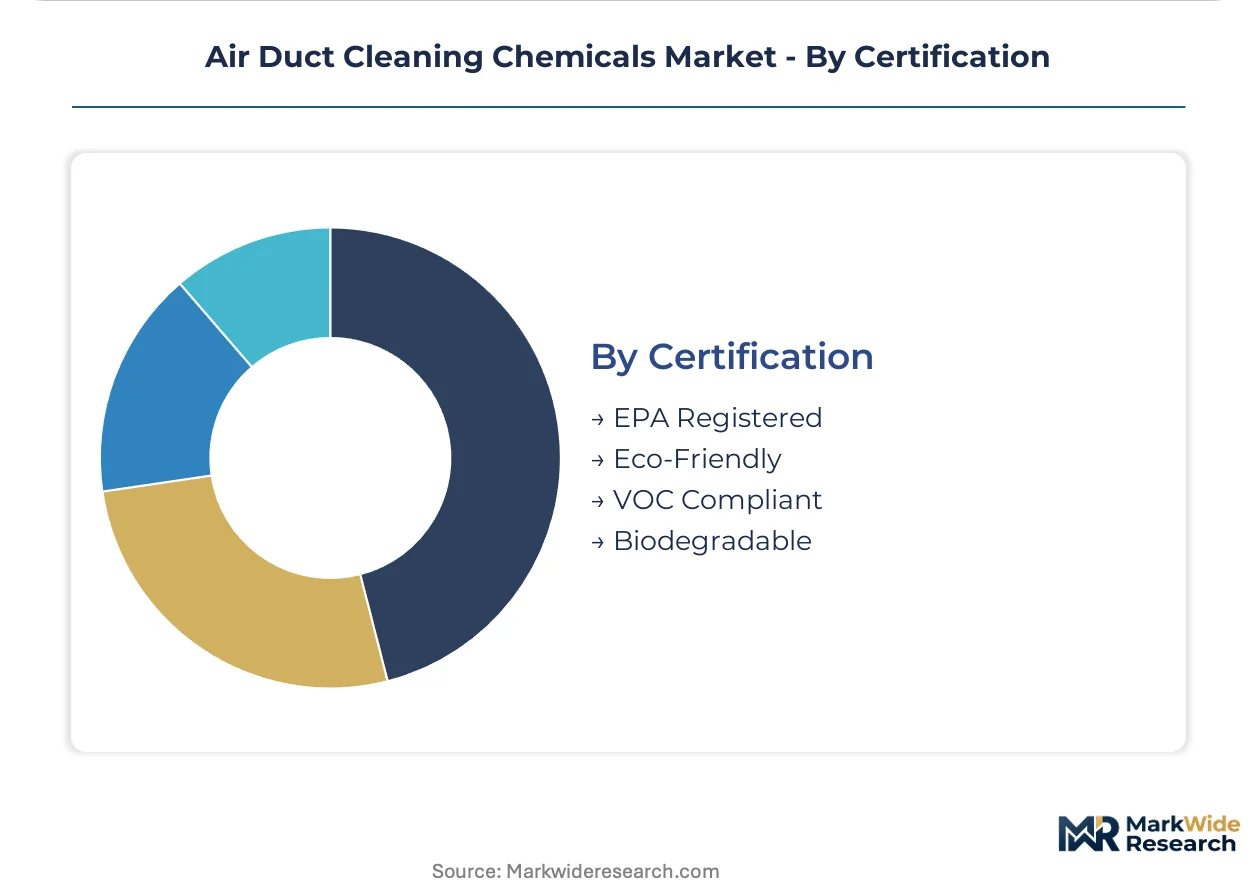
Certification:
Margin tier separates compliance-mandated registrations from voluntary sustainability claims.
- EPA Registered:Antimicrobial products undergo prescribed efficacy testing for interstate commerce eligibility. Federal and institutional procurement specifications exclude non-registered alternatives.
- Eco-Friendly:Third-party environmental certifications support voluntary sustainability commitments. Corporate facility managers specify these for ESG reporting alignment.
- VOC Compliant:Formulations meet California Air Resources Board and Northeast state emission limits.
- Biodegradable:Degradation testing documentation supports environmental discharge claims.
Procurement mandate sits with EPA Registered. Specification pull-through is concentrating in Eco-Friendly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability in the US Gulf Coast anchors formulation supply for North American duct cleaning chemical producers. Regional demand concentrates in Sun Belt states with intensive cooling loads. European REACH compliance costs and Asian manufacturing scale complete the tripolar supply picture.
United States
Commercial building stock in Arizona, Texas, and Florida drives concentrated chemical consumption for high-velocity HVAC maintenance. EPA registration requirements for antimicrobial claims tighten formulation standards and exclude non-compliant imports. Houston and Dallas-Fort Worth metropolitan areas host the densest clusters of specialty chemical blending facilities serving regional duct service contractors.
Germany
Industrial ventilation systems in automotive manufacturing and precision engineering sustain demand for heavy-duty deposit removal chemistries. ECHA REACH authorization requirements for biocidal active substances filter available product portfolios and elevate compliance costs for formulators. The Rhine-Ruhr industrial corridor concentrates facility management procurement for integrated chemical and equipment supply contracts.
China
Rapid commercial construction in Yangtze River Delta and Pearl River Delta cities expands addressable building stock for duct maintenance protocols. GB standards for indoor air quality and HVAC hygiene create emerging regulatory pressure on property managers. Shanghai and Shenzhen municipal governments pilot green building certification schemes that reference low-VOC cleaning specifications.
Canada
Cold climate heating infrastructure in Ontario and Quebec sustains seasonal duct cleaning cycles distinct from US cooling-dominated patterns. Health Canada and PMRA oversight of antimicrobial products parallels EPA registration requirements with additional bilingual labeling mandates. Toronto and Vancouver metropolitan areas concentrate commercial property management procurement for multi-site maintenance contracts.
United Kingdom
Heritage building ventilation retrofits in London and Southeast England create specialized demand for non-corrosive formulations compatible with aging metallic ductwork. HSE ventilation standards and emerging post-Brexit chemical regulation divergence shape procurement specifications. The M25 corridor clusters facilities management firms serving institutional clients with integrated compliance documentation requirements.
Air Duct Cleaning Chemicals Market Competitive Environment
Global majors compete with regional champions across formulation chemistry and distribution channel access. The vendor base organizes around three tiers: integrated chemical-equipment providers, specialty formulation houses with regulatory registrations, and commodity janitorial suppliers losing share to substrate-specific products. Consolidation pressure concentrates among distributors seeking specification influence in federal procurement channels. Strategic moves center on EPA registration acquisition and multi-site service contract bundling.
Within the remediation-heritage tier, Abatement Technologies occupies a position exemplifying containment-grade protocol credibility. Bio-Cide International and W.W. Grainger represent contrasting archetypes: the former anchors competitive differentiation through registered antimicrobial chemistries, while the latter controls distribution breadth between manufacturers and facility maintenance buyers. These three names illustrate how technical legitimacy, regulatory compliance, and channel scale constitute distinct vectors for market position.
| Leading Market Players |
|---|
| Abatement Technologies |
| W.W. Grainger |
| Bio-Cide International |
| Rotobrush International |
| Ductworks |
| Water Treatment Products |
| ComStar International |
| OdorX |
| Heat Seal Equipment |
| Others |
Value Chain & Pricing Dynamics
Captive blending capacity in the US Gulf Coast anchors both supply security and pricing power for North American formulators, insulating registered producers from import volatility while compressing margin flexibility for non-integrated competitors. EPA registration costs create fixed barriers that favor volume-scale players with dedicated technical staff, concentrating pricing leverage among incumbent specialty houses.
Pricing Analysis
Warranty-backed application protocols separate premium EPA-registered treatments from unbundled commodity alternatives. Three-tier pricing structure across containment-grade, commercial-standard, and economy janitorial levels reflects certification investment and substrate-testing depth. Cost compression in the economy tier intensifies because mechanical agitation substitutes displace chemical-dependent maintenance in high-value installations. Federal procurement offices show least price sensitivity due to LEED compliance mandates, while independent residential contractors exhibit highest sensitivity to per-gallon differentials.
Supply Chain Analysis
EPA registration and state VOC compliance gating filter supplier eligibility before volume procurement decisions. Active ingredient sourcing concentrates in the United States, Germany, and China, with quaternary ammonium compound feedstocks drawing from Gulf Coast petrochemical complexes. Supply chain risk centers on single-source vulnerability for EPA-registered antimicrobial actives subject to re-registration delays. Distribution runs through integrated industrial supply houses and specialized HVAC service distributors rather than generic janitorial channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure is intensifying as EPA registration tightening forces commodity janitorial suppliers to exit or acquire technical capabilities, eliminating undifferentiated competitors from federal procurement channels.
For Market Incumbents: Lock in specification influence through backward integration into encapsulated enzyme delivery systems and pre-measured dosing format manufacturing. Secure multi-year federal facilities contracts before ASHRAE guidance formalizes cleaning frequency standards that will favor established registrants with validated protocols. For New Entrants and Emerging Players: Launch via direct-to-residential-technician digital channels targeting Arizona and Florida homeowners with pre-diluted spray formats that reduce training burden. Target the residential retrofit segment where aging duct infrastructure and heightened indoor air quality awareness create specification whitespace absent entrenched vendor relationships. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated industrial distributors seeking EPA registration portfolios and Sun Belt service contract density. Long-term viability favors formulators with pre-registered substance dossiers under REACH and PMRA parallel pathways. Watch state adoption velocity of EPA Safer Choice criteria as the inflection signal for procurement specification shifts in institutional channels.| Strategic Initiative | Industry Significance |
|---|---|
| EPA Registration Acquisition | Regulatory asset purchase accelerates interstate commerce eligibility for antimicrobial claims. |
| Encapsulated Enzyme Manufacturing Scale-Up | Proprietary delivery technology reduces HVAC downtime penalties in commercial service contracts. |
| Multi-Site Service Contract Bundling | Integrated chemical-equipment provisioning captures specification influence in federal procurement. |
| State VOC Compliance SKU Rationalization | Unified formulation platforms reduce manufacturing complexity across CARB and Northeast jurisdictions. |
| Residential Direct Channel Launch | Pre-measured spray formats bypass distributor markup and accelerate independent technician adoption. |
Study Parameters
Multi-period observation of EPA registration timelines, state VOC adoption patterns, and HVAC service contract award flows anchored the trend analysis, supplemented by interviews with specialty chemical plant managers, federal facilities procurement officers, HVAC service contractor owners, and industrial distribution channel partners. Secondary validation drew from EPA registration databases, OSHA ventilation standard dockets, USGBC LEED project directories, and ACC specialty chemical shipment reports. Bottom-up volume estimates triangulated against top-down building stock and maintenance frequency assumptions.
Input-output matrices mapped formulation chemistry grades to end-use application settings, deployment form factors, and regional regulatory compliance tiers across the projection horizon. CAGRs derived from segment-level volume build-ups incorporating HVAC utilization intensity by climate zone and procurement specification evolution under ASHRAE guidance. Forecast inputs included petrochemical feedstock price indices and federal building maintenance budget appropriation trends.
EPA registration delays, REACH authorization disruptions for biocidal actives, and mechanical agitation technology cost reductions are the dominant revision risks to volume and value projections. Forecasts reflect assumptions about regulatory enforcement continuity and climate-driven HVAC utilization patterns. A model refresh is warranted upon material change in ASHRAE chemical intervention frequency standards or state Safer Choice procurement mandate adoption velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Southeast Asia Surface Treatment Chemicals Market
Cleaning Chemicals
Dry Cleaning Solvents Market
Cleaning Chemicals
Concentrated Laundry Powder Market
Cleaning Chemicals
Global Antiseptic Products Market
Cleaning Chemicals
Document Cleaning Powder Market
Cleaning Chemicals
Latin America Detergent Market
Cleaning Chemicals
Biodegradable Spray Tank Line-Cleaning Chemistry Market
Cleaning Chemicals
Dry Electrostatic Wipes Market
Cleaning Chemicals
Low-Foaming Detergent Market
Cleaning Chemicals
Water Soluble Detergent Pods Market
Cleaning Chemicals
North America Metal Cleaning Chemicals Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Multi-Residue Detoxifying Field Wash Aid Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Sanitizing Agents Market