
 Sanitizing Agents Market | 2026-2036
Sanitizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Sanitizing Agents Market Analysis
Refillable concentrate systems paired with reusable dispensers is pivoting procurement economics for institutional buyers. Ecolab leverages its captive service network to lock in multi-year healthcare contracts. Procter and Gamble sustains consumer loyalty through fragrance-differentiated formulations. STERIS dominates sterile manufacturing environments with vapor-phase hydrogen peroxide systems.
Sanitizing agents are chemical formulations designed to reduce microbial populations on surfaces to safe levels, typically achieving a five-log reduction of specified pathogens within thirty seconds to five minutes of contact time. These agents serve critical functions in interrupting disease transmission chains across food preparation zones, clinical settings, and high-traffic public infrastructure. Liquid sanitizers occupy the largest volume share due to compatibility with automated dispensing equipment and fogging protocols. Quaternary ammonium compounds are gaining formulation share in food processing lines where chlorine corrosion poses equipment risks. Healthcare applications command premium pricing tiers driven by sporicidal validation requirements and Joint Commission audit standards.
The EPA regulates surface disinfectant and sanitizer efficacy claims through its pesticide registration framework under FIFRA, requiring substantiated kill claims against labeled organisms. EMA and national competent authorities enforce biocidal product authorization under BPR for European commercialization, creating dual-track compliance burdens for multinational suppliers. FDA oversight of sanitizers used on food-contact surfaces adds a third regulatory layer with specific residue tolerance thresholds. Stakeholders must monitor evolving pathogen-specific emergency use authorizations and prequalification pathways that reshape competitive access to institutional procurement channels.
Market Dynamics
Healthcare procurement centralization is compressing vendor margins while elevating efficacy documentation burdens. Institutional buyers in the United States, Germany, and India now mandate multi-pathogen validation data as table stakes for contract eligibility, forcing formulation suppliers to absorb preclinical testing costs upfront.
Growth Catalysts
- WHO Prequalification Schemes:International health agencies are prioritizing prequalified sanitizers for pandemic stockpiles, opening procurement channels for validated suppliers across low- and middle-income health systems.
- Food Processing Equipment Corrosion:Quaternary ammonium compounds are displacing chlorine-based formulations in beverage canning lines where metal degradation threatens line uptime and capital replacement cycles.
- Joint Commission Audit Standards:US hospital accreditation requirements now embed sporicidal efficacy into environmental services scorecards, expanding addressable demand for validated hydrogen peroxide and peracetic acid systems.
Market Restraints
- Isopropyl Alcohol Feedstock Volatility:Sanitizer manufacturers face margin compression when petrochemical supply disruptions spike input costs for alcohol-based formulations.
- Chinese Quaternary Ammonium Concentrate Dominance:Overreliance on Zhejiang and Jiangsu province suppliers for QAC active ingredients creates geographic concentration risk during export license delays.
- BPR Authorization Timelines:ECHA's biocidal product review queue stretches 18-36 months for novel actives, freezing commercialization timelines for European market entry.
Strategic Opportunities
- Indian Food Safety and Standards Authority Mandates:FSSAI's expanding hygienic processing rules for dairy and meat plants creates regulatory tailwinds for validated sanitizer suppliers in underpenetrated cold chain infrastructure.
- Electrostatic Sprayer Convergence:Pairing charged droplet application systems with low-volume concentrate chemistries enables fogging protocols that reduce labor hours per square meter in aviation and transit terminals.
- Direct Institutional E-Procurement:State hospital purchasing cooperatives in Maharashtra and Karnataka are piloting digital tender platforms that disintermediate traditional distribution layers for bulk sanitizer contracts.
Industry Challenges
- EPA Pesticide Registration Data Requirements:New molecular entities require multi-year Good Laboratory Practice toxicology studies, stretching R&D-to-revenue timelines and demanding specialized regulatory affairs talent scarce outside Washington DC consulting clusters.
- Legacy Dispenser Infrastructure Incompatibility:Concentrate dilution systems often fail to integrate with installed base sensor-activated wall units, forcing capital-intensive retrofit decisions or formulation compromise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sanitizing Agents Market |
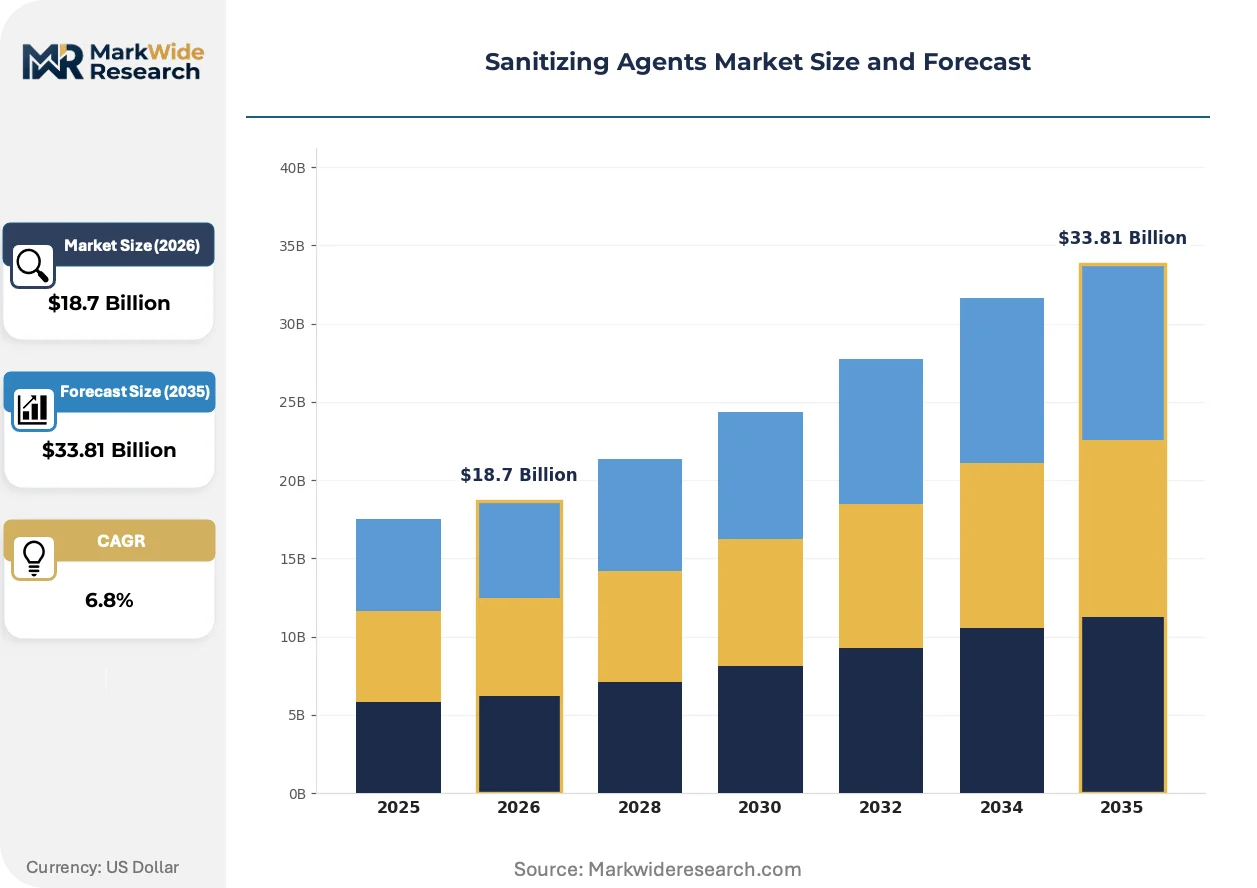
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Sanitizers, Foam Sanitizers, Wipes, Gels Active Ingredient: Alcohol, Hydrogen Peroxide, Quaternary Ammonium Compounds, Sodium Hypochlorite Application: Household Use, Healthcare Facilities, Food Industry, Personal Care Packaging Type: Spray Bottles, Bulk Containers, Sachets, Pump Bottles |
| Companies Covered | Ecolab, Procter and Gamble, The Clorox Company, STERIS, Reckitt Benckiser Group, 3M, SC Johnson Professional, Diversey, GOJO Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sanitizing Agents Market Emerging Trajectories
Electrostatic and ultrasonic application hardware is compressing contact time requirements while elevating coverage uniformity standards. Formulation chemists now optimize surface wetting properties for charged droplet physics rather than manual wipe protocols alone.
Peracetic acid vapor systems are electrifying terminal sterilization workflows in pharmaceutical aseptic filling suites. Contract manufacturing organizations are retrofitting isolator lines to accommodate vapor-phase protocols that eliminate manual surface disinfection steps. This electrifying shift is collapsing validation documentation burdens while reducing human intervention in Grade A environments.
REACH restriction proposals targeting quaternary ammonium compound ecotoxicity are forcing formulation pivots ahead of 2026 sunset reviews. Suppliers are accelerating alcohol-peroxide hybrid development to preempt authorization withdrawals. European food processing and institutional cleaning segments are most exposed, with Nordic buyers already demanding biodegradable surfactant alternatives in tender specifications.
Hospital environmental services departments are consolidating purchase authority into centralized value analysis committees. Traditional distributor relationships are yielding to direct manufacturer contracting with multi-year service bundles. This concentration is most visible in German Krankenhaus procurement networks and US health system GPO affiliates, where vendor consolidation favors suppliers with captive technical service organizations.
Sanitizing Agents Market Segmentation
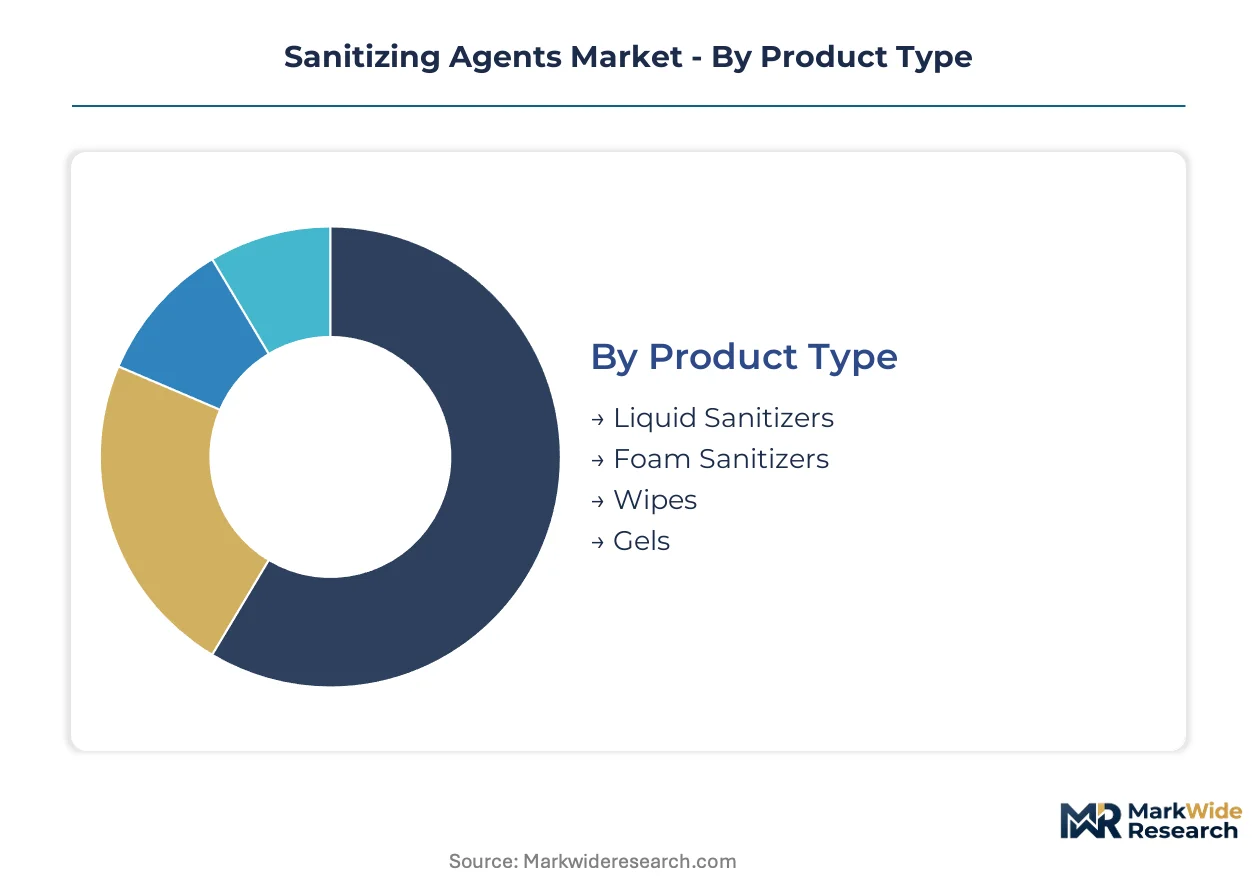
Sanitizing agents fragment across formulation physics, active chemistry, and deployment context. Procurement centralization in healthcare and food processing is collapsing SKU proliferation while elevating specification discipline across every segment boundary.
Product Type:
Supply concentration favors formats compatible with automated dispensing infrastructure and electrostatic application hardware.
- Liquid Sanitizers:Water-based formulations with optimized surface wetting properties dominate institutional procurement due to fogging protocol compatibility. German hospital GPOs and Indian state purchasing cooperatives now mandate liquid concentrate systems for multi-year contracts.
- Foam Sanitizers:Viscous formulations extend contact time on vertical surfaces and equipment crevices. Food processing plants in Maharashtra and Karnataka specify foam protocols for conveyor sanitization where drip-off compromises line hygiene.
- Wipes:Pre-saturated substrates serve point-of-care clinical workflows and aviation cabin turnover. EPA registration requirements for wipe substrates add compliance layers beyond the active chemistry alone.
- Gels:Thickened alcohol or quaternary ammonium formulations target hand hygiene protocols in personal care and household segments. Pump dispenser compatibility constraints limit gel adoption in automated institutional settings.
Today's leader: Liquid Sanitizers. Tomorrow's challenger: Foam Sanitizers.
Active Ingredient:
Cost tier stratification separates commodity alcohol formulations from premium sporicidal systems with validation documentation burdens.
- Alcohol:Ethanol and isopropanol formulations deliver rapid kill kinetics against enveloped viruses. Feedstock volatility from petrochemical supply disruptions compresses manufacturer margins during energy price spikes.
- Hydrogen Peroxide:Oxidative chemistry achieves sporicidal efficacy without persistent residue. Vapor-phase systems from STERIS dominate pharmaceutical aseptic filling suites where manual disinfection steps threaten Grade A environmental classification.
- Quaternary Ammonium Compounds:Surface-active cationic biocides displace chlorine in beverage canning lines where metal corrosion threatens capital equipment life. REACH restriction proposals targeting QAC ecotoxicity are forcing European formulation pivots ahead of authorization reviews.
- Sodium Hypochlorite:Chlorine-based chemistry retains cost advantage in municipal water treatment and mass-market household applications. Corrosion limitations exclude hypochlorite from stainless steel food processing infrastructure.
Alcohol commands volume leadership. Hydrogen peroxide climbs the fastest on sporicidal validation premiums.
Application:
Customer type divergence separates price-sensitive household procurement from specification-driven institutional tenders with multi-year service bundles.
- Healthcare Facilities:Joint Commission audit standards and Joint Commission International accreditation embed sporicidal efficacy into environmental services scorecards. US health systems and German Krankenhaus networks consolidate purchase authority into value analysis committees favoring suppliers with captive technical service organizations.
- Food Industry:FSSAI hygienic processing mandates for dairy and meat cold chain infrastructure create regulatory tailwinds in underpenetrated Indian states. Quaternary ammonium formulations gain share where chlorine corrosion threatens line uptime.
- Household Use:Fragrance differentiation and pump dispenser ergonomics drive consumer loyalty in retail channels. Procter and Gamble sustains position through brand equity and formulation sensorial properties.
- Personal Care:Hand sanitization protocols in hospitality and corporate settings demand portable formats with skin conditioning additives. Post-pandemic inventory normalization has compressed spot purchase premiums in this segment.
Healthcare Facilities anchor premium pricing. Food Industry offers steepest expansion trajectory on regulatory mandate acceleration.
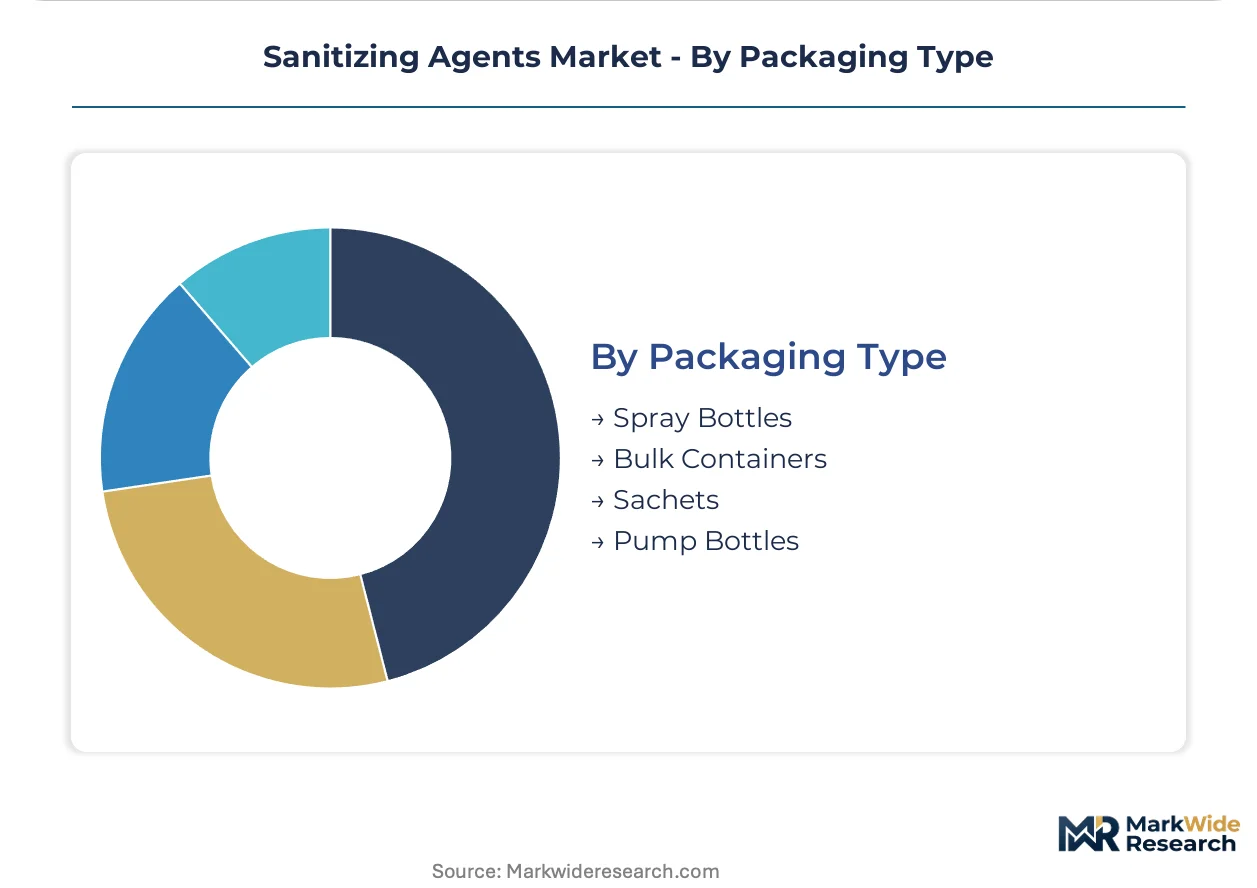
Packaging Type:
Volume scale separates bulk concentrate procurement for institutional dilution systems from single-use convenience formats.
- Bulk Containers:Concentrate systems paired with reusable dispensers pivot procurement economics for institutional buyers. Ecolab leverages captive service networks to lock multi-year healthcare contracts with dilution control hardware.
- Spray Bottles:Trigger-actuated formats serve household and light commercial surface applications. Electrostatic sprayer convergence is displacing manual spray protocols in aviation and transit terminal fogging operations.
- Pump Bottles:Metered dose dispensers dominate hand hygiene stations in corporate and hospitality settings. Sensor-activated wall unit incompatibility with concentrate systems forces capital-intensive retrofit decisions.
- Sachets:Single-use pouches serve travel, field deployment, and emergency stockpile applications. WHO prequalification schemes prioritize sachet formats for pandemic response logistics in low- and middle-income health systems.
Bulk Containers dominate institutional procurement. Sachets gain share on emergency preparedness mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern sanitizing agents industry traces its commercial origins to nineteenth-century European chemical manufacturing, with German industrial clusters pioneering phenol-based antiseptic formulations before American and Asian production centers scaled alcohol and quaternary ammonium chemistry for mass institutional deployment.
United States
Hospital procurement centralization through group purchasing organizations drives specification discipline, with Joint Commission audit standards embedding sporicidal efficacy into environmental services contracts. EPA pesticide registration under FIFRA mandates substantiated kill claims against labeled organisms, creating compliance barriers for novel molecular entities. Cincinnati and St. Paul anchor captive technical service networks that lock multi-year healthcare contracts through dilution control hardware bundles.
Germany
Krankenhaus procurement networks consolidate purchase authority into value analysis committees favoring suppliers with integrated service organizations. ECHA biocidal product authorization under BPR stretches commercialization timelines for European market entry. The Rhine-Ruhr industrial corridor concentrates formulation manufacturing for beverage canning lines where quaternary ammonium compounds displace chlorine to prevent metal corrosion.
India
FSSAI hygienic processing mandates for dairy and meat cold chain infrastructure create regulatory tailwinds in underpenetrated states. State hospital purchasing cooperatives in Maharashtra and Karnataka pilot digital tender platforms that disintermediate traditional distribution layers. Mumbai and Pune industrial zones concentrate contract manufacturing for concentrate systems paired with reusable dispensers.
China
Zhejiang and Jiangsu province suppliers dominate quaternary ammonium concentrate production, creating geographic concentration risk during export license delays. MEE environmental standards tighten effluent discharge requirements for active ingredient manufacturing. The Yangtze River Delta clusters bulk alcohol formulation capacity serving both domestic institutional procurement and export markets.
Brazil
ANVISA pharmaceutical and sanitary surveillance standards elevate documentation burdens for hospital-grade formulation commercialization. Food processing expansion in São Paulo and Minas Gerais states drives demand for corrosion-resistant sanitizers in beverage packaging infrastructure. The São Paulo metropolitan corridor anchors Latin American distribution networks for multinational suppliers seeking regional manufacturing presence.
Sanitizing Agents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across validation documentation and captive service bundling. The vendor base stratifies into three tiers: multinational chemical conglomerates with integrated healthcare service networks, consumer goods specialists with fragrance-differentiated retail positioning, and regional concentrate suppliers competing on bulk pricing for institutional tenders. Dominant competitive moves include multi-year contract lock-ins through dilution hardware deployment and geographic expansion via direct institutional e-procurement platform integration.
Among multinational service-integrated suppliers, Ecolab and STERIS exemplify the premium-tier archetype through captive technical service organizations. Procter and Gamble occupies a distinct consumer-facing position sustained by brand equity and formulation sensorial properties. The Clorox Company and Reckitt Benckiser Group sit within the household and institutional hybrid tier, while 3M and SC Johnson Professional represent diversified chemical conglomerates with sanitizing agents as one vertical within broader portfolios.
| Leading Market Players |
|---|
| Ecolab |
| Procter and Gamble |
| The Clorox Company |
| STERIS |
| Reckitt Benckiser Group |
| 3M |
| SC Johnson Professional |
| Diversey |
| GOJO Industries |
| Others |
Supply Flow & Price Mechanics
Sporicidal validation premiums separate hospital-grade hydrogen peroxide systems from commodity alcohol formulations, compressing procurement economics for institutional buyers while elevating supplier margins for EPA-registered actives with documented kill claims. This bifurcation concentrates pricing power with Ecolab and STERIS in United States health system GPOs, while Chinese quaternary ammonium concentrate suppliers compete on bulk tenders for Indian food processing contracts.
Pricing Analysis
Three-tier pricing structure across premium sporicidal, standard institutional, and economy household levels dominates the sanitizing agents landscape. Price differentiation rests on EPA registration tier and Joint Commission validation documentation, with healthcare facilities absorbing premium markups for vapor-phase hydrogen peroxide systems. Cost compression in alcohol-based formulations intensifies because isopropyl feedstock volatility from petrochemical supply disruptions squeezes manufacturer margins. Household consumers exhibit highest price sensitivity, while German Krankenhaus value analysis committees prioritize efficacy documentation over unit cost.
Supply Chain Analysis
Direct-to-institutional channels handle hyperscale healthcare and food processing procurement, displacing traditional distribution layers in Maharashtra and Karnataka state hospital cooperatives. Active ingredient manufacturing concentrates in China, Germany, and India, with Zhejiang and Jiangsu province suppliers dominating quaternary ammonium concentrate production. Raw material dependencies draw from petrochemical ethanol streams, peroxide precursor chemicals, and palm-derived surfactants. Single-source vulnerability from Chinese export license delays threatens formulation continuity for European and Asian contract manufacturers. Distribution runs through captive technical service networks for premium-tier suppliers and digital tender platforms for emerging market institutional buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sanitizing agents market functions as a regulatory compounder where EPA emerging pathogen protocols and WHO prequalification schemes continuously reset competitive access thresholds, elevating demand for validated suppliers with documented multi-pathogen efficacy.
For Market Incumbents: Cement multi-year contract lock-ins through dilution control hardware deployment in United States health system GPOs and German Krankenhaus networks. Deepen backward integration into quaternary ammonium active ingredient production to offset Chinese supply concentration risk. Prioritize captive technical service organization expansion as defensive moat against emerging electrostatic application hardware entrants. For New Entrants and Emerging Players: Launch via direct institutional e-procurement platform integration targeting underpenetrated Indian state hospital purchasing cooperatives in Maharashtra and Karnataka. Focus initial penetration on FSSAI-mandated dairy and meat cold chain infrastructure where validated supplier scarcity creates procurement gaps. Pursue white-label concentrate formulation partnerships with established contract manufacturers to bypass EPA registration timeline barriers. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH restriction proposals threaten quaternary ammonium authorization withdrawals across European food processing segments. Long-term viability favors suppliers with hybrid alcohol-peroxide development pipelines and biodegradable surfactant alternatives. Target acquisition archetype: regional concentrate suppliers with FSSAI validation and existing Indian state tender relationships. Monitor ECHA biocidal product review queue velocity as inflection indicator for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Active Ingredients | Captive supply of quaternary ammonium compounds insulates margins from Chinese export license volatility. |
| EPA Emerging Pathogen Protocol Registration | Documented kill claims against labeled organisms unlock United States health system GPO procurement channels. |
| Direct Institutional E-Procurement Platform Integration | Digital tender participation in Maharashtra and Karnataka disintermediates traditional distribution markups. |
| WHO Prequalification Scheme Compliance | Validated sachet formats access pandemic stockpile procurement across low- and middle-income health systems. |
| Electrostatic Sprayer Hardware Convergence | Charged droplet application compatibility reduces labor hours per square meter in aviation terminal contracts. |
Methodological Framework
Multiple input streams — regulatory filing databases, customs and trade flow records, institutional procurement contract registries — were reconciled across primary interviews with EPA registration consultants, hospital environmental services directors, food processing plant managers, and biocidal product formulation chemists. Secondary validation drew from EPA FIFRA registration databases, ECHA biocidal product review queues, FSSAI hygienic processing mandates, and SEC 10-K disclosures from publicly traded suppliers. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume and value estimates.
Historical shipment data was cross-referenced against expert panel inputs covering formulation physics, active chemistry, deployment context, and regional regulatory clusters across the projection horizon. Segmentation dimensions modeled include product type, active ingredient class, application vertical, packaging format, and geographic procurement centralization pattern. CAGRs were derived from regression analysis of validated supplier contract values and institutional buyer expenditure surveys. Industry-specific forecast inputs incorporated EPA registration pipeline velocity and FSSAI mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under petrochemical supply disruption scenarios or accelerated REACH restriction enforcement. Periodic stress-testing of base assumptions is recommended, particularly regarding Chinese quaternary ammonium export license stability and isopropyl alcohol feedstock price trajectories.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cleaning Chemicals
Global Cleaner and Degreaser Aftermarket Market
Cleaning Chemicals
Cleaning Chemicals for Airports and Transport Hubs Market
Cleaning Chemicals
Global Cationic Reagent Market
Cleaning Chemicals
Mastic Remover Market
Cleaning Chemicals
Air Duct Cleaning Chemicals Market
Cleaning Chemicals
Dishwashing Liquid Market
Cleaning Chemicals
Solar Component Cleaning Chemicals Market
Cleaning Chemicals
Fragrance-Free Cleaning Chemicals for Sensitive Environments Market
Cleaning Chemicals
Dust and Emission Control Chemicals for Ore Handling Market
Cleaning Chemicals
Dust Suppressant Market
Cleaning Chemicals
Housekeeping Chemicals for Hotels and Resorts Market
Cleaning Chemicals
Electrostatic Liquid Cleaner Market
Cleaning Chemicals
Glass Cleaner Market
Cleaning Chemicals
US Institutional Cleaning Ingredients Market
Cleaning Chemicals
Firefighting Chemicals Market
Cleaning Chemicals
Liquid Detergent Market