
 Mechanical Pencil Leads Market | 2026-2036
Mechanical Pencil Leads Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Pencil Leads Market Insights
Stationery retail and direct-to-consumer channels is fragmenting as e-commerce platforms and specialty art supply stores redraw traditional distribution. Pentel Co., Ltd. leverages its polymer formulation expertise to sustain premium positioning in technical drawing segments. Faber-Castell AG anchors European market presence through controlled artisan retail networks and heritage brand strength.
Mechanical pencil leads are slender extruded cores of graphite, polymer, clay, or wax-based compounds, typically manufactured in diameters of 0.3 mm to 2.0 mm and graded by hardness from 9H to 6B for precise mark-making in writing and drafting applications. HB leads dominate volume sales across student and office segments where consistency and breakage resistance matter most. Polymer-based compositions represent the fastest-expanding material category as manufacturers replace traditional clay binders with advanced polymer matrices that reduce dust and improve feed reliability in fine-diameter mechanisms.
Japan's METI oversees industrial standards for writing instruments including JIS S 6003 specifications for lead quality and dimensional tolerances, while the EU REACH framework governs chemical composition disclosure and restricted substance limits for products sold across Europe. These regulatory layers elevate compliance costs for smaller extruders but simultaneously protect incumbent manufacturers with established testing infrastructure. Stakeholders must monitor graphite supply chain certification developments and polymer feedstock price volatility as dual determinants of margin sustainability.
Market Dynamics
Polymer matrix technology is displacing traditional clay binders across fine-diameter lead production, compressing dust emissions while demanding retooling investments from established extruders. This material transition concentrates competitive advantage among manufacturers with captive polymer formulation capabilities.
Growth Catalysts
- Technical drafting precision requirements:Architectural and engineering firms in Germany and Japan specify sub-millimeter tolerances that polymer-composite leads satisfy more reliably than conventional formulations.
- REACH disclosure mandates:The EU's chemical composition framework accelerates substitution of unverified graphite sources toward certified supply chains with documented provenance.
- East Asian education intensity:Examination preparation culture in South Korea and Taiwan sustains bulk consumption of standardized HB-grade products through institutional procurement.
Market Restraints
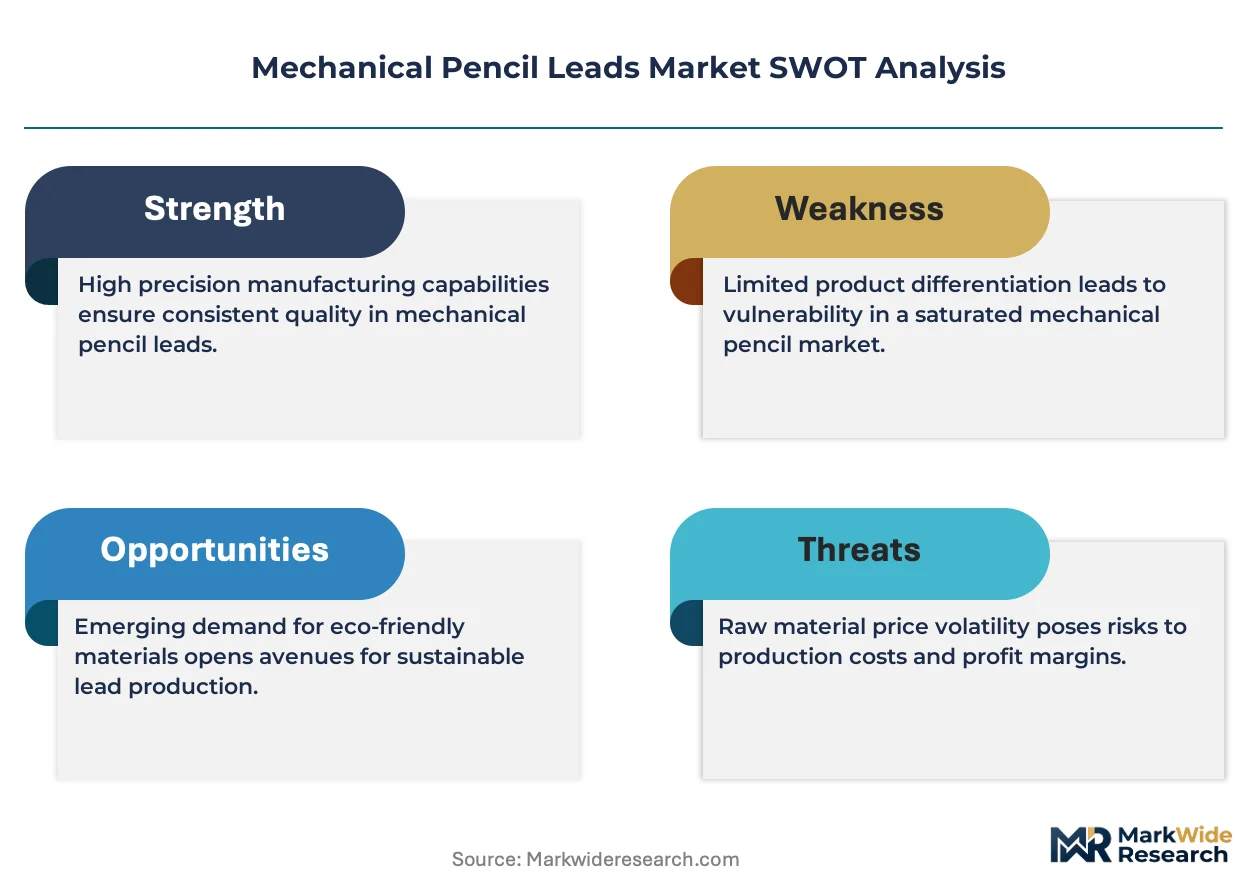
- Graphite supply concentration:Overreliance on unprocessed flake graphite from specific mining jurisdictions creates price volatility exposure for extruders without backward integration.
- Polymer feedstock cost structure:Specialty acrylate and styrene derivatives used in advanced binders track petrochemical indices with limited hedging instruments available to mid-scale producers.
- Digital stylus substitution:Active pen technology in tablets and convertible laptops captures sketching and annotation tasks previously served by mechanical pencils in professional environments.
Strategic Opportunities
- Artisan retail channel expansion:Specialty stationery boutiques in France and Italy command premium shelf space for heritage-formulated leads with documented manufacturing provenance.
- Environmental certification convergence:FSC-certified wood-cased pencils and their mechanical counterparts increasingly share retail positioning, creating bundled merchandising potential.
- India technical education scaling:National accreditation requirements for engineering drawing courses institutionalize precision instrument specifications that favor imported polymer leads over domestic clay-based alternatives.
Industry Challenges
- Polymer formulation talent scarcity:Specialized compounding expertise for ultra-fine extrusion dies concentrates among Japanese and German engineering cohorts with limited knowledge transfer pipelines.
- Multi-jurisdiction compliance timelines:Simultaneous METI JIS S 6003 testing and ECHA REACH registration create sequential certification bottlenecks for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Pencil Leads Market |
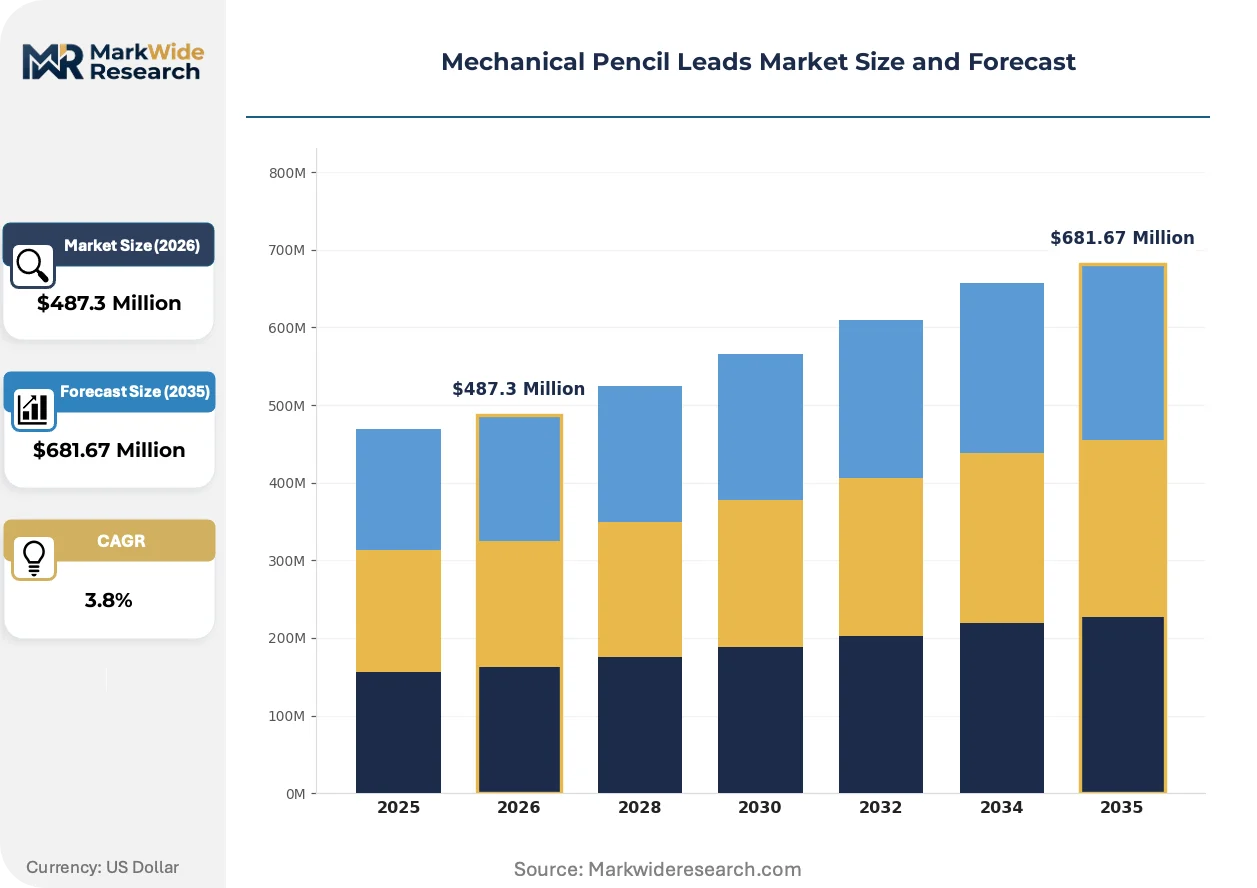
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $681.67 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HB, 2B, 4B, 6B, Colored, Watercolor Material Composition: Graphite, Polymer, Clay, Wax-based, Ceramic, Charcoal Application: Writing, Sketching, Drafting, Technical Drawing, Coloring, Calligraphy End User: Students, Artists, Architects, Engineers, Designers, Office Professionals |
| Companies Covered | Pentel Co., Ltd., Faber-Castell AG, Staedtler Mars GmbH & Co. KG, Pilot Corporation, Mitsubishi Pencil, Zebra Co., Ltd., Tombow Pencil Co., Ltd., Koh-I-Noor Hardtmuth, Rotring, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Pencil Leads Market Trends and Innovations
Material science advances and regulatory disclosure requirements are compressing traditional manufacturing methods while opening premium positioning pathways for certified sustainable supply chains.
Polymer-composite lead formulations incorporating thermoplastic elastomer binders is rendering obsolete clay-based extrusion lines designed for 0.5 mm and finer diameters. Technical drawing departments at German polytechnics and Japanese design institutes have accelerated adoption schedules by eighteen months. Legacy extrusion equipment faces accelerated depreciation as manufacturers retool for dust-reduced, break-resistant formulations.
Japan's METI has tightened JIS S 6003 dimensional tolerance specifications for 0.3 mm and 0.5 mm leads used in precision instruments. Domestic manufacturers must recalibrate quality assurance protocols to maintain certification eligibility for institutional supply contracts. South Korean exporters targeting Japanese technical schools now face additional third-party verification requirements for dimensional consistency documentation.
Direct-to-consumer subscription models for specialized lead grades are disrupting traditional art supply distributor relationships. Professional illustrators in urban creative clusters now receive curated hardness assortments through monthly replenishment services rather than retail purchasing. This channel compression is most pronounced in Berlin, Tokyo, and Melbourne where freelance design practitioners concentrate.
Mechanical Pencil Leads Market Segmentation
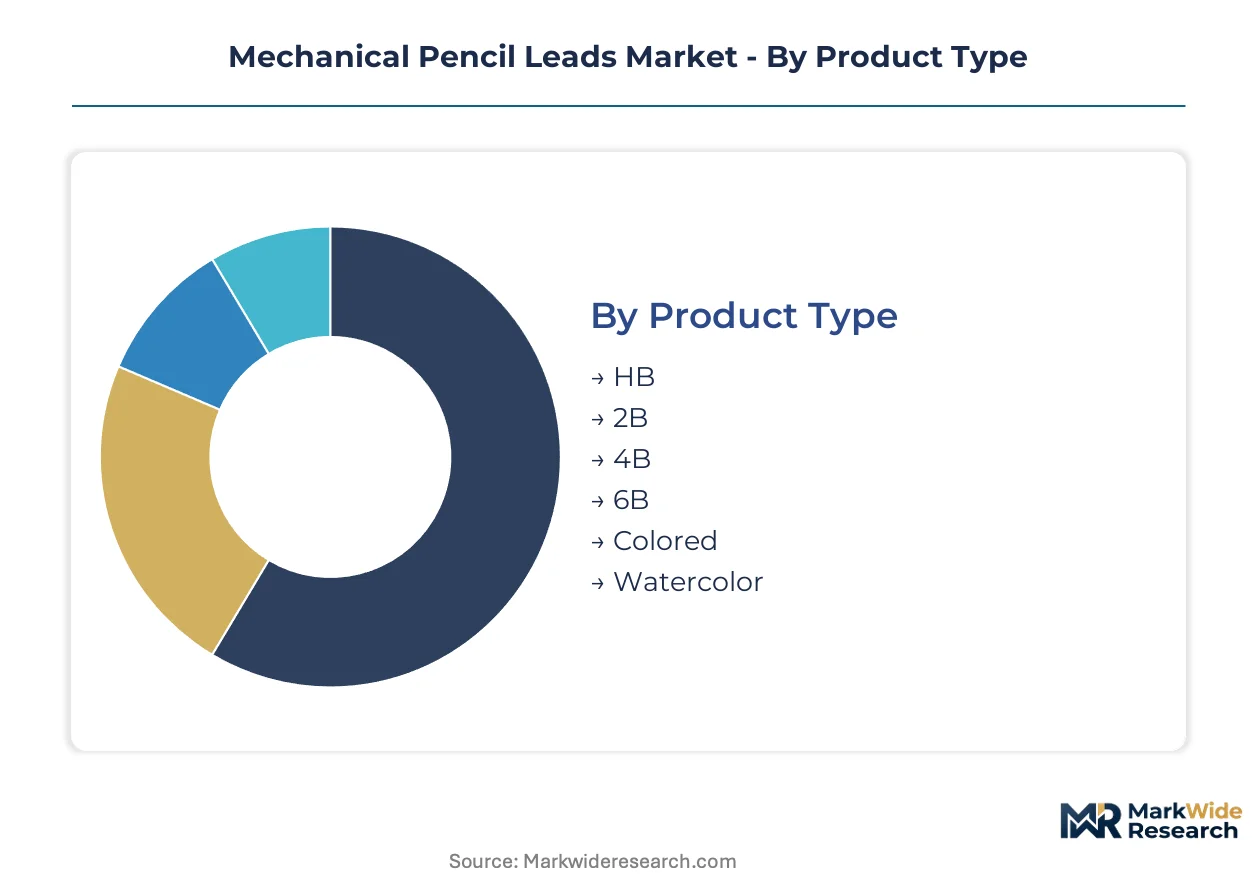
Mechanical pencil leads fragment across hardness grades, material binders, and precision requirements that dictate manufacturing complexity and price positioning. Each segmentation dimension carries distinct margin profiles and regulatory exposure that reshape competitive strategy.
Product Type:
Hardness grading determines graphite-to-clay ratios, wear rates, and the specific drawing tasks each formulation serves.
- HB:Balanced graphite-clay composition delivers consistent line weight for everyday writing and examination settings. Institutional procurement in South Korean test preparation centers sustains volume dominance despite narrow per-unit margins.
- 2B:Softer graphite concentration produces darker marks preferred by illustrators and standardized test candidates. Japanese technical high schools specify 2B for entrance examination answer sheets, creating concentrated demand spikes.
- 4B:Rich graphite load suits artistic sketching with pronounced tonal range.
- 6B:Maximum softness enables bold expressive strokes in figure drawing applications.
- Colored:Pigment-infused polymer matrices expand beyond monochrome constraints for annotation and coding tasks.
- Watercolor:Water-soluble binders dissolve for wash effects in mixed-media illustration.
HB commands the established base. The steepest expansion runs through 2B.
Material Composition:
Binding technology separates commodity extrusion from precision manufacturing with measurable performance differentiation.
- Polymer:Thermoplastic elastomer matrices reduce particulate dust and improve feed reliability in 0.3 mm mechanisms. German polytechnics and Japanese design institutes accelerated adoption schedules after METI tightened JIS S 6003 tolerances.
- Graphite:Natural flake and synthetic varieties remain cost benchmarks for standard-diameter leads. REACH disclosure mandates in Europe are forcing substitution toward certified supply chains with documented provenance.
- Clay:Traditional binder faces equipment obsolescence as manufacturers retool for dust-reduced formulations.
- Wax-based:Lubricating properties suit specialized drafting instruments requiring smooth feed mechanics.
- Ceramic:Extreme hardness enables marking on non-paper surfaces in industrial applications.
- Charcoal:Organic binder appeals to fine artists seeking traditional material aesthetics.
Graphite retains volume leadership. Polymer is gaining share fastest.
Application:
Use case specificity determines diameter tolerance requirements and hardness grade distribution.
- Technical Drawing:Sub-millimeter dimensional tolerances demand polymer-composite formulations in architectural and engineering workflows. German firms specify certified leads for contract documentation compliance.
- Writing:Consistency and breakage resistance dominate institutional procurement for student and office segments.
- Sketching:Tonal variation drives softness grade assortment in artistic supply channels.
- Drafting:Precision line weight control separates professional from consumer-grade specifications.
- Coloring:Pigment stability and blendability define performance benchmarks.
- Calligraphy:Stroke modulation requirements favor specialized hardness gradients.
Writing absorbs the highest unit volumes. Technical Drawing shows the steepest value-per-unit trajectory.
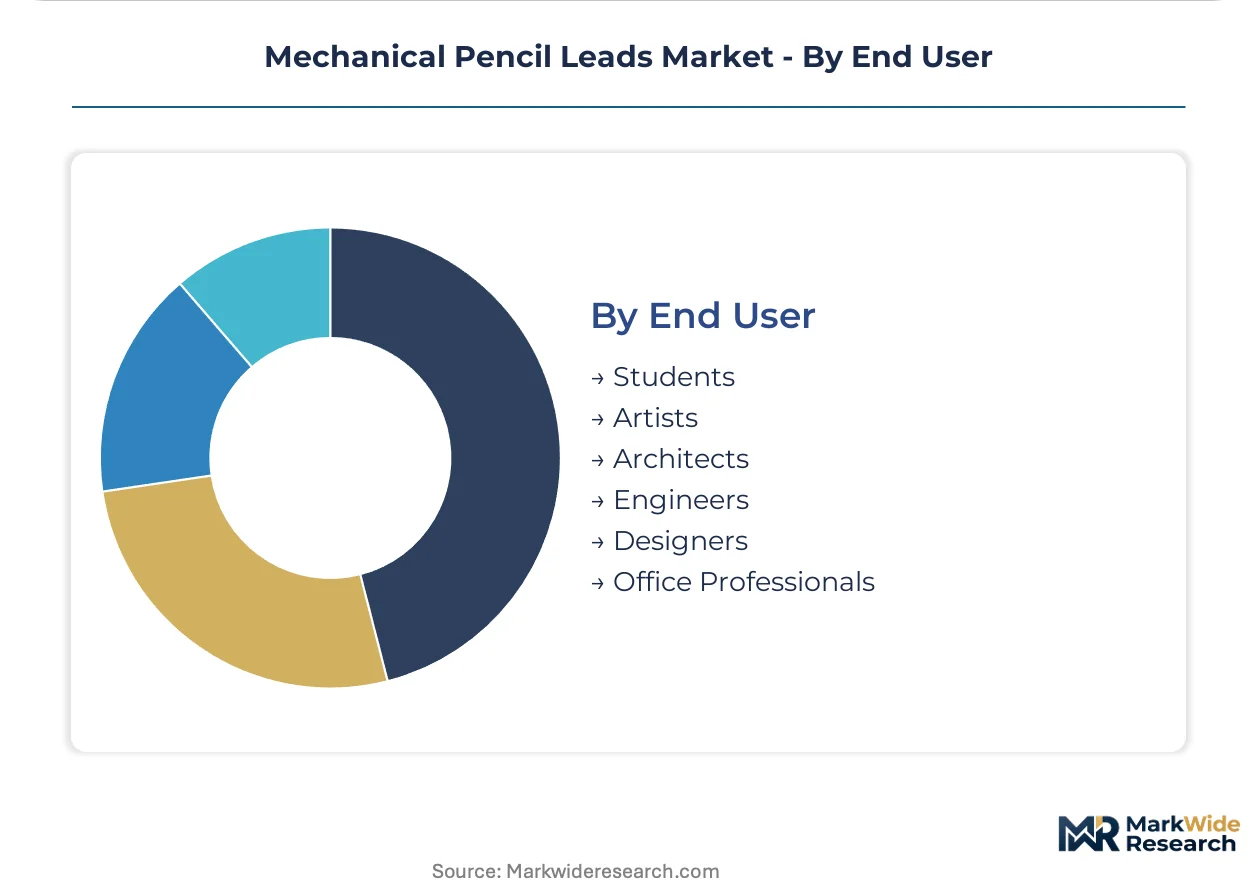
End User:
Customer type dictates purchasing authority, price sensitivity, and specification complexity.
- Students:Examination culture in Taiwan and South Korea drives standardized HB and 2B procurement through institutional tenders. Bulk purchasing power compresses margins while guaranteeing volume throughput.
- Architects:Contract documentation requirements enforce certified polymer leads with traceable dimensional tolerances.
- Artists:Specialty boutiques in France and Italy command premium positioning for heritage-formulated assortments.
- Engineers:CAD workflow integration reduces manual drafting frequency but preserves specification-grade requirements for verification tasks.
- Designers:Subscription replenishment services in Berlin and Tokyo reshape distributor relationships.
- Office Professionals:Standardization around 0.5 mm HB minimizes procurement complexity.
Students anchor volume demand. Architects generate the highest value-per-customer concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement standards for precision instruments and education sector subsidies are redirecting demand toward certified polymer formulations across multiple jurisdictions. National regulators in East Asia and Europe enforce divergent compliance timelines that fragment market access. Urban design clusters and examination preparation centers concentrate consumption in specific metropolitan corridors.
Japan
Technical high schools and design institutes in Tokyo and Osaka drive specification-grade lead consumption for entrance examinations and architectural training. METI enforces JIS S 6003 dimensional tolerances that disqualify non-compliant imports from institutional tenders. Polymer formulation specialists cluster in Nagoya's precision manufacturing corridor, supplying certified leads to domestic technical drawing departments.
Germany
Architectural firms in Berlin and Munich specify sub-millimeter tolerance leads for contract documentation compliance under federal procurement rules. ECHA REACH disclosure mandates accelerate substitution toward certified graphite supply chains with documented provenance. The Rhine-Ruhr industrial belt hosts extrusion equipment manufacturers retooling for dust-reduced polymer formulations.
South Korea
Examination preparation culture sustains bulk procurement of standardized HB and 2B grades through national education tenders. MFDS chemical safety notifications align with REACH-equivalent disclosure requirements for imported polymer binders. Seoul's Gangnam district concentrates specialty stationery retailers serving design professionals with curated hardness assortments.
United States
Freelance illustrators in Brooklyn and Los Angeles subscribe to direct-to-consumer replenishment services for specialized lead grades. The EPA oversees particulate emissions standards affecting domestic extrusion facility operations. Austin's emerging design cluster attracts polymer lead distributors targeting independent creative practitioners.
India
National accreditation requirements for engineering drawing courses institutionalize precision instrument specifications favoring imported polymer leads. BIS quality certification for writing instruments creates compliance barriers for uncertified imports. Mumbai's technical education institutes and Bangalore's design schools concentrate demand for specification-grade products.
Mechanical Pencil Leads Market Competitive Landscape
On the supply side, the industry is consolidating around manufacturers with captive polymer formulation capabilities and established multi-jurisdiction certification infrastructure. Three strategic archetypes dominate: Japanese precision specialists with METI-aligned testing protocols, German heritage brands leveraging artisan retail networks, and mid-scale polymer compounders serving private-label distributors. Competitive moves concentrate on backward integration into graphite sourcing and technology licensing agreements for ultra-fine extrusion dies.
Among Japan-based specialists, Pentel Co., Ltd., Pilot Corporation, and Mitsubishi Pencil exemplify the precision-tier archetype with established JIS S 6003 certification pipelines. These entities occupy positions where polymer matrix expertise and institutional supply relationships reinforce premium positioning. Faber-Castell AG and Staedtler Mars GmbH & Co. KG represent German heritage fabricators with controlled distribution through specialty retail channels. The competitive dynamic situates polymer formulation capability as the primary differentiation vector, with regulatory compliance infrastructure serving as a secondary barrier to mid-scale entrants.
| Leading Market Players |
|---|
| Pentel Co., Ltd. |
| Faber-Castell AG |
| Staedtler Mars GmbH & Co. KG |
| Pilot Corporation |
| Mitsubishi Pencil |
| Zebra Co., Ltd. |
| Tombow Pencil Co., Ltd. |
| Koh-I-Noor Hardtmuth |
| Rotring |
| Others |
Pricing and Supply Chain Analysis
Nagoya's precision manufacturing corridor anchors polymer formulation capacity that translates directly into pricing power for certified lead producers serving Japanese technical institutes. Capacity constraints at specialized extrusion facilities elevate premiums for JIS S 6003-compliant products while compressing margins for uncertified imports competing on price.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in this market. Three-tier pricing structure across certified polymer, standard graphite, and economy clay-based levels dominates transactional flows. Pricing pressure stems from petrochemical feedstock volatility affecting specialty acrylate binders. Students and institutional buyers exhibit highest price sensitivity, while architects and technical drafters prioritize dimensional tolerance over unit cost.
Supply Chain Analysis
Extended payment terms from Japanese stationery distributors to Nagoya extruders compress working capital cycles for mid-scale compounders. Raw material sourcing concentrates in China for flake graphite, Japan for polymer matrices, and Germany for precision extrusion equipment. Supply chain risk centers on single-source vulnerability for ultra-fine die manufacturing. Distribution runs through specialty art supply boutiques and direct-to-consumer subscription channels in urban creative clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer subscription platforms are reconstituting buyer relationships around replenishment algorithms rather than retail discovery, creating ecosystem lock-in effects comparable to software platform economics.
For Market Incumbents: Entrench polymer formulation expertise through captive R&D investment in thermoplastic elastomer binders. Digital stylus substitution threatens technical drawing volume; defend through backward integration into certified graphite sourcing and exclusive supply contracts with Japanese design institutes. For New Entrants and Emerging Players: Pursue private-label supply agreements with European specialty stationery boutiques seeking heritage-formulated alternatives to established brands. India's technical education scaling offers the most penetrable geography; enter through BIS certification partnerships with Mumbai engineering institutes. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors compounders with demonstrated JIS S 6003 and REACH compliance infrastructure over pure-play extruders. Long-term viability hinges on polymer matrix patent portfolios and captive die manufacturing capability. Monitor graphite supply chain certification developments as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Formulation Patent Expansion | Captures proprietary binder chemistry for dust-reduced fine-diameter leads demanded by German polytechnics. |
| JIS S 6003 Certification Investment | Unlocks institutional supply contracts with Tokyo technical high schools and Osaka design institutes. |
| Direct-to-Consumer Subscription Launch | Bypasses art supply distributor margins in Berlin and Melbourne creative clusters. |
| Certified Graphite Supply Agreement | Secures REACH-compliant flake sourcing with documented provenance for European market access. |
| Ultra-Fine Extrusion Die Joint Venture | Addresses equipment scarcity constraining 0.3 mm polymer lead production capacity. |
Research Methodology
Desk research of trade customs records, JIS S 6003 certification registries, and ECHA REACH disclosure databases preceded structured interviews with polymer formulation chemists, specialty stationery buyers, and technical drawing department procurement officers. Primary fieldwork with Japanese extrusion equipment manufacturers and German architectural firm supply managers validated secondary findings. Bottom-up segment sizing triangulated against top-down education sector expenditure data.
Assumptions held fixed include prevailing METI tolerance specifications and REACH substance restriction lists across the analysis window. The modeling framework segmented by hardness grade, material binder technology, and end-user archetype. CAGRs derived from elasticity-adjusted demand projections incorporating examination culture intensity indices and digital stylus penetration rates in professional environments.
Sensitivities concentrate around polymer feedstock price volatility and graphite supply chain certification timeline shifts. Forecasts reflect documented assumptions regarding regulatory compliance stability. Macroeconomic contraction affecting education budgets, accelerated digital stylus substitution, or tightened JIS dimensional tolerances would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Supplies
Pencil Sharpeners Market
Office Supplies
Student Stationery Market
Office Supplies
Stationery Market
Office Supplies
Marker Pens Market
Office Supplies
Latin America School Stationery Supplies Market
Office Supplies
United States School Stationery Supplies Market
Office Supplies
GCC School Stationery Supplies Market
Office Supplies
Office Supplies Market
Office Supplies
Thumb Hole Book Page Holder Market
Office Supplies
Malaysia Stationery Market
Office Supplies
Copiers Market
Office Supplies
Perforated File Market
Office Supplies
Global Stationery and Supplies Market
Office Supplies
Europe School Stationery Supplies Market
Office Supplies
Global Office Stationery Market
Office Supplies
Greetings Cards Market