
 Brazil Luxury Jewelry Market | 2026-2036
Brazil Luxury Jewelry Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Luxury Jewelry Market Insights
Premium 18-karat and 22-karat gold tiers is rotating toward dominance as Brazilian consumers prioritize intrinsic metal value over plated alternatives. H. Stern Jewelers Inc. leverages its vertically integrated gemstone sourcing from Minas Gerais mines to control raw material quality. Jóias Vivara sustains nationwide retail coverage through hybrid flagship and mall-based boutique networks. Amsterdam Sauer specializes in large-format imperial topaz and tourmaline settings that differentiate its collections from mass-market imports.
Brazil luxury jewelry comprises high-value ornamental pieces crafted from precious metals and certified gemstones, typically employing lost-wax casting, hand-engraving, and stone-setting techniques that meet LBMA purity standards for gold and platinum. These items serve as wealth preservation instruments, ceremonial markers, and personal status signals within Latin America's largest consumer economy. Rings and necklaces anchor volume demand among affluent consumers purchasing bridal and anniversary categories, while bracelets represent the fastest-growing product type as stackable gold designs gain traction among fashion enthusiasts. Gold material dominates manufacturing input costs, though platinum settings command superior margins in the high-net-worth individual segment where customization and exclusivity drive pricing power.
ANVISA enforces precious metal alloy disclosure requirements that mandate stamped karat certifications on all domestically retailed jewelry, while the national mining regulator's traceability protocols for colored gemstones restrict undocumented supply chain participation. These frameworks elevate compliance costs for smaller ateliers but reinforce consumer confidence in provenance claims. Stakeholders must monitor evolving federal customs classifications for imported rough gemstones, as tariff adjustments could reshape cost structures for houses dependent on foreign material inputs.
Market Dynamics
ANVISA's precious metal alloy disclosure mandates and the national mining regulator's gemstone traceability protocols are compressing informal supply chain participation while elevating compliance costs for smaller ateliers across Brazil's jewelry manufacturing base.
Growth Catalysts
- ANVISA Karat Certification Mandate:Stamped purity disclosures on domestically retailed gold and platinum pieces are reinforcing consumer confidence in provenance claims and reducing information asymmetry in high-value transactions.
- Minas Gerais Gemstone Cluster:Concentrated imperial topaz and tourmaline deposits enable vertically integrated houses to control raw material quality from extraction through finished setting.
- Stackable Gold Bracelet Demand:Fashion enthusiasts in São Paulo and Rio de Janeiro are driving volume expansion in modular wristwear designs that accommodate multiple-unit purchasing patterns.
Market Restraints
- Gold Input Cost Volatility:LBMA benchmark price fluctuations transmit directly to manufacturing cost structures, compressing margin buffers for houses without captive metal inventories.
- Undocumented Supply Chain Exclusion:The national mining regulator's traceability protocols are blocking artisanal miners lacking formal extraction licenses from legitimate market participation.
- Platinum Technical Limitation:Higher melting temperatures and specialized casting requirements restrict production scalability compared to gold alloys, constraining high-net-worth segment volume expansion.
Strategic Opportunities
- Northeast Brazil Penetration Gap:Recife and Salvador present underdeveloped retail infrastructure for certified luxury jewelry, with affluent consumer density rising in coastal metropolitan zones.
- Bridal Customization Convergence:Lost-wax casting combined with CAD design tools enables made-to-order engagement rings at production economics approaching standard catalog pieces.
- Customs Tariff Monitoring:Stakeholders tracking federal rough gemstone import classifications can preemptively restructure sourcing before duty adjustments reshape foreign material cost structures.
Industry Challenges
- Master Craftsman Talent Scarcity:Hand-engraving and stone-setting specializations require multi-year apprenticeship pipelines that Brazilian technical institutes have not scaled to replacement rates.
- Traceability Compliance Timeline:Colored gemstone documentation from mine to retail demands blockchain or paper-chain systems that smaller ateliers lack capital to implement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Luxury Jewelry Market |
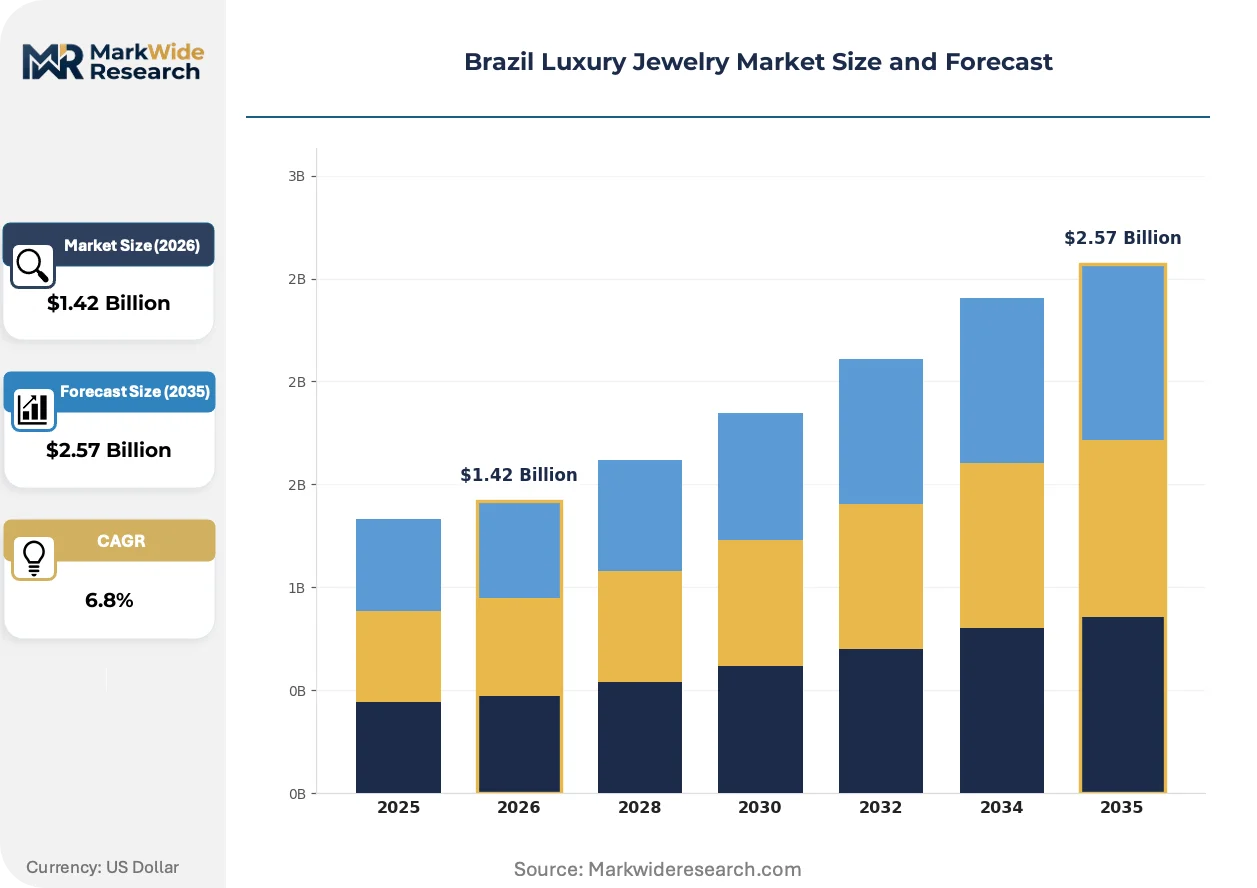
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Material: Gold, Platinum, Silver, Gemstones Customer Type: Affluent Consumers, High-Net-Worth Individuals, Fashion Enthusiasts, Gift Buyers Sales Channel: Online Retail, Luxury Boutiques, Department Stores, Auction Houses |
| Companies Covered | Jóias Vivara, H. Stern Jewelers Inc., Pandora A/S, Manoel Bernardes S.A., LVMH Moët Hennessy Louis Vuitton SE, Amsterdam Sauer, Antonio Bernardo, Carla Amorim, Compagnie Financiere Richemont SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Luxury Jewelry Market Trends and Innovations
Craft techniques and verification technologies are diverging across Brazil's luxury jewelry sector, with heritage handwork competing against precision manufacturing while regulatory pressure accelerates transparency infrastructure deployment.
Blockchain-enabled provenance tracking is bifurcating the certified gemstone segment from undocumented supply channels. High-net-worth collectors in São Paulo are demanding mine-to-retail documentation for imperial topaz acquisitions. This technology is compressing gray-market participation while creating premium pricing tiers for fully traceable pieces.
ANVISA's precious metal alloy disclosure requirements are tightening stamped karat enforcement across all domestic retail channels. Smaller ateliers face documentation burden increases that larger houses absorb through existing compliance departments. The bridal and anniversary categories are most affected, with retailers now rejecting inventory lacking verifiable alloy certifications.
Hybrid flagship and mall-based boutique networks are displacing standalone heritage storefronts as the dominant distribution architecture. Jóias Vivara's nationwide coverage model demonstrates operational economics that pure-flagship competitors struggle to replicate. This pattern concentrates in São Paulo state, where consumer density justifies multi-format presence within single metropolitan zones.
Brazil Luxury Jewelry Market Segmentation
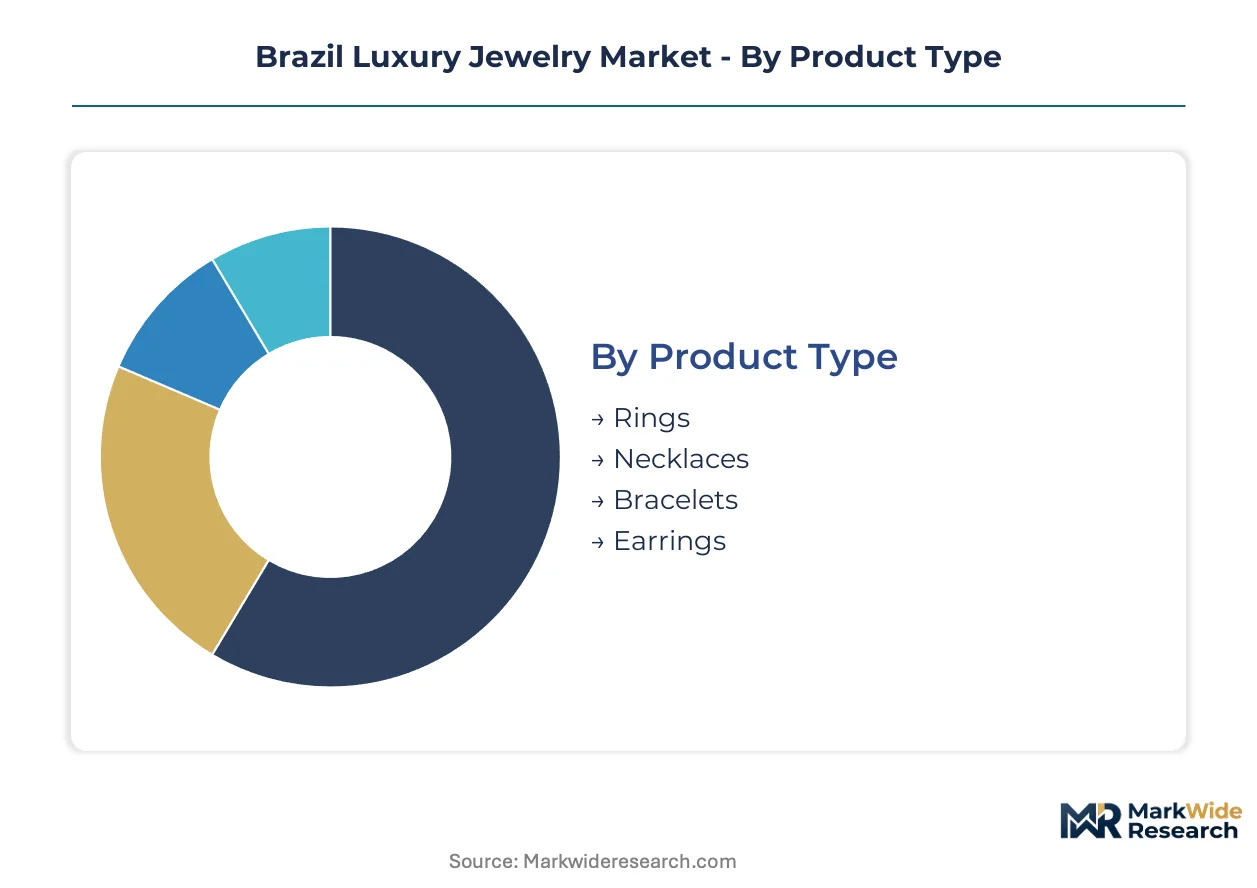
Segmentation in Brazil's luxury jewelry market reveals how ANVISA karat certifications and mining regulator traceability protocols reshape competitive positioning across product tiers. Understanding these divides enables stakeholders to align compliance investments with profit pool concentration.
Product Type:
ANVISA's alloy disclosure mandates apply uniformly across all jewelry forms, yet enforcement intensity varies by transaction value and retail channel density.
- Rings:Bridal and anniversary categories dominate manufacturing throughput, with 18-karat and 22-karat gold settings commanding premium positioning in São Paulo and Rio de Janeiro retail networks. ANVISA's stamped certification requirements have elevated documentation costs for smaller ateliers serving this segment.
- Bracelets:Modular stackable designs are expanding most quickly among fashion enthusiasts seeking multiple-unit purchasing patterns. Lost-wax casting and hand-engraving techniques from Minas Gerais ateliers differentiate Brazilian-produced pieces from mass-market imports.
- Necklaces:Imperial topaz and tourmaline pendants anchor high-value ceremonial purchases with full mine-to-retail documentation.
- Earrings:Stud and drop configurations concentrate in gift-buying occasions with lower average transaction values than bridal categories.
Rings handle the majority of throughput; bracelets are the fastest mover on share.
Material:
Input cost structures diverge sharply based on LBMA benchmark exposure and domestic extraction license requirements.
- Gold:18-karat and 22-karat tiers absorb the largest share of manufacturing investment, with price volatility transmitting directly to margin buffers for houses lacking captive metal inventories. São Paulo consumers prioritize intrinsic metal value over plated alternatives.
- Gemstones:Imperial topaz and tourmaline from Minas Gerais deposits enable vertically integrated houses to control quality from extraction through finished setting. The national mining regulator's traceability protocols block undocumented supply chain participation.
- Platinum:Higher melting temperatures and specialized casting requirements restrict production scalability despite superior margins in the high-net-worth individual segment.
- Silver:Lower price points serve entry-level luxury positioning with reduced ANVISA documentation scrutiny.
Gold dominates volume throughput; gemstones are climbing the fastest on margin contribution.
Customer Type:
Purchasing behavior splits between wealth preservation motives and fashion-driven acquisition patterns.
- Affluent Consumers:Bridal and anniversary categories anchor repeat purchase cycles with emphasis on certified provenance and heirloom durability.
- High-Net-Worth Individuals:Customization and exclusivity drive pricing power, with demand concentrating in platinum settings and large-format gemstone pieces requiring master craftsman handwork.
- Fashion Enthusiasts:São Paulo and Rio de Janeiro buyers are expanding purchases of stackable bracelet designs and regionally distinctive gold craftsmanship.
- Gift Buyers:Seasonal purchase concentration in earrings and silver-tier pieces with lower documentation burden.
Affluent consumers handle the majority of throughput; high-net-worth individuals are gaining share fastest on value per transaction.
Sales Channel:
Distribution architecture is displacing standalone heritage storefronts as compliance costs favor scaled operations.
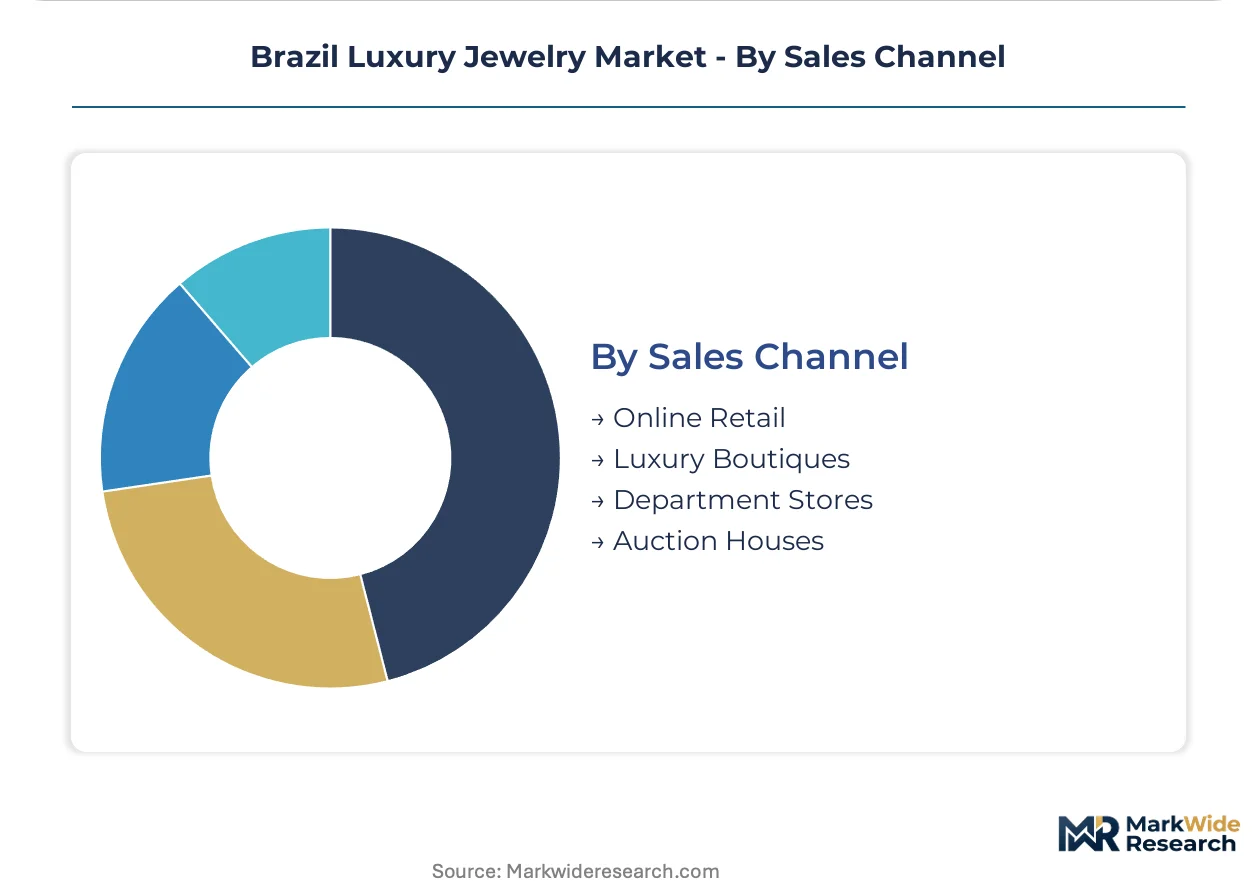
- Luxury Boutiques:Hybrid flagship and mall-based networks demonstrate operational economics that pure-flagship competitors struggle to replicate, concentrating in São Paulo state consumer density zones.
- Online Retail:Digital channels are expanding most quickly for standardized designs with verifiable ANVISA certifications, though high-value pieces still require physical inspection.
- Department Stores:Mid-tier positioning with reduced gemstone documentation requirements serves gift-buying occasions.
- Auction Houses:Secondary market liquidity for estate pieces with established provenance chains.
Luxury boutiques handle the majority of throughput; online retail is the fastest mover on channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports luxury jewelry to North American and European collector markets, while domestic consumption concentrates in southeastern metropolitan corridors. Regional demand patterns split between wealth preservation purchases in established hubs and fashion-driven acquisition in emerging coastal zones.
São Paulo
High-net-worth individuals in São Paulo's Jardins and Itaim Bibi districts drive demand for 22-karat gold bridal sets and certified imperial topaz pieces. ANVISA's karat certification mandates apply with full enforcement intensity across the state's dense retail network. The city's hybrid flagship and mall-based boutique infrastructure supports multi-format presence that smaller competitors struggle to replicate.
Rio de Janeiro
Leblon and Ipanema neighborhoods anchor demand for stackable gold bracelet designs among fashion enthusiasts seeking modular wristwear. The national mining regulator's traceability protocols block undocumented gemstone supply chains from reaching legitimate retail channels. Local ateliers in the Centro district specialize in lost-wax casting techniques that differentiate Brazilian craftsmanship from mass-market imports.
Minas Gerais
Vertically integrated houses exploit concentrated imperial topaz and tourmaline deposits to control raw material quality from extraction through finished setting. ANVISA oversight of precious metal alloys elevates compliance costs for smaller operators in the Ouro Preto and Teófilo Otoni clusters. Master craftsmen in these historic mining centers maintain hand-engraving specializations that require multi-year apprenticeship pipelines.
Bahia
Salvador's coastal metropolitan zone presents underdeveloped retail infrastructure for certified luxury jewelry despite rising affluent consumer density. The national mining regulator's documentation requirements for colored gemstones restrict artisanal miners lacking formal extraction licenses from market participation. Northeast Brazil penetration gaps create strategic opportunities for houses with capital to deploy hybrid distribution formats.
Rio Grande do Sul
Porto Alegre's affluent consumer base favors platinum settings in high-value ceremonial purchases despite technical casting limitations. LBMA gold price volatility transmits directly to manufacturing cost structures for houses without captive metal inventories. Local ateliers concentrate on silver-tier entry-level positioning with reduced documentation scrutiny compared to gold and platinum categories.
Brazil Luxury Jewelry Market Competitive Landscape
Listed leaders compete with private specialists across distribution format and material integration depth. The vendor base spans vertically integrated gemstone houses, nationwide retail networks, and artisan ateliers with heritage craft positioning. Three archetypes dominate: mining-to-retail integrators controlling Minas Gerais deposits; multi-format retailers sustaining nationwide coverage through hybrid channels; and master-craftsman houses emphasizing handwork differentiation. Competitive moves concentrate on geographic expansion into underpenetrated northeast corridors and bridal customization convergence combining lost-wax casting with CAD design tools.
Within the mining-to-retail integrator tier, H. Stern Jewelers Inc. and Amsterdam Sauer exemplify upstream control over colored gemstone supply chains. Among nationwide retail specialists, Jóias Vivara occupies a position representing scaled hybrid distribution economics. These three houses anchor competitive dynamics around material provenance documentation and multi-format presence density in southeastern consumer zones.
| Leading Market Players |
|---|
| Jóias Vivara |
| H. Stern Jewelers Inc. |
| Pandora A/S |
| Manoel Bernardes S.A. |
| LVMH Moët Hennessy Louis Vuitton SE |
| Amsterdam Sauer |
| Antonio Bernardo |
| Carla Amorim |
| Compagnie Financiere Richemont SA |
| Others |
Pricing and Supply Chain Analysis
ANVISA's karat certification regime gates both supplier qualification and price differentiation simultaneously, as stamped purity disclosures separate documented ateliers from gray-market competitors while enabling premium positioning for verified provenance. High-net-worth individuals in São Paulo pay substantial markups for fully traceable imperial topaz settings that informal channels cannot replicate.
Pricing Analysis
Affluent consumers anchor a three-tier pricing structure across premium, standard, and economy levels in Brazil's luxury jewelry sector. Price differentiation rests on certification grade and volume scale, with ANVISA-stamped 22-karat pieces commanding substantial premiums over undocumented alternatives. Cost compression in entry-level silver tiers is intensifying because of raw material volatility, while high-net-worth individuals exhibit minimal price sensitivity for bespoke platinum commissions.
Supply Chain Analysis
Strategic stockpiling of LBMA-certified gold dominates inventory strategy among scaled houses, contrasting with just-in-time gemstone procurement from Minas Gerais extraction clusters. Supply concentrates in Brazil's southeastern mining belt, with secondary dependencies on imported rough stones from Sri Lanka and Madagascar. Distribution runs through hybrid flagship and mall-based boutique networks that displaced standalone heritage storefronts. Single-source vulnerability in master craftsman talent pools threatens production scalability for hand-engraved specializations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's luxury jewelry sector sits at a platform-economics inflection where blockchain-enabled provenance tracking creates interoperability between mine documentation and retail certification systems, reshaping competitive moats around transparency infrastructure.
For Market Incumbents: Shield market position by deepening captive control over Minas Gerais gemstone deposits before traceability mandates harden compliance barriers. Accelerate certification investment in ANVISA-stamped karat enforcement to widen the documentation gap against smaller ateliers lacking compliance department scale. For New Entrants and Emerging Players: Anchor in Salvador and Recife's underdeveloped retail corridors where affluent consumer density rises without matching boutique infrastructure penetration. Target bridal customization convergence combining lost-wax casting with CAD design tools as the most penetrable wedge against established catalog-heavy competitors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across blockchain-enabled provenance systems as documentation infrastructure becomes table stakes for legitimate market participation. Long-term viability over the coming decade favors vertically integrated houses controlling extraction through retail. Watch federal customs tariff adjustments on rough gemstone imports as the critical signal for sourcing cost structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Deployment | Mine-to-retail documentation creates premium pricing tiers separating certified from gray-market channels. |
| Hybrid Distribution Expansion | Flagship-mall boutique networks replicate Jóias Vivara's operational economics in underserved northeast corridors. |
| Master Craftsman Apprenticeship Scaling | Multi-year hand-engraving pipelines secure production capacity for high-net-worth customization demand. |
| Custom Bridal Convergence | CAD-designed lost-wax casting approaches standard catalog production economics for made-to-order engagement rings. |
| Strategic Stockpile Accumulation | Captive LBMA gold inventories buffer margin compression from benchmark price volatility. |
Research Methodology
A spread of perspectives from jewelry house supply chain directors, ANVISA regulatory affairs specialists, Minas Gerais mining cooperative representatives, and São Paulo luxury retail buyers converged on the working assumptions. Primary fieldwork combined with secondary validation from ANVISA alloy disclosure filings, national mining regulator traceability protocols, customs import records, and LBMA benchmark pricing archives. Bottom-up atelier capacity assessments triangulated against top-down consumer expenditure patterns.
Segmentation dimensions modeled span product type, material tier, customer archetype, and sales channel density across the analysis window. CAGRs derived from production volume trajectories and average transaction value movements in certified versus undocumented supply tiers. Forecast inputs incorporated ANVISA enforcement intensity projections and federal customs classification monitoring for rough gemstone imports.
Decision-makers should treat outputs as directional under assumptions of sustained ANVISA certification mandate expansion and stable LBMA gold pricing; material deviation in regulatory enforcement or commodity volatility would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
France Luxury Goods Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
China Luxury Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
Designer Bags and Luxury Handbags Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Luxury Watches Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Luxury Pen Market
Luxury Goods
Personal Luxury Goods Market
Luxury Goods
Spain Luxury Jewelry Market