
 South Korea Luxury Goods Market | 2026-2036
South Korea Luxury Goods Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Luxury Goods Market Analytics
Seoul's boutique retail corridor is recalibrating supply-side capacity as global maisons expand flagship footprints. LVMH Moët Hennessy Louis Vuitton SE leverages vertical integration across leather goods and spirits to anchor its Gangnam district presence. Chanel SA sustains scarcity-driven pricing through controlled distribution in Cheongdam-dong, while Gentle Monster competes via design-led eyewear and immersive retail concepts that dominate domestic fashion discourse.
South Korea luxury goods encompass premium apparel, accessories, timepieces, and leather goods distinguished by craftsmanship thresholds, heritage branding, and price positioning above mass-market equivalents by multiples of ten or more. These items serve status-signaling and wealth-preservation functions for buyers. Watches and handbags occupy the deepest margin pools due to resale value retention and limited-edition scarcity mechanics. Ultra-luxury price tiers attract the fastest-growing domestic demand, while accessible luxury segments face compression from fast-fashion premium lines.
MFDS labeling standards shape cosmetics-adjacent luxury goods, KFTC monitors pricing transparency in department store concessions, and Korea Customs Service enforces import valuation protocols that affect grey-market flow. These frameworks elevate compliance costs for foreign houses while protecting domestic retail channels. Stakeholders must monitor whether Seoul's regulatory tightening on digital resale platforms alters secondary-market liquidity for watches and handbags.
Market Dynamics
Ultra-luxury demand concentration in Seoul's Gangnam corridor is forcing domestic retail capacity expansion while MFDS labeling mandates reshape product transparency requirements across cosmetics-adjacent categories.
Growth Catalysts
- Younger affluent cohorts:Millennials and Gen Z consumers in Seoul and Busan are expanding acquisition of ultra-luxury handbags and timepieces, creating sustained volume pull through flagship retail channels.
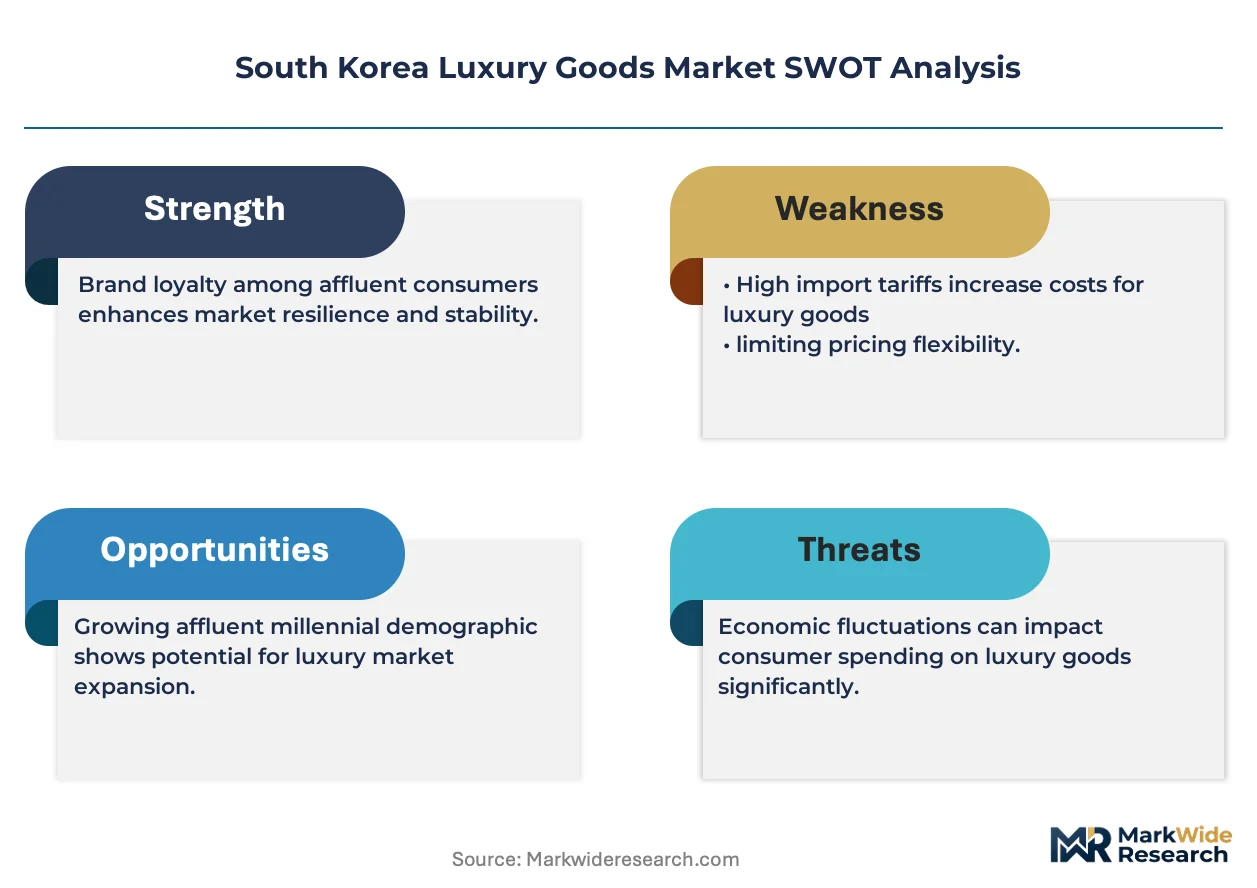
- MFDS cosmetics framework:Enhanced ingredient disclosure requirements for beauty-adjacent luxury goods are elevating brand trust premiums and differentiating compliant domestic retail from grey-market alternatives.
- Digital asset regulation evolution:Korea Customs Service import valuation protocols are tightening documentation standards, channeling demand toward authorized distribution networks with verified provenance.
Market Restraints
- Department store concession costs:KFTC-monitored pricing transparency requirements have compressed margin structures for foreign houses operating within Shinsegae and Hyundai retail ecosystems.
- Cheongdam-dong supply concentration:Scarcity-driven distribution models limit unit velocity despite price premiums, constraining revenue scale for ultra-luxury leather goods.
- Fast-fashion premium substitution:Accessible luxury segments face compression from design-forward mass-market lines that replicate aesthetic cues at fractional price points.
Strategic Opportunities
- Busan luxury corridor development:Underpenetrated secondary metropolitan demand offers expansion runway for timepiece and jewelry maisons beyond Seoul saturation.
- Immersive retail technology convergence:Augmented reality visualization and spatial computing integration enable experiential differentiation in flagship Gangnam boutiques.
- Secondary platform regulation:Seoul's tightening digital resale oversight creates white space for authenticated pre-owned channels with verified provenance systems.
Industry Challenges
- Heritage craftsmanship succession:Leather goods and haute horlogerie houses face narrowing pipelines of trained artisans capable of executing heritage techniques at volume.
- Grey-market documentation compliance:Korea Customs Service valuation disputes create inventory friction for parallel import channels serving price-sensitive segments.
- Cross-border digital tax complexity:Evolving e-commerce duty structures complicate direct-to-consumer fulfillment from European production centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Luxury Goods Market |
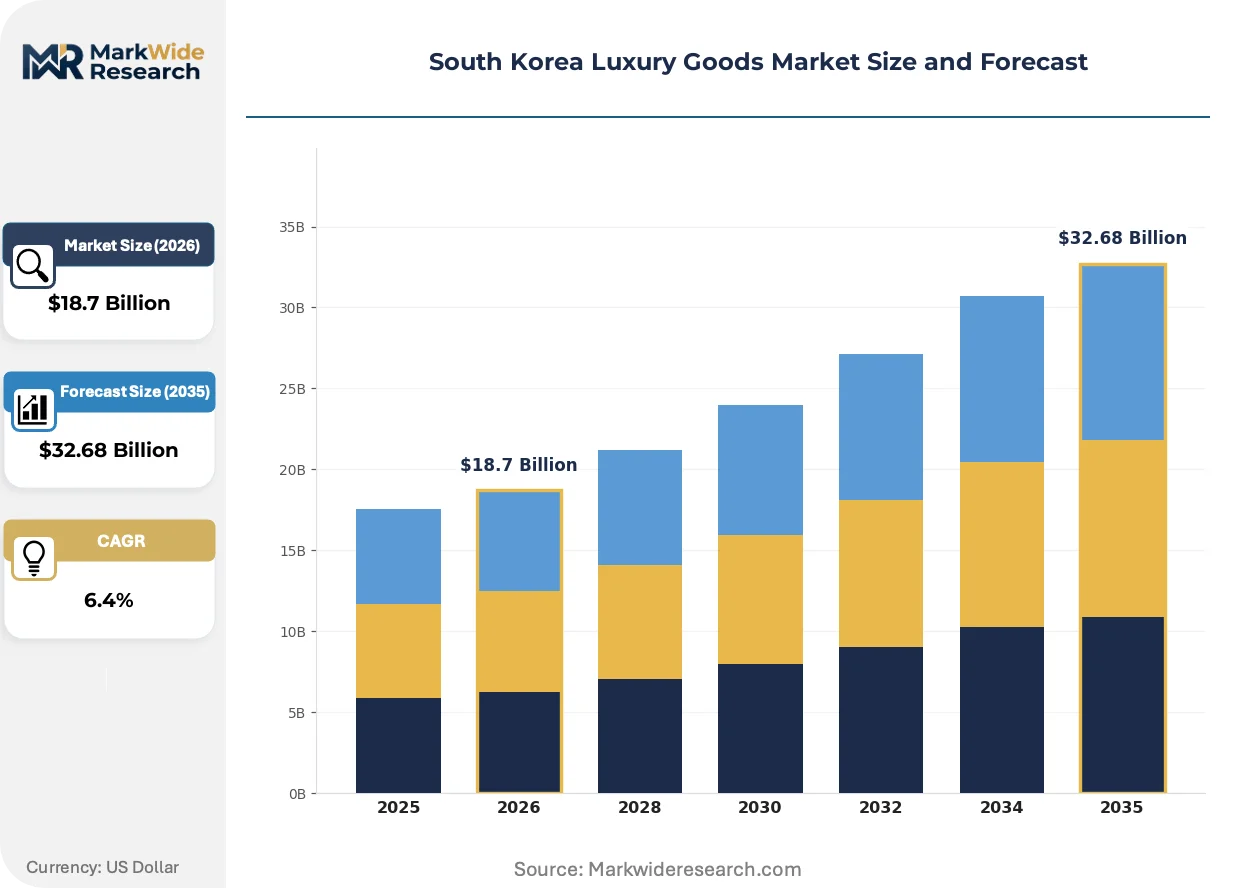
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Watches, Handbags, Clothing, Footwear Customer Type: Affluent Consumers, Tourists, Online Shoppers, Corporate Clients Distribution Channel: Department Stores, E-commerce, Specialty Retailers, Luxury Boutiques Price Tier: High-End, Mid-Range, Ultra-Luxury, Accessible Luxury |
| Companies Covered | Kering SA, Rolex SA, LVMH Moët Hennessy Louis Vuitton SE, Burberry Group Plc, The Swatch Group Ltd., Chanel SA, Compagnie Financière Richemont SA, Gentle Monster, Hermès International SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Luxury Goods Market Evolving Landscape
Phygital retail integration and regulatory transparency mandates are recalibrating how ultra-luxury houses engage South Korean consumers across discovery, purchase, and post-sale service touchpoints.
Blockchain-based provenance authentication is overtaking paper-based certificates of authenticity in high-value timepiece and handbag transactions. Domestic collectors in Seoul's Cheongdam-dong cluster are adopting digital ownership records at accelerating velocity. This shift is compressing grey-market liquidity while elevating authorized retail premiums.
MFDS has expanded mandatory ingredient disclosure thresholds for cosmetics-adjacent luxury goods effective across all domestic retail channels. Foreign houses must reformulate packaging and supply chain documentation to maintain shelf placement in department store concessions. Fragrance and skincare categories face the steepest compliance cost escalation.
Resale platform authentication services are displacing informal peer-to-peer transactions among younger affluent buyers. Digital-native collectors in Busan and Seoul are migrating toward consignment channels with in-house verification capabilities. This behavioral pivot is most visible in limited-edition handbag segments where secondary price discovery remains opaque.
South Korea Luxury Goods Market Segmentation
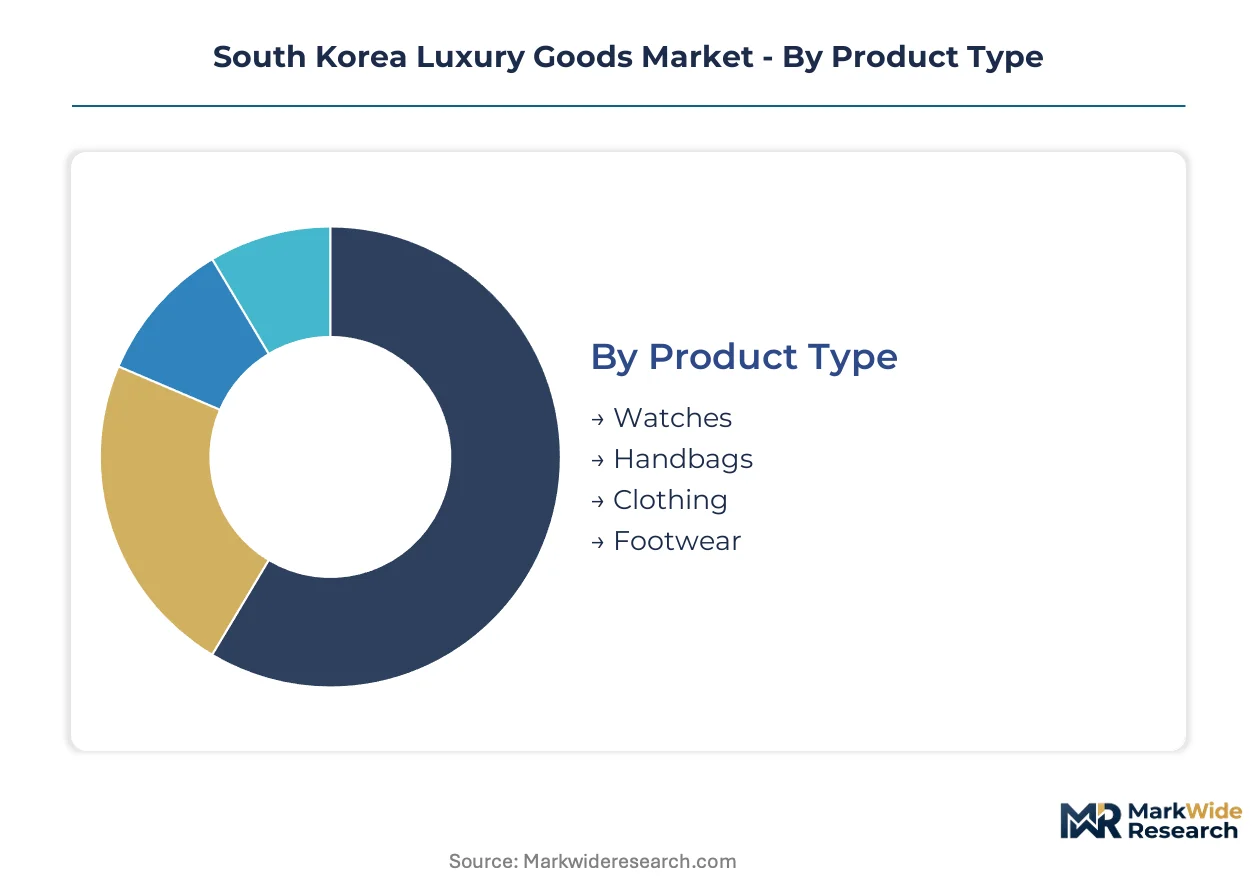
Segmentation reveals how supply-side concentration in Seoul's Gangnam and Cheongdam corridors maps to distinct buyer behaviors and channel preferences. Each dimension exposes margin architecture and regulatory exposure that shapes competitive positioning for foreign maisons and domestic players alike.
Product Type:
Supply concentration for leather goods and haute horlogerie anchors in Seoul's flagship districts, with production scarcity mechanics driving differential margin capture across categories.
- Watches:Mechanical and haute horlogerie timepieces with heritage movement calibers dominate Cheongdam-dong collector circles. Demand concentrates among younger affluent buyers in Seoul's Gangnam corridor, where MFDS-adjacent import documentation requirements channel purchases toward authorized retailers with verified provenance systems.
- Handbags:Ultra-luxury leather goods featuring controlled distribution and limited-edition scarcity mechanics sustain the deepest margin pools. Gangnam district boutiques capture the highest volume velocity, though unit constraints from scarcity-driven pricing limit revenue scale expansion.
- Clothing:Premium apparel spans ready-to-wear and made-to-measure ateliers with craftsmanship thresholds distinguishing mass-market equivalents.
- Footwear:Luxury leather and designer sneaker categories face compression from fast-fashion premium lines replicating aesthetic cues.
Today's leader: Handbags. Tomorrow's challenger: Watches.
Customer Type:
Cost tier stratification separates high-frequency domestic collectors from episodic tourist spend and institutional procurement with distinct service requirements.
- Affluent Consumers:Domestic high-net-worth individuals and younger affluent cohorts in Seoul and Busan drive recurring ultra-luxury acquisition. This segment commands white-glove service protocols and exclusive access programming from flagship boutiques.
- Tourists:Tax-advantaged visitors from Greater China and Southeast Asia concentrate purchases in department store concessions with immediate VAT refund infrastructure.
- Online Shoppers:Digital-native collectors migrating toward authenticated resale platforms with in-house verification capabilities.
- Corporate Clients:Institutional gifting and executive reward programs requiring volume procurement with customization services.
Domestic affluent consumers anchor current revenue. Tourist flows present the steepest recovery variable.
Distribution Channel:
Volume concentration in department store ecosystems creates margin pressure from concession cost structures monitored by KFTC pricing transparency requirements.
- Department Stores:Shinsegae and Hyundai retail ecosystems host foreign maisons in high-traffic concessions with immediate tax refund infrastructure. KFTC-monitored pricing transparency requirements have compressed margin structures for operators within these channels.
- E-commerce:Direct-to-consumer platforms and authenticated resale channels are gaining share among younger buyers seeking verified provenance.
- Specialty Retailers:Multi-brand luxury concept stores with curated merchandising and experiential service differentiation.
- Luxury Boutiques:Maison-operated flagship locations in Gangnam and Cheongdam-dong with controlled distribution and immersive retail concepts.
Department stores dominate transaction volume. Luxury boutiques capture margin premiums.
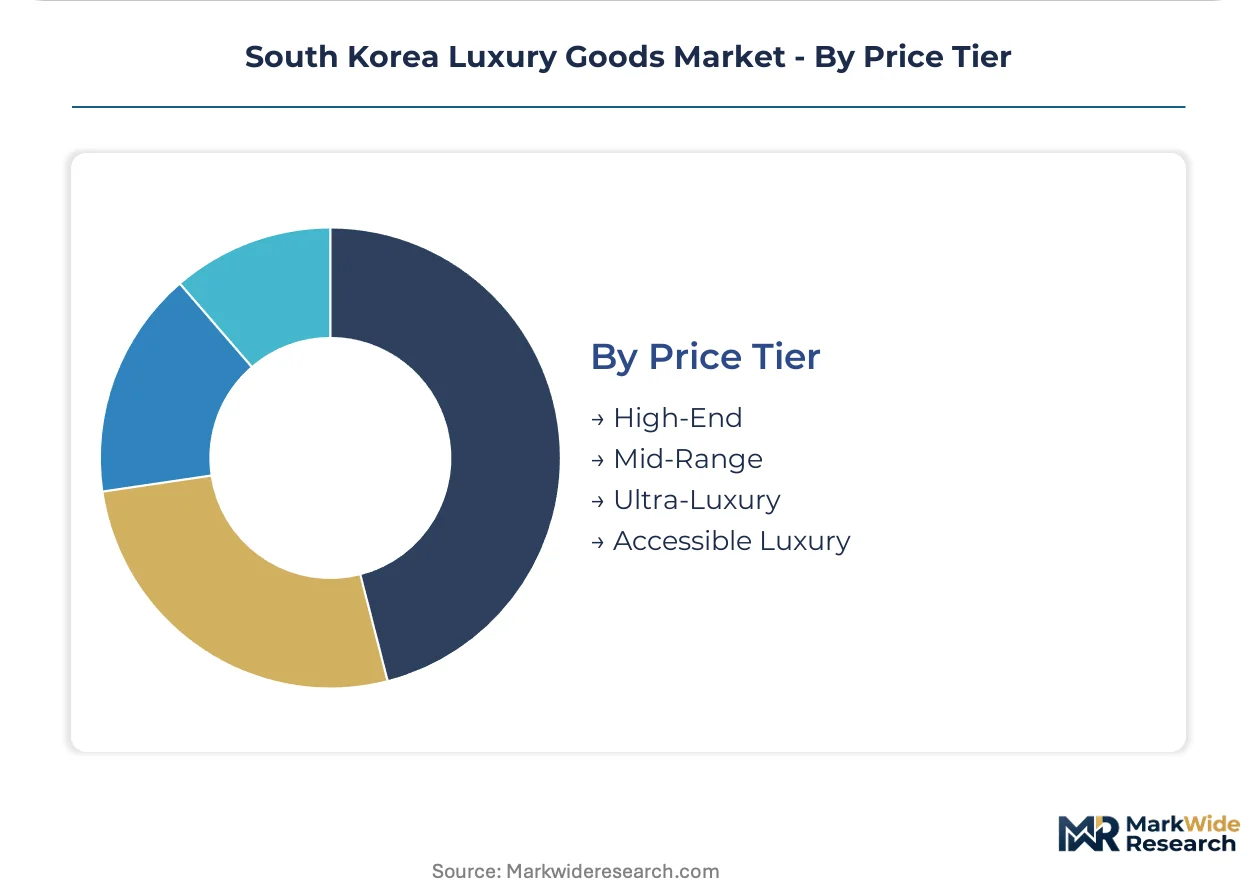
Price Tier:
Margin architecture stratifies sharply between scarcity-driven ultra-luxury and accessible segments facing substitution pressure from design-forward mass-market lines.
- Ultra-Luxury:Price positioning at multiples of ten above mass-market equivalents with heritage craftsmanship and controlled scarcity mechanics. This tier attracts the fastest-growing domestic demand from younger affluent collectors in Seoul and Busan seeking status-signaling and wealth-preservation functions.
- High-End:Established luxury houses with recognized heritage branding and consistent quality thresholds.
- Mid-Range:Diffusion lines and contemporary luxury positioning with broader accessibility.
- Accessible Luxury:Entry-tier price positioning facing compression from fast-fashion premium lines replicating aesthetic cues at fractional price points.
Ultra-luxury commands margin expansion. Accessible luxury faces structural pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in luxury goods given heritage brand concentration in Western Europe, yet compliance cost differentials across Asian retail jurisdictions are reshaping regional distribution strategies. Production remains anchored in France, Italy, and Switzerland while consumption gravity shifts toward East Asian metropolitan clusters with favorable tax and customs frameworks.
Seoul Capital Area
Younger affluent cohorts in Gangnam and Cheongdam-dong drive ultra-luxury handbag and timepiece acquisition at velocity exceeding regional peers. MFDS cosmetics labeling mandates elevate compliance costs for beauty-adjacent categories, channeling demand toward authorized retail with verified provenance. The Cheongdam luxury corridor hosts flagship boutiques from LVMH, Chanel, and Hermès with controlled distribution mechanics.
Busan-Ulsan
Secondary metropolitan demand for jewelry and haute horlogerie is expanding as domestic collectors seek differentiation from Seoul-saturated markets. Korea Customs Service import valuation protocols tighten documentation standards for parallel channels, reinforcing authorized retailer advantages. The Busan luxury corridor remains underpenetrated relative to per-capita wealth indicators.
Daegu-Gyeongbuk
Textile heritage from historical garment production creates localized craftsmanship appreciation for leather goods and made-to-measure apparel. KFTC pricing transparency requirements apply uniformly across national department store concessions, compressing margin structures in Shinsegae-affiliated retail. Daegu's emerging luxury retail footprint lags wealth concentration metrics.
Daejeon-Sejong
Government district proximity generates institutional gifting demand with volume procurement requirements and customization service expectations. Digital asset regulation evolution affects blockchain-based provenance authentication adoption rates for high-value timepiece transactions. Sejong's administrative population exhibits conservative luxury consumption patterns relative to private-sector affluence.
Gwangju-Honam
Cultural sector patronage sustains demand for artisanal luxury categories with heritage storytelling components. Korea Customs Service enforcement of import valuation protocols creates inventory friction for grey-market channels serving price-sensitive segments. Gwangju's luxury retail infrastructure remains concentrated in department store concessions with limited maison-operated boutique presence.
South Korea Luxury Goods Market Competitive Landscape
French and Swiss producers anchor the ultra-luxury tier; Italian leather specialists and Korean eyewear innovators hold differentiated positions in accessible and design-forward segments. The vendor base concentrates around heritage maisons with century-plus brand equity and controlled scarcity distribution models. Three archetypes dominate: vertically integrated European conglomerates with multi-category portfolios, independent family-owned houses with artisanal positioning, and Asian design-led challengers with immersive retail concepts. Competitive moves center on flagship retail expansion in Seoul's Gangnam corridor and blockchain-based provenance authentication deployment.
Within the European conglomerate tier, LVMH Moët Hennessy Louis Vuitton SE and Kering SA represent vertically integrated operators with multi-brand portfolios spanning leather goods, timepieces, and spirits. Chanel SA exemplifies the independent family-owned archetype with scarcity-driven pricing and controlled distribution mechanics. Gentle Monster anchors the Korean design-led challenger position with immersive retail concepts and eyewear specialization that dominates domestic fashion discourse.
| Leading Market Players |
|---|
| Kering SA |
| Rolex SA |
| LVMH Moët Hennessy Louis Vuitton SE |
| Burberry Group Plc |
| The Swatch Group Ltd. |
| Chanel SA |
| Compagnie Financière Richemont SA |
| Gentle Monster |
| Hermès International SA |
| Others |
Value Network & Pricing Analysis
Captive retail networks operated by European conglomerates anchor both supply positioning and pricing power across South Korea's luxury corridor. LVMH's in-house control of Gangnam flagship distribution eliminates intermediary margin capture, while Chanel's vertically integrated Cheongdam-dong boutiques sustain scarcity premiums through direct-to-consumer channel ownership. This integration choice insulates ultra-luxury tiers from KFTC-monitored department store concession cost compression.
Pricing Analysis
Retailer markup layers in Shinsegae and Hyundai concessions compress foreign house margins under KFTC transparency monitoring, while direct-operated Gangnam boutiques capture full premium realization. Price differentiation rests on heritage authentication and controlled scarcity mechanics rather than volume scale. Pricing pressure intensifies in accessible luxury tiers as fast-fashion premium lines replicate aesthetic cues. Tourist segments in department store channels exhibit highest price sensitivity; domestic collectors in Cheongdam-dong show lowest elasticity due to wealth-preservation demand.
Supply Chain Analysis
Dual-sourcing requirements for high-value timepiece components mandate Swiss and German movement supplier qualification, though heritage maisons maintain single-source artisan dependencies for leather goods. Geographic supply concentration centers on France for leather craftsmanship, Switzerland for haute horlogerie calibers, and Italy for textile production. Raw material dependencies include crocodile leather from certified farms, precious metals from London Metal Exchange channels, and synthetic sapphire for watch crystals. Supply chain risk concentrates in single-source vulnerability for trained artisan pipelines. Distribution runs through Seoul's Gangnam corridor for volume, with Busan emerging for secondary market development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's luxury goods market offers geographic-arbitrage positioning against tighter European retail taxation, with Seoul's favorable customs framework and VAT refund infrastructure attracting Greater China tourist flows that bypass higher-duty European entry points.
For Market Incumbents: Acquire immersive retail technology assets to defend flagship positioning against Gentle Monster's spatial computing concepts. Consolidate Cheongdam-dong scarcity distribution through controlled waitlist mechanics that counter grey-market liquidity erosion. Invest in blockchain provenance systems as MFDS-adjacent transparency requirements elevate authorized retail trust premiums. For New Entrants and Emerging Players: Blockchain-authenticated resale platforms represent the most penetrable wedge for digital-native collectors seeking verified pre-owned channels. Target Busan's underpenetrated jewelry and haute horlogerie demand as Seoul saturation intensifies. Deploy consignment-with-verification go-to-market models that displace informal peer-to-peer transactions among younger affluent buyers. For Investors and Strategic Acquirers: Roll-up economics work for authenticated pre-owned platform consolidation because Seoul's tightening digital resale oversight fragments verification capabilities across subscale operators. Long-term viability hinges on capturing Cheongdam-dong collector liquidity migration toward trusted secondary channels. Watch for MFDS expansion of cosmetics-adjacent disclosure requirements as signal for compliance-cost-driven authorized retail consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Immersive Retail Technology Deployment | Augmented reality visualization in Gangnam boutiques differentiates against Gentle Monster's experiential concepts. |
| Blockchain Provenance Authentication | Digital ownership records compress grey-market liquidity while elevating authorized retail premiums under MFDS transparency trends. |
| Busan Luxury Corridor Expansion | Secondary metropolitan development captures underpenetrated jewelry demand beyond Seoul-saturated markets. |
| Authenticated Pre-Owned Platform Launch | Verified consignment channels displace informal resale as Korea Customs Service tightens import documentation. |
| Heritage Artisan Pipeline Investment | Controlled scarcity mechanics depend on succession planning for leather goods and haute horlogerie craftsmanship. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan, and Daegu-Gyeongbuk, with primary inputs from each. Primary interviews incorporated brand managers at European luxury houses, category buyers at Shinsegae and Hyundai department stores, and Korea Customs Service valuation specialists. Secondary validation drew from MFDS regulatory filings, KFTC pricing transparency enforcement records, and Seoul Metropolitan retail development permits. Bottom-up segment sizing triangulated against top-down macroeconomic consumption indicators.
Granularity-level modeling captured product type, customer archetype, distribution channel, and price tier dimensions at the metropolitan cluster level. CAGRs derived from trend extrapolation of younger affluent cohort acquisition patterns and regulatory compliance cost trajectories. Forecast inputs incorporated MFDS cosmetics framework evolution and digital asset regulation progression across the analysis window.
The model holds under stable customs valuation protocols and continued Gangnam corridor retail capacity expansion; deviation in Korea Customs Service enforcement intensity or Seoul commercial real estate cost spikes would shift channel profitability materially. Forecasts reflect these base conditions with acknowledged sensitivity to tourist flow recovery patterns and grey-market documentation friction.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
GCC Luxury Goods Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
Brazil Luxury Jewelry Market
Luxury Goods
Luxury Mechanical Watches Market
Luxury Goods
Accessible Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
Europe Secondhand Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Luxury Piano Market
Luxury Goods
Luxury Pen Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Watch Winder Market
Luxury Goods
India Lab Grown Diamond Jewelry Market