
 Global Gold and Diamond Jewellery Market | 2026-2036
Global Gold and Diamond Jewellery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gold and Diamond Jewellery Market Analysis
Capital-intensity divergence between vertically integrated miners and brand-dependent retailers is redrawing competitive boundaries in the jewellery value chain. De Beers Group leverages upstream diamond sourcing and controlled rough supply to sustain margin capture across the pipeline. Chow Tai Fook Jewellery Group anchors its position through extensive retail networks and deep penetration in Greater China. LVMH differentiates via portfolio luxury positioning across multiple maisons, while Pandora A/S competes on accessible price points and recycled silver and gold offerings.
Gold and diamond jewellery comprises ornamental body adornments crafted from precious metals and gemstones, typically specified by karat purity for gold and the four Cs—cut, color, clarity, carat—for diamonds, with primary commercial purpose spanning personal expression, wealth storage, and ceremonial gifting. Rings and necklaces dominate transaction volume in established markets, while bracelets and earrings capture faster growth among younger demographics seeking stackable, occasion-flexible pieces. The luxury buyers segment commands disproportionate margin pools, though middle-class consumers and first-time buyers drive absolute unit expansion, particularly through online retail channels that bypass traditional specialty jewelry shop overhead structures.
The Kimberley Process Certification Scheme, EU Conflict Minerals Regulation, and India's BIS hallmarking mandate collectively reshape sourcing transparency and product authenticity requirements across multiple jurisdictions. These frameworks elevate compliance costs for unbranded operators while creating market access advantages for entities with established chain-of-custody documentation. Stakeholders must monitor evolving ESG disclosure obligations and synthetic diamond detection standards as determinants of long-term positioning.
Market Dynamics
Blockchain-enabled provenance verification is compressing trust premiums for ethically sourced diamonds while fragmenting competitive advantage away from traditional brand equity toward supply-chain transparency documentation.
Growth Catalysts
- Bridal ceremonial demand:Younger cohorts in India and China formalize household formation through gold-intensive wedding rituals, anchoring volume expansion in these population centers.
- Kimberley Process Certification Scheme:Tightened rough diamond traceability requirements create market access barriers for unbranded operators, concentrating share among documented supply chain holders.
- Recycled precious metals:ESG-mandated sourcing from reclaimed gold and silver streams satisfies institutional procurement criteria for circular economy compliance.
Market Restraints
- Rough diamond supply concentration:Controlled release from major mining jurisdictions constrains midstream cutting and polishing capacity expansion regardless of retail demand signals.
- Gold price volatility:London Bullion Market Association pricing fluctuations compress working capital efficiency for inventory-heavy retail operators.
- Synthetic diamond detection:Laboratory-grown gem identification complexity elevates authentication costs and insurance premiums across the certification pipeline.
Strategic Opportunities
- Vietnam and Indonesia penetration:Underdeveloped branded jewellery retail infrastructure in Southeast Asian middle-income markets offers first-mover network establishment potential.
- EU Conflict Minerals Regulation:Mandatory supply chain due diligence for EU-imported gold creates competitive differentiation for operators with pre-existing chain-of-custody systems.
- Direct-to-consumer digital channels:Bypassing traditional wholesale and specialty retail markups enables margin recapture and customer data ownership for vertically integrated players.
Industry Challenges
- Gemmological certification capacity:Accredited laboratory throughput constraints create bottlenecks for high-value transaction completion, particularly in peak seasonal windows.
- Legacy inventory systems:SKU-level karat and gemstone tracking requirements for BIS hallmarking and blockchain integration demand capital-intensive ERP reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gold and Diamond Jewellery Market |
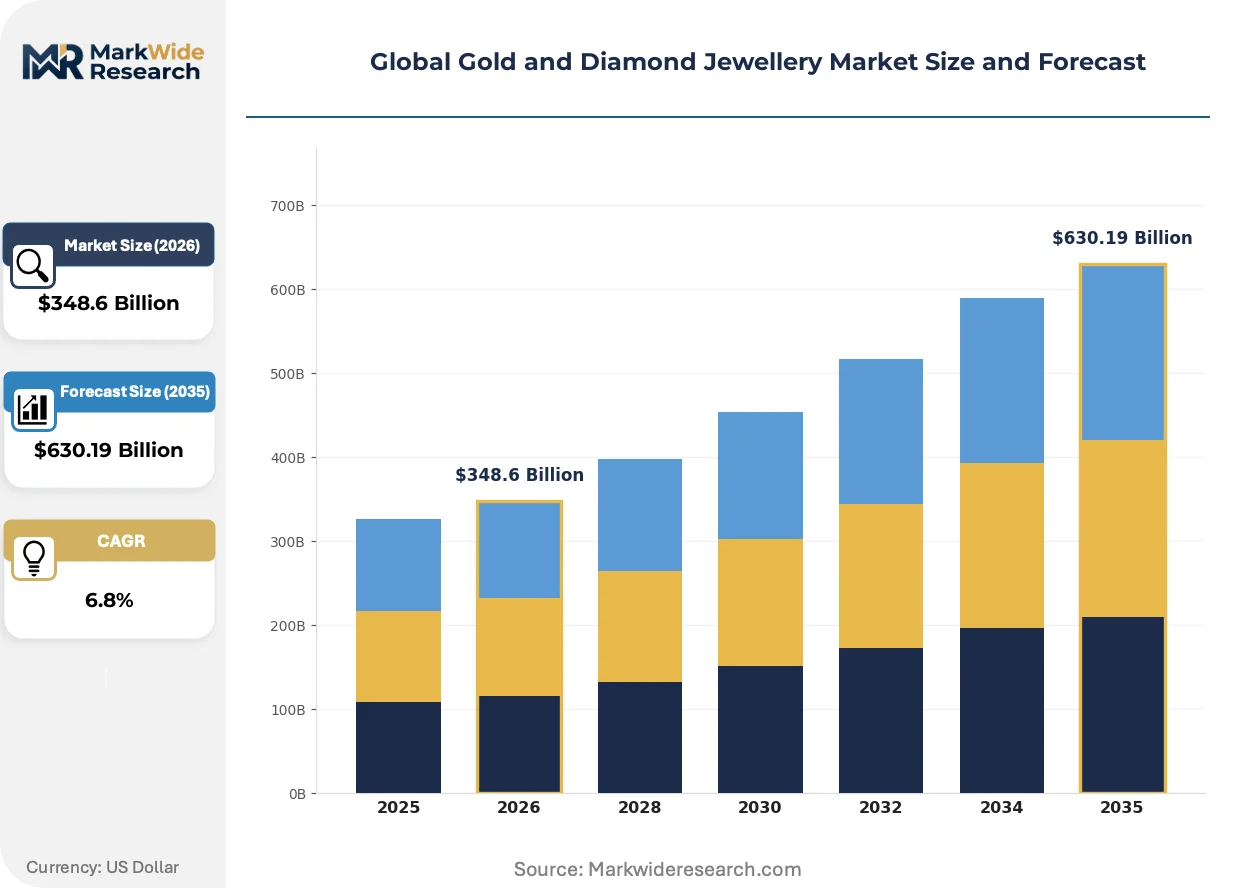
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $630.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rings, Necklaces, Bracelets, Earrings Consumer Segment: Luxury Buyers, Middle-Class Consumers, First-Time Buyers, Gift Purchasers Material: Gold, Platinum, White Gold, Rose Gold Distribution Channel: Online Retail, Department Stores, Specialty Jewelry Shops, Auctions |
| Companies Covered | Chow Tai Fook Jewellery Group, Richemont, Signet Jewelers, LVMH, Tiffany & Co., Cartier, Malabar Gold & Diamonds, De Beers Group, Pandora A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gold and Diamond Jewellery Market Emerging Trajectories
Digital traceability infrastructure and synthetic gem proliferation are bifurcating authenticity verification methods while reshaping how younger consumers assign value to provenance narratives over traditional brand heritage.
Blockchain-based diamond provenance platforms is supplanting paper-based Kimberley Process certificates as the trust infrastructure for high-value transactions. Luxury buyers and institutional procurement officers now require immutable origin documentation, compressing margins for operators dependent on undifferentiated rough sourcing.
EU Conflict Minerals Regulation due diligence obligations are elevating compliance costs for gold refiners and jewellery manufacturers serving European markets. The framework mandates third-party audited supply chain disclosures, forcing consolidation among smaller fabricators lacking documentation systems while advantaging integrated miners with captive smelting operations.
Second-hand and estate jewellery channels are capturing share from primary retail as authentication technologies reduce information asymmetry in pre-owned transactions. Online resale platforms with AI-powered gemstone grading are displacing traditional pawn and auction intermediaries, with this shift most visible among digitally native consumers in North American and Western European urban markets.
Global Gold and Diamond Jewellery Market Segmentation
Segmentation in jewellery markets reveals how margin capture diverges across ceremonial utility, wealth storage function, and self-expression occasions. Understanding these divides exposes where pricing power concentrates and which channels are displacing legacy retail.
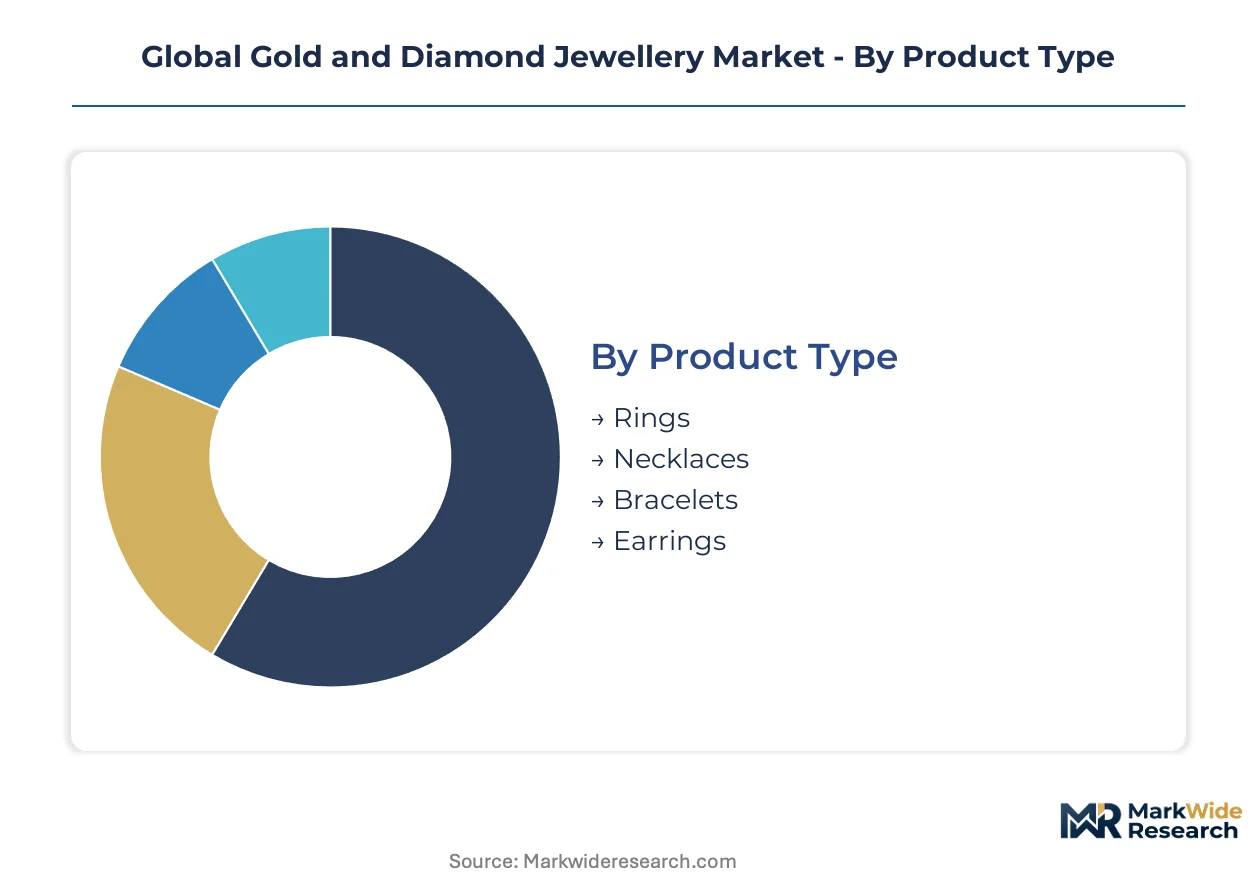
Product Type:
Margin pools concentrate in pieces with ceremonial lock-in and repeat purchase potential, where emotional significance sustains premium pricing.
- Rings:Bridal and wedding bands dominate transaction value through karat-intensive gold specifications and diamond solitaire settings. Demand clusters in Indian and Chinese wedding rituals, where household formation drives multi-piece ceremonial purchases.
- Necklaces:Chain and pendant configurations serve dual purpose as wearable wealth storage and ornamental display. Greater China absorbs volume through Chow Tai Fook's retail network, with temple and festival gifting sustaining replacement cycles.
- Bracelets:Stackable bangles and charm bracelets attract younger demographics seeking occasion-flexible layering options. Pandora's recycled silver and gold offerings anchor accessible price positioning here.
- Earrings:Stud and drop configurations capture fastest growth among digitally native buyers purchasing through direct-to-consumer channels. Lightweight designs reduce gold weight exposure while maintaining margin through gemstone accenting.
The dominant share belongs to rings, while bracelets are closing the gap fastest.
Consumer Segment:
Volume concentration sits with aspirational buyers entering formalized gifting and self-purchase occasions, while absolute margin extraction favors established luxury collectors.
- Luxury Buyers:High-net-worth individuals purchasing signed pieces from LVMH maisons and heritage houses. Bespoke commissioning and rare gemstone acquisition sustain pricing power insulated from gold volatility.
- Middle-Class Consumers:Salaried households in emerging economies accumulating gold through periodic purchases. India's BIS hallmarking mandate shapes trust requirements for this price-sensitive cohort.
- First-Time Buyers:Younger entrants purchasing entry-level pieces through online retail, bypassing specialty jewelry shop markups. Digital-native discovery patterns concentrate this segment in Southeast Asian urban centers.
- Gift Purchasers:Seasonal and occasion-driven buyers selecting standardized pieces with authentication documentation. Corporate procurement for employee recognition programs expands institutional demand here.
Luxury buyers command the widest margins per transaction, though first-time buyers are expanding the customer base most rapidly.
Material:
Working capital intensity and price volatility exposure vary sharply by metal composition, with alloy specifications determining fabrication complexity and regional preference alignment.
- Gold:18K and 22K purities anchor Indian and Middle Eastern markets where cultural accumulation preferences override fashion cycles. London Bullion Market Association pricing directly impacts inventory valuation for retailers.
- Platinum:Dense white metal preferred for diamond settings in North American and Japanese bridal markets. Limited above-ground stock concentrates supply chain control with South African and Russian mining jurisdictions.
- White Gold:Rhodium-plated alloy offering platinum aesthetics at accessible price points. Nickel content variations trigger EU REACH compliance obligations for dermatological safety.
- Rose Gold:Copper-alloyed pink tone capturing fashion-driven demand among younger European and North American consumers. Color consistency requirements elevate refining precision standards.
Yellow gold maintains category leadership by volume, yet platinum is gaining share fastest in high-value bridal applications.
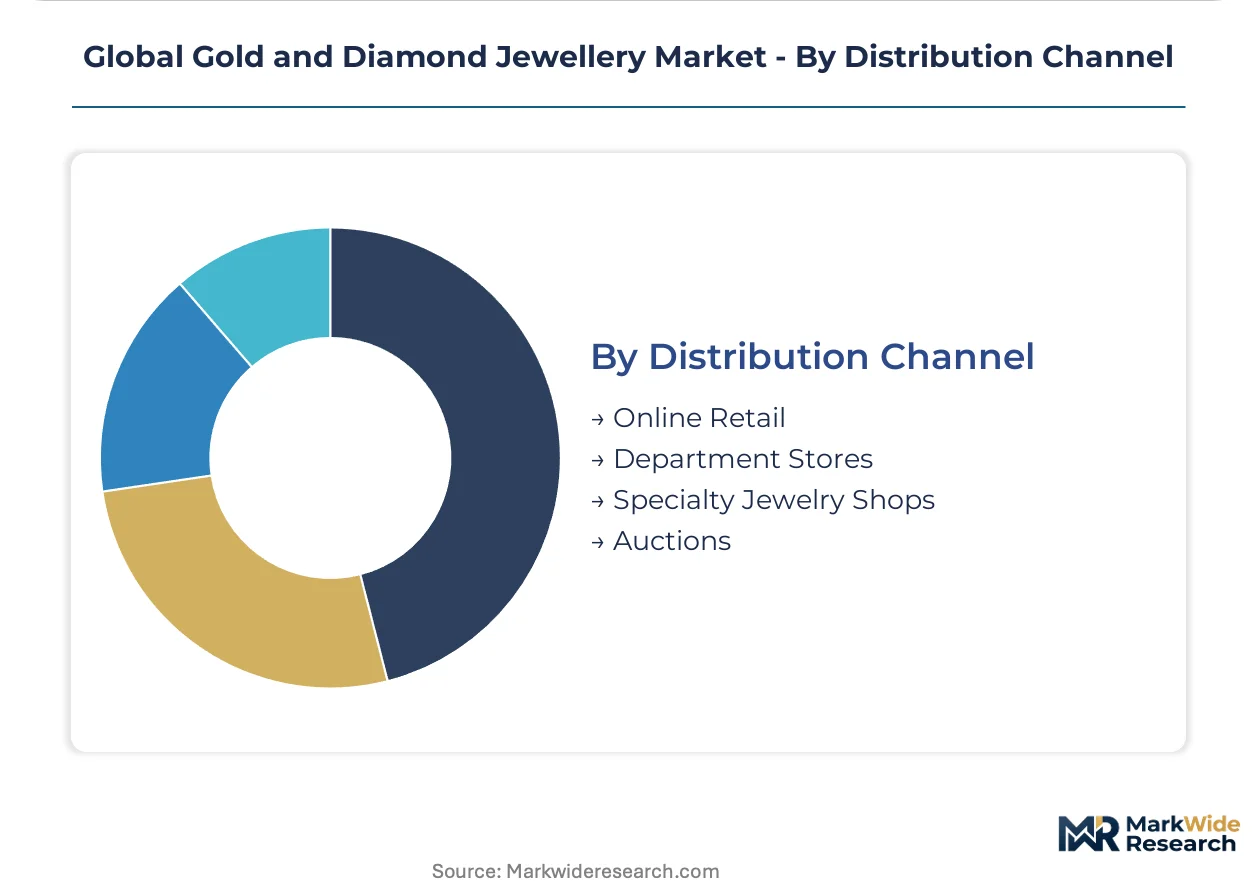
Distribution Channel:
Channel economics determine margin retention versus customer acquisition cost tradeoffs, with digital infrastructure investments reshaping competitive positioning.
- Online Retail:Direct-to-consumer platforms enabling margin recapture and first-party data ownership. Blockchain-enabled provenance verification addresses trust barriers for high-value transactions without physical inspection.
- Department Stores:Multi-brand concessions offering discovery convenience in mature markets. Foot traffic erosion in North American and Western European malls compresses this channel's growth trajectory.
- Specialty Jewelry Shops:Consultative selling environment sustaining premium for complex purchases. Legacy inventory systems face capital-intensive ERP reconfiguration demands for BIS hallmarking compliance.
- Auctions:Estate and secondary market channels benefiting from AI-powered authentication reducing information asymmetry. Sotheby's and Christie's digital platforms expand geographic access for rare pieces.
Specialty jewelry shops retain the largest transaction share currently, while online retail is climbing the fastest as authentication technologies mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Mumbai's Zaveri Bazaar outstrips comparable trading hubs in Dubai by margins reflecting India's cultural gold accumulation norms and the BIS hallmarking mandate's trust premium. This asymmetry shapes how regional markets capture value across the jewellery value chain.
India
Bridal ceremonial demand drives multi-piece gold purchases during wedding seasons, with 22K purity specifications dominating household accumulation preferences. The BIS hallmarking mandate enforces karat authenticity verification, compressing margins for unbranded local fabricators. Mumbai's Zaveri Bazaar and Surat's diamond cutting clusters concentrate midstream polishing capacity and wholesale distribution networks.
China
Greater China's middle-class wealth expansion sustains volume growth through Chow Tai Fook's retail network penetration and festival gifting cycles. SAMR's consumer protection frameworks tighten product disclosure requirements for gemstone treatments and alloy compositions. Shenzhen's jewellery manufacturing district anchors fabrication capacity serving domestic consumption and export channels.
United States
Direct-to-consumer digital channels capture share from traditional specialty retail as authentication technologies reduce trust barriers for online high-value transactions. FTC's Jewelry Guides mandate disclosure of diamond treatments and metal alloy content. New York's Diamond District maintains rough trading and bespoke commissioning concentration despite foot traffic erosion in surrounding retail corridors.
UAE
Dubai's tax-advantaged trading position attracts gold refining and re-export activity serving South Asian and African markets. MOHAP's precious metals regulatory framework aligns with international anti-money laundering standards for bullion transactions. The Dubai Multi Commodities Centre's gold vaulting infrastructure concentrates physical storage and certificate trading for institutional investors.
Belgium
Antwerp's diamond bourse maintains rough trading dominance despite blockchain-enabled provenance platforms fragmenting traditional certification advantages. EU Conflict Minerals Regulation due diligence obligations elevate compliance costs for refiners serving European markets. The city's historic cutting and polishing workshops face capacity constraints from gemmological certification bottlenecks during peak trading windows.
Global Gold and Diamond Jewellery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with upstream miners controlling rough supply documentation and midstream retailers capturing brand-dependent margins. The market structure concentrates around vertically integrated mining houses, extensive retail network operators, and accessible price-point specialists. Three archetypes dominate: rough supply controllers with captive pipeline access, brand heritage houses with luxury positioning, and recycled materials specialists with circular economy credentials. Competitive moves center on blockchain provenance integration and direct-to-consumer channel expansion.
Within the luxury heritage tier, Richemont and LVMH exemplify portfolio diversification across multiple maisons with bespoke commissioning capabilities. Chow Tai Fook Jewellery Group anchors the retail network archetype through Greater China penetration and festival-driven gifting positioning. Pandora A/S occupies the accessible specialist position with recycled precious metals offerings and stackable product configurations targeting younger demographics.
| Leading Market Players |
|---|
| Chow Tai Fook Jewellery Group |
| Richemont |
| Signet Jewelers |
| LVMH |
| Tiffany & Co. |
| Cartier |
| Malabar Gold & Diamonds |
| De Beers Group |
| Pandora A/S |
| Others |
Supply Flow & Price Mechanics
Long-term rough diamond offtake agreements between De Beers Group and sightholder cutting houses lock in both pipeline access and price visibility, insulating midstream polishers from London Bullion Market Association gold volatility while compressing margins for spot-market dependent fabricators.
Pricing Analysis
Customization-premium spreads between bespoke bridal commissions and standardized festival gifting pieces anchor margin stratification across the value chain. Three-tier pricing structure across heritage maisons, established retail networks, and unbranded local fabricators reflects certification documentation depth and chain-of-custody completeness. Pricing pressure stems from synthetic diamond detection costs elevating authentication premiums for mid-tier operators. Middle-class consumers in India exhibit highest price sensitivity due to BIS hallmarking compliance premiums, while luxury buyers remain insulated through bespoke commissioning relationships.
Supply Chain Analysis
Antwerp's diamond bourse chokepoint underwrites rough trading liquidity despite blockchain platforms fragmenting traditional certification advantages. Geographic supply concentration centers on Botswana, Russia, and Canada for rough diamonds, with South Africa and China dominating gold refining capacity. Raw material dependencies include Kimberley Process-certified rough, LBMA-accredited bullion, and rhodium plating chemicals for white gold finishes. Single-source vulnerability concentrates in Russian mining jurisdictions facing EU Conflict Minerals Regulation restrictions. Distribution runs through vertically integrated retail networks in Greater China, specialty jewelry shops in India, and direct-to-consumer platforms in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through BIS hallmarking and Kimberley Process documentation creates switching costs that protect incumbent positions from unbranded competition.
For Market Incumbents: Compound network advantages by extending blockchain provenance integration from rough sourcing through retail certification, countering synthetic diamond substitution threats. Deepen captive smelting operations to secure LBMA-accredited gold streams ahead of EU Conflict Minerals Regulation enforcement. Channel control through festival-driven gifting calendars in Greater China anchors repeat purchase cycles against direct-to-consumer disruption. For New Entrants and Emerging Players: Differentiate on recycled precious metals credentials targeting ESG-mandated institutional procurement in European markets. Vietnam and Indonesia's underdeveloped branded retail infrastructure offers the most penetrable white-space for first-mover network establishment. Go-to-market execution should leverage AI-powered authentication platforms to reduce trust barriers in online resale channels displacing traditional auction intermediaries. For Investors and Strategic Acquirers: Recycled materials specialists with circular economy certifications and established refinery partnerships represent the optimal acquisition target archetype for exposure to ESG-driven sourcing mandates. Long-term viability hinges on defensible documentation systems rather than brand heritage alone. The signal to watch is synthetic diamond detection standard adoption rates as an inflection indicator for authentication technology investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Provenance Integration | Immutable origin documentation from De Beers Group rough through retail sale compresses trust premiums for ethically sourced diamonds. |
| Recycled Metals Sourcing Scale-Up | LBMA-accredited reclaimed gold streams satisfy EU Conflict Minerals Regulation due diligence for circular economy compliance. |
| Direct-to-Consumer Channel Expansion | Bypassing traditional wholesale markups enables margin recapture and first-party data ownership for vertically integrated operators. |
| AI-Powered Authentication Deployment | Machine learning gemstone grading reduces information asymmetry in pre-owned transactions through online resale platforms. |
| Southeast Asian Retail Network Buildout | First-mover establishment in Vietnam and Indonesia captures middle-income household formation through festival gifting cycles. |
Methodological Framework
A spread of perspectives from rough diamond sightholders, BIS-licensed hallmarking centers, retail network operations directors, and EU regulatory compliance officers converged on the working assumptions shaping demand elasticity and certification cost pass-through. Primary fieldwork combined structured interviews with secondary validation against Kimberley Process statistics, LBMA trade flow data, and SAMR consumer protection disclosure filings. Bottom-up unit economics from cutting and polishing clusters in Surat and Shenzhen were triangulated against top-down consumption estimates from Chow Tai Fook and Pandora A/S channel disclosures.
Segmentation dimensions modeled include product type ceremonial utility, consumer segment wealth tier, material karat purity specification, and distribution channel digital penetration across the analysis window. CAGRs were derived from trend extrapolation anchored in bridal cohort household formation rates and middle-class wealth expansion trajectories. Industry-specific forecast inputs incorporated BIS hallmarking mandate compliance cost curves and synthetic diamond detection technology adoption S-curves.
The analysis sits within stated boundaries; outcomes outside sustained Kimberley Process enforcement or abrupt LBMA gold price discontinuities would require recalibration of inventory valuation and working capital assumptions. Practitioners should keep alternative scenarios live as ESG disclosure obligations and laboratory-grown gem identification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Luxury Products for Kids Market
Luxury Goods
China Luxury Market
Luxury Goods
India Watch Market
Luxury Goods
Qatar Luxury Good Market
Luxury Goods
Mens Watch Market
Luxury Goods
Luxury Goods Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Luxury Resale Platform Market
Luxury Goods
North America Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
Hard Luxury Goods Market
Luxury Goods
Luxury Appraisal Service Market
Luxury Goods
South Korea Luxury Goods Market
Luxury Goods
Brazil Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Middle East and Africa Luxury Goods Market