
 Wooden Watch Market | 2026-2036
Wooden Watch Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Watch Market Outlook
Aftermarket service revenue from strap replacement and wood conditioning kits is reshaping how wooden watch brands capture lifetime value from buyers. Holzkern leverages its Austrian woodworking heritage to sustain premium positioning across European specialty retailers. Jord anchors its competitive stance through direct-to-consumer customization platforms that control the full design-to-delivery experience. WeWood differentiates via reforestation-linked product lines that occupy the sustainability narrative in North American and Asian markets.
A wooden watch is a timekeeping instrument constructed with cases, bezels, or bracelets formed from hardwoods such as maple, bamboo, oak, or teak, often paired with mineral glass crystals and Japanese or Swiss quartz movements, primarily serving consumers seeking biodegradable alternatives to metal and plastic accessories. Analog product types dominate current shipment volumes due to their alignment with artisan craftsmanship positioning, while hybrid configurations represent the fastest-growing segment as brands integrate modest connectivity without sacrificing natural material aesthetics. Maple and bamboo material grades command the widest distribution footprint, though teak variants concentrate margin pools in limited-edition collector releases where tropical hardwood scarcity amplifies exclusivity premiums.
FSC chain-of-custody certification governs raw material legitimacy across the European Union, while the EPA's formaldehyde emission standards under TSCA Title VI constrain adhesive and finishing compound selection for wooden components entering the United States. Japan's METI maintains consumer product safety benchmarks that importers must satisfy for quartz movement integration and battery compartment integrity. Stakeholders must monitor evolving deforestation-free supply chain mandates in multiple jurisdictions, as traceability documentation requirements will determine which material sourcing regions remain commercially viable for scaled production.
Market Dynamics
REACH compliance in Europe is compressing adhesive chemistry options for wooden watch manufacturers, forcing reformulation of case-assembly compounds and redirecting sourcing toward certified low-emission suppliers across the Baltic and Alpine regions.
Growth Catalysts
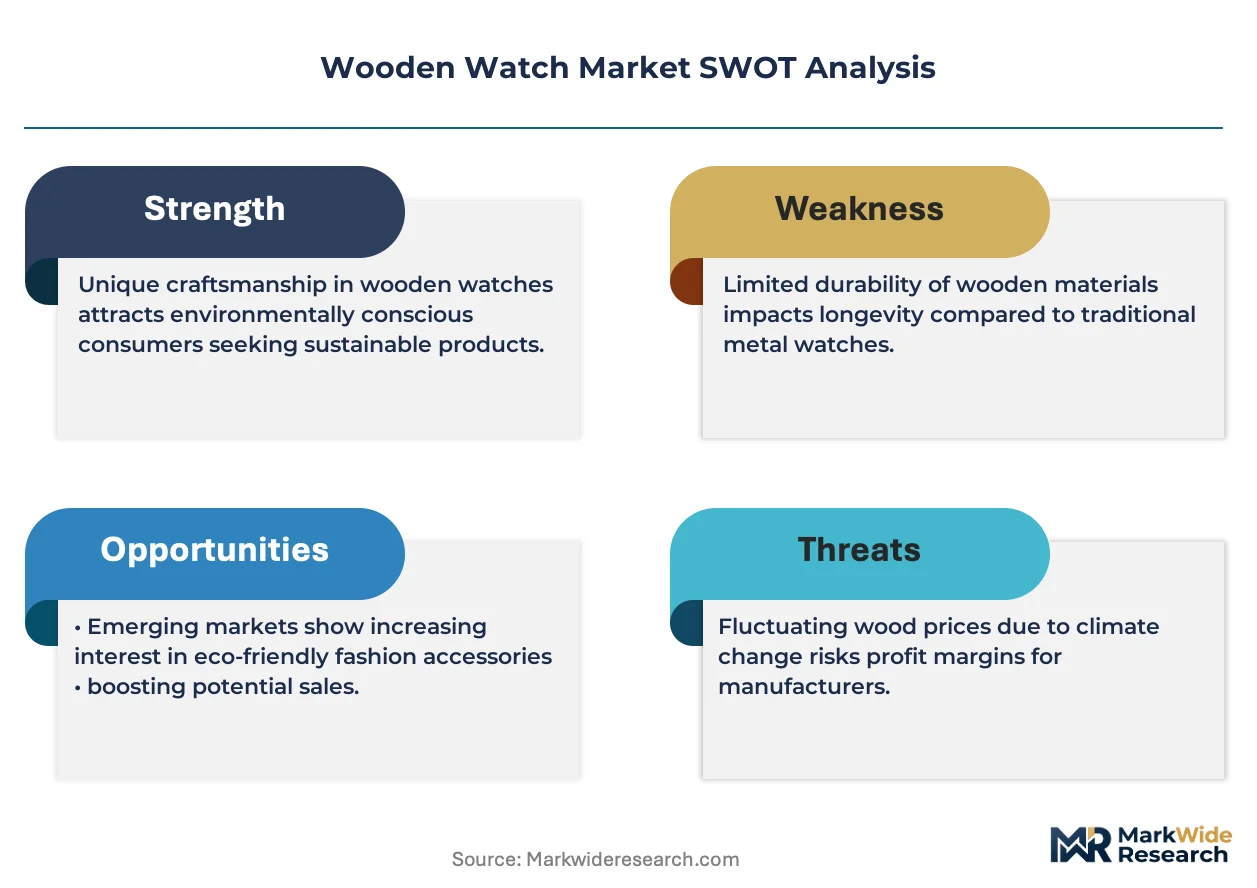
- FSC Chain-of-Custody Mandates:European Union timber legality frameworks validate sustainably harvested maple and bamboo, enabling premium positioning in German and Austrian specialty retail channels.
- Biodegradable Material Substitution:Consumer rejection of petroleum-based accessories accelerates demand for teak and oak alternatives in Japan's artisan craft corridors.
- Artisan Craft Positioning:Analog movement integration with hand-finished hardwood cases commands collector premiums in limited-edition releases.
Market Restraints
- Tropical Hardwood Scarcity:Teak supply concentration in Southeast Asian certified forests limits production scale for high-margin collector tiers.
- EPA Formaldehyde Standards:TSCA Title VI emission thresholds constrain finishing compound selection for wooden components entering United States distribution.
- Quartz Movement Import Friction:Japan's METI safety benchmarks for battery compartment integrity add compliance layers to Asian supply routes.
Strategic Opportunities
- Reforestation-Linked Product Lines:Tree-planting pledges tied to purchase transactions penetrate sustainability-focused North American and Asian consumer segments.
- Hybrid Connectivity Integration:Modest smart features embedded in natural material aesthetics capture tech-curious buyers without alienating craft purists.
- Aftermarket Service Unbundling:Strap replacement subscriptions and wood conditioning kits generate recurring revenue from installed base.
Industry Challenges
- Master Craftsman Shortage:Precision woodworking skills for case and bezel fabrication concentrate in aging Austrian and Japanese artisan pools.
- Deforestation-Free Documentation:Evolving traceability mandates across multiple jurisdictions threaten commercial viability of non-certified sourcing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Watch Market |
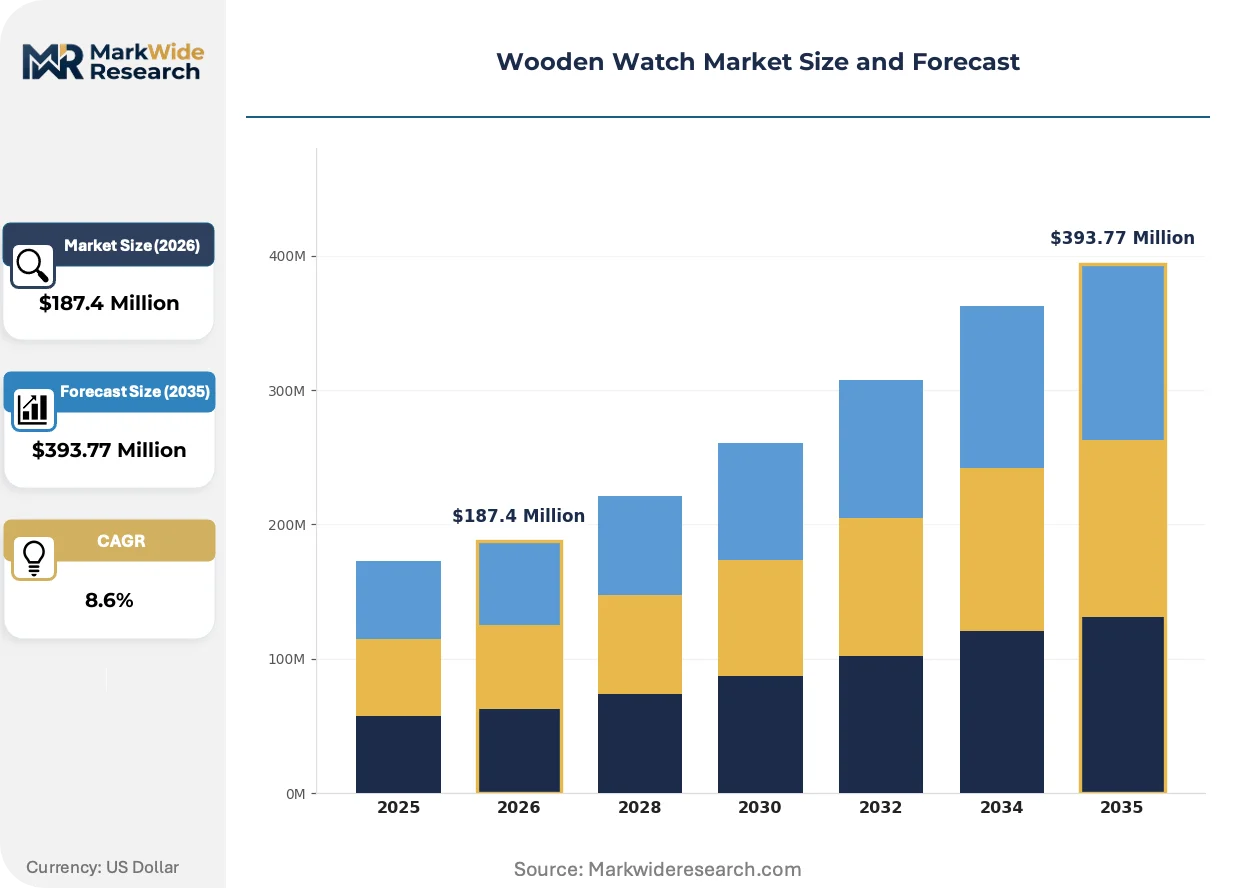
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $393.77 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Hybrid, Smart Material: Maple, Bamboo, Oak, Teak Design Style: Classic, Modern, Minimalist, Vintage Target Audience: Eco-Conscious Consumers, Fashion Enthusiasts, Gift Buyers, Collectors |
| Companies Covered | TMBR, Holzkern, Jord, Treehut, William Wood Watches, Original Grain, WeWood, Mam, Tense, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Watch Market Strategic Shifts
Wooden watch manufacturing is absorbing digital traceability tools and connectivity modules while preserving the tactile authenticity that defines the category's artisan positioning.
Laser-etched serial numbering and blockchain-linked provenance tracking is digitizing supply chain transparency for FSC-certified components. European specialty retailers now require batch-level documentation before stocking new collections. This verification infrastructure compresses gray-market vulnerability while elevating consumer trust premiums.
REACH Annex XVII restrictions on formaldehyde-releasing substances are tightening finishing compound specifications across EU member states. Manufacturers must reformulate shellac and resin sealants or forfeit access to German and Austrian distribution. Japanese importers are mirroring these standards to maintain parity in European export channels.
Direct-to-consumer customization platforms are fragmenting traditional wholesale relationships in North American markets. Buyers now configure case woods, dial materials, and engraving through browser-based design tools. This channel shift concentrates margin capture with brands while reducing specialty retailer intermediation.
Wooden Watch Market Segmentation
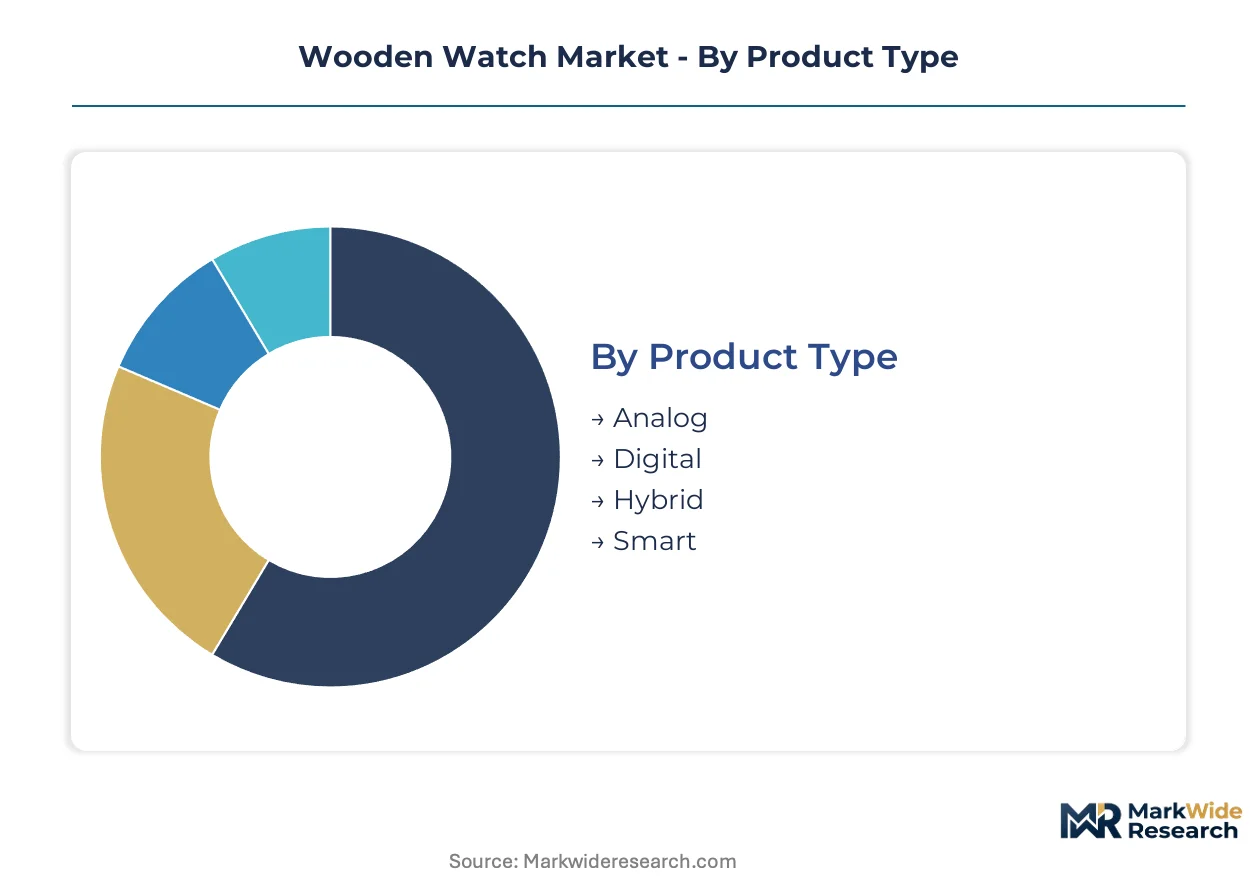
Wooden watch segmentation reveals distinct velocity profiles across product configurations, with analog and hybrid cycles diverging sharply from digital and smart alternatives. Material scarcity and design positioning create tiered replacement rhythms that reshape inventory planning and margin capture strategies for specialty retailers and direct-to-consumer platforms.
Product Type:
Analog configurations turn over slowest due to heirloom positioning and repairability, while smart variants face compressed replacement cycles from battery degradation and connectivity obsolescence.
- Analog:Hand-finished hardwood cases paired with Japanese or Swiss quartz movements dominate current shipment volumes. German and Austrian specialty retailers concentrate demand here, where artisan craft narratives justify premium pricing and extended ownership horizons.
- Hybrid:Modest connectivity features embedded in natural material aesthetics are climbing the fastest, capturing tech-curious buyers in Japan's sustainable fashion districts without alienating craft purists who reject full smartwatch aesthetics.
- Digital:LCD or LED displays housed in bamboo or maple cases serve price-sensitive entry segments.
- Smart:Full-featured wearables with wooden exteriors face battery and software lifecycle constraints.
Analog anchors the volume base while hybrid gains share at the steepest rate.
Material:
Cost tiers separate certified temperate hardwoods from tropical scarcity premiums, with bamboo occupying the lowest landed cost position and teak commanding collector-tier pricing.
- Maple:FSC-certified North American and European temperate hardwood offers the broadest distribution footprint. REACH-compliant finishing compounds from Baltic suppliers sustain access to German retail channels where emission standards are tightening.
- Bamboo:Rapid-renewable grass species with hardness comparable to oak dominates entry-level and mid-market positioning. Japanese importers favor bamboo for its alignment with domestic aesthetic preferences and lower carbon intensity in shipping-weight calculations.
- Oak:Dense European and North American hardwood with pronounced grain patterns suits classic design styling.
- Teak:Tropical hardwood scarcity from Southeast Asian certified forests limits production scale and amplifies exclusivity premiums in limited-edition collector releases.
Maple and bamboo together anchor the volume base while teak expands share fastest among margin-focused tiers.
Design Style:
Customer type and application context determine design selection, with gift buyers and collectors driving divergent aesthetic requirements.
- Classic:Traditional case geometries with Roman numerals and leather straps concentrate in European heritage retail. Austrian woodworking heritage brands leverage this styling for intergenerational gift positioning.
- Modern:Clean lines and integrated wood bracelets appeal to fashion enthusiasts in urban Asian markets.
- Minimalist:Unmarked dials and reduced case profiles serve design-conscious professionals.
- Vintage:Aged finishes and patina effects target collector segments seeking scarcity signaling.
Classic styling anchors the volume base while minimalist configurations expand most quickly among younger demographics.
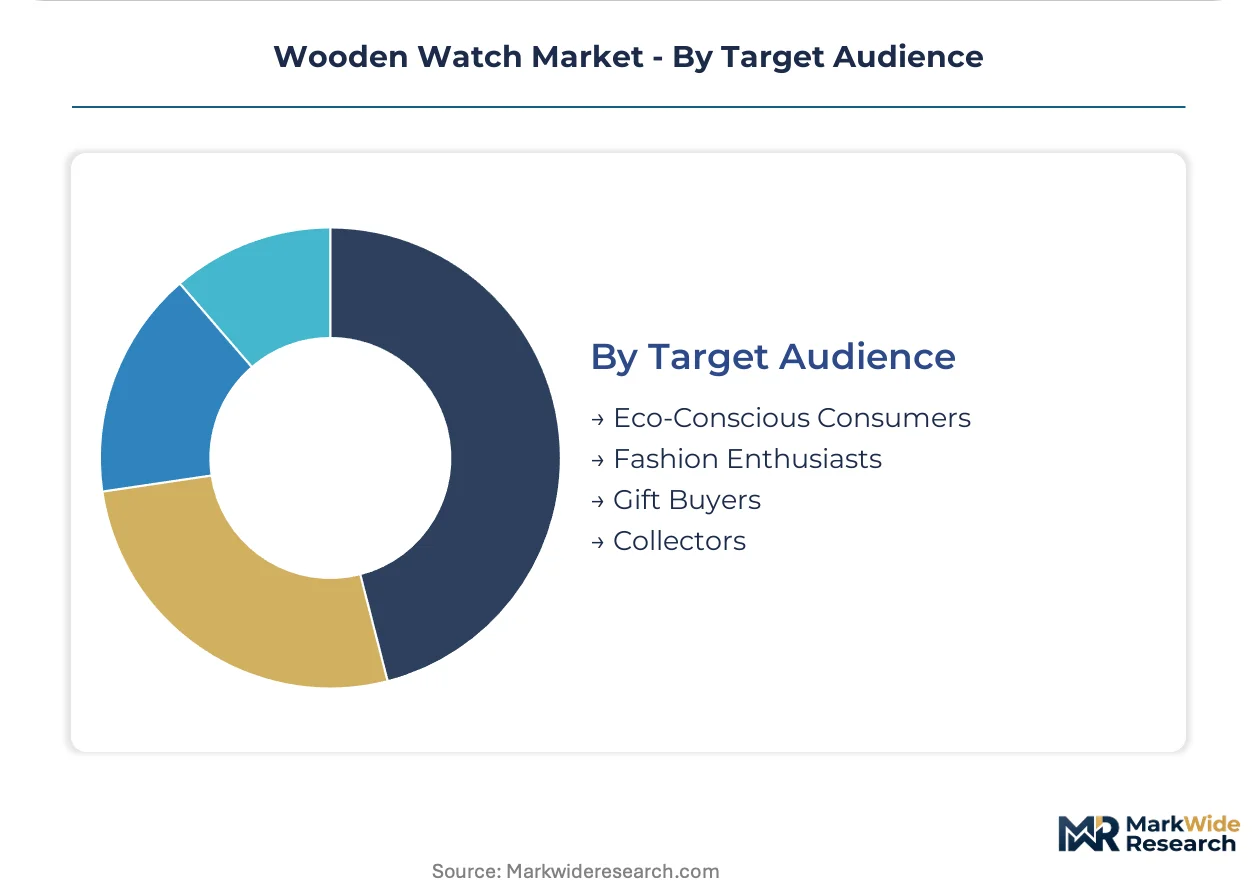
Target Audience:
Procurement patterns diverge sharply between sustainability-motivated self-purchase and occasion-driven gift acquisition, with collectors operating on an entirely separate valuation logic.
- Eco-Conscious Consumers:FSC chain-of-custody documentation and reforestation-linked purchase pledges drive selection criteria. North American and German buyers concentrate here, where biodegradable material substitution motivations override price sensitivity.
- Fashion Enthusiasts:Trend-responsive buyers seeking accessory differentiation through natural material aesthetics. Japanese sustainable fashion districts and European urban style corridors concentrate this demand.
- Gift Buyers:Occasion-driven purchasers prioritizing presentation packaging and engraving services.
- Collectors:Limited-edition seekers focused on tropical hardwood scarcity and artisan provenance documentation.
Eco-conscious consumers anchor the volume base while collectors gain share fastest at the premium tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German buyers show the lowest price elasticity for FSC-certified artisan pieces, while Indian consumers drive volume through entry-level bamboo configurations. Japanese collectors absorb the highest per-unit premiums for limited teak releases. United States demand splits between sustainability-motivated coastal metros and price-sensitive interior markets.
Germany
Heritage woodworking traditions and REACH-compliant specialty retail anchor demand for maple and oak artisan pieces. ECHA emission standards under Annex XVII constrain adhesive formulations, redirecting sourcing toward certified Baltic suppliers. Munich and Hamburg specialty corridors concentrate premium positioning where intergenerational gift buyers validate FSC chain-of-custody documentation.
Japan
Artisan craft retail corridors in Tokyo and Osaka sustain collector premiums for hand-finished hardwood cases with Swiss quartz movements. METI consumer product safety benchmarks govern battery compartment integrity and import compliance. Kyoto's sustainable fashion districts accelerate hybrid configuration adoption among tech-curious buyers seeking natural material aesthetics.
United States
Biodegradable material substitution motivations concentrate in Pacific Northwest and Northeast urban markets, while interior states drive bamboo entry-level volume. EPA formaldehyde emission standards under TSCA Title VI constrain finishing compound selection for wooden components. Brooklyn and Portland maker-retail clusters incubate direct-to-consumer customization platforms that fragment traditional wholesale relationships.
Austria
Alpine woodworking heritage sustains premium positioning across Innsbruck and Salzburg specialty retail channels where artisan provenance commands intergenerational loyalty. REACH compliance mandates validate low-emission shellac and resin sealants from regional suppliers. Vienna design studios anchor limited-edition collector releases where tropical hardwood scarcity amplifies exclusivity premiums.
India
Price-sensitive entry-level demand concentrates in Mumbai and Delhi urban corridors where bamboo configurations serve accessory differentiation seekers. BIS quality benchmarks for consumer goods govern import and domestic manufacturing standards. Bangalore sustainable lifestyle retail incubates reforestation-linked product lines targeting eco-conscious younger demographics.
Wooden Watch Market Competitive Environment
Capability concentration sits with heritage woodworking specialists; scale advantage sits with direct-to-consumer platforms. The vendor base distributes across Austrian craft houses, North American sustainability brands, and Asian volume fabricators. Three archetypes dominate: heritage-certified artisans, reforestation-linked storytellers, and customization-enabled platform operators. Competitive moves concentrate on geographic licensing partnerships and backward integration into certified timber sourcing.
Within the heritage artisan tier, Holzkern exemplifies Alpine woodworking lineage positioning, while Jord anchors direct-to-consumer customization capabilities. WeWood occupies the sustainability narrative vector through reforestation-linked product architecture. These three represent distinct competitive postures: craft authenticity, platform control, and environmental mission integration.
| Leading Market Players |
|---|
| TMBR |
| Holzkern |
| Jord |
| Treehut |
| William Wood Watches |
| Original Grain |
| WeWood |
| Mam |
| Tense |
| Others |
Value Chain & Pricing Dynamics
Baltic Sea container freight corridors feeding German and Austrian specialty retail channels transmit cost volatility from FSC-certified timber sourcing directly into landed price spreads, compressing margins on maple and bamboo entry tiers while amplifying premium capture for teak collector editions where tropical hardwood scarcity insulates pricing power.
Pricing Analysis
Long-term offtake contracts with certified Baltic and Alpine timber suppliers anchor cost predictability for heritage artisan brands, while spot-market bamboo procurement serves volume-oriented entry segments. Three-tier pricing structure across premium teak collector editions, standard maple artisan pieces, and economy bamboo configurations separates buyers by certification grade and movement provenance. Pricing pressure stems from REACH-compliant adhesive reformulation costs that manufacturers must absorb or pass through. Eco-conscious German and Austrian buyers show the lowest price sensitivity, while Indian urban corridors drive volume through cost-optimized bamboo configurations.
Supply Chain Analysis
EU timber legality frameworks under ECHA REACH restrictions constrain raw material flows from non-certified Southeast Asian forests, redirecting sourcing toward FSC-chain-of-custody-validated Baltic and Alpine suppliers. Maple and bamboo feedstock draws from North American temperate forests and Chinese rapid-renewable plantations respectively, while teak remains tethered to limited certified concessions in Myanmar and Indonesia. Single-source vulnerability concentrates in Japanese quartz movement suppliers subject to METI battery compartment integrity mandates. Distribution runs through direct-to-consumer customization platforms that disintermediate traditional European specialty retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a biodegradability fortress against petroleum-based smartwatch and metal accessory substitution, with incumbents navigating pressure from low-cost bamboo alternatives and full-silicon wearable convergence.
For Market Incumbents: Harden defensibility through backward integration into FSC-certified timber concessions in the Baltics, eliminating gray-market exposure while securing emission-compliant adhesive supply chains. Deepen artisan craft narratives with blockchain-linked provenance documentation that justifies collector-tier premiums against mass-market bamboo entrants. Prioritize certification investment as the primary lever against regulatory tightening across EU member states.
For New Entrants and Emerging Players: Indian sustainable lifestyle retail corridors offer the most penetrable white-space for reforestation-linked product architectures targeting younger demographics with tree-planting pledge mechanics. Hybrid connectivity configurations in Japan's Kyoto fashion districts present second-mover opportunity as tech-curious buyers seek natural material aesthetics without full smartwatch compromise. Deploy direct-to-consumer customization platforms as the primary go-to-market angle to bypass entrenched European specialty retail gatekeepers.
For Investors and Strategic Acquirers: Carve-out targets emerge from heritage woodworking houses with dormant Alpine or Japanese artisan pools that could be reactivated under platform-operator ownership. Long-term viability hinges on deforestation-free documentation capabilities that survive evolving traceability mandates across multiple jurisdictions. Watch for inflection when EU chain-of-custody requirements expand to cover finishing compound chemistry beyond raw timber alone.
| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | REACH-compliant timber sourcing secures German and Austrian specialty retail access against regulatory exclusion. |
| Direct-to-Consumer Platform Launch | Jord's browser-based configuration tools concentrate margin capture while reducing retailer intermediation layers. |
| Reforestation-Linked Product Architecture | WeWood's tree-planting pledges penetrate North American sustainability-motivated consumer segments with mission differentiation. |
| Hybrid Connectivity Integration | Modest smart features embedded in natural materials capture Japanese tech-curious buyers without alienating craft purists. |
| Aftermarket Service Unbundling | Strap replacement subscriptions and wood conditioning kits generate recurring revenue from installed base beyond initial purchase. |
Study Parameters
Cross-validation between primary interviews with wooden watch brand executives, FSC certification auditors, and European specialty retail buyers anchors the qualitative findings, while secondary validation draws from customs timber trade data, ECHA REACH regulatory filings, and Japanese METI consumer product safety benchmarks. Bottom-up shipment analysis by material grade and movement type triangulates against top-down market sizing through specialty retail channel audits.
Calibration against historical analog-to-hybrid transition patterns in Japan's sustainable fashion districts and Germany's artisan craft corridors informs the projection framework across the analysis window. Segmentation dimensions model product type, material certification tier, design styling archetype, and target audience motivation. CAGRs derive from installed base replacement rhythm analysis and aftermarket service attach rate trajectories, with quartz movement import friction and tropical hardwood supply concentration as key forecast inputs.
Practitioners should monitor EU deforestation-free supply chain mandate expansion and EPA formaldehyde standard tightening for early signals of sourcing region commercial viability shifts. Forecasts reflect assumptions around FSC certification maintenance rates and artisan craft skill pool replenishment. Material shifts in Southeast Asian teak concession access or Baltic adhesive supplier consolidation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Goods
Pre-Owned Luxury Watches Market
Luxury Goods
China Luxury Market
Luxury Goods
Used Luxury Bags Trading Service Market
Luxury Goods
Luxury Apparels Market
Luxury Goods
GCC Secondhand Luxury Goods Market
Luxury Goods
United Kingdom Luxury Goods Market
Luxury Goods
China Luxury Goods Market
Luxury Goods
Luxury Pen Market
Luxury Goods
UAE Luxury Jewelry Market
Luxury Goods
Luxury Handbag Market
Luxury Goods
India Lab Grown Diamond Jewelry Market
Luxury Goods
Italy Luxury Goods Market
Luxury Goods
Asia-Pacific Luxury Goods Market
Luxury Goods
Secondhand Luxury Goods Market
Luxury Goods
Mens Watch Market
Luxury Goods
India Watch Market