
 Reusable Baby Diapers and Training Pants Market | 2026-2036
Reusable Baby Diapers and Training Pants Market Size, Share, and Industry Trends Forecast 2026-2036
Reusable Baby Diapers and Training Pants Market Analytics
Direct-to-consumer channels are decoupling from conventional retail distribution as subscription-based cloth diaper services gain traction among millennial and Gen-Z parents. Thirsties Baby leverages domestic manufacturing scale to sustain rapid fulfillment cycles for online orders. Bambino Mio anchors European market presence through specialized organic cotton sourcing networks. Kanga Care differentiates via proprietary snap-closure engineering that extends product lifecycle across multiple children.
Reusable baby diapers and training pants comprise absorbent, washable garments constructed from layered natural or synthetic fibers—typically cotton, hemp, bamboo, or microfiber—with moisture-wicking liners and waterproof outer shells designed for repeated use across 200-500 wash cycles. The primary commercial purpose centers on reducing household waste output while lowering lifetime infant hygiene expenditure versus disposable alternatives. Pocket diapers lead volume shipments due to customizable absorbency configurations that parents adapt as infants develop. Bamboo fiber content represents the fastest-growing material segment as suppliers respond to chemical-free certification requirements from organic retailers. All-in-One designs command premium positioning through convenience parity with disposables, concentrating margin pools in specialty boutiques and subscription services.
The EU Green Deal and REACH chemical frameworks restrict synthetic treatments in textile products sold across member states, compelling manufacturers to reformulate waterproof laminates and dye processes. The US EPA and state-level California Safer Consumer Products regulations scrutinize per- and polyfluoroalkyl substance content in water-resistant diaper covers, shaping import compliance costs for Asian suppliers. China's GB standards and SAMR textile labeling rules govern export certification for bamboo and hemp raw materials entering international supply chains. Stakeholders must monitor evolving PFAS restriction timelines and bio-based certification harmonization between jurisdictions to anticipate reformulation investments and sourcing shifts.
Market Dynamics
Subscription-based cloth diaper services are decoupling millennial and Gen-Z parents from conventional retail distribution, compressing traditional wholesale margins while accelerating direct-to-consumer fulfillment infrastructure investments across domestic manufacturing networks.
Growth Catalysts
- EU Green Deal textile mandates:The framework's sustainability certification requirements are pulling organic cotton and bamboo fiber into premium positioning, creating compliant supply pipelines for specialized retailers.
- PFAS restriction timelines:EPA and state-level scrutiny of per- and polyfluoroalkyl substances in water-resistant covers is forcing reformulation investments that favor bio-based laminate suppliers.
- Millennial parent channel preferences:Direct-to-consumer subscription models concentrate demand in Germany, France, and the United Kingdom, bypassing conventional baby-product retail.
Market Restraints
- Input cost volatility:Organic cotton and hemp fiber prices fluctuate with climate-impacted harvests in India and Turkey, squeezing margin stability for certified product lines.
- Supply concentration risk:Waterproof PUL laminate production clusters in Chinese coastal provinces, exposing brands to shipping cost spikes and customs processing delays.
- Technical performance gaps:All-in-One designs still leak at higher rates than disposables during overnight use, limiting category conversion among working parents.
Strategic Opportunities
- Underpenetrated German secondary cities:Subscription services have saturated Berlin and Munich but show minimal penetration in Stuttgart, Leipzig, and Dresden municipal markets.
- REACH-compliant dye processes:ECHA restrictions on azo compounds create first-mover advantage for brands investing in mineral-based colorant R&D.
- Technology convergence:Moisture-sensor integration with smartphone apps enables predictive changing alerts, opening premium pricing tiers for tech-forward parents.
Industry Challenges
- Certification timeline compression:OEKO-TEX and GOTS organic audits require 8-14 month validation cycles, delaying product launches behind competitor announcements.
- Skill scarcity in snap-closure engineering:Proprietary fastening systems demand specialized polymer molding expertise concentrated in legacy apparel manufacturing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reusable Baby Diapers and Training Pants Market |
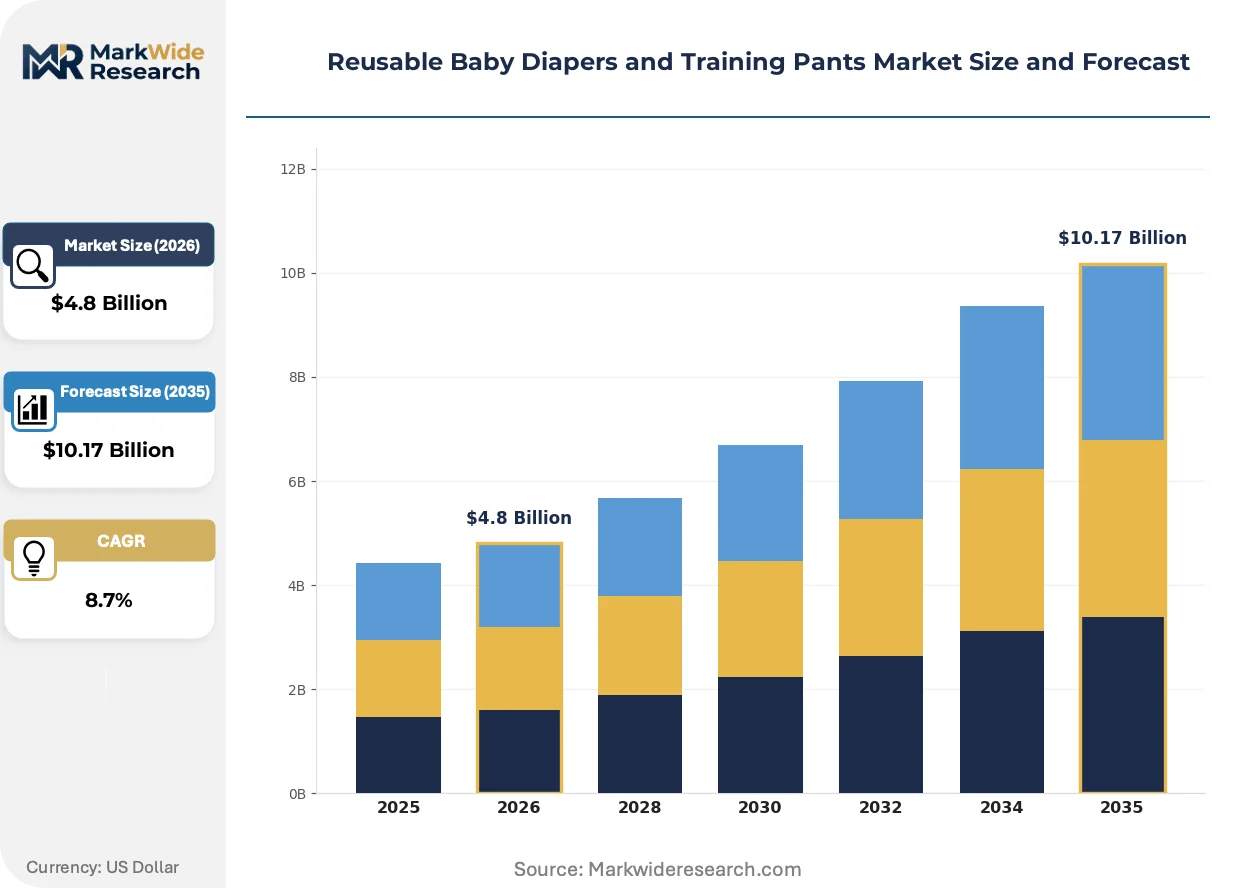
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: All-in-One, Pocket Diapers, Prefold, Fitted Material: Cotton, Hemp, Bamboo, Microfiber Closure Type: Snaps, Velcro, Tie, Pull-On Size: Newborn, Infant, Toddler, One-Size |
| Companies Covered | Procter & Gamble, Thirsties Baby, Bumkins, bumGenius, GroVia, Bambino Mio, Kanga Care, Gerber Childrenswear, ALVABABY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reusable Baby Diapers and Training Pants Market Evolving Landscape
Material science advances and regulatory chemistry restrictions are converging to reshape product architecture, with bio-based alternatives displacing synthetic laminates and smart-textile integration opening service-revenue streams beyond hardware sales.
Adjustable absorbency systems built around removable microfiber and hemp inserts are modularizing product lifecycle value. Parents configure pocket diapers differently across infant development stages, extending usable lifespan across multiple children. This architecture compresses replacement purchase frequency while concentrating margin in insert replenishment rather than shell turnover.
REACH chemical frameworks and the EU Green Deal's textile sustainability requirements are eliminating perfluorinated compounds from waterproof cover production. Manufacturers reformulate polyurethane laminates with plant-derived alternatives or shift to wool cover designs. German and French organic retailers now demand batch-level chemical testing documentation, filtering supplier bases toward vertically integrated mills with in-house certification capabilities.
Millennial parents increasingly reject upfront capital outlays for complete diaper stashes, preferring rental-to-own subscription structures that spread costs across 24-month contracts. Specialty boutiques in London and Paris unbundle after-sales service, offering laundering support and fit-consultation apps. This behavioral pivot concentrates customer lifetime value in recurring service fees rather than single-transaction hardware margins.
Reusable Baby Diapers and Training Pants Market Segmentation
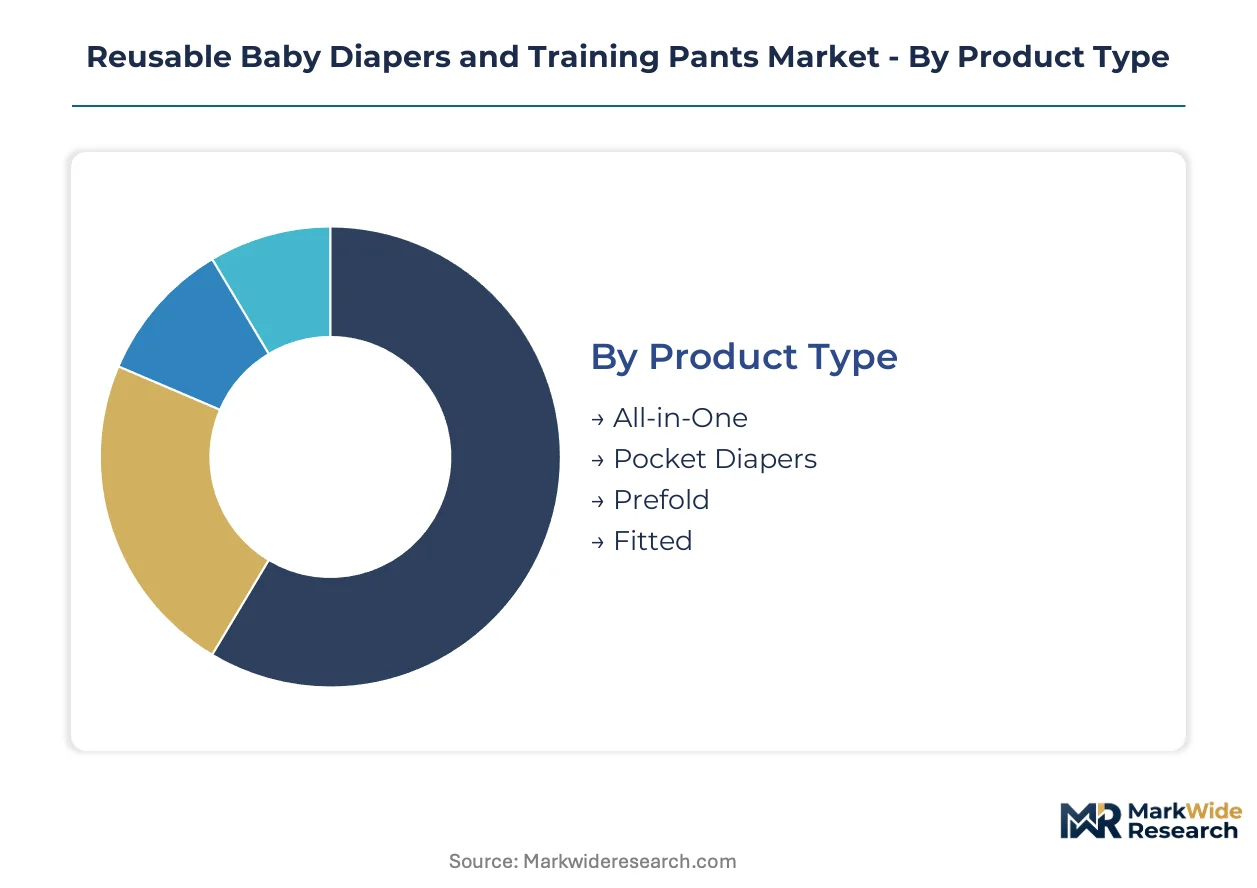
Segmentation in reusable baby diapers and training pants reveals how supply-side specialization maps to distinct parental workflows and certification requirements. Each dimension—product architecture, fiber sourcing, fastening mechanics, and sizing flexibility—carries different margin profiles and compliance burdens that reshape competitive positioning.
Product Type:
Manufacturing capacity clusters around designs that balance wash-cycle durability with parental convenience expectations.
- Pocket Diapers:Shell construction with removable absorbent inserts allows parents to customize hemp or bamboo layering as infants develop. Demand concentrates in German and French direct-to-consumer channels where millennial parents prioritize adaptability across multiple children.
- All-in-One:Integrated absorbent core and waterproof outer eliminate assembly steps, approaching disposable convenience. Premium positioning in London and Paris specialty boutiques reflects working-parent willingness to pay for simplified laundering workflows.
- Prefold:Rectangular cotton layers require folding and fastening with separate covers, maintaining lowest unit economics.
- Fitted:Contoured shape with elastic leg openings demands precise sizing but offers superior overnight containment for heavy wetters.
Pocket Diapers absorb the bulk of installed capacity; All-in-One is expanding most quickly.
Material:
Fiber selection determines certification pathways and exposure to climate-driven harvest volatility.
- Bamboo:Rapid-regeneration grass fibers yield chemical-free certification advantages under EU Green Deal textile mandates. German organic retailers now require batch-level OEKO-TEX documentation, filtering supply bases toward vertically integrated mills with in-house testing capabilities.
- Cotton:Conventional and organic grades dominate volume shipments, with GOTS-certified organic commanding premium positioning in United Kingdom subscription services.
- Hemp:Dense fiber structure provides maximum absorbency but requires softening treatments that complicate REACH compliance.
- Microfiber:Synthetic polyester blends deliver fastest drying times but face scrutiny under per- and polyfluoroalkyl substance restrictions.
Cotton retains the largest production footprint; Bamboo is climbing the fastest on chemical-free demand.
Closure Type:
Fastening mechanics influence product lifecycle extension and manufacturing skill requirements.
- Snaps:Molded polymer fasteners withstand 200-500 wash cycles without degradation, enabling multi-child use. Specialized injection molding expertise concentrates in legacy apparel manufacturing regions, creating capability scarcity for new entrants.
- Velcro:Hook-and-loop systems allow rapid size adjustment but accumulate lint and lose grip over repeated laundering.
- Tie:Fabric closures accommodate infinite sizing flexibility but demand manual dexterity that fatigues caregivers.
- Pull-On:Elastic waistbands support toilet training transitions, concentrating demand in toddler-size SKUs.
Snaps dominate durable goods positioning; Pull-On is gaining share fastest on training-pant conversion.
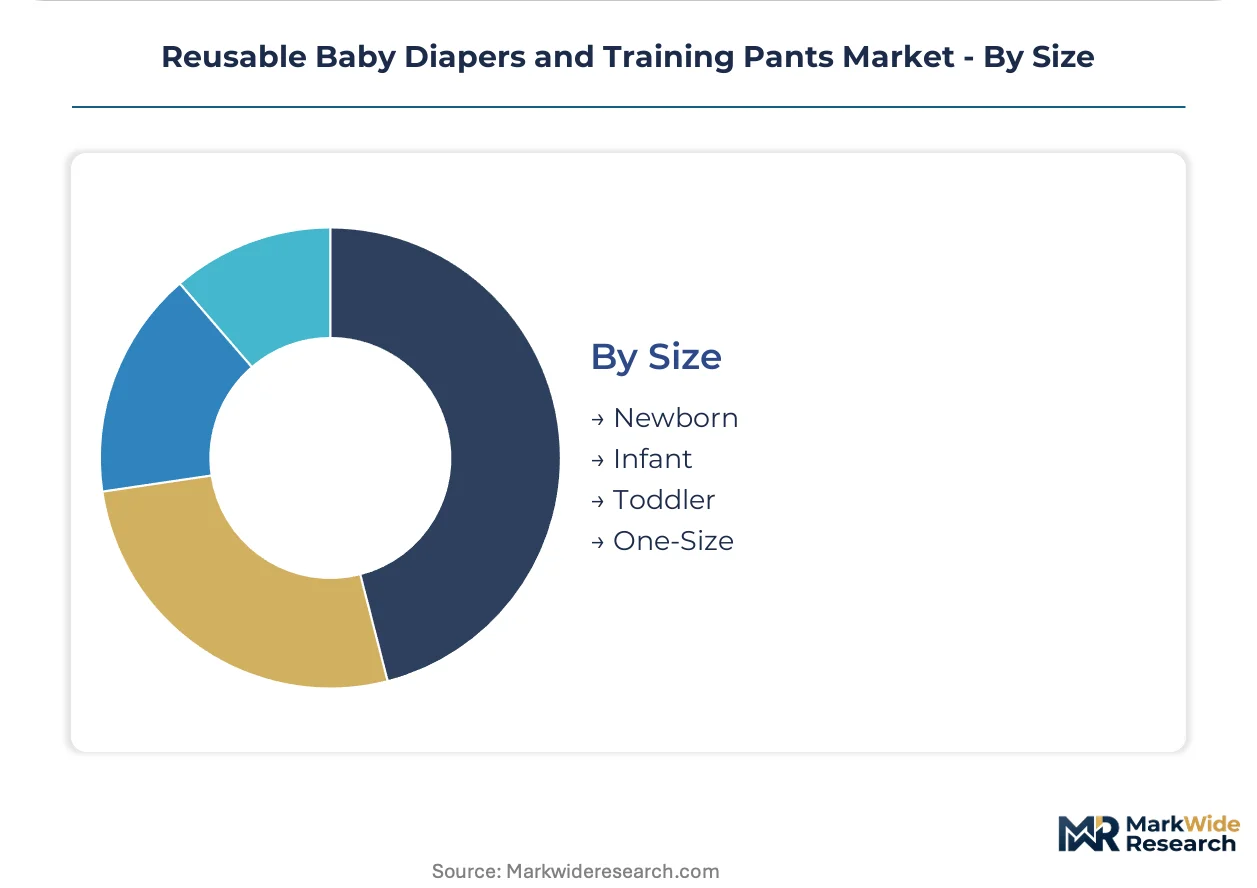
Size:
Dimensioning strategy determines inventory risk and customer acquisition economics.
- One-Size:Adjustable rise snaps and elastic systems span newborn through toddler stages, compressing replacement purchase frequency. United Kingdom subscription services favor this architecture for 24-month rental-to-own contracts that maximize customer lifetime value.
- Newborn:Preemie and low-birth-weight specifications serve hospital discharge kits and niche gifting segments.
- Infant:Mid-range weight bands capture highest transaction volumes but require precise fit consultation to prevent leakage returns.
- Toddler:Extended weight ranges accommodate delayed toilet training trends, particularly in urban German markets.
One-Size commands the broadest SKU efficiency; Toddler is expanding most quickly on delayed training demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and bonded warehousing districts near Hamburg accelerate raw material consolidation for laminate and fiber suppliers serving reusable diaper manufacturers.
Germany
Millennial parents in Berlin and Munich drive subscription service penetration for organic cotton pocket diapers. The EU Green Deal's textile sustainability requirements force batch-level chemical documentation from suppliers. Stuttgart's industrial belt hosts specialized polymer molding operations for snap-closure components.
France
Parisian specialty boutiques anchor premium All-in-One positioning for working-parent convenience segments. ECHA restrictions on azo compounds in REACH frameworks push mineral-based dye process investments. Lyon textile mills develop vertically integrated OEKO-TEX certification capabilities for export markets.
United Kingdom
London subscription services concentrate rental-to-own contract economics for One-Size adjustable systems. GOTS organic certification mandates from major retailers filter supply bases toward audited cotton cooperatives. Manchester's heritage apparel manufacturing districts retain specialized fastening system engineering expertise.
United States
California's Safer Consumer Products regulations scrutinize PFAS content in water-resistant covers, shaping reformulation timelines. EPA state-level enforcement creates compliance cost premiums for imported laminate products. Domestic manufacturing networks in North Carolina sustain rapid direct-to-consumer fulfillment cycles.
China
GB standards and SAMR textile labeling rules govern bamboo and hemp export certification for international supply chains. Yangtze River Delta provinces cluster waterproof PUL laminate production for global brands. Shanghai free trade zones expedite customs processing for certified organic fiber shipments.
Reusable Baby Diapers and Training Pants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium organic positioning concentrating among vertically integrated European mills while Asian fabricators capture volume laminate supply. The vendor base organizes around three strategic archetypes: domestic-scale fulfillment specialists, European organic certification anchors, and Asian component-scale suppliers. Competitive moves concentrate on REACH-compliant dye process investments and moisture-sensor technology licensing for subscription service integration.
Among heritage European specialists, Bambino Mio occupies a position exemplifying organic cotton sourcing network depth. Thirsties Baby represents domestic manufacturing scale advantages in rapid fulfillment cycle delivery. Kanga Care sits within the proprietary engineering tier, anchoring multi-child lifecycle extension through specialized fastening system durability.
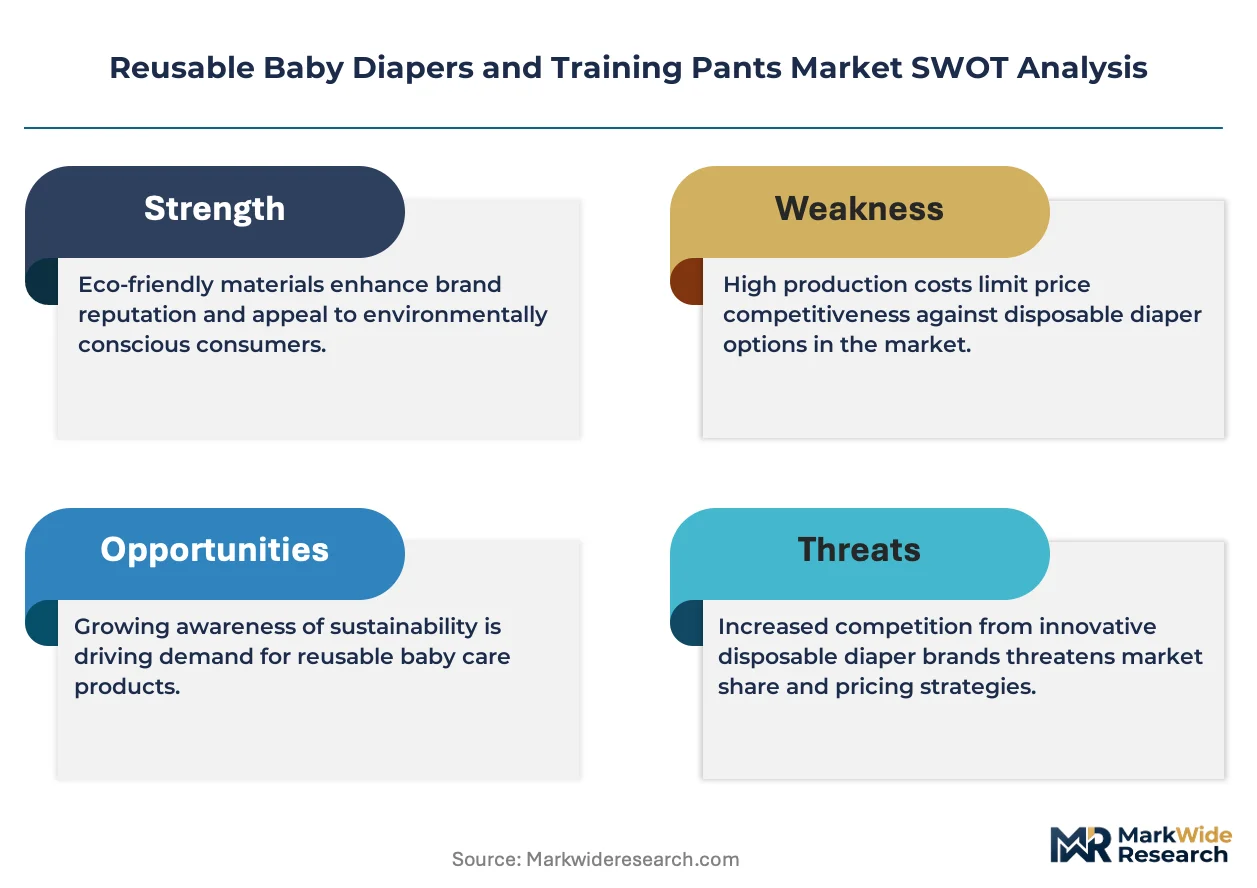
| Leading Market Players |
|---|
| Procter & Gamble |
| Thirsties Baby |
| Bumkins |
| bumGenius |
| GroVia |
| Bambino Mio |
| Kanga Care |
| Gerber Childrenswear |
| ALVABABY |
| Others |
Value Network & Pricing Analysis
Specialized polymer molding expertise concentrated in Manchester's heritage apparel districts and Stuttgart's industrial belt creates labor-cost differentials that widen pricing-tier spreads between premium snap-closure systems and economy Velcro alternatives. This workforce concentration forces brands to absorb higher per-unit costs for durable fastening engineering or sacrifice product lifecycle extension claims.
Pricing Analysis
Short lead-time premiums command substantial markups in direct-to-consumer subscription channels where millennial parents demand rapid replenishment cycles for insert replacements. Three-tier pricing structure across premium, standard, and economy levels separates GOTS-certified organic cotton from conventional grades and synthetic microfiber alternatives. Pricing pressure stems from climate-driven harvest volatility in Indian and Turkish organic cotton regions, squeezing margin stability for certified product lines. Economy-tier buyers in prefold and fitted segments exhibit highest price sensitivity, while premium All-in-One purchasers in London and Paris boutiques prioritize convenience over unit cost.
Supply Chain Analysis
Direct-to-consumer channels handle millennial parent demand through subscription-based fulfillment infrastructure anchored in domestic manufacturing networks. Raw material sourcing draws from Yangtze River Delta provinces for waterproof PUL laminates, Indian cotton cooperatives for GOTS-certified organic fiber, and Turkish hemp processors for absorbent inserts. Single-source vulnerability concentrates in Chinese coastal laminate production clusters exposed to shipping cost spikes and customs processing delays. Distribution runs through bonded warehousing districts near Hamburg and free trade zones in Shenzhen for raw material consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where specialized snap-closure engineering capability scarcity props pricing power for incumbents with captive polymer molding operations.
For Market Incumbents: To counter emerging Asian laminate suppliers undercutting on reformulated bio-based alternatives, secure backward integration into OEKO-TEX-certified dye processes and expand capacity in REACH-compliant European mills. Channel control through exclusive subscription service partnerships defends against direct-to-consumer entrants bypassing traditional retail. For New Entrants and Emerging Players: Specialty boutiques in underpenetrated German secondary cities represent the most accessible entry vector, with Stuttgart and Dresden municipal markets showing minimal subscription service saturation. Mineral-based colorant R&D investments exploit ECHA azo compound restrictions to capture first-mover positioning in French organic retail channels. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated mills possessing in-house OEKO-TEX and GOTS certification capabilities given EU Green Deal textile mandate acceleration. Long-term viability favors targets with established bamboo fiber supply networks and domestic fulfillment infrastructure. The signal to watch is PFAS restriction timeline acceleration in EPA and state-level enforcement jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Dye Process Investment | ECHA azo compound restrictions favor mineral-based colorant R&D in Lyon textile mills. |
| Subscription Service Channel Expansion | Rental-to-own contracts in London and Berlin concentrate customer lifetime value in recurring fees. |
| Bio-Based Laminate Reformulation | Plant-derived polyurethane alternatives displace perfluorinated compounds under EPA scrutiny. |
| Moisture-Sensor Technology Licensing | Smartphone app integration enables predictive changing alerts for tech-forward parent segments. |
| Domestic Manufacturing Scale-Up | North Carolina fulfillment networks sustain rapid direct-to-consumer cycle times versus Asian imports. |
Research Methodology
Trade association filings, customs and shipping records, and OEKO-TEX/GOTS certification databases formed the secondary backbone, cross-referenced with primary interviews across brand managers at specialty boutiques, supply planners at direct-to-consumer subscription services, polymer molding engineers in Manchester and Stuttgart manufacturing districts, and procurement leads at vertically integrated textile mills. Bottom-up shipment data triangulated against top-down consumer expenditure estimates validated volume and value outputs.
Historical trendline analysis across organic cotton price indices, laminate import volumes, and subscription service subscriber growth informed the projection framework. Segmentation dimensions modeled include product architecture, fiber certification tier, closure durability grade, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating PFAS restriction timeline scenarios and millennial parent channel preference shifts.
Caveats apply where EPA enforcement acceleration, EU Green Deal textile mandate expansion, or climate-impacted harvest failures in South Asian cotton regions could materially shift the outlook. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
East Africa Baby Diaper Market
Baby Diapers
Cat Diapers Market
Baby Diapers
Pet Diapers Market
Baby Diapers
United Arab Emirates Baby Diapers and Wipes Market
Baby Diapers
Biodegradable Diapers Market
Baby Diapers
Dog Diapers Market
Baby Diapers
Europe Diaper Market
Baby Diapers
United States Adult Diaper Market
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Middle East and Africa and Asia Pacific Baby Diaper Market
Baby Diapers
Africa and India Baby Diapers Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
GCC Diaper Market