
 Global Baby Swim Pants Diaper Market | 2026-2036
Global Baby Swim Pants Diaper Market Size, Share, and Industry Trends Forecast 2026-2036
Global Baby Swim Pants Diaper Market Analysis
Infant aquatic programming is decoupling from traditional seasonal patterns as heated indoor pools proliferate. Procter & Gamble leverages its North American retail footprint to anchor shelf presence across mass and club channels. Kimberly-Clark differentiates through hospital and birthing-center sampling programs that convert first-time parents. Unicharm Corporation dominates Japan's swim school supply contracts with specialized sizing for Asian infant anthropometrics.
Baby swim pants diapers are engineered as single-use or reusable containment garments featuring elasticized waistbands, hydrophobic outer layers, and absorbent cores that prevent solids release without waterlogging during submersion. Most disposable variants employ superabsorbent polymer composites sealed with ultrasonic bonding to maintain structural integrity in chlorinated or salt water. The disposable product type leads absolute volume while biodegradable formulations capture the fastest growth trajectory as regulatory pressure on petrochemical inputs intensifies. Online retail channels now occupy the margin-rich premium tier, whereas supermarkets compete on promotional bundling of standard polymer-based SKUs.
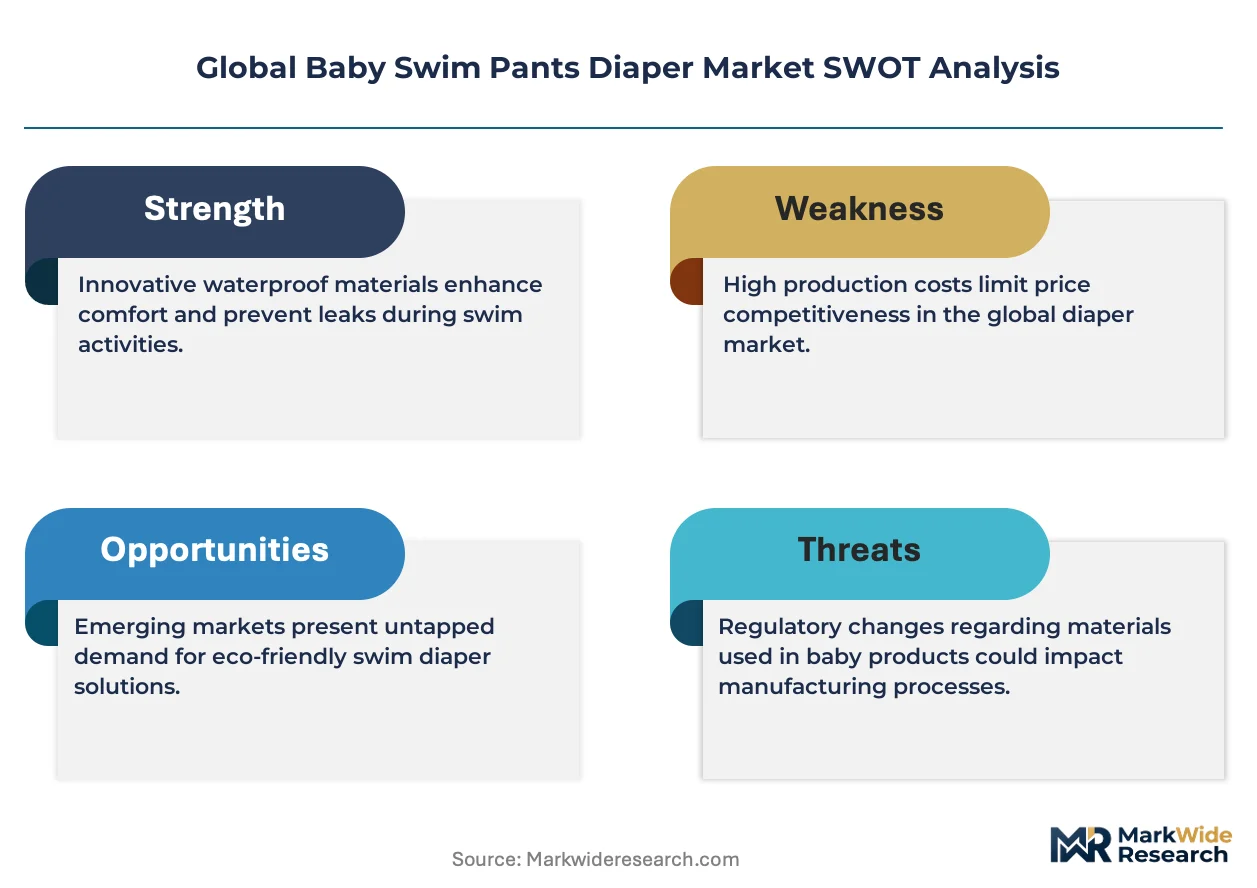
FDA oversight of skin-contact materials shapes absorbent core composition limits for US-bound products, while REACH and the EU Green Deal restrict certain phthalates and mandate recyclability disclosures across European imports. China's GB standards and SAMR labeling requirements add compliance layers for brands sourcing hybrid bamboo-cotton materials from domestic suppliers. Stakeholders must monitor evolving chemical restriction schedules and certification reciprocity agreements between major import jurisdictions to preempt supply chain disruptions.
Market Dynamics
EU REACH chemical restrictions and the EU Green Deal are forcing petrochemical-based absorbent core formulations toward biodegradable polymer substitutes, compressing legacy manufacturing economics while opening premium pricing tiers for compliant producers.
Growth Catalysts
- Indoor Aquatic Infrastructure Expansion:Heated year-round pools in the United States and Japan are decoupling infant swim instruction from seasonal demand patterns, sustaining baseline procurement volumes across swim school networks.
- REACH Chemical Restrictions:European regulatory pressure on phthalates and petrochemical inputs is accelerating R&D investment in bio-based superabsorbent polymers, creating first-mover advantages for compliant manufacturers.
- Hospital Sampling Programs:Birthing centers in North America and Japan are converting first-time parents to branded swim pants through postnatal care bundles, locking in trial-to-repeat purchase pathways.
Market Restraints
- Superabsorbent Polymer Cost Volatility:Petroleum-derived sodium polyacrylate feedstock prices fluctuate with crude oil benchmarks, squeezing margin structures for standard-tier disposable producers.
- Asian Manufacturing Concentration:Bamboo-cotton hybrid material sourcing clusters in China's Yangtze Delta create single-point vulnerability for brands dependent on GB-certified domestic suppliers.
- Biodegradation Performance Trade-off:Current bio-based cores exhibit 15-30% lower structural integrity in chlorinated water versus petrochemical equivalents, limiting competitive substitution rates.
Strategic Opportunities
- Subscription E-Commerce Models:Direct-to-consumer replenishment platforms in the United States are capturing premium-tier households through personalized sizing algorithms and bundled aquatic accessory offerings.
- India Underpenetration:BIS certification requirements and nascent indoor pool infrastructure create whitespace for early entrants targeting urban middle-class parents in Bangalore and Mumbai.
- Dual Carbon Policy Alignment:China's MEE carbon intensity targets are incentivizing domestic producers to develop compostable film layers, opening technology licensing opportunities for foreign patent holders.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous FDA, REACH, and SAMR compliance testing extends product launch cycles by 8-14 months, delaying revenue recognition for reformulated SKUs.
- Ultrasonic Bonding Equipment Scarcity:Specialized sealing machinery capable of handling biodegradable film substrates faces 6-9 month order backlogs from German and Japanese OEMs, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Baby Swim Pants Diaper Market |
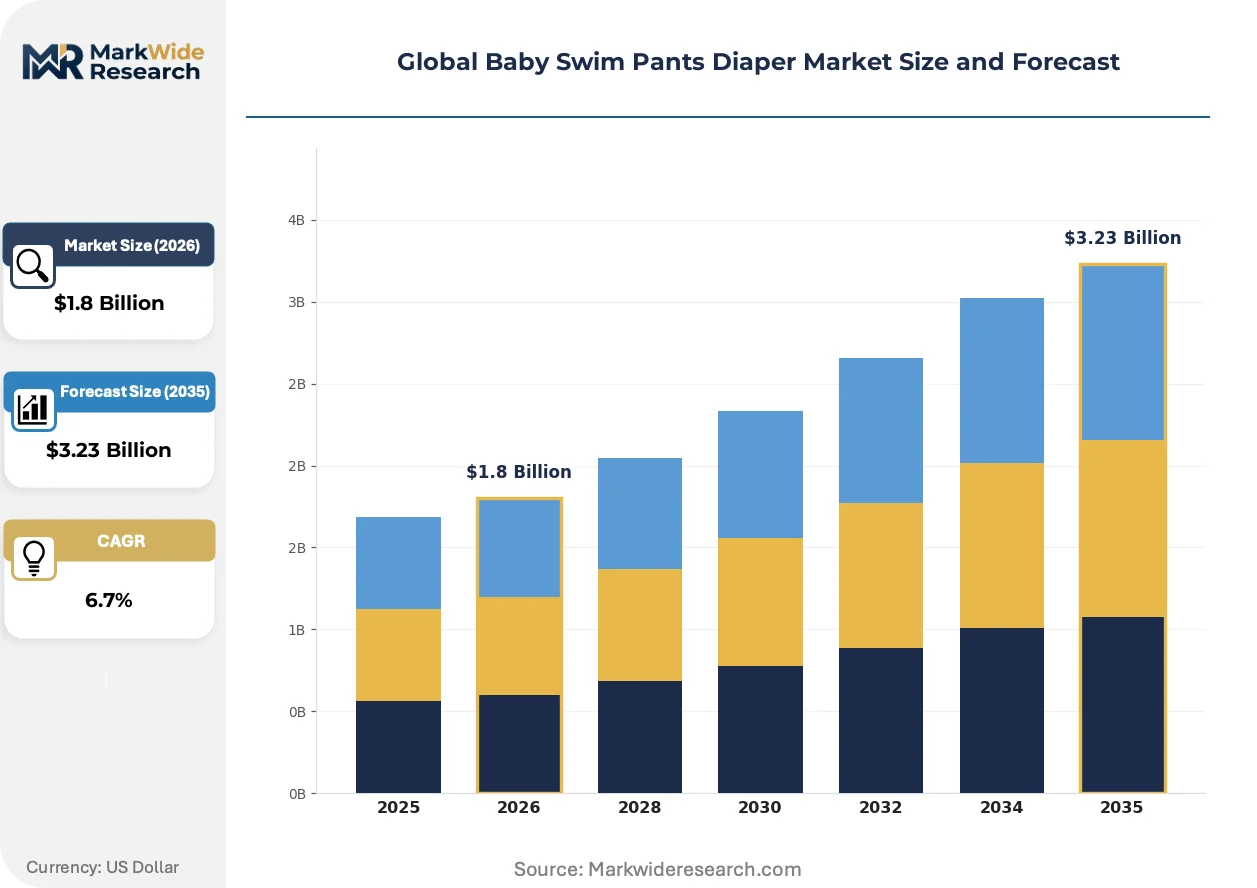
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Reusable, Biodegradable, Eco-friendly Material: Polymer, Cotton, Bamboo, Hybrid End User: Parents, Caregivers, Daycares, Swim Schools Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Procter & Gamble, Kimberly-Clark, Unicharm Corporation, Ontex, Quanzhou Energy Babycare Co., Ltd., Mega Limited, Domtar Corporation, Abena A/S, FINIS, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Baby Swim Pants Diaper Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry mandates are converging to reshape product architecture, manufacturing processes, and channel economics across infant aquatic containment categories.
Algae-derived biopolymer films are unifying hydrophobic barrier performance with marine biodegradability in next-generation outer layers. Japanese swim schools and Nordic municipal pools are piloting these SKUs at 3-5x standard pricing. This substrate convergence is unifying premium positioning with regulatory pre-compliance, compressing the timeline for petrochemical phase-out.
REACH Annex XVII restrictions on phthalate plasticizers are compelling reformulation of elasticized waistband compounds across European-bound production lines. Manufacturers are migrating to citrate-based alternatives, absorbing 12-18% raw material cost premiums. Hospital and birthing-center channels in Germany and France are responding fastest, demanding full material disclosure documentation ahead of 2027 enforcement windows.
Parents in the United States are consolidating aquatic gear purchases through swim school-affiliated digital storefronts, displacing supermarket impulse buying. These vertically integrated platforms bundle swim pants with lesson packages, capturing lifetime value through subscription mechanics. The channel pivot is most visible in Florida, Texas, and Arizona, where year-round programming density supports dedicated inventory allocation.
Global Baby Swim Pants Diaper Market Segmentation
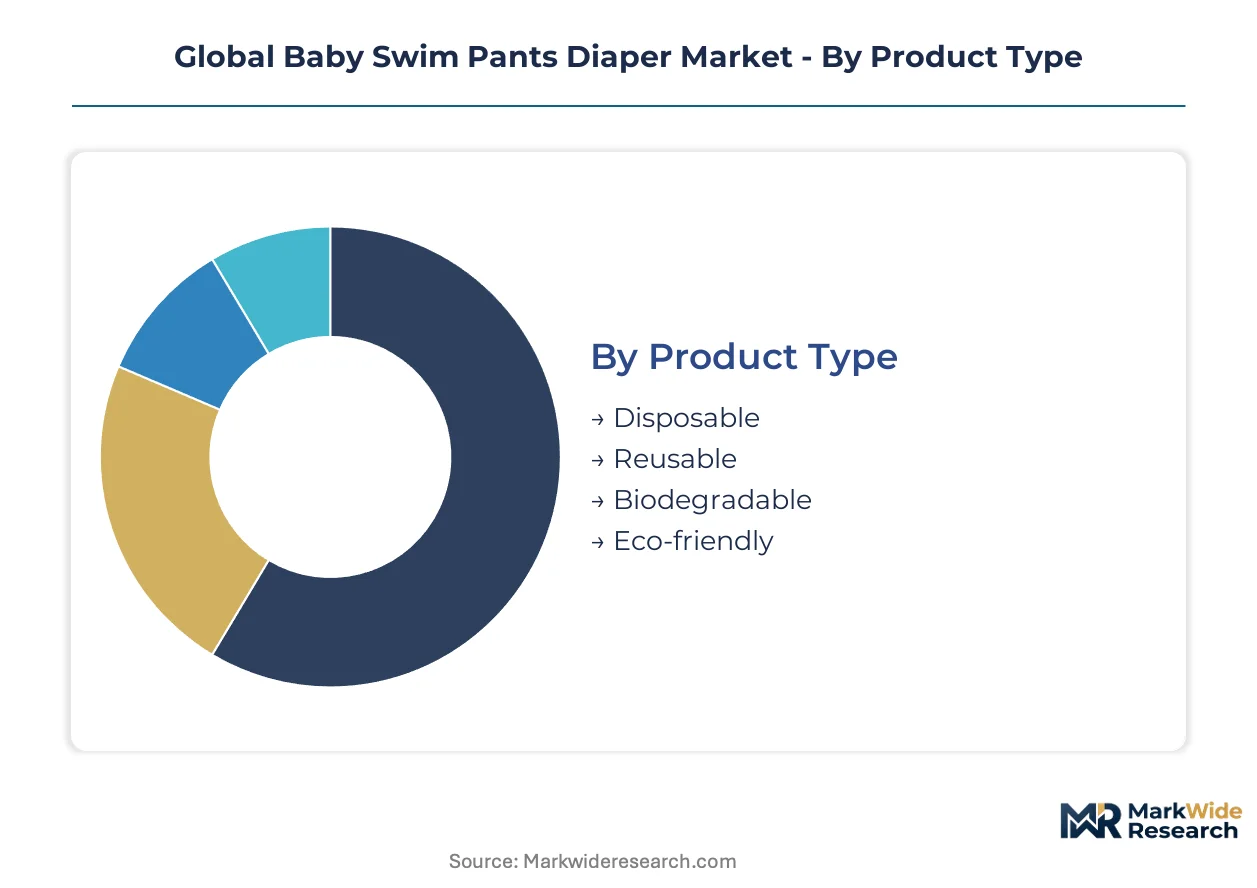
Product architecture in the Global Baby Swim Pants Diaper Market fragments across four distinct category systems. Each dimension carries unique margin implications and regulatory exposure that shape procurement patterns across infant aquatic programming networks.
Product Type:
Supply concentration in polymer conversion facilities favors high-volume disposable formats, while biodegradable lines require specialized compounding partnerships that constrain batch economics.
- Disposable:Ultrasonic-bonded superabsorbent polymer cores dominate procurement volumes across United States swim school networks. Chlorinated water integrity testing exceeds 4-hour submersion standards, locking in specification compliance for institutional buyers in Florida and Texas.
- Biodegradable:Algae-derived film layers and compostable absorbent matrices are climbing the fastest as EU REACH enforcement windows approach. Nordic municipal pools and Japanese aquatic centers absorb 3-5x pricing premiums for marine-degradable certification.
- Reusable:Elasticized PUL laminate shells with snap-in bamboo inserts serve cost-conscious parents in Germany and France.
- Eco-friendly:FSC-certified pulp cores with plant-based wetness indicators target premium-tier households in California and New York.
Today's leader: Disposable. Tomorrow's challenger: Biodegradable.
Material:
Raw material sourcing geography directly determines compliance pathway complexity for cross-border shipment.
- Polymer:Petroleum-derived sodium polyacrylate formulations anchor standard-tier production economics. FDA absorbent core limits and REACH phthalate restrictions are forcing reformulation timelines that extend 8-14 months for United States and European-bound SKUs.
- Hybrid:Bamboo-cotton blends with bio-based superabsorbent interlayers represent the fastest-growing specification as China's MEE carbon intensity targets incentivize domestic supplier conversion. Yangtze Delta manufacturing clusters face GB standards certification backlogs that constrain export capacity.
- Cotton:Organic long-staple varieties from Indian Gujarat suppliers serve reusable segment demand in European natural parenting channels.
- Bamboo:Viscose-processed fibers from Sichuan plantations dominate Asian eco-premium positioning.
Polymer retains volume dominance. Hybrid materials are expanding most quickly.
End User:
Procurement authority concentration varies sharply across institutional versus household decision structures.
- Swim Schools:Year-round heated pool networks in Arizona and Florida consolidate bulk purchasing through affiliated digital storefronts. Subscription mechanics capture lifetime value through bundled lesson packages and automatic replenishment algorithms.
- Parents:First-time buyers in North America convert through hospital sampling programs that establish trial-to-repeat pathways. Birthing center partnerships by major manufacturers lock in brand preference before retail exposure.
- Daycares:Municipal licensing requirements in France and Germany mandate aquatic program participation, institutionalizing category demand.
- Caregivers:Grandparent-purchased gift sets concentrate in Japanese department store channels during summer gifting seasons.
Swim schools command procurement scale. Parent households drive margin extraction.
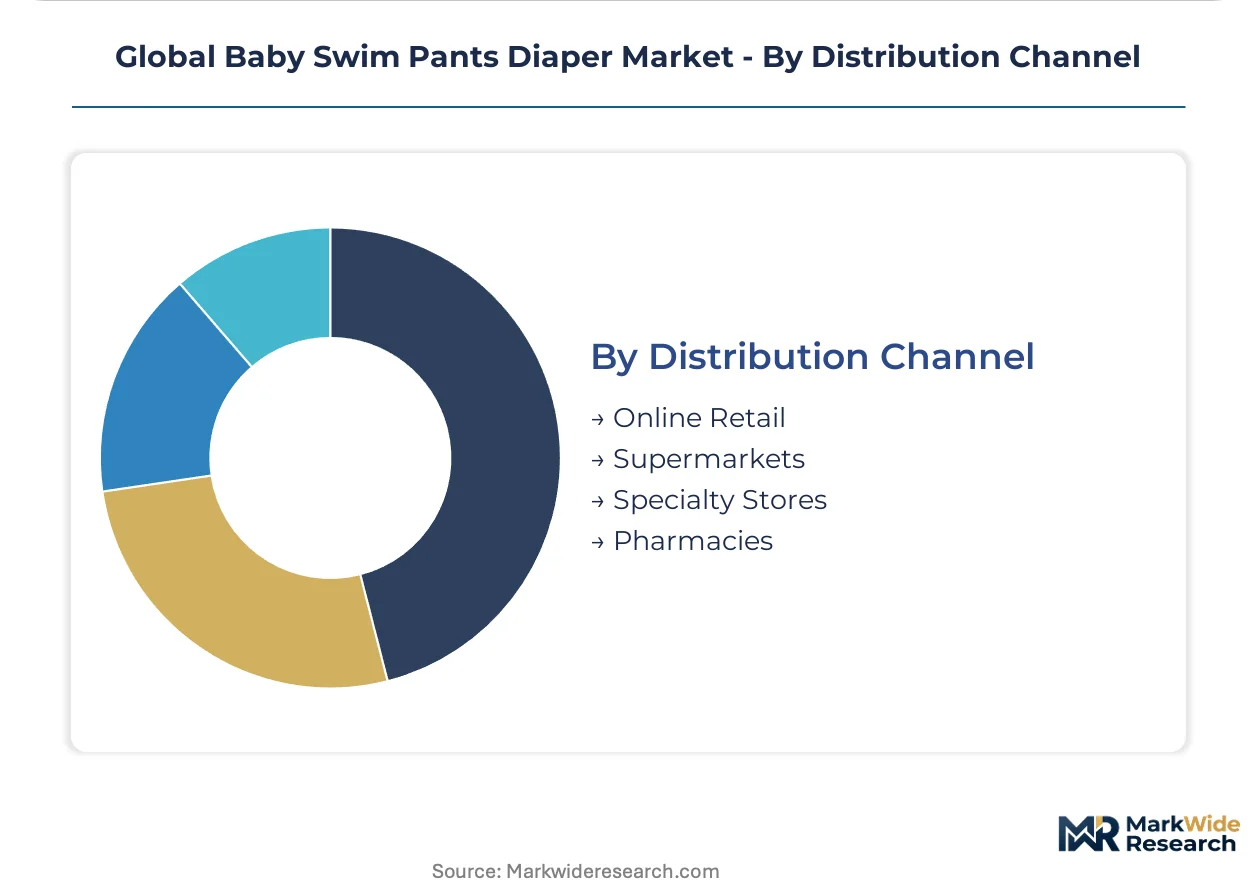
Distribution Channel:
Channel selection stratifies pricing realization and inventory risk allocation between manufacturers and retailers.
- Online Retail:Direct-to-consumer platforms in the United States deploy personalized sizing algorithms and aquatic accessory bundling. Premium-tier households accept 20-35% price elevation versus mass retail for convenience and subscription loyalty benefits.
- Supermarkets:Promotional bundling of standard polymer SKUs in Walmart and Target locations competes on unit economics. Shelf space allocation favors manufacturers with club channel presence and mass merchandising infrastructure.
- Specialty Stores:Independent baby boutiques in Germany and France stock full material disclosure documentation ahead of regulatory enforcement.
- Pharmacies:CVS and Walgreens locations capture impulse replacement purchases during travel and vacation seasons.
Online retail captures premium positioning. Supermarkets defend volume throughput.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate toward jurisdictions with lower compliance costs for petrochemical-based absorbent cores, while premium-tier capacity clusters in high-enforcement markets to capture biodegradability premiums.
United States
Year-round heated indoor pools in Florida, Texas, and Arizona sustain institutional procurement volumes that decouple demand from seasonal patterns. FDA absorbent core composition limits shape formulation standards for all domestic-bound production. Dallas-Fort Worth distribution hubs consolidate inventory for mass retail replenishment across the Sun Belt swim school networks.
China
GB standards and SAMR labeling requirements govern hybrid bamboo-cotton sourcing from Yangtze Delta manufacturing clusters. MEE carbon intensity targets incentivize domestic producers to develop compostable film layers for export markets. Shanghai-based compounders are scaling bio-based superabsorbent polymer pilot lines to serve European-bound SKU demand.
Germany
REACH Annex XVII phthalate restrictions and EU Green Deal recyclability mandates are accelerating reformulation timelines for elasticized waistband compounds. ECHA enforcement windows extending through 2027 compress legacy manufacturing economics. Bavarian chemical specialists are licensing citrate-based plasticizer alternatives to diaper manufacturers.
Japan
METI industrial standards and PMDA skin-contact material oversight govern product specifications for domestic swim school supply contracts. Specialized sizing for Asian infant anthropometrics anchors Unicharm's institutional channel dominance. Kanto region aquatic centers are piloting algae-derived biopolymer films at 3-5x standard pricing tiers.
India
BIS certification requirements and nascent indoor pool infrastructure in Bangalore and Mumbai create whitespace for early entrants targeting urban middle-class parents. CDSCO and FSSAI parallel oversight adds compliance layering for imported hybrid materials. Maharashtra-based distributors are building cold-chain logistics for premium-tier product penetration.
Global Baby Swim Pants Diaper Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers scramble to install ultrasonic bonding equipment capable of handling biodegradable film substrates. The vendor base stratifies across three tiers: multinational hygiene conglomerates with mass retail infrastructure, regional specialists with swim school direct contracts, and emerging bio-material compounders with regulatory pre-compliance positioning. Strategic archetypes include scale-driven mass merchandisers, compliance-first premium formulators, and subscription-platform integrators. Technology licensing and backward integration into bio-polymer feedstock sourcing represent the dominant competitive moves.
Among Cincinnati-based conglomerates, Procter & Gamble occupies the scale-driven tier through mass and club channel shelf presence. Irving-based Kimberly-Clark exemplifies the sampling-conversion archetype via hospital and birthing-center partnerships. Tokyo-based Unicharm Corporation anchors the regional-specialist position through swim school supply contract dominance in Asian markets.
| Leading Market Players |
|---|
| Procter & Gamble |
| Kimberly-Clark |
| Unicharm Corporation |
| Ontex |
| Quanzhou Energy Babycare Co., Ltd. |
| Mega Limited |
| Domtar Corporation |
| Abena A/S |
| FINIS, Inc. |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between marine-biodegradable and standard polymer tiers splits procurement economics across European and North American swim school networks. REACH-compliant formulations absorb 12-18% raw material premiums while commanding 3-5x shelf price elevation, compressing legacy manufacturing margins and redrawing supplier qualification thresholds.
Pricing Analysis
Retailer markup layers stratify across mass club channels and swim school-affiliated digital storefronts. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, volume scale, and geographic delivery cost. Price differentiation intensifies as biodegradable SKUs face cost compression from petroleum-derived sodium polyacrylate feedstock volatility. Parent households demonstrate highest price sensitivity through supermarket promotional bundling, while Nordic municipal pools accept premium positioning for marine-degradable certification.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given single-use product architecture, though reusable PUL laminate shells in Germany and France generate modest reverse logistics volumes. Manufacturing concentrates in China's Yangtze Delta, Japan's Kanto region, and the United States Gulf Coast. Raw material sourcing draws from Sichuan bamboo plantations, Saudi petrochemical complexes, and Indian Gujarat organic cotton suppliers. Single-source vulnerability clusters around GB-certified hybrid material suppliers. Distribution runs through Dallas-Fort Worth hubs for mass retail replenishment and Shanghai export terminals for European-bound biodegradable SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as infant aquatic programming institutionalizes and procurement authority concentrates in swim school networks demanding certified performance specifications.
For Market Incumbents: Hedge against REACH enforcement acceleration by securing citrate-based plasticizer supply agreements with Bavarian chemical specialists before 2027 compliance windows. Anchor shelf position through backward integration into algae-derived biopolymer feedstock sourcing, locking in premium-tier capacity before ultrasonic bonding equipment backlogs extend beyond nine months. For New Entrants and Emerging Players: Swim school-affiliated digital storefronts offer the most penetrable channel route for bypassing mass retail slotting fee barriers. Target urban middle-class parents in Bangalore and Mumbai through BIS certification pre-investment and cold-chain logistics partnerships with Maharashtra distributors. Lead with subscription mechanics bundling swim pants with lesson packages to capture lifetime value. For Investors and Strategic Acquirers: Asymmetric upside sits with bio-material compounders holding regulatory pre-compliance positioning in EU and Japanese enforcement jurisdictions. Five-to-ten year viability favors patent holders in compostable film layer technology with licensing revenue potential from Chinese domestic producers under MEE carbon intensity targets. Monitor ECHA enforcement window announcements and SAMR reciprocity agreements for inflection timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Formulation Transition | REACH Annex XVII compliance secures European market access before 2027 enforcement. |
| Swim School Direct Contracting | Arizona and Florida year-round networks institutionalize procurement volume stability. |
| Algae-Derived Biopolymer Licensing | Japanese Kanto region pilots validate 3-5x premium pricing acceptance thresholds. |
| Ultrasonic Bonding Capacity Expansion | German and Japanese OEM equipment scarcity constrains competitor scale-up timelines. |
| Hospital Sampling Program Scale | North American birthing center partnerships lock in trial-to-repeat conversion pathways. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with swim school procurement directors, diaper manufacturing plant managers, pediatric aquatic program coordinators, and retail category buyers with secondary validation. FDA absorbent core filings, ECHA REACH substance restrictions, SAMR labeling databases, and Nielsen retail audit data anchored bottom-up volume estimates against top-down macroeconomic triangulation.
Segment-weighting across product type, material composition, end user archetype, and distribution channel dimensions structured the analytical framework. CAGRs derived from elasticity-adjusted demand curves incorporating indoor pool infrastructure build rates, regulatory enforcement calendars, and petrochemical feedstock price indices. Infant anthropometric sizing variations and chlorinated water integrity testing standards informed regional adoption pattern modeling across the projection horizon.
Regulatory schedule acceleration, raw material supply disruption, and swim school network consolidation are the dominant revision risks to forecast assumptions. Practitioners should monitor ECHA enforcement announcements, Yangtze Delta manufacturing cluster output, and Sun Belt aquatic program expansion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Diapers
Baby Training Diaper Market
Baby Diapers
Malaysia Diapers Market
Baby Diapers
Baby Diaper Manufacturing Machine Market
Baby Diapers
Baby Disposable Diapers Market
Baby Diapers
Reusable Baby Diapers and Training Pants Market
Baby Diapers
GCC Diaper Market
Baby Diapers
North America Diaper Market
Baby Diapers
Nonwoven Baby Diaper Market
Baby Diapers
Baby Diapers Market
Baby Diapers
Smart Connected Diaper Market
Baby Diapers
UAE Baby Diapers Industry Market
Baby Diapers
Diaper Market
Baby Diapers
Biodegradable Baby Diapers Market
Baby Diapers
Baby Cloth Diaper Market
Baby Diapers
Adult Diapers Market
Baby Diapers
China Pant Type Adult Diaper Market