
 Digital Lending Platform Market | 2026-2036
Digital Lending Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Lending Platform Market Intelligence
The digital lending platform market is pivoting around a widening split between premium AI-native underwriting stacks and commodity loan origination software. Affirm Holdings, Inc. leverages its proprietary risk models to dominate point-of-sale consumer financing. Upstart Holdings Inc. sustains its edge through machine learning-driven credit scoring that extends beyond FICO parameters. Klarna anchors its position in buy-now-pay-later workflows across European retail networks.
A digital lending platform is a software system that automates the entire credit lifecycle from application through disbursement and servicing, typically integrating APIs for identity verification, bank account linking, and real-time decision engines that render approval judgments in under sixty seconds. Its primary commercial purpose is to reduce origination costs, compress time-to-funding, and expand credit access through algorithmic risk assessment. Cloud-based deployment leads in new implementations as banks and fintech companies prioritize elastic infrastructure over fixed on-premise capacity. Artificial intelligence and machine learning segments capture disproportionate R&D investment as alternative data sources displace traditional bureau scores. Peer-to-peer lending remains structurally constrained by regulatory capital requirements in most jurisdictions.
The Consumer Financial Protection Bureau shapes US market conduct through fair lending enforcement and adverse action notice requirements, while the Reserve Bank of India mandates digital lending guidelines that restrict unregulated third-party involvement in credit flows. The EU AI Act imposes risk classification obligations on automated credit decisioning systems deployed across member states. Stakeholders must monitor how divergent compliance architectures across the US, India, and Europe affect platform interoperability and cross-border service expansion.
Market Dynamics
Automated credit decisioning is absorbing alternative data streams at scale, forcing incumbent platforms to rearchitect risk engines around machine learning pipelines or cede market position to AI-native challengers.
Growth Catalysts
- Open banking mandates:PSD2 in the European Union and equivalent frameworks in Brazil and India are mandating standardized API access to customer transaction data. This infrastructure lowers data acquisition costs for lenders and accelerates real-time underwriting deployment.
- SME credit automation:Small and medium enterprises face persistent working capital gaps that traditional banks serve slowly. Digital lending platforms compress origination cycles from weeks to minutes, capturing this underserved demand segment.
- Cloud infrastructure elasticity:Amazon Web Services and Microsoft Azure consumption-based pricing allows fintech lenders to scale compute resources during peak application periods without fixed capital commitments.
Market Restraints
- Regulatory capital requirements:Peer-to-peer lending models face structurally higher funding costs than deposit-taking institutions, constraining origination volume relative to bank-affiliated platforms.
- Credit bureau dependency:Thin-file borrowers in emerging markets lack sufficient traditional credit history, limiting algorithmic accuracy until alternative data networks mature.
- Interest rate sensitivity:Central bank tightening cycles compress net interest margins for fixed-rate loan products, squeezing unit economics for originators without floating-rate exposure.
Strategic Opportunities
- Embedded finance integration:Point-of-sale lending APIs are penetrating e-commerce checkouts, travel booking platforms, and healthcare payment systems, expanding distribution beyond direct-to-consumer channels.
- EU AI Act compliance services:Risk classification obligations for automated credit decisioning create demand for explainability tools and audit infrastructure that vendors can productize.
- Cross-border data portability:Standardized open banking frameworks across multiple jurisdictions enable platform operators to replicate underwriting models in new geographies with reduced localization costs.
Industry Challenges
- Model risk management talent:Interpretable machine learning expertise remains scarce relative to demand, delaying deployment of compliant credit decisioning systems in regulated jurisdictions.
- Legacy core banking integration:Incumbent financial institutions operate on decades-old mainframe architectures that resist real-time API connectivity, extending implementation timelines and inflating professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Lending Platform Market |
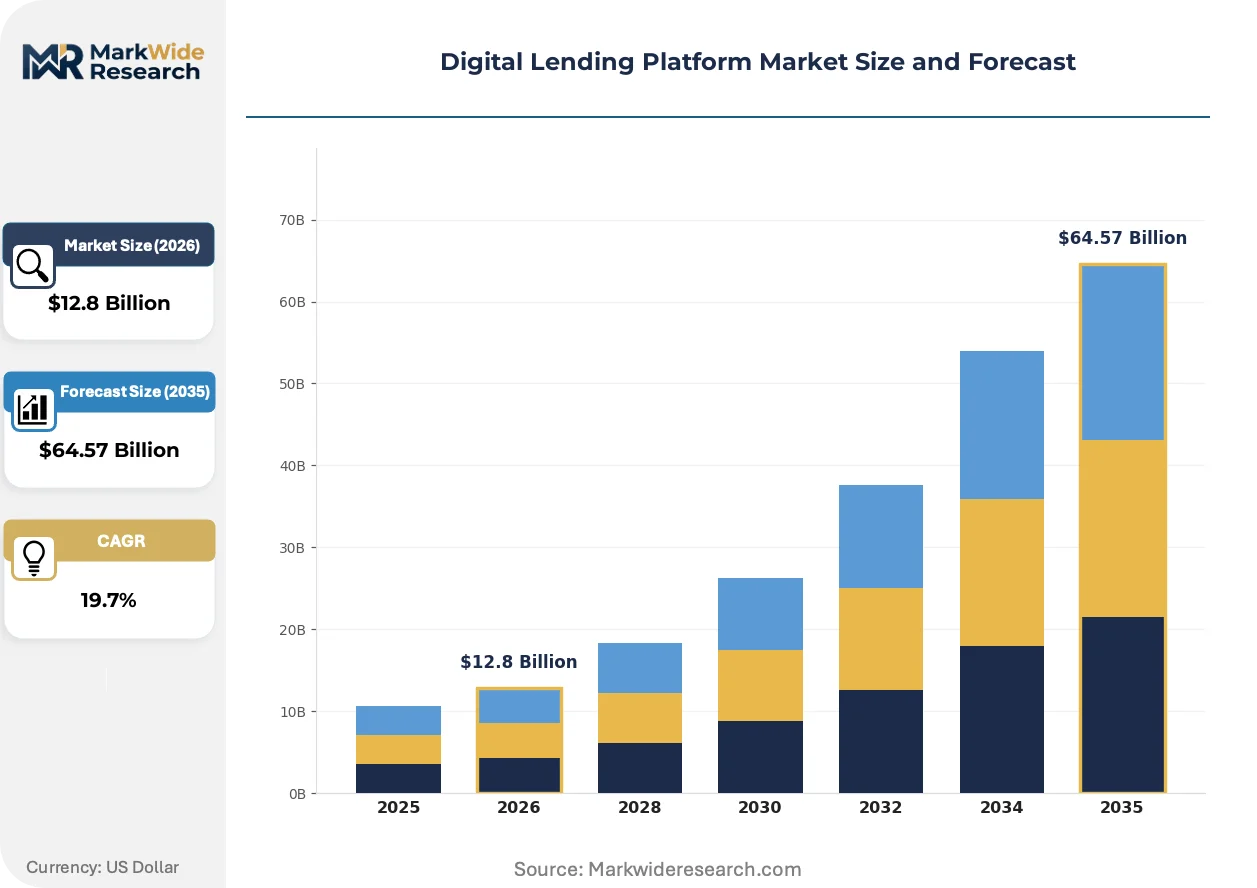
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $64.57 Billion |
| CAGR (2026 – 2036) | 19.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consumer Loans, Business Loans, Mortgage Lending, Peer-to-Peer Lending Deployment Mode: Cloud-Based, On-Premise, Hybrid, Mobile End User: Banks, Credit Unions, Fintech Companies, Alternative Lenders Technology: Blockchain, Artificial Intelligence, Big Data, Machine Learning |
| Companies Covered | Affirm Holdings, Inc., Klarna, Upstart Holdings Inc., Fiserv, Inc., FIS, Newgen Software, Nucleus Software, Finastra, LendingClub, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Lending Platform Market Strategic Shifts & Innovations
Real-time payment rails and generative AI are converging to compress loan disbursement windows from hours to seconds, redef borrower expectations across consumer and commercial segments.
Natural language processing is absorbing unstructured data sources including customer service transcripts, social media signals, and merchant reviews into credit risk models. Fintech lenders in India and Brazil are deploying these capabilities fastest, enabling approvals for thin-file applicants that traditional scores exclude. This capability expansion is compressing the competitive moat of incumbent credit bureaus.
The EU AI Act imposes mandatory risk classification and human oversight requirements on automated credit decisioning systems deployed across member states. Lenders must document algorithmic logic and maintain appeal mechanisms for adverse decisions, increasing compliance overhead. European platform vendors are responding by building explainability layers and audit trails directly into their core architectures.
Buyers are consolidating procurement around vertically integrated platform stacks that combine origination, servicing, and collections. Standalone point solutions face displacement as mid-market lenders prioritize unified data models and reduced vendor management overhead. This consolidation pattern is most visible in the United States, where regional banks are retiring fragmented legacy systems in favor of cloud-native alternatives.
Digital Lending Platform Market Segmentation
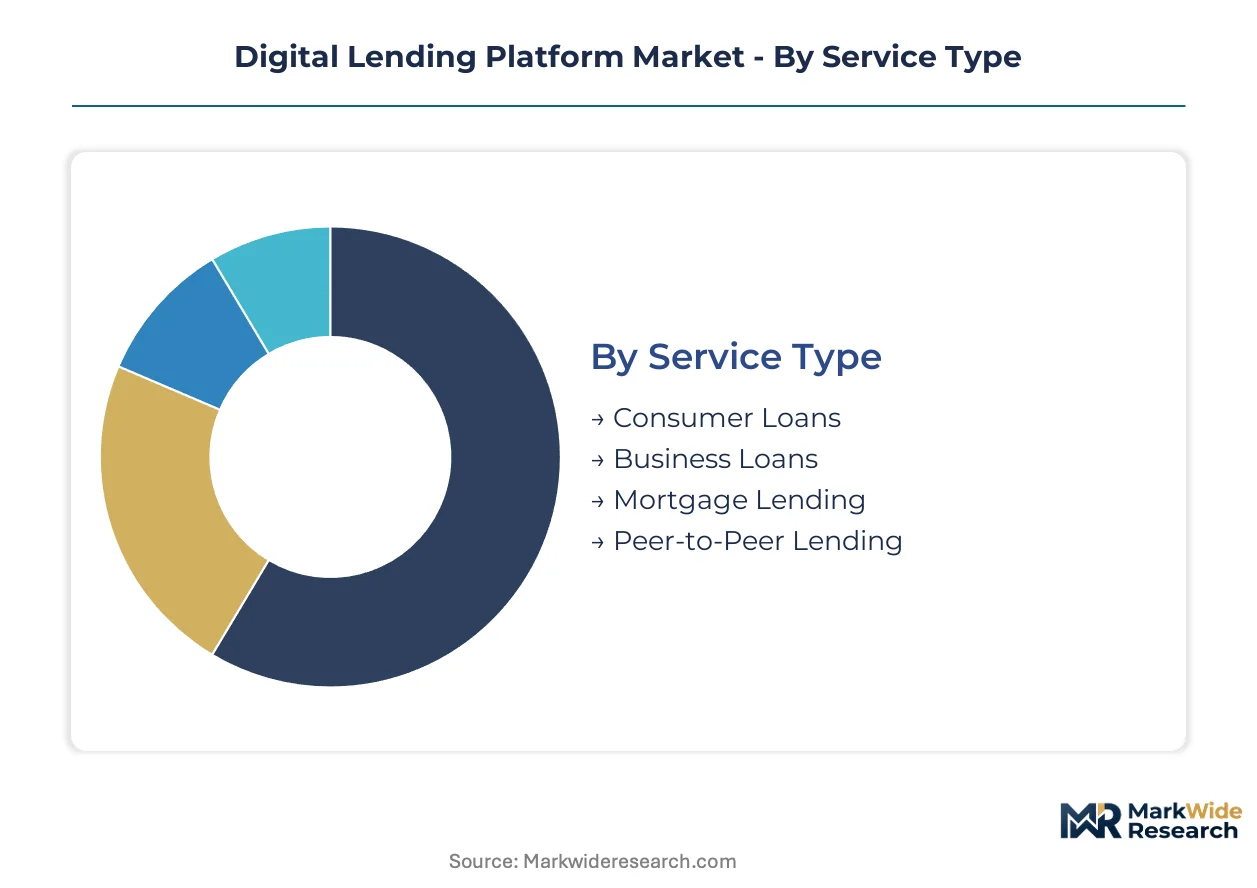
Segmentation in digital lending platforms reveals how technology choices and deployment architectures determine competitive positioning. Each category maps distinct value chains, from cloud infrastructure elasticity to AI-native underwriting capabilities, shaping where margin pools concentrate.
Service Type:
Consumer loans dominate transaction volume while business loans command premium pricing through complex risk assessment requirements.
- Consumer Loans:Point-of-sale financing and personal credit products automate approval decisions through alternative data integration. Demand concentrates in the United States and India as e-commerce penetration deepens and real-time payment rails mature.
- Business Loans:Working capital and term financing for SMEs requires cash-flow-based underwriting rather than collateral assessment. Indian fintech lenders deploy this capability fastest, capturing underserved credit gaps that traditional banks serve slowly.
- Mortgage Lending:Regulatory documentation requirements and appraisal workflows extend origination timelines.
- Peer-to-Peer Lending:Capital constraints from regulatory requirements limit scale relative to bank-affiliated platforms.
Today's leader: Consumer Loans. Tomorrow's challenger: Business Loans.
Deployment Mode:
Cloud architectures capture new implementations as lenders prioritize variable cost structures over fixed infrastructure commitments.
- Cloud-Based:Elastic compute resources scale during peak application periods without capital expenditure. AWS and Azure consumption models attract fintech lenders in Brazil and India seeking infrastructure flexibility.
- On-Premise:Data sovereignty requirements and legacy system dependencies sustain demand among large European banks with decades-old core architectures.
- Hybrid:Sensitive underwriting data remains on-premise while customer-facing applications deploy to cloud.
- Mobile:Smartphone-first origination targets underbanked populations in emerging markets.
Cloud-Based deployments hold the dominant share. Mobile represents the steepest expansion trajectory as smartphone penetration climbs.
End User:
Fintech companies drive fastest adoption while banks bring largest existing loan portfolios requiring platform modernization.
- Banks:Legacy core banking integration challenges extend implementation timelines. Regional banks in the United States consolidate fragmented systems into unified cloud-native stacks.
- Fintech Companies:Greenfield architectures embed machine learning pipelines from inception. These lenders in India and Brazil deploy alternative data capabilities fastest, approving thin-file applicants traditional scores exclude.
- Credit Unions:Member-focused lending models prioritize relationship data over transactional algorithms.
- Alternative Lenders:Specialized risk models target niche credit segments mainstream institutions avoid.
Banks provide the revenue base. Fintech Companies are gaining share fastest through AI-native underwriting.
Technology:
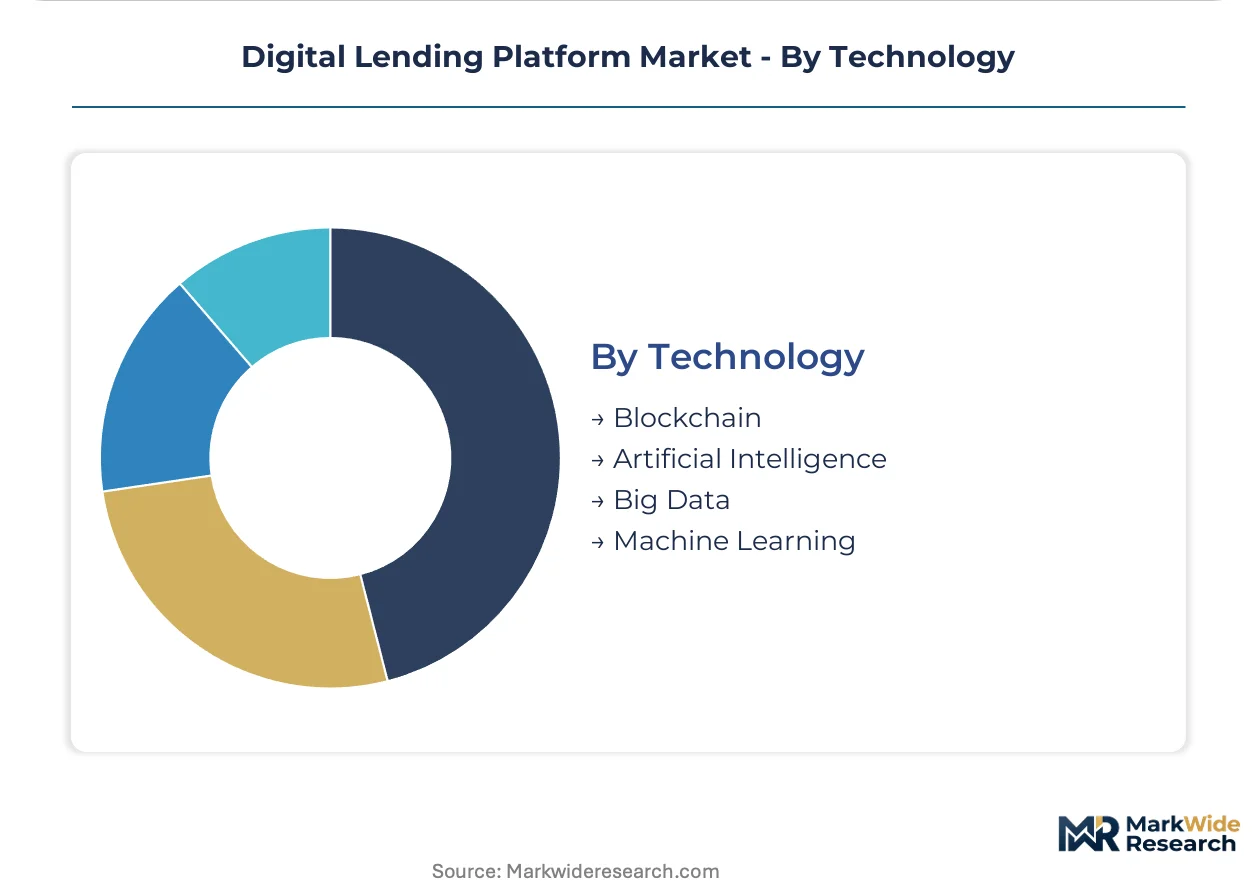
Artificial intelligence absorbs disproportionate R&D investment as alternative data displaces traditional bureau scores.
- Artificial Intelligence:Neural networks process unstructured data including customer service transcripts and merchant reviews into credit signals. European lenders face EU AI Act compliance requirements for explainability and human oversight.
- Machine Learning:Gradient-boosted models extend credit access beyond FICO parameters through cash-flow analysis. Upstart Holdings and similar platforms sustain competitive edge through proprietary feature engineering.
- Big Data:Transaction-level analytics from open banking APIs enable real-time income verification.
- Blockchain:Smart contract automation for loan servicing remains experimental with limited production deployment.
Artificial Intelligence leads current investment. Machine Learning is climbing the fastest as model interpretability tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine learning engineers and fintech product managers cluster in financial hubs across the United States, India, and Brazil, anchoring regional platform development velocity. Talent density in these markets accelerates deployment of alternative data underwriting and real-time decision engines. Regulatory divergence across these jurisdictions shapes platform architecture choices.
United States
Point-of-sale financing and embedded lending APIs drive platform adoption as e-commerce penetration deepens. The Consumer Financial Protection Bureau enforces fair lending standards and adverse action notice requirements that shape automated decisioning workflows. Silicon Valley and New York City host dense concentrations of fintech engineering talent developing AI-native underwriting stacks.
India
SME working capital gaps and smartphone-first banking penetration accelerate digital lending platform deployment. The Reserve Bank of India mandates digital lending guidelines restricting unregulated third-party involvement in credit flows. Bengaluru and Mumbai anchor fintech development clusters where lenders deploy cash-flow-based underwriting for thin-file applicants.
Brazil
Open banking frameworks and real-time payment infrastructure expand addressable markets for automated credit decisioning. The central bank's open banking mandates standardize API access to customer transaction data. São Paulo concentrates fintech engineering talent developing alternative scoring models for underbanked populations.
Germany
Embedded finance integration into B2B procurement platforms drives demand for automated SME lending workflows. The EU AI Act imposes risk classification and explainability requirements on automated credit decisioning systems. Berlin and Frankfurt host regulatory technology clusters developing compliance infrastructure for algorithmic lending.
United Kingdom
Buy-now-pay-later penetration in retail networks and open banking maturity sustain platform growth. The Financial Conduct Authority supervises consumer credit conduct and affordability assessments. London anchors European fintech talent density, with clusters in Shoreditch and Canary Wharf developing cross-border underwriting capabilities.
Digital Lending Platform Market Key Industry Players
Top-tier vendors anchor AI-native underwriting stacks, while commodity loan origination software occupies lower-margin tiers. The market exhibits bifurcation between premium risk-engine providers and standardized workflow platforms. Three archetypes dominate: point-of-sale financing specialists, machine learning credit scorers, and legacy core banking modernizers. Strategic moves concentrate on embedded finance partnerships and cloud infrastructure migration.
Within the AI-native underwriting tier, Upstart Holdings Inc. exemplifies machine learning-driven credit scoring that extends beyond traditional bureau parameters. Affirm Holdings, Inc. occupies a position in point-of-sale consumer financing workflows. Klarna anchors buy-now-pay-later distribution across European retail networks. These three represent distinct competitive vectors: alternative data scoring, merchant-embedded lending, and retail payment flexibility.
| Leading Market Players |
|---|
| Affirm Holdings, Inc. |
| Klarna |
| Upstart Holdings Inc. |
| Fiserv, Inc. |
| FIS |
| Newgen Software |
| Nucleus Software |
| Finastra |
| LendingClub |
| Others |
Cost & Logistics Intelligence
AI-native underwriting stacks and commodity loan origination software diverge sharply in both pricing power and supplier configuration. Premium vendors command subscription tiers anchored to decision-engine performance while commodity players compete on per-seat SaaS fees, with cloud infrastructure costs and compliance tooling investments determining margin structures across both tiers.
Pricing Analysis
Bundled platform stacks incorporating origination, servicing, and collections command annual recurring revenue premiums over unbundled point solutions. Three-tier pricing structure across enterprise, mid-market, and entry-level deployments reflects customization depth and API volume commitments. Pricing pressure stems from hyperscaler cloud cost pass-throughs and open-source alternative data pipelines eroding proprietary data moats. Mid-market regional banks exhibit highest price sensitivity as they consolidate fragmented legacy systems, while multinational fintechs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing requirements for cloud infrastructure mandate qualification across Amazon Web Services and Microsoft Azure for resilience against regional outages. Core platform development concentrates in the United States, India, and Brazil where machine learning engineering talent clusters densely. The supply chain rests on specialized inputs including GPU compute instances, identity verification APIs, and open banking data aggregators. Single-source vulnerability sits with proprietary risk model providers whose algorithmic IP resists substitution. Distribution runs through direct enterprise sales teams and systems integrator partnerships serving bank IT modernization programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate where AI-native platforms displace legacy scoring costs and embedded finance partnerships unlock premium pricing tiers.
For Market Incumbents: Anchor defensive positioning through backward integration into alternative data networks and captive cloud infrastructure capacity. Consolidate fragmented legacy core banking relationships before AI-native challengers capture regional bank procurement cycles. Prioritize EU AI Act compliance tooling investments to monetize audit infrastructure as a standalone revenue stream. For New Entrants and Emerging Players: Launch via API-first distribution models penetrating e-commerce checkout flows and healthcare payment systems where incumbent coverage remains thin. Target SME working capital gaps in Brazil and India where cash-flow-based underwriting penetration lags consumer lending. Pursue white-label partnerships with merchant acquirers seeking embedded lending capabilities without platform build-out. For Investors and Strategic Acquirers: Consolidation pressure builds where standalone point solution vendors face displacement by vertically integrated platform stacks. Long-term viability favors acquirers of explainable AI tooling and open banking data aggregators serving regulated European deployments. Monitor central bank digital currency pilots as inflection indicators for real-time disbursement infrastructure demand.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance API Integration | Point-of-sale lending penetration into e-commerce checkouts expands distribution beyond direct channels. |
| EU AI Act Compliance Layer Development | Explainability tooling and audit trails address mandatory risk classification obligations across member states. |
| Alternative Data Network Acquisition | Cash-flow analytics and merchant review signals displace traditional bureau scores for thin-file applicants. |
| Cloud-Native Core Banking Migration | Elastic infrastructure replaces fixed on-premise capacity for mid-market lenders consolidating legacy systems. |
| Cross-Border Open Banking Expansion | Standardized API frameworks enable underwriting model replication across Brazil, India, and European jurisdictions. |
Research Approach
Coverage spans the United States, India, Brazil, Germany, and the United Kingdom, with primary inputs from each market informing regional divergence analysis. The approach combines structured interviews with chief technology officers, digital lending product heads, regulatory compliance officers, and cloud infrastructure procurement leads alongside secondary validation through SEC filings, central bank guideline publications, and open banking framework documentation. Bottom-up platform deployment tallies triangulate against top-down banking IT spending estimates to anchor market sizing.
Rate-of-change decomposition separates volume expansion from pricing evolution across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end-user institution category, and underlying technology stack. CAGRs derive from logistic adoption curves fitted to historical platform procurement data and forward-looking regulatory implementation timelines. Industry-specific inputs incorporate open banking API maturity indices and SME credit gap estimates from national banking associations.
Several conditions sit outside the modeled scope, including sovereign debt crises triggering systemic credit freezes, major cloud provider outages disrupting real-time decisioning infrastructure, and abrupt regulatory reversals on alternative data permissibility. Forecasts reflect assumptions around gradual interest rate normalization and sustained open banking mandate enforcement. Deviation in central bank tightening intensity or AI liability litigation volume would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
India Student Loan Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
Microfinance Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
US Auto Loan Market
Loans and Leasing
Invoice Factoring Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Micro Lending Market
Loans and Leasing
China Car Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
Global Healthcare Equipment Leasing Market
Loans and Leasing
Used Car Financing Market
Loans and Leasing
Consumer Credit Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Loan Origination Software Market