
 Luxury Cigarette Market | 2026-2036
Luxury Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
Luxury Cigarette Market Analytics
Market Context
Premium blend specifications and ultra-premium leaf grading is collapsing the distinction between conventional premium and true luxury tiers, forcing incumbents to elevate quality benchmarks. Philip Morris International leverages its heated tobacco R&D infrastructure to sustain credibility in reduced-risk luxury positioning. British American Tobacco anchors its luxury portfolio through controlled distribution in duty-free channels. Davidoff competes on Swiss heritage manufacturing and limited-edition releases that command collector premiums.
Technical Definition and Segments
Luxury cigarettes denote tobacco products manufactured with select-grade flue-cured and oriental leaf blends, typically featuring sub-6mg tar delivery, natural cork tipping, and hand-finished packaging designed for ceremonial or social consumption rather than utilitarian nicotine delivery. The flavor profile dimension shows classic unflavored variants retaining dominant volume share while menthol faces regulatory compression across multiple jurisdictions, and vanilla and cherry occupy niche gifting occasions with concentrated margin pools. Packaging type segmentation reveals box formats commanding highest per-unit economics through rigid construction and embossing, while tin presentations serve limited releases and collector demographics with substantial price premiums over standard carton configurations.
Regulatory Outlook
The FDA exercises premarket authority over modified risk claims and constituent disclosure requirements that constrain how luxury brands communicate product differentiation. The EU Tobacco Products Directive mandates standardized packaging elements and cross-border tracking that limit brand expression in member states. Health Canada and WHO Framework Convention protocols on plain packaging constrain promotional channels in additional markets. Stakeholders must monitor evolving flavor prohibitions and track-and-trace mandates to determine whether heritage positioning or innovation narratives offer more durable competitive shelter.
Market Dynamics
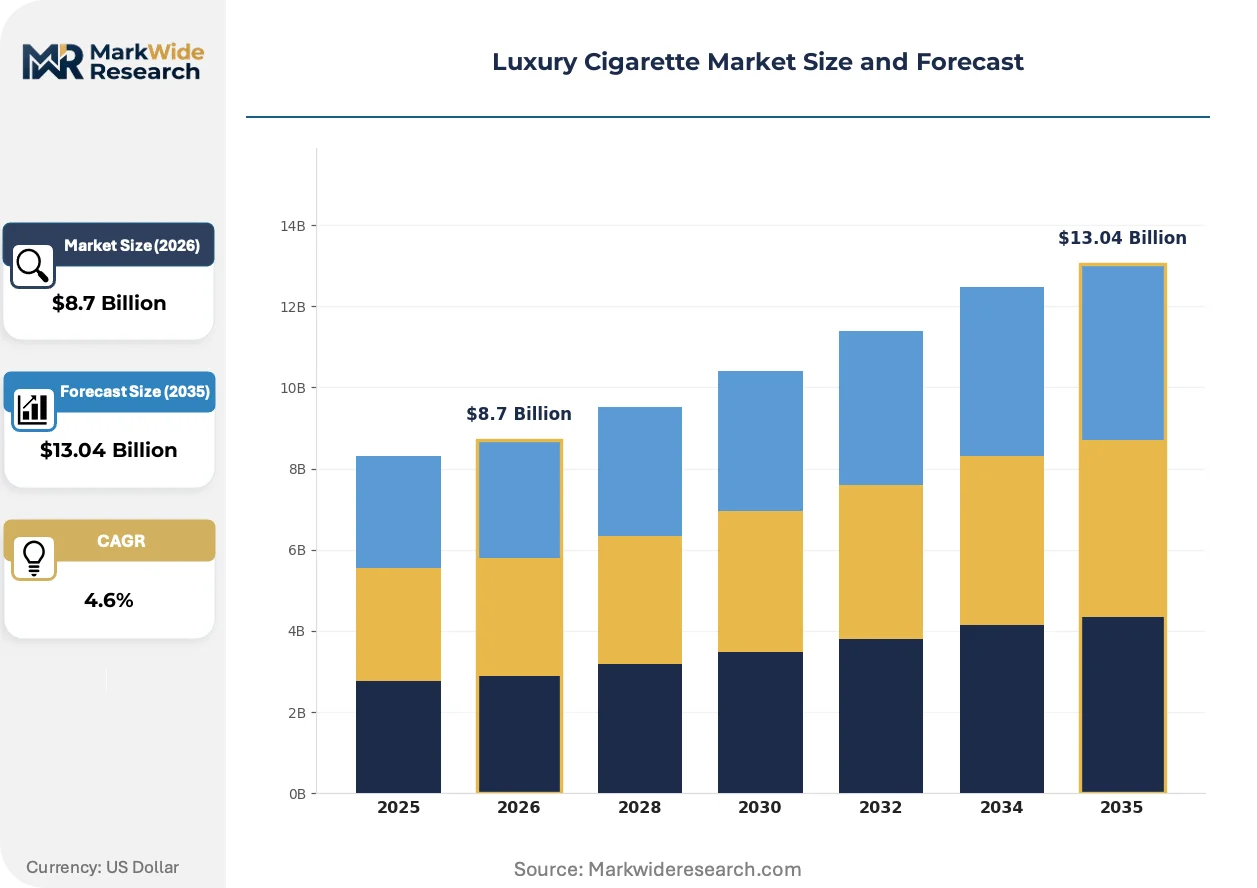
The EU Tobacco Products Directive and comparable flavor restrictions across multiple jurisdictions are compressing traditional product architectures, forcing manufacturers to reformulate blends and reposition heritage narratives as primary differentiation vectors.
Growth Catalysts
- Heated tobacco infrastructure:Philip Morris International leverages its reduced-risk R&D platforms to sustain credibility in luxury positioning where combustion-based alternatives face mounting regulatory pressure.
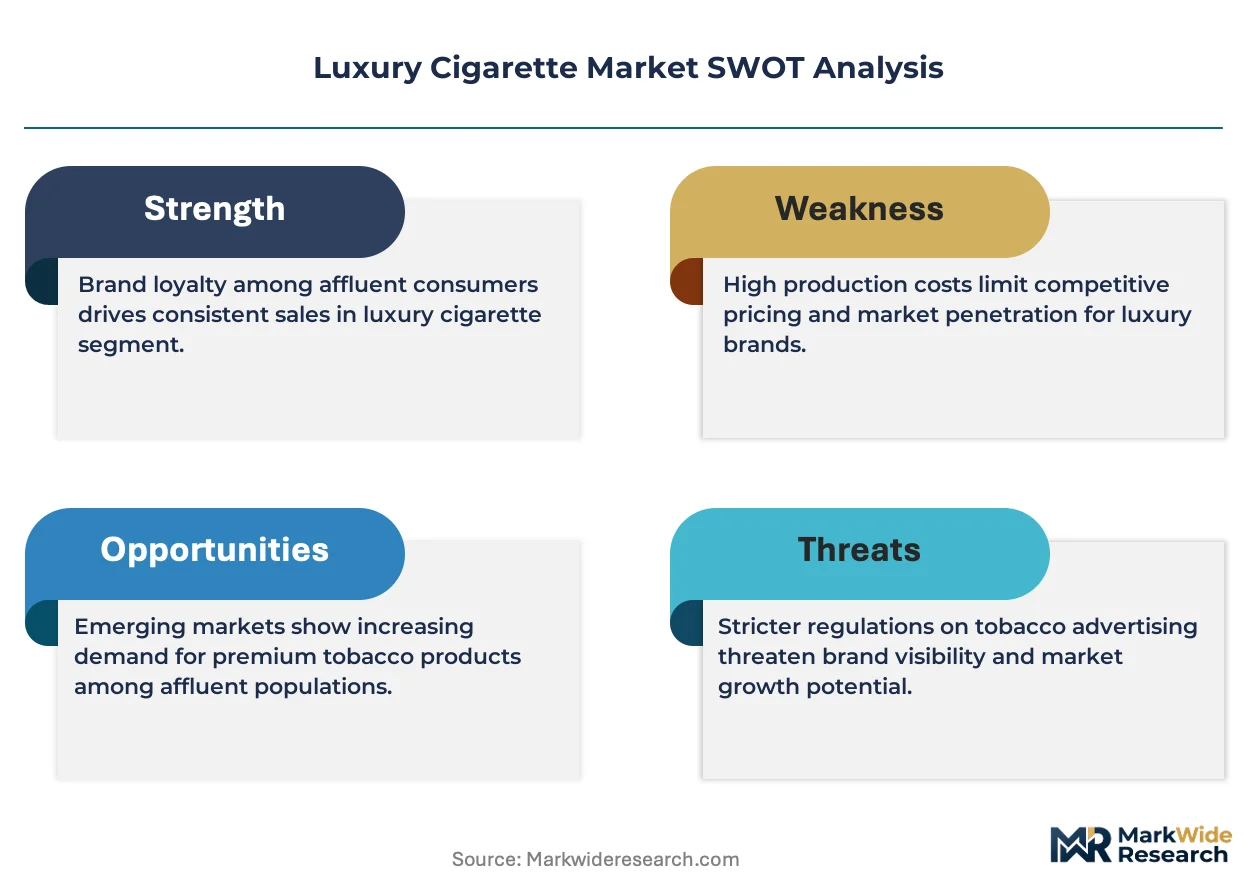
- Flavor prohibition carve-outs:Natural tobacco and unflavored variants retain regulatory tolerance in jurisdictions where menthol and characterizing flavors face outright bans, preserving margin-rich ceremonial consumption occasions.
- Duty-free channel concentration:British American Tobacco anchors luxury portfolio distribution through controlled airport and travel retail networks that insulate pricing from domestic tax escalations.
Market Restraints
- Oriental leaf supply concentration:Premium blend specifications depend on Turkish and Greek oriental tobacco varieties where climatic volatility and crop disease pressure create input cost instability.
- Plain packaging mandates:Health Canada and WHO Framework Convention protocols eliminate brand expression through visual identity, constraining heritage-based luxury signaling in affected markets.
- Nicotine replacement convergence:Pharmaceutical-grade nicotine pouches and vaping systems capture ceremonial consumption occasions previously reserved for premium combustible products.
Strategic Opportunities
- Collector edition economics:Limited-release tin presentations and numbered series command substantial price premiums over standard carton configurations among high-net-worth demographic segments.
- Swiss manufacturing heritage:Davidoff competes on Geneva-origin production credibility where neutral political positioning and precision craft associations support ultra-premium pricing tiers.
- State-affiliated distribution in China:Rising disposable incomes and controlled retail networks create protected channels for premium tobacco consumption insulated from competitive price erosion.
Industry Challenges
- Track-and-trace compliance timelines:EU Tobacco Products Directive mandates for serialized packaging and cross-border monitoring systems impose capital-intensive infrastructure upgrades on heritage manufacturers with limited digital capabilities.
- Modified risk claim substantiation:FDA premarket authority over reduced-risk communications requires extensive clinical documentation that constrains how luxury brands articulate product differentiation without triggering enforcement action.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Luxury Cigarette Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Brand: Davidoff, Dunhill, Montecristo, Cohiba Packaging Type: Box, Tin, Carton, Soft Pack Flavor Profile: Classic, Menthol, Vanilla, Cherry Target Demographic: Affluent Consumers, Young Professionals, Collectors, Occasionally Smokers |
| Companies Covered | Japan Tobacco, Reynolds American, Philip Morris International, Swedish Match, China National Tobacco Corporation, British American Tobacco, Imperial Brands, Davidoff, Altria Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Luxury Cigarette Market Evolving Landscape
Product architecture is pivoting toward reduced-risk formats and heritage narrative reinforcement as regulatory pressure on combustion-based consumption intensifies across major jurisdictions.
Heated tobacco platforms are displacing conventional luxury cigarette architectures in premium consumer segments. High-net-worth individuals in emerging economies adopt these systems for ceremonial consumption where social visibility matters. This technology is displacing traditional flue-cured and oriental blend formats in airport duty-free channels and private club settings where innovation signaling carries social currency.
REACH and RoHS compliance frameworks in Europe are tightening constituent disclosure requirements for tobacco additives and packaging materials. Manufacturers must reformulate natural cork tipping and embossing substrates to eliminate restricted substances. Swiss and German production facilities face the most intensive retooling cycles as they supply EU member states with the strictest enforcement protocols.
Ceremonial gifting patterns are rotating toward limited-edition collector formats with documented provenance. High-net-worth buyers in China and the Middle East now prioritize numbered releases and artisan craft narratives over standard ultra-premium carton configurations. This behavioral shift is most visible in airport travel retail and private banking client entertainment channels where product uniqueness signals relationship investment depth.
Luxury Cigarette Market Segmentation
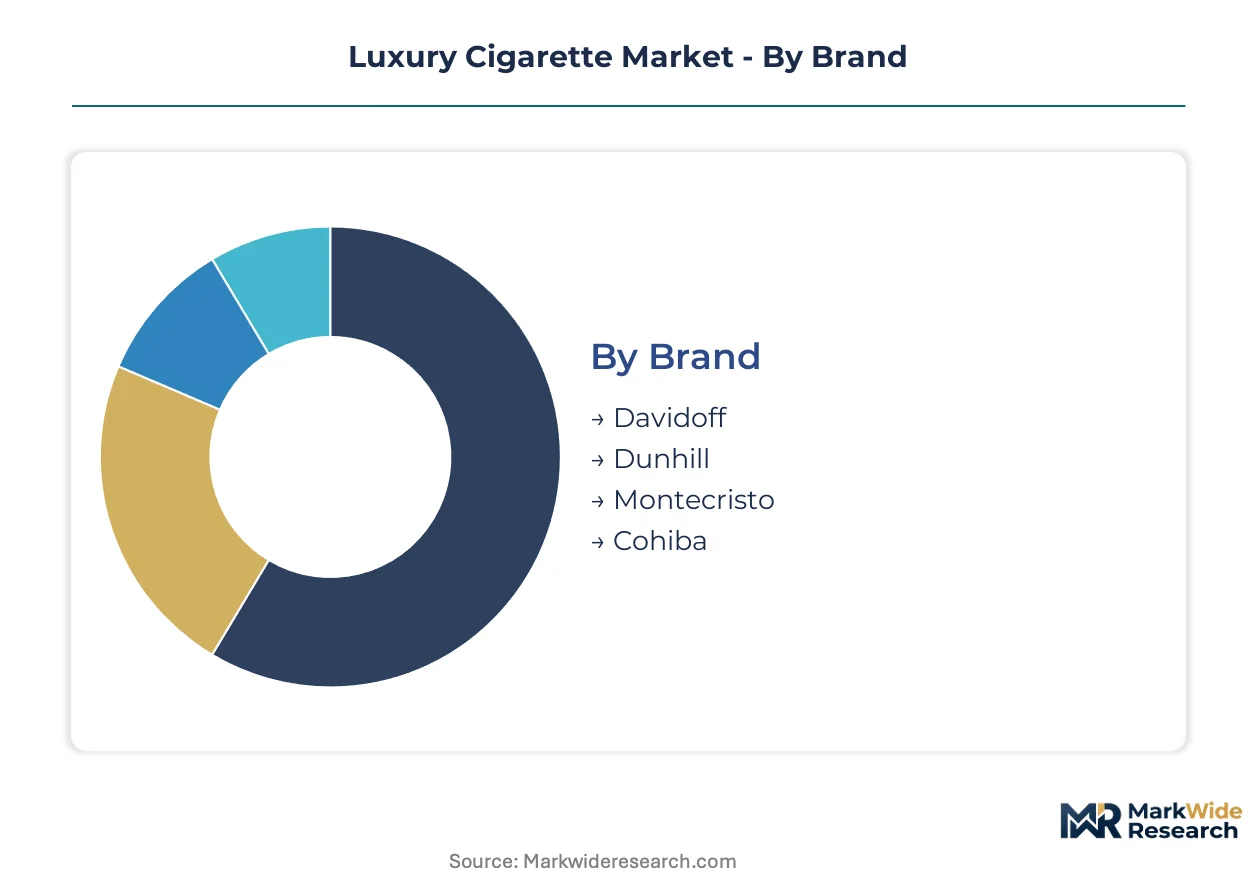
Segmentation in luxury cigarettes determines how manufacturers allocate limited production capacity across diverging regulatory tolerances and ceremonial consumption patterns. Each dimension carries distinct margin profiles and exposure to substitute threats from heated tobacco and pharmaceutical nicotine systems.
Brand:
Swiss heritage manufacturers face intensifying substitution pressure as reduced-risk platforms capture ceremonial occasions previously reserved for combustion-based prestige brands.
- Davidoff:Geneva-origin production facilities emphasize precision craft associations and neutral political positioning that commands ultra-premium pricing tiers in Middle Eastern and Asian duty-free channels. Collector demographics in China and the UAE drive demand for numbered releases where provenance documentation supports relationship signaling in private banking entertainment contexts.
- Dunhill:British heritage positioning leverages London luxury retail associations and historical motorsport sponsorship equity to sustain credibility among affluent European consumers. The brand concentrates distribution in airport travel retail networks where British American Tobacco controls shelf placement and insulates pricing from domestic tax escalations.
- Montecristo:Cuban cigar heritage transfers to cigarette extensions through Habanos SA licensing arrangements that exploit Caribbean tobacco mythology.
- Cohiba:Revolutionary-era origin narrative and limited production mythology command collector premiums in Latin American and Spanish markets.
Davidoff anchors the volume base among heritage Swiss manufacturers while Dunhill gains share at the steepest rate through duty-free channel expansion.
Packaging Type:
Cost tier stratification in packaging materials creates diverging margin pools where rigid construction investments separate ceremonial gifting from utilitarian consumption.
- Box:Rigid cardboard construction with embossed finishing and foil stamping commands highest per-unit economics through tactile quality signals that support premium shelf positioning. China and the Middle East concentrate demand where box formats dominate business entertainment and festival gifting occasions.
- Tin:Metal presentations with hinged lids and numbered series certificates serve limited releases and collector demographics with substantial price premiums over standard configurations. Swiss and German production facilities face intensive REACH and RoHS retooling cycles to eliminate restricted substances from embossing substrates.
- Carton:Multi-pack configurations balance volume efficiency with moderate premium signaling for habitual affluent consumers.
- Soft Pack:Flexible paper wrapping occupies utilitarian positioning with minimal ceremonial value and compressed margins.
Box formats anchor the volume base among premium packaging investments while tin presentations expand most quickly through collector edition economics.
Flavor Profile:
Regulatory geography determines which flavor architectures retain commercial viability as FDA and EU Tobacco Products Directive mandates compress menthol and characterizing flavor availability.
- Classic:Unflavored tobacco blends featuring sub-6mg tar delivery and natural cork tipping retain dominant volume share through regulatory tolerance in jurisdictions where characterizing flavors face outright bans. China, Japan, and Middle Eastern markets concentrate demand for ceremonial consumption where pure tobacco taste signals authenticity.
- Menthol:Cooling additive formulations face regulatory compression across European Union member states and Canadian provinces following WHO Framework Convention protocols on flavor restrictions. Remaining commercial presence concentrates in Asian markets where Health Canada and EU prohibitions do not apply.
- Vanilla:Sweet aromatic profiles occupy niche gifting occasions with concentrated margin pools in Middle Eastern duty-free channels.
- Cherry:Fruit-infused variants serve occasional ceremonial consumption with limited regulatory tolerance outside specific Asian and Latin American jurisdictions.
Classic unflavored variants anchor the volume base through regulatory shelter while vanilla profiles climb the fastest among remaining permitted flavor architectures.
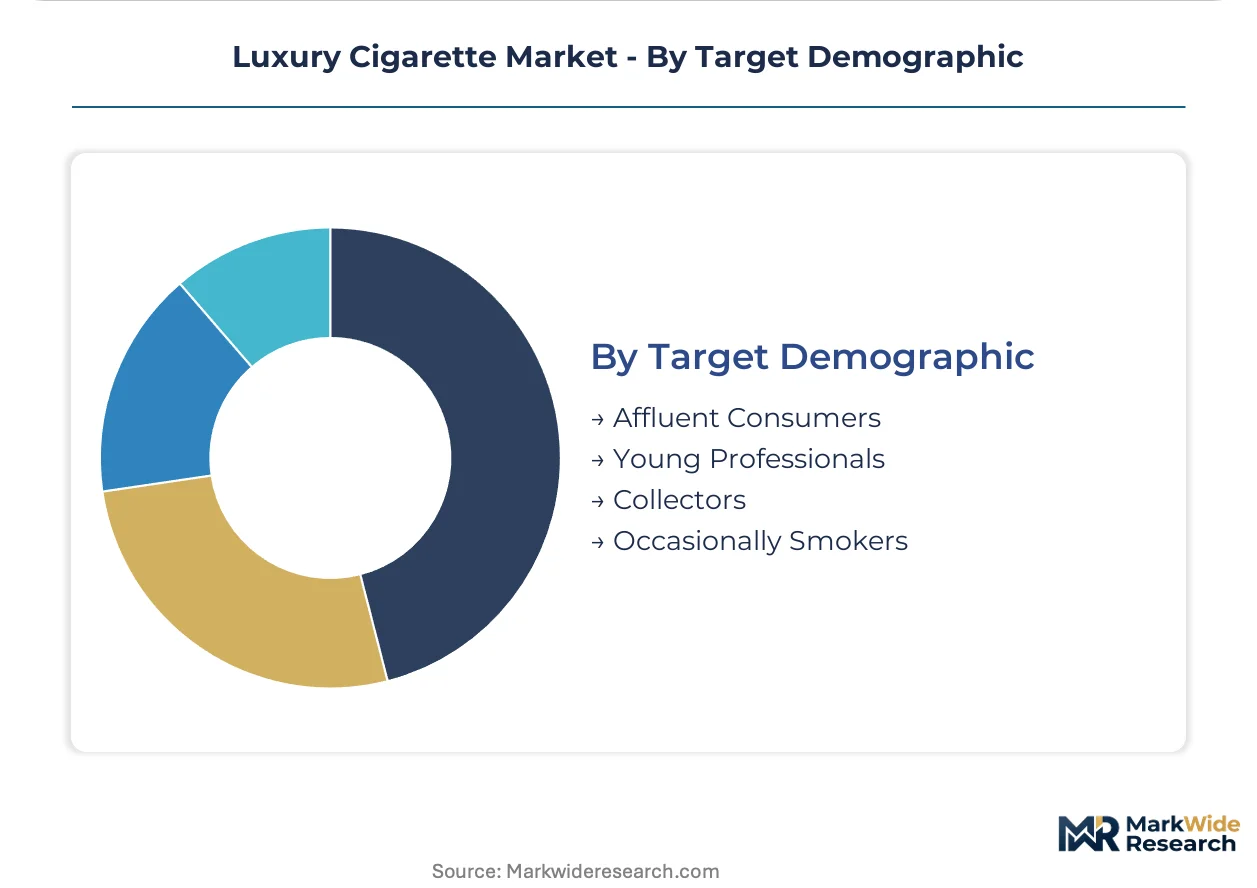
Target Demographic:
Customer type stratification reveals diverging susceptibility to nicotine replacement convergence as pharmaceutical-grade pouches and vaping systems capture younger ceremonial consumption occasions.
- Affluent Consumers:High-net-worth individuals with established brand loyalties and price inelasticity sustain core revenue pools through habitual premium consumption in private club and residential settings. China concentrates this demographic where state-affiliated distribution networks and rising disposable incomes support protected premium tobacco channels.
- Collectors:Numbered-release and limited-edition buyers prioritize documented provenance and artisan craft narratives over standard ultra-premium configurations. This segment shows strongest growth in airport travel retail and private banking client entertainment channels where product uniqueness signals relationship investment depth.
- Young Professionals:Emerging affluent consumers face highest substitution risk from heated tobacco platforms that offer innovation signaling with reduced social stigma.
- Occasionally Smokers:Ceremonial-only consumption patterns concentrate in festival and business entertainment contexts with irregular purchase frequency.
Affluent consumers anchor the volume base through habitual purchase patterns while collectors expand most quickly through limited-release economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Turkish and Greek oriental leaf cultivation anchors supply-side concentration for premium blend specifications. State-affiliated distribution networks in China and controlled retail channels in the Middle East concentrate demand. Regulatory fragmentation across the EU, North America, and Asia-Pacific forces manufacturers to maintain parallel product architectures.
China
Rising disposable incomes among high-net-worth individuals in Shanghai and Beijing sustain protected premium tobacco channels. State-affiliated distribution networks insulate pricing from competitive erosion. The China National Tobacco Corporation controls retail networks where ceremonial consumption concentrates in Guangdong and Zhejiang provinces.
United States
Affluent consumers in New York, Los Angeles, and Miami sustain habitual premium consumption in private club settings. FDA premarket authority over modified risk claims constrains how luxury brands articulate product differentiation. Duty-free channels at Hartsfield-Jackson Atlanta and Los Angeles International anchor travel retail concentration for heritage brands.
Germany
Swiss and German production facilities face intensive REACH and RoHS retooling cycles to eliminate restricted substances from embossing substrates. The EU Tobacco Products Directive mandates standardized packaging elements that limit brand expression. Manufacturing clusters in Hamburg and Munich supply EU member states with strictest enforcement protocols.
United Arab Emirates
Dubai International Airport and Abu Dhabi travel retail networks concentrate collector demographics seeking numbered releases. MOHAP protocols govern product registration while permitting greater brand expression than EU jurisdictions. High-net-worth buyers from Saudi Arabia and Kuwait prioritize documented provenance in private banking entertainment contexts.
Japan
Heated tobacco platforms capture ceremonial consumption occasions previously reserved for combustion-based prestige brands in Tokyo and Osaka. METI oversight of reduced-risk product categories creates regulatory clarity absent in Western jurisdictions. Innovation signaling carries social currency in airport duty-free channels at Narita and Haneda.
Luxury Cigarette Market Competitive Landscape
Concentration sits with diversified tobacco conglomerates that leverage heated tobacco R&D infrastructure and duty-free channel control. Three to five multinational players dominate volume while Swiss heritage specialists occupy ultra-premium price tiers. Strategic moves center on portfolio diversification into reduced-risk formats and limited-edition collector releases that command substantial price premiums.
Among the diversified conglomerates, Philip Morris International and British American Tobacco exemplify scale-driven archetypes that anchor market structure through controlled distribution networks. Davidoff occupies a distinct position within the Swiss heritage tier where Geneva-origin production credibility supports ultra-premium pricing. Japan Tobacco represents the Asia-Pacific anchor with state-affiliated channel access in its domestic market.
| Leading Market Players |
|---|
| Japan Tobacco |
| Reynolds American |
| Philip Morris International |
| Swedish Match |
| China National Tobacco Corporation |
| British American Tobacco |
| Imperial Brands |
| Davidoff |
| Altria Group |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for Turkish and Greek oriental leaf varieties concentrate pricing power with heritage manufacturers who control aged-stock reserves. This lead-time structure rewards backward integration into cultivation networks while penalizing spot-market dependent competitors facing climatic volatility.
Pricing Analysis
The EU Tobacco Products Directive dictates the pricing tier structure through standardized packaging mandates that eliminate visual differentiation. Three-tier pricing stratifies across ultra-premium collector editions, standard luxury box formats, and compressed-margin soft-pack configurations. Price differentiation hinges on provenance documentation and Swiss manufacturing heritage. Cost compression in menthol variants is intensifying because flavor prohibitions across European and Canadian jurisdictions collapse addressable volume.
Supply Chain Analysis
Ninety-day inventory cycles for oriental leaf expose manufacturers to climatic volatility in Turkish and Greek growing regions. Premium blend specifications draw from flue-cured Virginia stocks, natural cork tipping suppliers, and embossed packaging substrate providers. Single-source vulnerability concentrates in oriental tobacco varieties where crop disease pressure creates input cost instability. Distribution runs through state-affiliated networks in China and controlled duty-free channels at Dubai International Airport and Frankfurt.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward collector demographics and high-net-worth individuals in emerging economies who consolidate ceremonial consumption occasions around documented provenance. This consolidation fragments price inelastic habitual consumption patterns.
For Market Incumbents: Secure controlled distribution in airport travel retail networks to insulate pricing from domestic tax escalations. Invest in heated tobacco R&D infrastructure to capture ceremonial occasions where Philip Morris International already sustains credibility. Diversify into limited-edition tin presentations with numbered series certificates to command collector premiums. For New Entrants and Emerging Players: Anchor in vanilla flavor profiles and Middle Eastern duty-free channels where regulatory tolerance permits niche gifting occasions with concentrated margin pools. Target collector demographics in China and the UAE seeking artisan craft narratives over standard configurations. Deploy private banking client entertainment partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because flavor prohibition carve-outs and plain packaging mandates create divergent competitive shelters across jurisdictions. Acquisition targets should demonstrate state-affiliated channel access or Swiss manufacturing heritage credibility. Watch heated tobacco adoption rates in Tokyo and Osaka as the inflection indicator for combustion-based prestige brand displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Narrative Reinforcement | Geneva-origin production credibility commands ultra-premium pricing tiers where EU packaging mandates limit visual differentiation. |
| Heated Tobacco Platform Expansion | Reduced-risk R&D infrastructure captures ceremonial consumption occasions previously reserved for combustion-based prestige brands. |
| Limited-Edition Collector Releases | Numbered tin presentations with provenance documentation support relationship signaling in private banking entertainment contexts. |
| Duty-Free Channel Concentration | Controlled airport retail networks at Dubai International and Frankfurt insulate pricing from domestic tax escalations. |
| REACH and RoHS Compliance Retooling | Swiss and German facilities eliminate restricted substances from embossing substrates to maintain EU market access. |
Research Methodology
Operator-level perspectives from brand managers at heritage manufacturers, category buyers at airport travel retail networks, and procurement leads at China National Tobacco Corporation anchored the qualitative base. Secondary validation drew from FDA premarket tobacco product application filings, EU Tobacco Products Directive implementation reports, and customs records tracking oriental leaf trade flows. Bottom-up volume estimates triangulated against top-down macroeconomic consumption patterns.
Sensitivity analysis tested forecast robustness across alternative regulatory scenarios and heated tobacco adoption trajectories over the projection horizon. The analytical framework modeled segmentation dimensions including packaging type, flavor profile, target demographic, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for documented policy shifts. Industry-specific inputs incorporated REACH compliance timelines and state-affiliated distribution network expansion rates.
Decision-makers should treat outputs as directional under assumptions of continued flavor prohibition tolerance for natural tobacco variants and stable state-affiliated channel structures in China; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Japan Heated Tobacco Products Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Homemade Cigars Market