
 E-Cigarette and Vape Market | 2026-2036
E-Cigarette and Vape Market Size, Share, and Industry Trends Forecast 2026-2036
E-Cigarette and Vape Market Intelligence
Capital-intensity divergence between closed-system and open-system manufacturers is redrawing competitive boundaries in the E-Cigarette and Vape industry. Philip Morris International leverages its heated tobacco infrastructure to sustain premium positioning across regulated markets. British American Tobacco anchors its portfolio through pod-system investments that dominate convenience retail channels. Altria Group controls distribution depth via specialty store partnerships and direct-to-consumer platforms.
E-cigarettes and vape products comprise battery-powered devices that aerosolize nicotine-containing or nicotine-free e-liquids through resistive heating elements, typically operating at 3.7 to 4.2 volts with coil resistances between 0.5 and 2.5 ohms for commercial applications. Their primary purpose is to deliver inhaled aerosol as an alternative to combustible tobacco consumption. Pod systems lead product type segments due to portability and prefilled cartridge convenience, while e-liquids generate recurring revenue streams that sustain margin pools. Distribution through online retail channels expands fastest as age-verification technologies mature, though specialty stores retain higher per-unit transaction values.
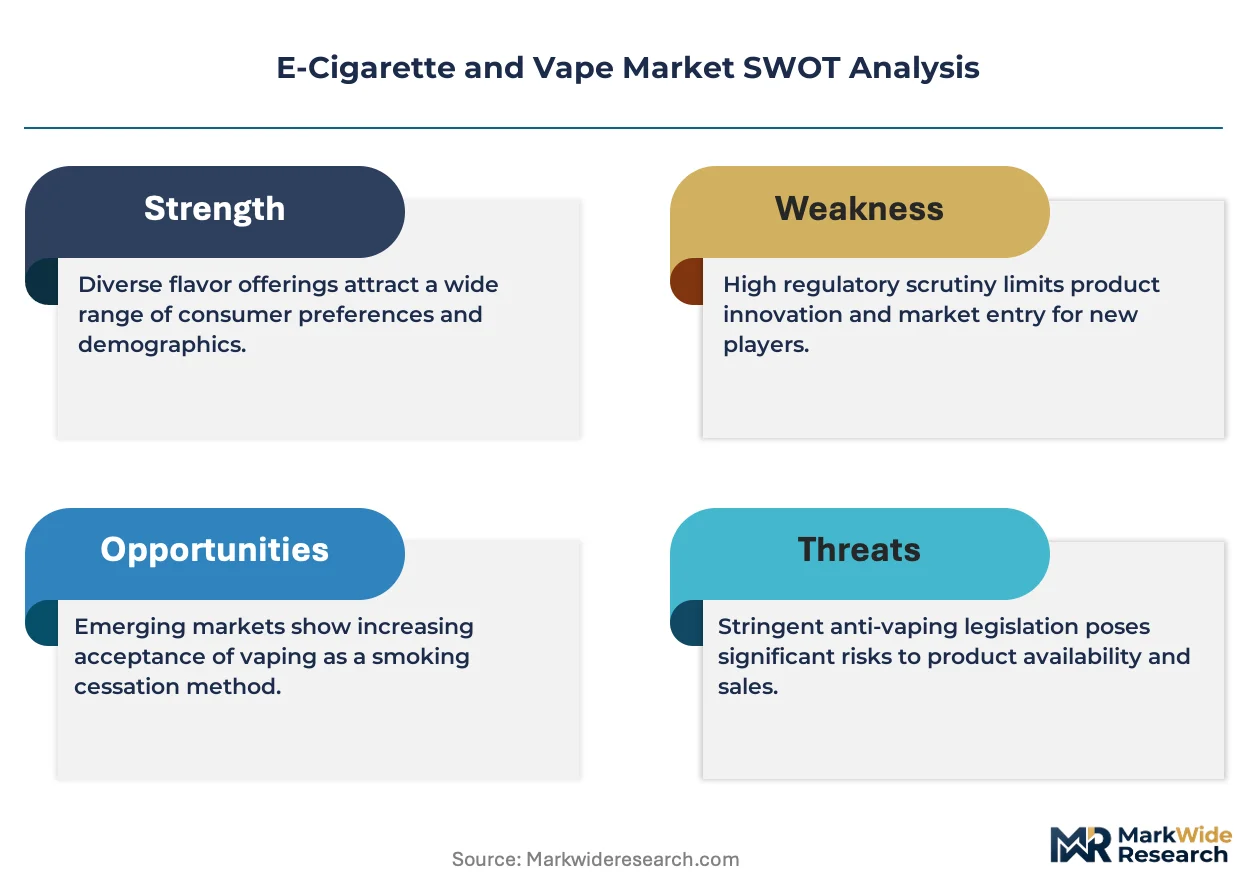
FDA premarket authorization requirements and EU Tobacco Products Directive standards constrain product innovation timelines while elevating compliance costs for market entrants. State-level flavor bans in jurisdictions like California and Massachusetts fragment demand patterns and force inventory segmentation. The EU Green Deal's extended producer responsibility frameworks impose end-of-life collection obligations on device manufacturers. Stakeholders must monitor evolving synthetic nicotine classification debates and battery waste regulations to anticipate supply chain restructuring requirements.
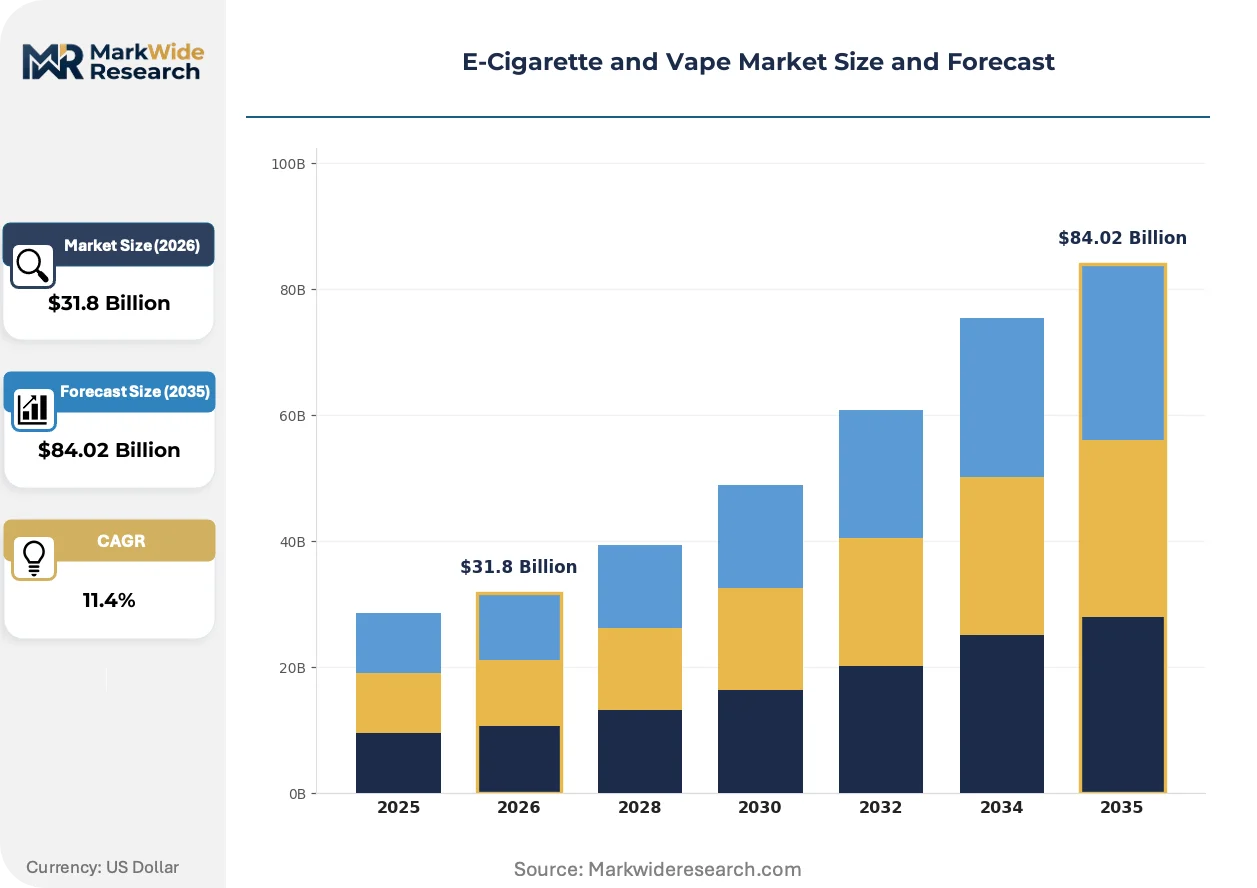
Market Dynamics
FDA premarket tobacco product application requirements and state-level flavor restrictions are fragmenting competitive positioning across the United States, forcing manufacturers to maintain parallel product portfolios and compliance systems for each jurisdiction.
Growth Catalysts
- Pod-system portability:Compact form factors and prefilled cartridge convenience attract young adult recreational users seeking discrete consumption options.
- EU Tobacco Products Directive harmonization:Standardized labeling and notification requirements reduce cross-border market entry friction for compliant manufacturers.
- Synthetic nicotine classification debates:Regulatory ambiguity around non-tobacco-derived nicotine sources creates temporary product development windows before formal reclassification.
Market Restraints
- Lithium-ion battery supply concentration:Cell production concentrates in East Asian manufacturing clusters, exposing device assemblers to input cost volatility and logistics bottlenecks.
- FDA marketing denial orders:Premarket authorization rejections for flavored cartridge products eliminate revenue streams without substitute product readiness.
- Combustible tobacco price elasticity:Traditional cigarette tax differentials in certain states reduce relative cost attractiveness of switching to vapor products.
Strategic Opportunities
- Direct-to-consumer platform expansion:Age-verification technology maturation enables bypass of retail channel restrictions in permissive jurisdictions.
- Extended producer responsibility frameworks:EU Green Deal battery collection mandates create service revenue streams through take-back program operation.
- Heated tobacco convergence:Hybrid device architectures combining vapor and heated tobacco functions capture dual-user segments in premium positioning.
Industry Challenges
- Aerosol toxicology certification timelines:FDA premarket authorization studies require 12-24 month clinical data generation before submission eligibility.
- Flavor chemist talent scarcity:Food-grade formulation expertise must cross-train into inhalation safety assessment protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | E-Cigarette and Vape Market |
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $84.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vape Pens, Pod Systems, E-Liquids, Mods End User: Smokers, Non-Smokers, Recreational Users, Quitters Distribution Channel: Online Retail, Specialty Stores, Convenience Stores, Supermarkets Flavor Profile: Tobacco, Menthol, Fruit, Dessert |
| Companies Covered | Philip Morris International Inc., British American Tobacco, Altria Group, Inc., Imperial Brands, Japan Tobacco Inc., R.J. Reynolds Vapor Company, JUUL Labs, Inc., International Vapor Group, NicQuid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
E-Cigarette and Vape Market Strategic Shifts & Innovations
Device architecture and regulatory classification frameworks are diverging simultaneously, compressing product lifecycles while expanding compliance complexity for portfolio managers.
Ceramic coil heating elements are replacing traditional metal wire configurations in premium pod systems. Young adult recreational users in urban coastal markets adopt ceramic-core devices for perceived flavor purity and reduced metallic aftertaste. The technology is miniaturizing power delivery systems to sub-10-watt outputs while maintaining aerosol density consistency.
Massachusetts and California flavor bans are forcing inventory segmentation strategies that treat each state as distinct regulatory territories. Manufacturers must maintain separate SKU catalogs, packaging configurations, and distribution contracts for restricted versus permissive jurisdictions. Pod-system brands with national retail partnerships face the highest operational complexity in this fragmented compliance landscape.
Specialty store channel consolidation is accelerating as independent vape shops exit under margin pressure from flavor restrictions and licensing fee increases. Direct-to-consumer platforms and convenience retail chains capture displaced volume, with age-verification API integration becoming the critical capability for online conversion. This channel rotation is most visible in Texas and Florida, where state preemption laws block local flavor restrictions and preserve retail density.
E-Cigarette and Vape Market Segmentation
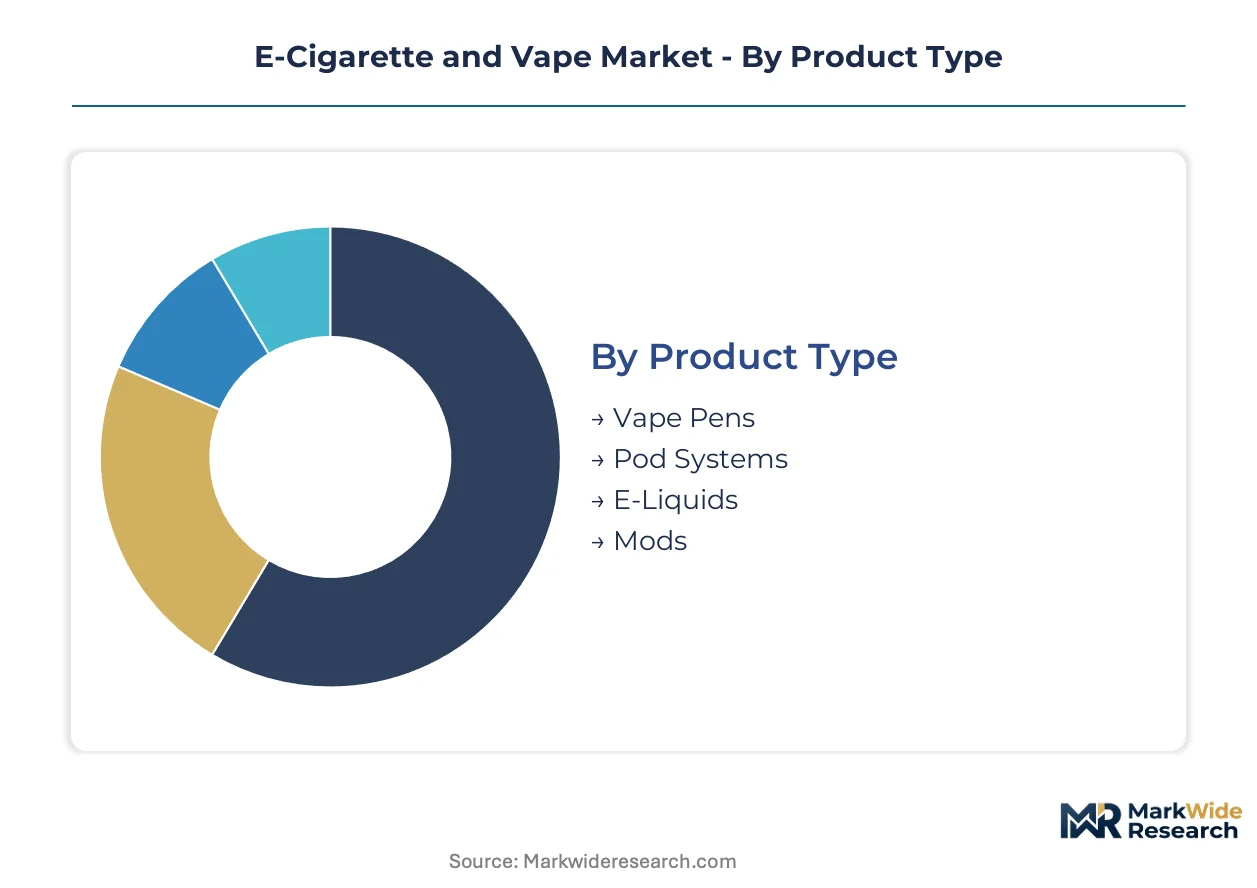
Segment boundaries in the E-Cigarette and Vape Market are blurring as regulatory pressure and user preference evolution force portfolio reconfiguration. Manufacturers must track substitution dynamics across product architectures, user profiles, and channel access points to maintain margin capture.
Product Type:
Substitution pressure concentrates most intensely on open-system architectures as closed-system alternatives achieve performance parity at lower user burden.
- Pod Systems:Compact battery-integrated devices utilizing prefilled or refillable cartridges with proprietary coil assemblies. Demand clusters among young adult recreational users in urban coastal markets where discrete form factors enable social consumption compliance. FDA premarket authorization timelines for cartridge flavors constrain inventory flexibility.
- E-Liquids:Propylene glycol and vegetable glycerin formulations with nicotine salt or freebase delivery, spanning 3mg to 50mg concentrations. Recurring purchase patterns sustain manufacturer margin pools while flavor chemist scarcity limits formulation innovation velocity. Massachusetts and California flavor bans fragment SKU viability.
- Vape Pens:Cylindrical devices with integrated tanks and fixed voltage outputs. Entry-level positioning attracts price-sensitive switchers from combustible tobacco.
- Mods:Modular systems with variable wattage control and rebuildable atomizer compatibility. Enthusiast segment concentration limits mass-market penetration.
Pod Systems anchor the volume base while E-Liquids gains share at the steepest rate through recurring revenue attachment.
End User:
Cost tier stratification separates clinical cessation-oriented users from discretionary recreational adopters with divergent willingness-to-pay profiles.
- Recreational Users:Young adult adopters prioritizing flavor variety and social signaling over nicotine dependency management. Urban density in Texas and Florida preserves retail access where state preemption blocks local restrictions. Ceramic coil adoption concentrates in this segment for perceived flavor purity.
- Quitters:Former smokers utilizing vapor products as cessation aids with gradual nicotine tapering protocols. Healthcare provider recommendation channels in the United Kingdom and Germany validate product selection. Dual-use patterns with heated tobacco complicate pure-segment classification.
- Smokers:Current combustible tobacco users exploring reduced-risk alternatives. Price elasticity sensitivity limits premium product attachment.
- Non-Smokers:Nicotine-naive individuals initiating use through social contagion. Regulatory scrutiny concentrates on this segment for youth access prevention.
Recreational Users dominate transaction frequency while Quitters command the highest per-unit price tolerance.
Distribution Channel:
Channel volume is shifting toward digital access points as age-verification technology matures and retail licensing burdens intensify.
- Online Retail:Direct-to-consumer platforms leveraging third-party age-verification APIs and signature-confirmed delivery. Texas and Florida volume concentration reflects permissive state regulatory frameworks. Convenience store displacement accelerates where flavor restrictions eliminate competitive assortment.
- Specialty Stores:Independent vape shops providing coil building services and flavor sampling. Margin compression from licensing fee increases drives consolidation into multi-location chains.
- Convenience Stores:Tobacco-forward retail with limited SKU breadth and restricted flavor availability. Pod system dominance reflects space constraints.
- Supermarkets:Mass-market retail with age-gated fixture placement. Regulatory compliance complexity limits category expansion.
Online Retail captures volume growth fastest while Specialty Stores retain the highest margin per transaction.
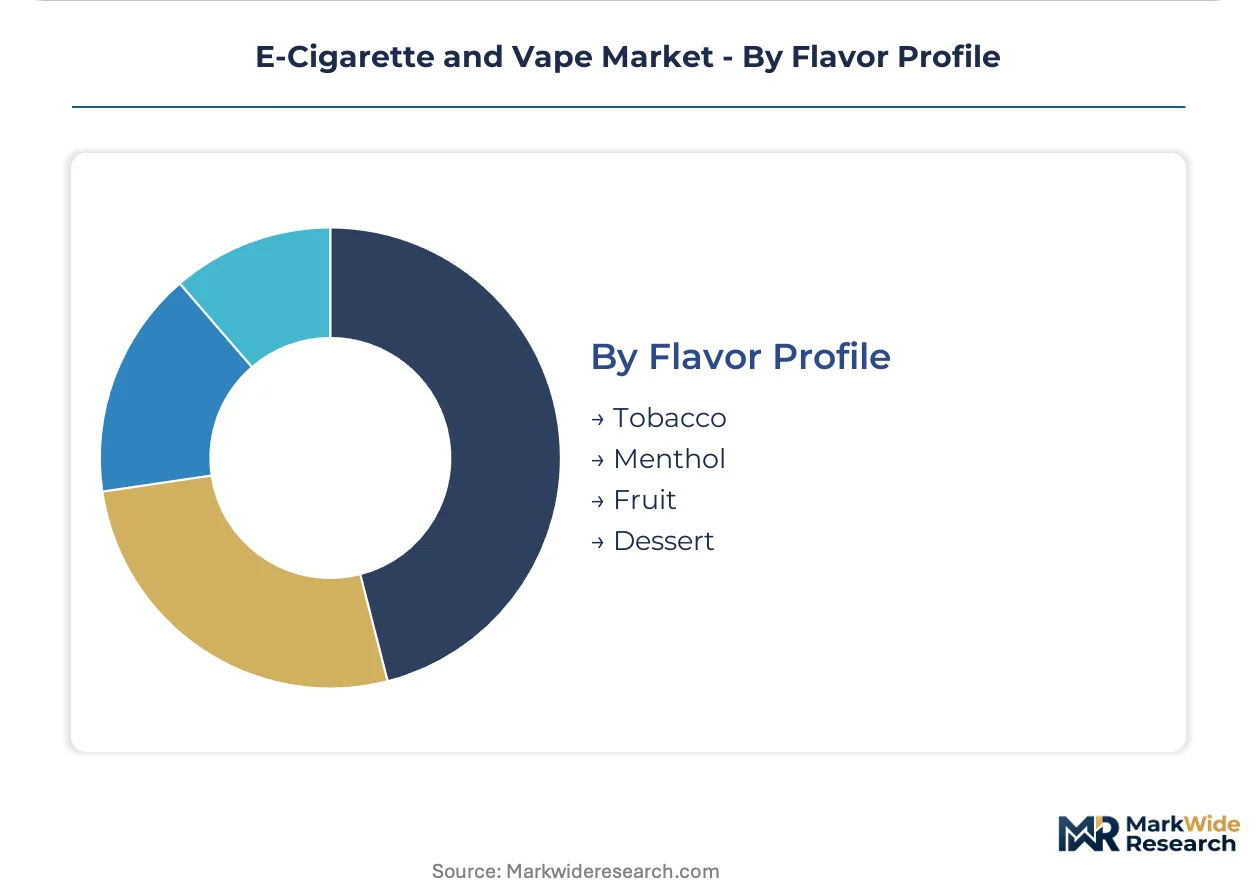
Flavor Profile:
Regulatory classification debates are forcing flavor portfolio segmentation that treats synthetic and tobacco-derived nicotine bases as distinct compliance categories.
- Fruit:Berry and tropical formulations commanding premium pricing in permissive jurisdictions. FDA marketing denial order exposure creates inventory risk concentration.
- Dessert:Custard and bakery profiles with complex flavor layering requiring extended steeping protocols. Enthusiast segment loyalty sustains niche positioning.
- Tobacco:Combustible taste replication for switcher transition support. Premarket authorization pathway clarity favors this segment.
- Menthol:Cooling agent integration with mint or tobacco bases. Characterizing flavor restrictions in Massachusetts and California eliminate legal sale.
Tobacco flavor anchors regulatory compliance while Fruit climbs fastest where jurisdiction permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the United Kingdom demonstrate the lowest price elasticity for premium pod systems, while consumers in India and Indonesia remain highly sensitive to device cost differentials. This demand-elasticity contrast shapes regional portfolio strategies across manufacturers.
United States
Young adult recreational users in Texas and Florida drive volume through permissive state frameworks that preempt local flavor restrictions. FDA premarket tobacco product application requirements create 12-24 month approval bottlenecks that constrain flavor innovation. Los Angeles and Miami retail clusters concentrate ceramic coil adoption among urban coastal demographics seeking discrete consumption formats.
Germany
Healthcare provider validation channels support quitters transitioning from combustible tobacco through pharmacy-distributed nicotine salt formulations. EU Tobacco Products Directive notification requirements standardize cross-border labeling but elevate compliance documentation burdens. Berlin and Hamburg specialty store networks maintain coil-building service capabilities that sustain enthusiast segment loyalty despite online retail encroachment.
United Kingdom
Smoking cessation program integration positions vapor products as clinically endorsed reduced-risk alternatives within National Health Service pathways. Medicines and Healthcare products Regulatory Agency oversight applies to licensed cessation products while general consumer devices fall under Trading Standards enforcement. Manchester and Birmingham distribution hubs service direct-to-consumer platforms leveraging third-party age-verification API integration.
Japan
Heated tobacco convergence dominates premium positioning as Philip Morris International's IQOS infrastructure captures dual-user segments seeking hybrid functionality. Ministry of Health, Labour and Welfare nicotine liquid regulations prohibit sales of high-concentration e-cigarettes while heated tobacco products operate under separate classification. Tokyo and Osaka convenience retail chains prioritize space-efficient pod systems over open-system architectures.
India
Price-sensitive switchers from traditional bidis and cigarettes gravitate toward low-cost vape pen configurations with fixed voltage outputs. Prohibition of Electronic Cigarettes Act enforcement varies across state jurisdictions, creating regulatory patchwork that informal channels exploit. Maharashtra and Gujarat manufacturing clusters produce device components for export markets while domestic distribution operates through unlicensed retail networks.
E-Cigarette and Vape Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the E-Cigarette and Vape Market structure. Multinational tobacco conglomerates control premium pod-system distribution through convenience retail partnerships and direct-to-consumer platforms. Independent e-liquid formulators and device assemblers occupy mid-market positions with regional manufacturing footprints. Competitive dynamics center on FDA premarket authorization acquisition and ceramic coil technology licensing.
Within the integrated tobacco conglomerate tier, Philip Morris International Inc., British American Tobacco, and Altria Group, Inc. exemplify divergent strategic postures. Philip Morris International anchors heated tobacco convergence through infrastructure investments that capture dual-user segments. British American Tobacco represents pod-system dominance in convenience retail channels with proprietary cartridge architectures. Altria Group occupies a position emphasizing distribution depth through specialty store partnerships and age-verified direct-to-consumer platforms.
| Leading Market Players |
|---|
| Philip Morris International Inc. |
| British American Tobacco |
| Altria Group, Inc. |
| Imperial Brands |
| Japan Tobacco Inc. |
| R.J. Reynolds Vapor Company |
| JUUL Labs, Inc. |
| International Vapor Group |
| NicQuid |
| Others |
Cost & Logistics Intelligence
Capacity utilization rates above 85% in Shenzhen and Dongguan manufacturing clusters compress marginal cost curves for lithium-ion battery cells and ceramic heating elements, establishing price floors that upstream device assemblers cannot undercut without sacrificing coil consistency or battery safety certification tiers.
Pricing Analysis
Recurring e-liquid cartridge purchases generate 60-70% of lifetime customer value, shifting pricing power toward subscription and auto-replenishment models. Three-tier pricing structure across premium ceramic-core pod systems, standard metal-coil alternatives, and economy vape pen configurations reflects certification grade differentiation and after-sales service bundling. Cost compression in the standard tier intensifies as Chinese contract manufacturers achieve scale in closed-system assembly. Recreational users in urban coastal markets exhibit the lowest price sensitivity, while price-sensitive switchers from combustible tobacco in India and Indonesia gravitate toward entry-level fixed-voltage devices.
Supply Chain Analysis
China dominates lithium-ion cell production and ceramic substrate fabrication, while South Korea and Japan supply precision heating wire and battery management integrated circuits. Device assembly draws from propylene glycol and vegetable glycerin feedstocks concentrated in Malaysian and Indonesian chemical processing hubs. Single-source vulnerability concentrates in high-purity nicotine extraction, where four suppliers control 80% of pharmaceutical-grade output. Distribution runs through direct-to-consumer platforms with age-verification API integration in permissive jurisdictions, bypassing retail channel fragmentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pod-system penetration among young adult recreational users remains below 40% in Texas and Florida, creating runway for adoption expansion before regulatory saturation.
For Market Incumbents: Consolidate ceramic coil technology licensing positions and captive e-liquid formulation capacity to defend against synthetic nicotine reclassification threats. Acquire distressed specialty store networks in Massachusetts and California to maintain distribution depth despite flavor ban displacement. Lock in exclusive battery supply agreements with Shenzhen manufacturers before lithium carbonate price volatility escalates input costs. For New Entrants and Emerging Players: Differentiate on EU Tobacco Products Directive pre-notification compliance to capture cross-border market entry before incumbents reconfigure portfolios. Target pharmacy-distributed nicotine salt formulations in Germany and the United Kingdom where healthcare provider validation commands premium pricing. Pursue direct-to-consumer platform launches with integrated age-verification APIs in Texas and Florida where state preemption preserves retail access. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic heating element specialists with FDA premarket authorization submission readiness over metal-coil legacy architectures. Five-to-ten year viability hinges on synthetic nicotine classification resolution and extended producer responsibility framework compliance capability. Watch FDA marketing denial order appeal success rates as inflection indicator for flavor portfolio valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Authorization Submission | Regulatory clearance unlocks flavored cartridge sales in the United States market. |
| Ceramic Coil Technology Licensing | Flavor purity positioning captures young adult recreational users in urban coastal clusters. |
| Direct-to-Consumer Platform Expansion | Age-verification API integration bypasses retail channel restrictions in permissive jurisdictions. |
| Extended Producer Responsibility Program Launch | EU Green Deal battery collection mandates create service revenue streams in Germany. |
| Synthetic Nicotine Product Line Diversification | Regulatory ambiguity window enables temporary portfolio expansion before reclassification. |
Research Approach
A spread of perspectives from device manufacturing executives, e-liquid formulation chemists, specialty store operators, and FDA regulatory consultants converged on the working assumptions for market sizing and growth trajectory validation. Primary fieldwork combined structured interviews with secondary triangulation against FDA premarket tobacco product application filings, EU Tobacco Products Directive notification databases, and customs import records for lithium-ion battery cells. Bottom-up demand modeling across pod system, e-liquid, and device categories was cross-checked against top-down tobacco industry revenue allocation estimates.
Segmentation dimensions modeled include product architecture, end-user motivation profile, distribution channel access point, and flavor regulatory classification cluster across the analysis window. CAGRs were derived from trend extrapolation of historical volume data adjusted for regulatory intervention probability and substitution elasticity between vapor and heated tobacco alternatives. Forecast inputs incorporated ceramic coil adoption curves, age-verification technology penetration rates, and state-level flavor restriction implementation timelines.
Material uncertainties — FDA marketing denial order reversals, synthetic nicotine reclassification rulings, and lithium supply contract renegotiations — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these regulatory and commodity volatility vectors. Recalibration cycles align with material shifts in premarket authorization approval velocity and EU extended producer responsibility enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Tobacco Pouch Market
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Global Smokeless Tobacco Market
Tobacco Products
Disposable E-Cigarettes Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Nicotine Pouches Market
Tobacco Products
E-Cigarettes and Vaporizer Market
Tobacco Products
Homemade Cigars Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Premium Cigarette Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Global Flavor Capsule Cigarette Market