
 GCC E-Cigarette Market | 2026-2036
GCC E-Cigarette Market Size, Share, and Industry Trends Forecast 2026-2036
GCC E-Cigarette Market Intelligence
Asset-light leasing and consignment models for vape retail fixtures is tilting competitive dynamics toward operators with balance-sheet flexibility rather than manufacturing scale alone. Philip Morris International leverages its heated-tobacco infrastructure to sustain shelf presence in Gulf duty-free channels. British American Tobacco anchors its position through proprietary pod-system supply chains that bypass third-party distributors. JUUL Labs competes via flavor-restricted portfolios calibrated to Saudi and UAE compliance thresholds.
An e-cigarette is an electronic nicotine delivery system comprising a lithium-ion battery, atomizer, and e-liquid reservoir that vaporizes propylene glycol or vegetable glycerin solutions for inhalation, typically operating at 3.7 to 4.2 volts and temperatures between 200°C and 250°C. Pod systems now capture the majority of volume in GCC markets due to their discrete form factor and lower per-use cost structure, while disposable units face margin compression from flavor-ban enforcement in Saudi Arabia. Online retail channels sustain premium pricing through subscription models, though specialty stores retain higher conversion rates for first-time purchasers seeking product education.
Saudi Food and Drug Authority standards on maximum nicotine concentration and UAE Emirates Authority for Standardization and Metrology labeling requirements collectively restrict product formulations available for legal sale. MOHAP and Dubai Municipality health inspections further constrain retail placement near schools and religious sites, reshaping store-location strategy. Stakeholders must monitor pending harmonization of Gulf Cooperation Council technical regulations, as unified standards would eliminate current regulatory arbitrage between member states.
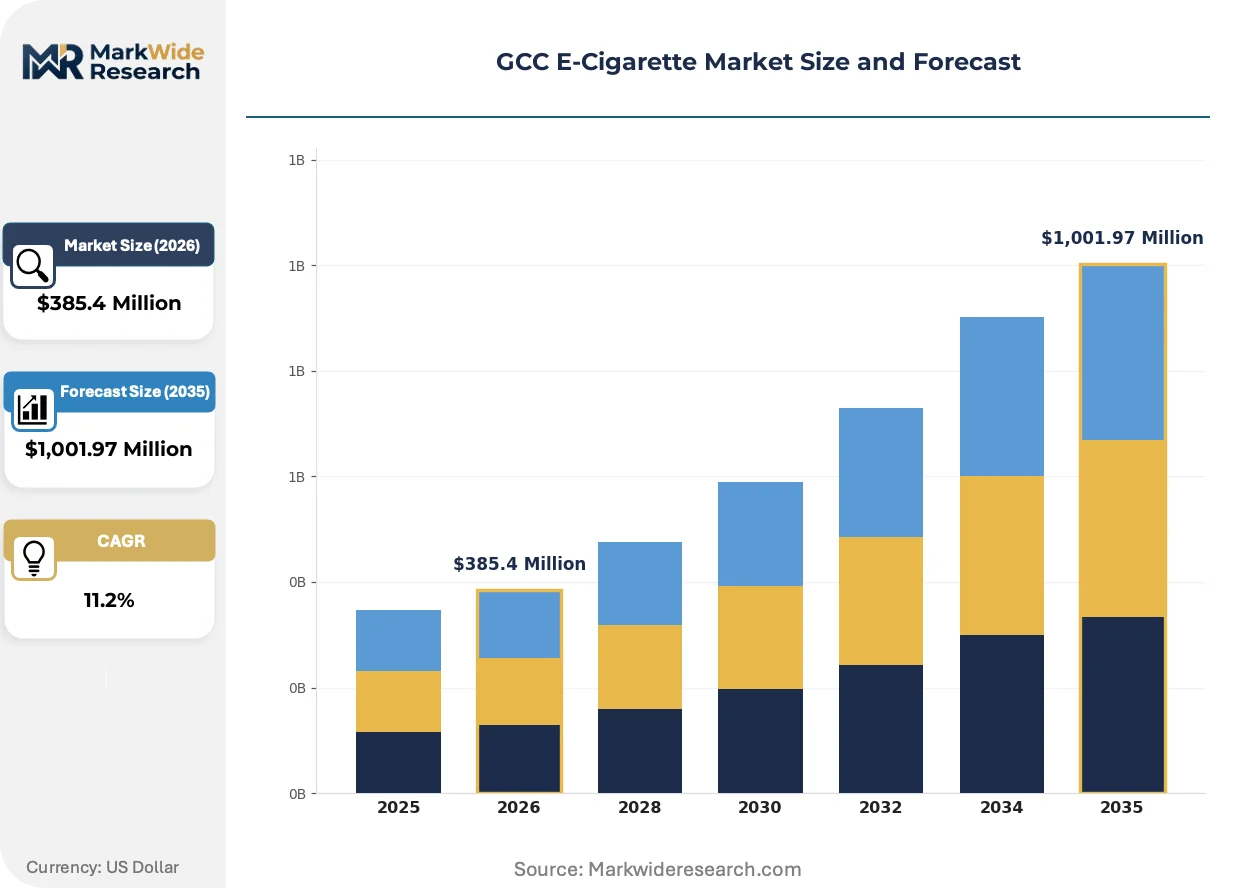
Market Dynamics
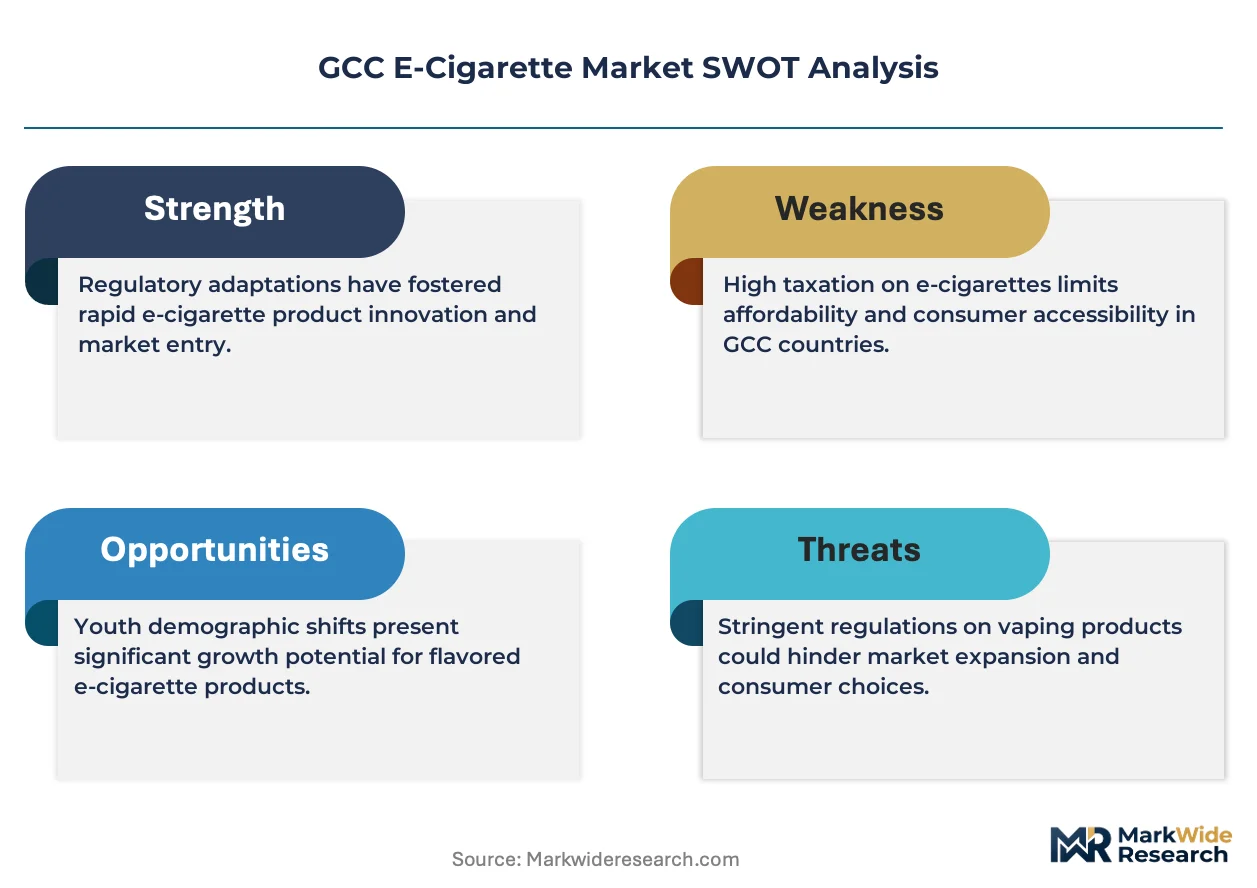
Regulatory fragmentation across Saudi Arabia, the UAE, and neighboring Gulf states is forcing manufacturers to maintain multiple product variants, compressing margins and tilting advantage toward operators with localized compliance infrastructure.
Growth Catalysts
- Tourism-driven duty-free channels:Dubai International Airport and King Khalid International sustain premium volume through transit passenger conversion. High-margin pod systems dominate this channel.
- SFDA nicotine thresholds:Saudi Arabia's 20mg/mL maximum concentration standard has stabilized product formulations, reducing R&D fragmentation and accelerating registration timelines for compliant portfolios.
- Closed-system technology:Proprietary pod architectures with temperature-controlled atomizers are capturing share from open-tank systems due to consistency and leak reduction.
Market Restraints
- Flavor prohibition enforcement:Saudi Food and Drug Authority bans on characterizing flavors beyond tobacco and menthol eliminate the primary differentiation lever for disposable manufacturers.
- Lithium-ion supply concentration:Battery cell sourcing remains concentrated among East Asian suppliers, exposing GCC assemblers to freight cost volatility and extended lead times.
- Religious site proximity rules:Dubai Municipality and MOHAP buffer-zone requirements restrict retail placement within 150 meters of mosques and schools, constraining addressable real estate in dense urban cores.
Strategic Opportunities
- Kuwait regulatory opening:Pending standardization by the Public Authority for Industry creates first-mover advantage for pre-registered Saudi and UAE product lines.
- Subscription direct-to-consumer:Recurring revenue models bypass shelf-space competition and capture lifetime value from young adult users in Riyadh and Jeddah.
- Heated-tobacco convergence:Integration of e-liquid and heated-tobacco hybrid devices leverages existing retail relationships while diversifying beyond vapor-only portfolios.
Industry Challenges
- Product registration cadence:SFDA and Emirates Authority for Standardization and Metrology require separate toxicology dossiers and stability testing, extending time-to-market by 8-14 months.
- Retailer education gaps:Specialty store staff lack technical training on battery safety and nicotine pharmacokinetics, elevating liability exposure and dampening conversion rates for complex devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC E-Cigarette Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable, Rechargeable, Pod Systems, E-Liquids Distribution Channel: Online Retail, Specialty Stores, Convenience Stores, Supermarkets Customer Type: Full-Time Users, Part-Time Users, New Users, Bystanders Flavor Profile: Tobacco, Menthol, Fruit, Dessert |
| Companies Covered | Philip Morris International, British American Tobacco, Imperial Brands, Japan Tobacco International, JUUL Labs, Altria Group, R.J. Reynolds Vapor Company, Aspire Global, Shenzhen IVPS Technology, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC E-Cigarette Market Strategic Shifts & Innovations
Device architecture and retail access models are undergoing simultaneous transformation as compliance costs reshape viable competitive strategies across the Gulf.
Ceramic coil atomization with embedded temperature sensors is rendering obsolete traditional cotton-wick systems in premium pod devices. Young adult recreational users in Dubai and Riyadh are migrating to these systems within 18-month replacement cycles. The shift is compressing aftermarket coil and wick revenue pools while concentrating margin capture at the device OEM level.
MOHAP's 2024 labeling amendments mandate Arabic-English dual-language packaging with pictorial health warnings covering 65% of surface area. This regulatory tightening is eliminating gray-market imports and accelerating formal distribution channel consolidation. Saudi Arabia's parallel SFDA traceability requirements are forcing distributors to deploy serialization infrastructure ahead of unified GCC standards.
Specialty vape retailers are unbundling after-sales service from hardware transactions, shifting toward membership models with device maintenance and liquid replenishment subscriptions. This behavioral pivot is displacing single-purchase economics in Abu Dhabi and Dammam. The model concentrates customer data ownership with vertically integrated operators capable of direct fulfillment.
GCC E-Cigarette Market Segmentation
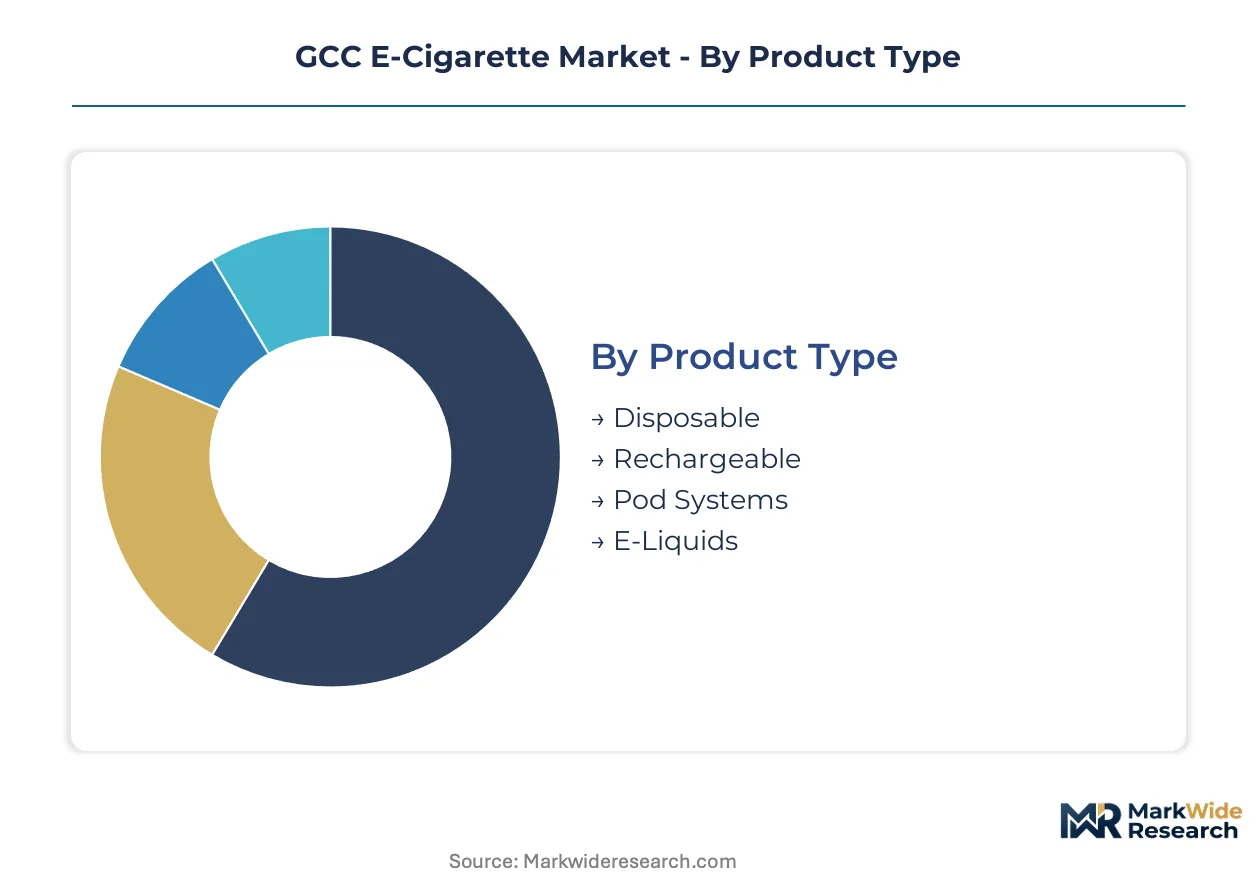
Segmentation in the GCC e-cigarette market reveals how regulatory pressure and user behavior fragment commercial opportunity across product architectures, channel economics, and flavor compliance. Understanding these divides is essential for allocating capital toward segments with sustainable margin structures.
Product Type:
Use-case spectrum spans from single-session convenience to modular systems with recurring liquid replenishment, with each architecture carrying distinct regulatory exposure and lifetime value profiles.
- Disposable:Single-unit devices with integrated battery and pre-filled reservoir, typically 1.2-2mL capacity, face margin compression from SFDA flavor prohibitions and environmental disposal scrutiny in Dubai Municipality jurisdictions.
- Pod Systems:Proprietary cartridge architectures with magnetic or snap-fit connections dominate volume in Riyadh and Dubai retail, where discrete form factors and closed-system compliance with nicotine concentration thresholds accelerate adoption among young adult recreational users.
- Rechargeable:Open-tank systems with replaceable coils retain enthusiast segments in specialty retail but require technical literacy that dampens conversion among first-time purchasers in Jeddah and Dammam.
- E-Liquids:Standalone propylene glycol and vegetable glycerin formulations, sold in 10-30mL bottles, concentrate revenue in online subscription channels where Saudi and UAE labeling compliance can be verified pre-shipment.
The dominant share belongs to Pod Systems, while Disposable is closing the gap fastest despite regulatory headwinds.
Distribution Channel:
Channel cost tiers separate premium experience-based retail from high-velocity convenience placement, with regulatory proximity rules reshaping real estate viability across Saudi and UAE urban cores.
- Specialty Stores:Dedicated vape retailers with trained staff and tasting bar infrastructure capture highest conversion rates for complex devices in Abu Dhabi and Dammam, though MOHAP and Dubai Municipality buffer-zone restrictions constrain addressable locations near schools and religious sites.
- Online Retail:Direct-to-consumer platforms with subscription mechanics bypass shelf-space competition and sustain premium pricing through recurring revenue models targeting Riyadh and Jeddah young adult demographics.
- Convenience Stores:High-traffic petroleum retail and urban kiosk networks in Dubai and Riyadh prioritize disposable and pod formats with minimal staff interaction requirements.
- Supermarkets:Hypermarket chains in Saudi Arabia and the UAE maintain limited SKU counts focused on tobacco-menthol flavor portfolios compliant with SFDA and Emirates Authority for Standardization and Metrology standards.
Specialty Stores command the highest margin per transaction, yet Online Retail is expanding most quickly as serialization infrastructure enables regulatory-compliant fulfillment.
Customer Type:
Volume concentration tilts toward established users with predictable consumption patterns, while acquisition economics favor identifying behavioral transition points between trial and habitual use.
- Full-Time Users:Daily consumers with device loyalty and flavor preferences drive recurring revenue in subscription channels and specialty retail membership programs across Dubai and Riyadh.
- New Users:First-time purchasers seeking smoking alternatives concentrate in specialty stores requiring staff education on battery safety and nicotine pharmacokinetics, elevating liability exposure for untrained retailers.
- Part-Time Users:Occasional recreational consumers favor disposable formats for social contexts, though Saudi flavor restrictions compress this segment's available product range.
- Bystanders:Non-users exposed to secondhand vapor represent a regulatory constituency rather than revenue source, influencing Dubai Municipality and MOHAP public space restrictions.
Full-Time Users generate the majority of lifetime value, while New Users are gaining share fastest as smoking cessation messaging penetrates Saudi and UAE health communications.
Flavor Profile:
Margin structure concentrates in profiles with regulatory clearance, where compliance certification creates defensible shelf position against gray-market competition.
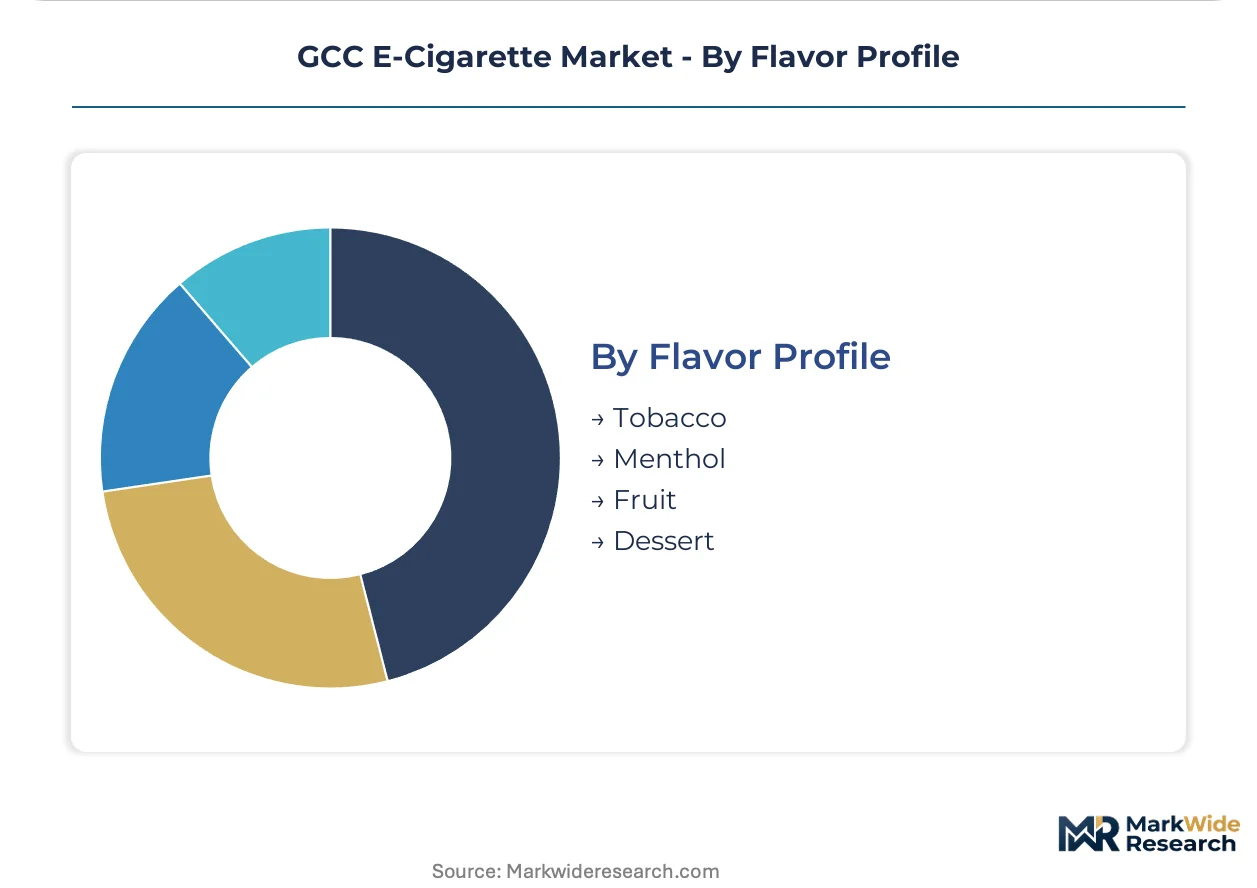
- Tobacco:Traditional cured and blended flavor formulations enjoy universal regulatory acceptance across SFDA and Emirates Authority for Standardization and Metrology jurisdictions, anchoring supermarket and convenience placement.
- Menthol:Cooling agent formulations with synthetic or natural menthol crystallization remain permitted under Saudi and UAE standards, sustaining differentiation within otherwise restricted flavor portfolios.
- Fruit:Characterizing flavor bans in Saudi Arabia eliminate legal domestic sale, though transit passenger demand at Dubai International Airport duty-free sustains limited premium volume.
- Dessert:Sweet profile formulations face identical prohibition enforcement as fruit variants, relegating remaining demand to pre-ban inventory liquidation and informal channels.
Tobacco maintains the installed base, yet Menthol is climbing the fastest as manufacturers reformulate portfolios around compliant differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency on battery cells and atomizer components tilts trade balances across Gulf Cooperation Council members, while domestic assembly operations concentrate in free zones near major aviation hubs.
Saudi Arabia
Riyadh and Jeddah absorb the majority of domestic consumption as young adult recreational users drive pod system adoption. SFDA nicotine concentration ceilings at 20mg/mL and flavor prohibitions beyond tobacco and menthol constrain product portfolios. Eastern Province manufacturing zones host assembly operations serving duty-free export channels.
United Arab Emirates
Dubai International Airport transit passenger volumes sustain premium pod system sales through duty-free retail networks. MOHAP labeling amendments mandate Arabic-English dual-language packaging with 65% pictorial health warning coverage. Abu Dhabi specialty retailers are unbundling after-sales service into membership models with recurring liquid replenishment.
Kuwait
Pending standardization by the Public Authority for Industry creates regulatory clarity for pre-registered Saudi and UAE product lines seeking first-mover positioning. Hawalli Governorate retail corridors concentrate initial distribution partnerships. The country's central bank payment infrastructure supports subscription direct-to-consumer models targeting young adult demographics.
Bahrain
Manama's compact urban geography enables rapid specialty store network expansion with minimal logistics overhead. The national standards body aligns technical regulations with emerging GCC harmonization frameworks. Seef Mall and City Centre retail clusters host premium positioning for closed-system devices.
Qatar
Hamad International Airport duty-free channels capture transit passenger demand with restricted flavor portfolios compliant with national tobacco control directives. Doha retail placement faces buffer-zone constraints near educational and religious institutions. The Qatar Free Zones Authority offers assembly incentives for regional re-export operations.
GCC E-Cigarette Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in atomizer and battery supply. Market structure tilts toward consolidated multinational operators with localized compliance infrastructure, compressing margins for fragmented assemblers lacking registration scale. Three archetypes dominate: heated-tobacco platform extenders, proprietary pod-system architects, and open-tank component suppliers. Competitive moves concentrate on portfolio diversification beyond vapor-only portfolios and geographic expansion through duty-free channel capture.
Within the multinational platform tier, Philip Morris International and British American Tobacco exemplify operators leveraging existing tobacco infrastructure for Gulf shelf presence. JUUL Labs occupies a position calibrated to Saudi and UAE compliance thresholds with flavor-restricted portfolios. These three anchors represent divergent strategic postures: heated-tobacco convergence, proprietary supply chain control, and regulatory-minimum product configuration.
| Leading Market Players |
|---|
| Philip Morris International |
| British American Tobacco |
| Imperial Brands |
| Japan Tobacco International |
| JUUL Labs |
| Altria Group |
| R.J. Reynolds Vapor Company |
| Aspire Global |
| Shenzhen IVPS Technology |
| Others |
Cost & Logistics Intelligence
Single-source dependency on East Asian lithium-ion cell manufacturers exposes GCC assemblers to freight cost volatility that compresses both premium tier spreads and distributor margin structures across Saudi Arabia and the UAE.
Pricing Analysis
Young adult recreational users in Dubai and Riyadh anchor a three-tier pricing structure across premium, standard, and economy levels, with ceramic coil devices commanding brand premiums against cotton-wick alternatives. Price differentiation hinges on SFDA compliance certification and after-sales service bundling in membership models. Pricing pressure stems from flavor prohibition enforcement eliminating disposable differentiation levers. Part-time users in social contexts exhibit highest price sensitivity, while full-time subscription customers show lowest elasticity.
Supply Chain Analysis
Propylene glycol and vegetable glycerin feedstocks flow predominantly from China, India, and the United States, with lithium-ion cells sourced from South Korea and Japan. Ceramic coil substrates and temperature control chipsets complete the component matrix. Single-source vulnerability concentrates in battery cell supply, exposing assemblers to extended lead times. Distribution runs through Dubai and Jeddah free-zone consolidation points before final-mile deployment to specialty retailers and online fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across Saudi Arabia, the UAE, and Kuwait creates fragmentation opportunity as compliance complexity favors operators with localized registration infrastructure over multinational standardizers.
For Market Incumbents: Harden proprietary pod-system architectures against heated-tobacco convergence threats by deepening backward integration into ceramic coil manufacturing. Secure shelf position in Dubai International Airport duty-free channels before Kuwait regulatory opening accelerates competitor entry. Investment in SFDA and Emirates Authority for Standardization and Metrology pre-registration dossiers preserves first-mover advantage against harmonized GCC standards. For New Entrants and Emerging Players: Pursue subscription direct-to-consumer models targeting Riyadh and Jeddah young adult demographics, where recurring revenue mechanics bypass established shelf-space competition. Kuwait's pending Public Authority for Industry standardization offers the most penetrable geography for pre-registered Saudi and UAE product line extension. Go-to-market execution should emphasize Arabic-English dual-language packaging compliance as a trust signal. For Investors and Strategic Acquirers: The market sits at a pre-harmonization phase that favors vertically integrated operators with captive compliance infrastructure. Long-term viability over the next decade rests on serialization technology ownership and direct fulfillment capabilities. Acquisition targets should demonstrate established SFDA and MOHAP registration track records. The signal to watch is Gulf Cooperation Council technical regulation harmonization progress as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Registration Investment | SFDA and Emirates Authority dossier completion accelerates time-to-market against harmonized GCC standards. |
| Ceramic Coil Manufacturing Integration | In-house temperature sensor embedding captures margin compression from cotton-wick obsolescence in premium devices. |
| Subscription Platform Development | Recurring revenue mechanics in Riyadh and Jeddah bypass shelf-space competition and concentrate customer data ownership. |
| Duty-Free Channel Capture | Dubai International Airport and King Khalid International transit passenger conversion sustains premium pod system volume. |
| Serialization Infrastructure Deployment | Traceability system investment ahead of unified GCC standards eliminates gray-market competition exposure. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured interviews with SFDA regulatory affairs specialists, Dubai specialty store operators, MOHAP compliance officers, and lithium-ion battery procurement managers at GCC assembly facilities. Secondary validation drew from SFDA product registration databases, Emirates Authority for Standardization and Metrology labeling amendments, Dubai Municipality trade license records, and GCC customs import manifests. Bottom-up volume builds from retail channel audits were triangulated against top-down macroeconomic consumption models.
Calibration against historical pod system adoption curves and heated-tobacco displacement patterns informed trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product architecture, distribution channel cost tier, customer usage frequency, and flavor compliance status. CAGRs were derived from regression analysis of replacement cycle compression and regulatory event impacts. Forecast inputs incorporated MOHAP buffer-zone restriction expansion scenarios and SFDA traceability mandate implementation pacing.
Sensitivities concentrate around Gulf Cooperation Council harmonization timeline acceleration, lithium-ion freight cost spikes, and flavor prohibition enforcement intensity variations. Cross-checking against Dubai Department of Economic Development retail license issuance trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
Europe E-Cigarettes Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Global E-Cigarettes Market
Tobacco Products
Heated Tobacco Products Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Tobacco Products Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Philippines E-Cigarette and Vape Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Global Cigarette Vending Machine Market
Tobacco Products
Smokeless Cigarettes Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
Liquor Flavored Cigars Market