
 Nicotine Pouches Market | 2026-2036
Nicotine Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotine Pouches Market Intelligence
The addressable customer base for nicotine pouches is expanding beyond traditional smokeless tobacco users to include new demographics of adult consumers. Swedish Match leverages its historical dominance in Scandinavian markets to sustain a premium brand presence. British American Tobacco competes through its extensive global distribution network and a diverse flavor portfolio. Altria Group positions its products to capture share within the critical United States market.
Nicotine pouches are small, pre-portioned bags containing nicotine salts or synthetic nicotine mixed with plant-based fibers, designed for oral use. Their primary function is to deliver nicotine to the user without tobacco leaf, combustion, or vapor inhalation. The Flavored product segment accounts for the majority of sales, though it faces increasing regulatory pressure. Distribution through Convenience Stores and Tobacco Shops remains the principal channel for reaching both new users and ex-smokers.
The US Food and Drug Administration (FDA) exercises authority over premarket authorizations and marketing standards, directly impacting product viability. In parallel, EU-level directives and national agencies like Health Canada impose varying rules on nicotine content and permitted ingredients. Navigating these disparate tax structures and the threat of flavor restrictions remains the central strategic challenge for all market participants.
Market Dynamics
The central dynamic shaping the nicotine pouch market is the intense regulatory scrutiny on flavored products. This pressure forces continuous product reformulation and market access strategies across divergent legal frameworks, such as those governed by the US FDA and various EU national agencies.
Growth Catalysts
- Harm Reduction Endorsement:Public health frameworks in countries like Sweden that acknowledge tobacco-free nicotine products as a less harmful alternative to combustible cigarettes encourage smoker transition and create a favorable policy environment.
- Ex-Smoker Demand:A growing cohort of former smokers actively seeks non-combustible, tobacco-leaf-free nicotine delivery systems, creating a foundational and expanding consumer base for manufacturers.
- Channel Expansion:Increased availability through mainstream retail channels, including convenience stores and online platforms, improves accessibility for adult consumers beyond traditional tobacco outlets, reaching a broader demographic.
Market Restraints
- Flavor Prohibitions:Regulatory actions, such as the US FDA's scrutiny and potential restriction of flavored nicotine products, threaten the market's largest product segment and limit consumer choice.
- Disparate Taxation:The lack of a harmonized tax structure, with some jurisdictions imposing steep excise taxes comparable to traditional tobacco, increases consumer costs and can dampen adoption rates.
- Vaping Product Competition:Electronic nicotine delivery systems, or vapes, represent a significant substitution threat, competing directly for the same demographic of adult nicotine users seeking alternatives to smoking.
Strategic Opportunities
- Synthetic Nicotine Development:Investment in synthetic nicotine offers a pathway to differentiate products and potentially navigate certain tobacco-specific regulatory frameworks, creating a distinct product category.
- Underpenetrated Geographies:Markets in Eastern Europe and parts of Asia present significant white space for expansion, provided companies can navigate nascent regulatory environments and establish distribution.
- Online Direct-to-Consumer Models:Building robust age-gated e-commerce platforms enables direct engagement with adult consumers, fostering brand loyalty and bypassing potential restrictions in physical retail channels.
Industry Challenges
- Premarket Authorization Burden:The complexity and cost of navigating premarket authorization processes, such as the FDA's Premarket Tobacco Product Application (PMTA) pathway, create high barriers to entry for new entrants.
- Public Health Misinformation:Differentiating nicotine pouches from traditional smokeless tobacco and combustible cigarettes in public perception remains a persistent communications challenge for the entire industry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotine Pouches Market |
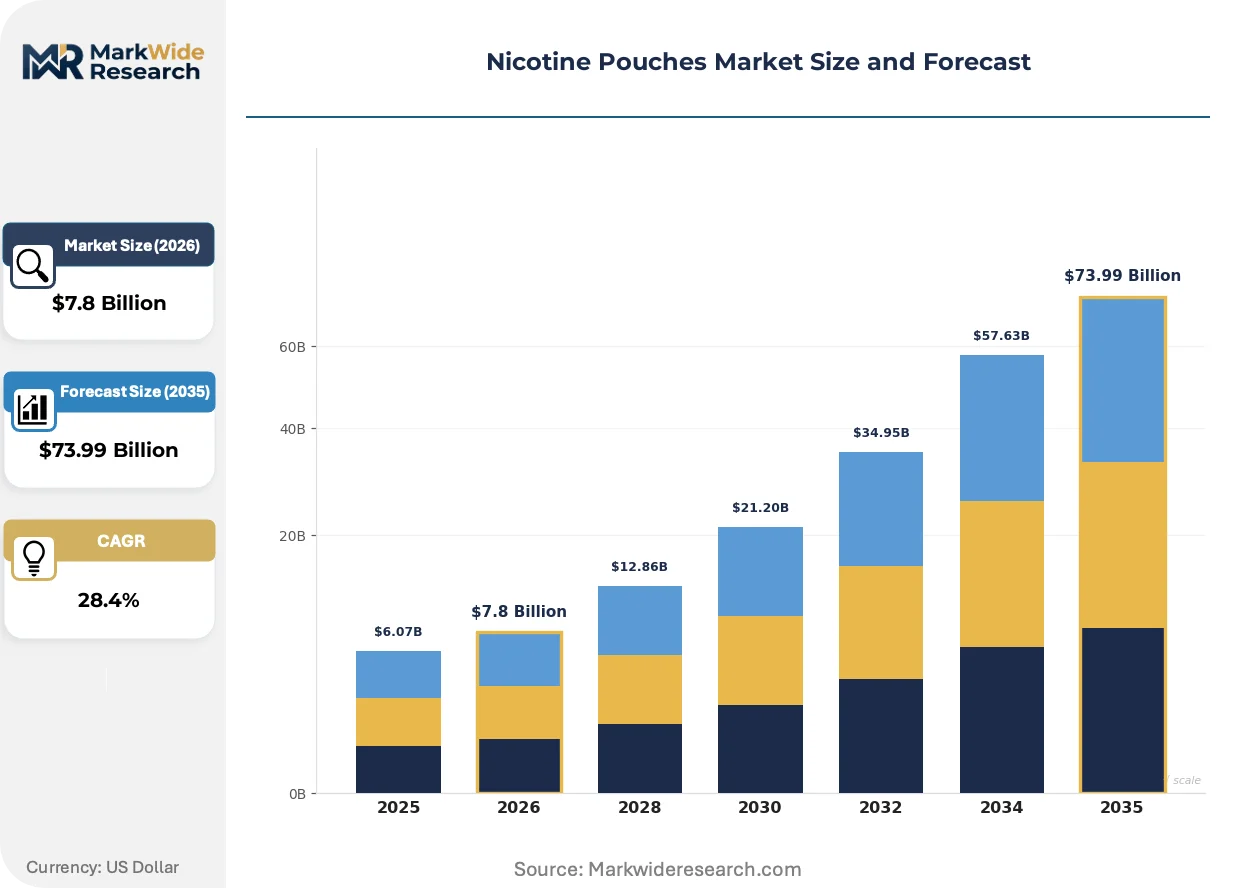
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $73.99 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavored, Unflavored, Herbal, CBD Ingredient Type: Nicotinamide, Tobacco-Free, Nicotine Salt, Natural Extracts Distribution Channel: Online Retail, Convenience Stores, Supermarkets, Tobacco Shops User Type: Regular Users, Occasional Users, New Users, Ex-Smokers |
| Companies Covered | GN Tobacco, Habit Factory, Swedish Match, Neoptolem, Another Snus Factory, British American Tobacco, NGP Tobacco, Helix Innovations, Altria Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotine Pouches Market Strategic Shifts & Innovations
Product innovation in the nicotine pouch market is advancing rapidly, driven by material science and a focus on consumer experience. These developments are occurring within a context of increasing regulatory oversight that shapes which new products ultimately reach the adult consumer and which are restricted from market entry.
Synthetic nicotine, created in a laboratory without using tobacco leaf, provides a pure and consistent nicotine source. Adult consumers and manufacturers are adopting this technology to create products with cleaner flavor profiles and greater formulation control. As a result, synthetic nicotine is overtaking tobacco-derived nicotine in new product formulations to sidestep regulations targeting tobacco itself.
Regulatory bodies are increasingly focused on flavor restrictions to curb perceived youth appeal. Health Canada's regulations on flavors in certain nicotine products signal a potential future direction for oral pouches globally. The flavored product segment, which constitutes the bulk of sales, is most affected, forcing reformulation toward less characteristically sweet profiles to comply with new and anticipated rules.
A notable behavioral shift is the rise of subscription-based, direct-to-consumer (DTC) purchasing models for nicotine pouches. This trend disrupts the traditional reliance on convenience stores and tobacco shops by offering consumers discretion, auto-replenishment, and consistent supply. This online shift is most prominent in the United States, where advanced e-commerce infrastructure and consumer habits support such models.
Nicotine Pouches Market Segmentation
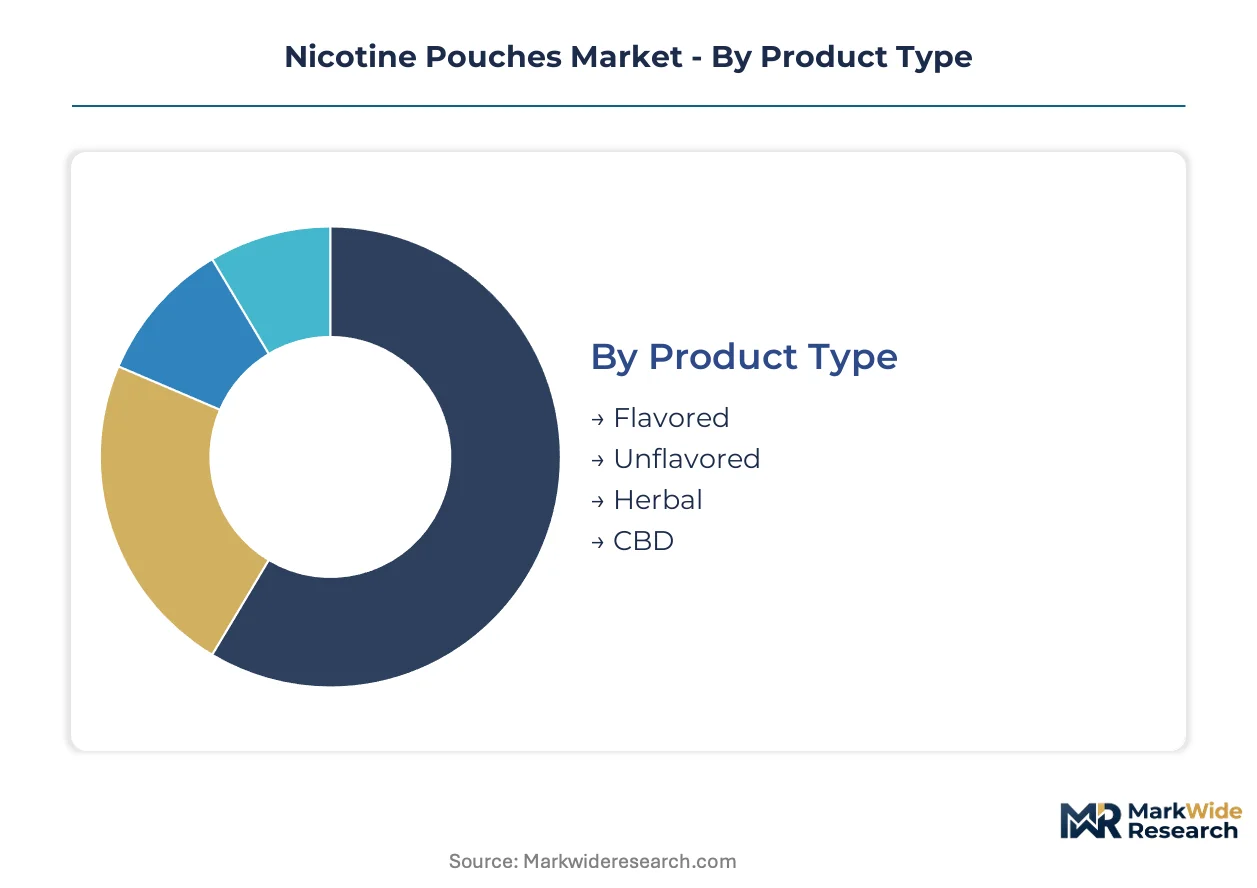
The nicotine pouches market exhibits distinct customer groups and product characteristics, influencing strategic decisions for manufacturers and distributors. Understanding these segments helps companies tailor product development, marketing efforts, and distribution strategies effectively. This detailed analysis provides a granular view of the market's composition.
Product Type:
Supply concentration in product types reflects the established preferences of adult consumers and the evolving regulatory landscape.
- Flavored:These products incorporate various taste profiles, often fruit, mint, or dessert-inspired, designed to enhance the user experience. The Flavored segment currently dominates sales, particularly in regions with less stringent flavor restrictions, despite facing increasing regulatory pressure.
- Unflavored:Unflavored pouches deliver nicotine without additional taste profiles, appealing to consumers who prefer a neutral experience or reside in jurisdictions with flavor bans. This segment is gaining traction as regulatory bodies like Health Canada consider broader flavor prohibitions.
- Herbal:Herbal nicotine pouches utilize plant-based ingredients beyond traditional tobacco, often incorporating botanicals for a distinct user experience. These products cater to a niche market seeking alternative compositions.
- CBD:CBD-infused pouches combine nicotine with cannabidiol, offering a dual-component product designed for specific consumer preferences. These products face additional regulatory hurdles due to CBD content.
Today's leader: Flavored. Tomorrow's challenger: Unflavored.
Ingredient Type:
The ingredient composition directly influences the product's appeal to specific customer types, from those seeking traditional experiences to consumers prioritizing novel formulations.
- Nicotinamide:This ingredient represents a specific form of vitamin B3 that can be used as a nicotine source, offering a unique chemical profile. Products using nicotinamide are exploring new regulatory pathways.
- Tobacco-Free:These pouches contain nicotine derived from sources other than the tobacco leaf, such as synthetic nicotine, and are often perceived as a "cleaner" alternative. The demand for tobacco-free products is expanding among ex-smokers seeking alternatives to traditional tobacco.
- Nicotine Salt:Nicotine salts are a chemically modified form of nicotine found naturally in tobacco leaves, designed for smoother delivery and higher bioavailability. Many popular nicotine pouch brands utilize nicotine salt for its efficient absorption.
- Natural Extracts:This segment incorporates botanical extracts for flavor or other properties, alongside nicotine, appealing to consumers seeking more natural ingredient lists. These products often aim for a premium market position.
Nicotine Salt products maintain significant market presence, while Tobacco-Free formulations show the steepest expansion trajectory.
Distribution Channel:
The chosen distribution channels dictate the volume and accessibility of nicotine pouches to the adult consumer base, impacting market penetration and reach.
- Online Retail:E-commerce platforms provide discretion, convenience, and a broader product selection, particularly appealing to tech-savvy adult consumers. The United States market shows a strong shift towards online direct-to-consumer models for nicotine pouches.
- Convenience Stores:These ubiquitous retail outlets offer high visibility and immediate availability, making them a primary channel for impulse purchases and regular replenishment. Convenience stores remain a principal channel for reaching both new users and ex-smokers.
- Supermarkets:Larger grocery stores provide a mainstream retail environment, allowing for broader consumer exposure and integration into routine shopping habits. Supermarkets often face stricter internal policies regarding nicotine product placement.
- Tobacco Shops:Specialized tobacco retailers cater to established nicotine users, offering expert advice and a focused product assortment. These shops serve as a traditional point of sale for tobacco alternatives.
Convenience Stores currently move the highest volume, but Online Retail is gaining share fastest.
User Type:
Targeting specific user types allows manufacturers to optimize product offerings and marketing messages for maximum margin capture and long-term customer loyalty.
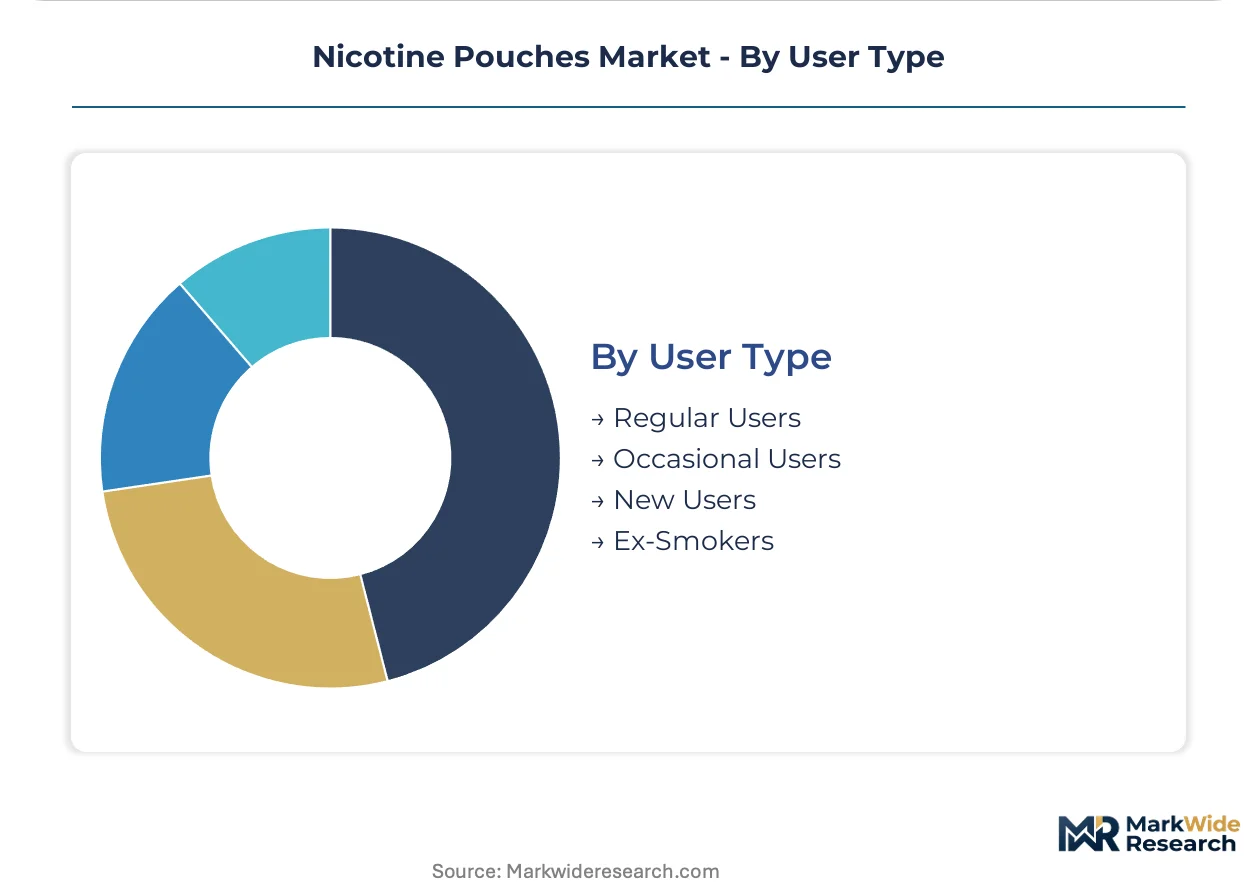
- Regular Users:These consumers have integrated nicotine pouches into their daily routine, often prioritizing consistent supply and familiar product profiles. Their purchasing patterns drive baseline market stability.
- Occasional Users:This group consumes nicotine pouches intermittently, often in specific social settings or situations where smoking is restricted. They seek convenience and discreet options.
- New Users:Individuals exploring nicotine pouches for the first time, often transitioning from other nicotine products or seeking a novel experience. Attracting new users requires clear product benefits and accessible entry points.
- Ex-Smokers:A significant and expanding demographic actively seeking tobacco-free alternatives to combustible cigarettes for harm reduction purposes. Public health frameworks in countries like Sweden encourage this transition.
Regular Users represent a stable customer base, while the Ex-Smokers segment is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States emerges as a pivotal growth geography for nicotine pouches, Sweden's public health frameworks have long supported tobacco-free alternatives. This contrast highlights divergent regulatory approaches and consumer acceptance levels across key markets. Manufacturers adapt product development and market access strategies to these varied regional dynamics.
United States
United States demand for nicotine pouches is driven by ex-smokers seeking tobacco-free options. The US FDA exercises authority over premarket authorizations, impacting product viability and market entry. New York City and California represent significant consumer bases, where online direct-to-consumer models are gaining traction.
Sweden
Sweden's market benefits from a long-standing cultural acceptance of oral tobacco alternatives, fostering high adoption rates. The Swedish Public Health Agency acknowledges harm reduction benefits, creating a favorable policy environment. Stockholm acts as a hub for established brands, leveraging historical dominance in Scandinavian markets.
Canada
Canadian consumers are increasingly adopting nicotine pouches as discreet alternatives to traditional tobacco products. Health Canada's regulations on flavors signal potential future restrictions for oral pouches, influencing product reformulation. Toronto and Vancouver show growing interest, supported by expanding availability through online platforms.
Germany
German demand for nicotine pouches is growing among adult consumers seeking smoke-free nicotine options. The country's national agencies are navigating EU-level directives concerning nicotine content and permitted ingredients. Berlin and Hamburg are emerging as key urban markets, with convenience stores acting as primary distribution channels.
Japan
Japanese consumers show rising interest in novel nicotine delivery systems, including pouches, as an alternative to cigarettes. Japan Tobacco Inc. (JT) influences the market through product development and distribution strategies. Tokyo and Osaka drive initial adoption, where product innovation focuses on cleaner flavor profiles.
Nicotine Pouches Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the nicotine pouches market. The industry structure features a tiered landscape, with established tobacco giants holding significant distribution advantages alongside agile niche players. Strategic archetypes include global tobacco leaders and specialized oral nicotine product manufacturers. Companies pursue portfolio diversification and geographic expansion to capture market share.
Global tobacco leaders such as British American Tobacco and Altria Group exemplify the strategy of leveraging extensive distribution networks and established brand recognition. These entities position products to capture share within critical markets, notably the United States, by offering diverse flavor portfolios. Swedish Match, a historical dominant player, anchors the premium segment, particularly in Scandinavian markets, showcasing deep specialization in oral nicotine products. These companies collectively demonstrate varied approaches to market penetration, from broad-based availability to targeted premium offerings.
| Leading Market Players |
|---|
| GN Tobacco |
| Habit Factory |
| Swedish Match |
| Neoptolem |
| Another Snus Factory |
| British American Tobacco |
| NGP Tobacco |
| Helix Innovations |
| Altria Group |
| Others |
Cost & Logistics Intelligence
Specialized manufacturing workforce concentrations in Scandinavia and Eastern Europe drive labor-cost differentials, influencing the pricing tiers of nicotine pouches. This dynamic shapes the competitive landscape between premium brands and more accessible economy options. The interplay between skilled labor availability and market entry strategies is critical.
Pricing Analysis
Capacity additions in Eastern Europe are reshaping price floors for nicotine pouches, driven by lower manufacturing overheads. The dominant pricing model is per-unit transactional, with online direct-to-consumer models increasingly offering subscription options. Price differentiation stems from established brand premium, notably from Swedish Match, and the certification level, such as US FDA premarket authorization status. Pricing softness reflects increasing competition from new entrants and the availability of lower-cost synthetic nicotine. Occasional users exhibit the highest price sensitivity, whereas regular users prioritize consistent supply and familiar product profiles.
Supply Chain Analysis
Dual-sourcing requirements for critical ingredients are becoming more common among major manufacturers to mitigate risk. Supply chain concentration for nicotine pouch manufacturing is notable in Sweden and parts of Eastern Europe, while raw materials originate from global chemical suppliers. Synthetic nicotine, plant-based fibers, and flavor compounds represent critical raw material dependencies. Regulatory restrictions on specific ingredients or flavor categories present a significant structural risk. Distribution runs through convenience stores and increasingly through online direct-to-consumer platforms, improving accessibility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nicotine pouches market is a stable compounder, with sustained ex-smoker demand for harm reduction alternatives driving consistent growth. This foundational consumer shift underpins long-term market expansion.
For Market Incumbents: Acquire specialized flavor houses to secure compliant formulations and intellectual property for future product development. Consolidate distribution networks in underpenetrated geographies like Eastern Europe to expand market reach. Flavor prohibitions by regulators such as the US FDA pose a significant threat to the largest product segment. Investment in synthetic nicotine development offers a pathway to navigate tobacco-specific regulations, differentiating product offerings.
For New Entrants and Emerging Players: Adult consumers seeking unflavored or herbal options represent an underserved buyer archetype, especially in regions implementing strict flavor bans. Target these specific niches with innovative product compositions. The unflavored segment is most penetrable due to evolving regulatory landscapes and consumer preferences for neutral experiences. Leverage age-gated e-commerce platforms for direct engagement and subscription models, fostering brand loyalty and bypassing traditional retail barriers.
For Investors and Strategic Acquirers: Global tobacco leaders are the most active acquirers in this space, seeking to diversify their portfolios beyond combustible products. The market demonstrates long-term viability over a 5-10 year window, driven by continued harm reduction trends and consumer transitions. Specialized synthetic nicotine manufacturers or robust e-commerce platform providers represent attractive acquisition targets. The signal to watch is the harmonization of global flavor regulations, which will clarify market access and product viability across regions.
| Strategic Initiative | Industry Significance |
|---|---|
| Synthetic Nicotine R&D | Secures regulatory compliance and offers cleaner flavor profiles for adult consumers. |
| DTC E-commerce Platform Expansion | Bypasses physical retail restrictions and fosters direct brand loyalty with adult users. |
| Flavor Reformulation Investment | Adapts product lines to comply with evolving regulatory mandates from bodies like Health Canada. |
| Geographic Market Entry in Asia | Captures white space demand in underpenetrated regions, expanding consumer reach. |
| Premarket Authorization Capability | Navigates complex regulatory pathways, ensuring product viability with the US FDA. |
Research Approach
Direct dialogue with product development executives, regulatory affairs leads, distribution channel managers, and adult consumer focus groups grounds the qualitative insights. This primary research combines with extensive secondary validation from various sources. Secondary data includes US FDA filings, Health Canada regulatory documents, national public health agency reports, and industry association publications. Bottom-up and top-down triangulation ensures data consistency and robust market sizing.
A bottom-up approach aggregates granular segment data, cross-referenced with top-down market sizing for holistic validation. Segmentation dimensions modeled include product type, ingredient type, distribution channel, user type, and regional regulatory frameworks. Compound Annual Growth Rates are derived from historical trends and projected market dynamics over the projection horizon. Regulatory shifts on flavors and synthetic nicotine adoption rates are key forecast inputs for this analysis.
Underlying measurement precision varies by segment; established flavored products carry tighter precision than emerging herbal options. Forecasts reflect documented assumptions regarding regulatory enforcement and consumer adoption rates. Unexpected flavor bans or new taxation structures could significantly revise market projections; deviation in regulatory policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
United States Pipe Tobacco Market
Tobacco Products
Liquor Flavored Cigars Market
Tobacco Products
North America E-Cigarette Market
Tobacco Products
Luxury Cigarette Market
Tobacco Products
E-Cigarette and Vaping Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
West Africa Cigarettes Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Tobacco Pouch Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
Heat-Not-Burn Tobacco Products Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
Africa Tobacco Products Market