
 Philippines E-Cigarette and Vape Market | 2026-2036
Philippines E-Cigarette and Vape Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines E-Cigarette and Vape Market Insights
Republic Act No. 11900, the Vaporized Nicotine and Non-Nicotine Products Regulation Act, is realigning the cost-of-entry calculus for foreign and domestic market participants by mandating product registration, flavor restrictions, and age-verification protocols. Philip Morris International leverages its heated-tobacco infrastructure to extend distribution reach into licensed vape retail channels. RELX International anchors its position through specialty store partnerships and stringent quality certification programs. British American Tobacco competes by sustaining dual-track investments in both disposable formats and rechargeable pod systems.
An e-cigarette and vape is a battery-powered electronic nicotine delivery system that aerosolizes a liquid solution—typically containing propylene glycol, vegetable glycerin, flavoring agents, and optionally nicotine—through resistive heating of a metal coil within an atomizer assembly. The device serves as a reduced-harm alternative for adult smokers seeking to transition away from combustible tobacco consumption. Disposable vapes currently occupy the fastest-expanding product type segment due to low trial barriers and minimal maintenance requirements, though pod systems retain superior margin pools through recurring e-liquid cartridge purchases. Online retail channels are displacing traditional convenience store distribution among urban young adults, while specialty stores sustain premium positioning through hands-on product education and after-sales support.
The Philippine Food and Drug Administration administers product registration and ingredient disclosure mandates, while the Department of Trade and Industry enforces packaging, labeling, and advertising standards under the national consumer protection framework. These overlapping requirements elevate compliance costs for new entrants and compress timelines for product-market introduction. Stakeholders must monitor pending legislative amendments addressing flavor bans and taxation restructuring, as these policy signals will determine which product formats and price tiers retain commercial viability in the Philippine market.
Market Dynamics
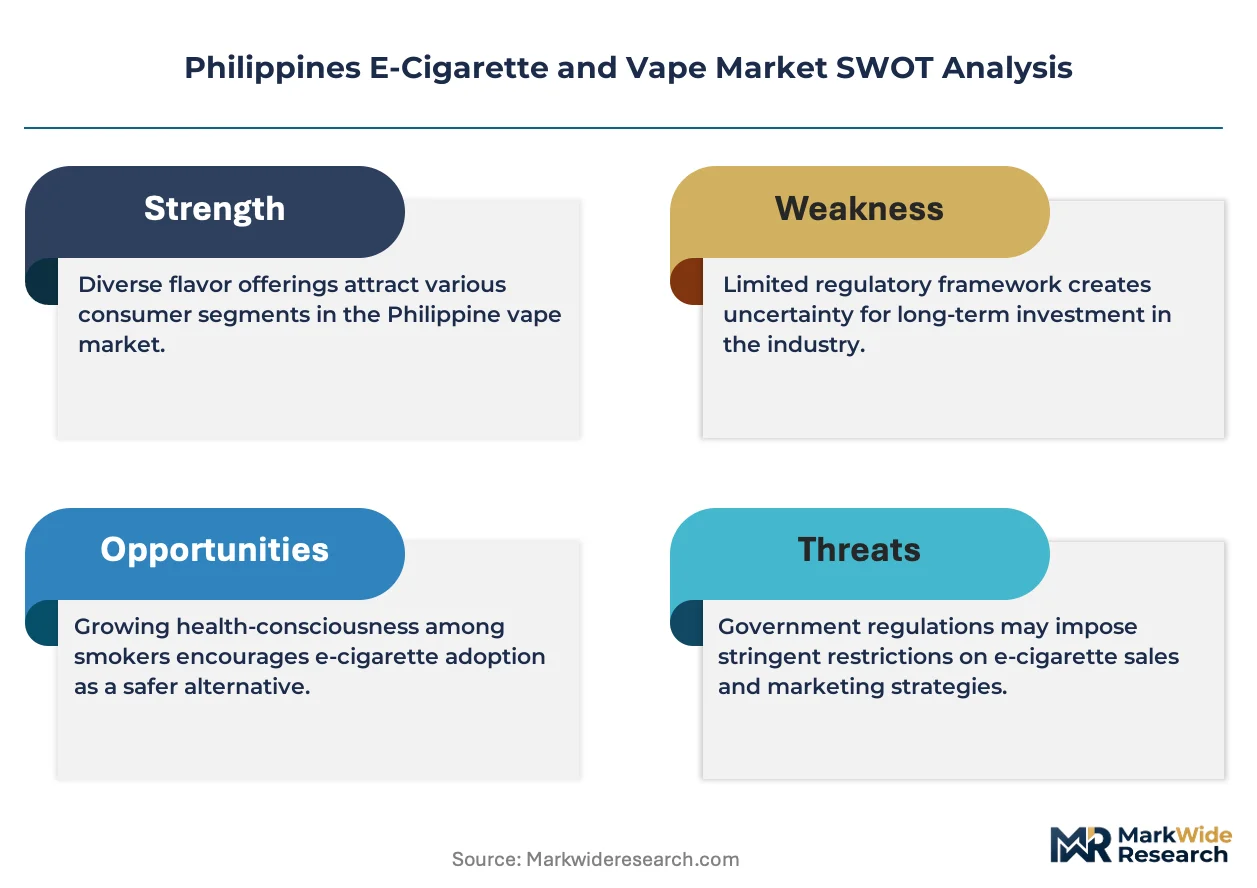
The Philippine Food and Drug Administration's escalating registration mandates for vapor products are compressing product introduction timelines and elevating compliance spend for all market participants.
Growth Catalysts
- Adult smoker transition:Combustible tobacco users in Metro Manila and CALABARZON provinces are converting to reduced-harm alternatives at measurable velocity.
- Republic Act No. 11900:The Vaporized Nicotine and Non-Nicotine Products Regulation Act creates legal clarity that enables licensed retail channel expansion.
- Disposable format accessibility:Minimal maintenance requirements and low trial barriers are accelerating first-time adoption among urban young adults.
Market Restraints
- Flavor restriction uncertainty:Pending legislative amendments threaten commercial viability of flavored e-liquid portfolios.
- Ingredient disclosure burdens:Philippine Food and Drug Administration mandates require extensive toxicological documentation that extends time-to-market.
- Taxation restructuring risk:Proposed excise duty modifications could compress margin pools across all price tiers.
Strategic Opportunities
- Visayas and Mindanao penetration:Provincial markets outside Luzon remain underserved by licensed specialty retail networks.
- Pod system recurring revenue:Cartridge replenishment models offer superior lifetime value capture versus disposable formats.
- Online channel infrastructure:Direct-to-consumer platforms are displacing traditional convenience store distribution among digital-native demographics.
Industry Challenges
- Regulatory documentation expertise:Shortage of professionals fluent in Philippine Food and Drug Administration vapor product registration protocols is elongating compliance timelines.
- Supply chain reconfiguration:Import licensing requirements are forcing distributors to rebuild logistics networks around approved entry points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines E-Cigarette and Vape Market |
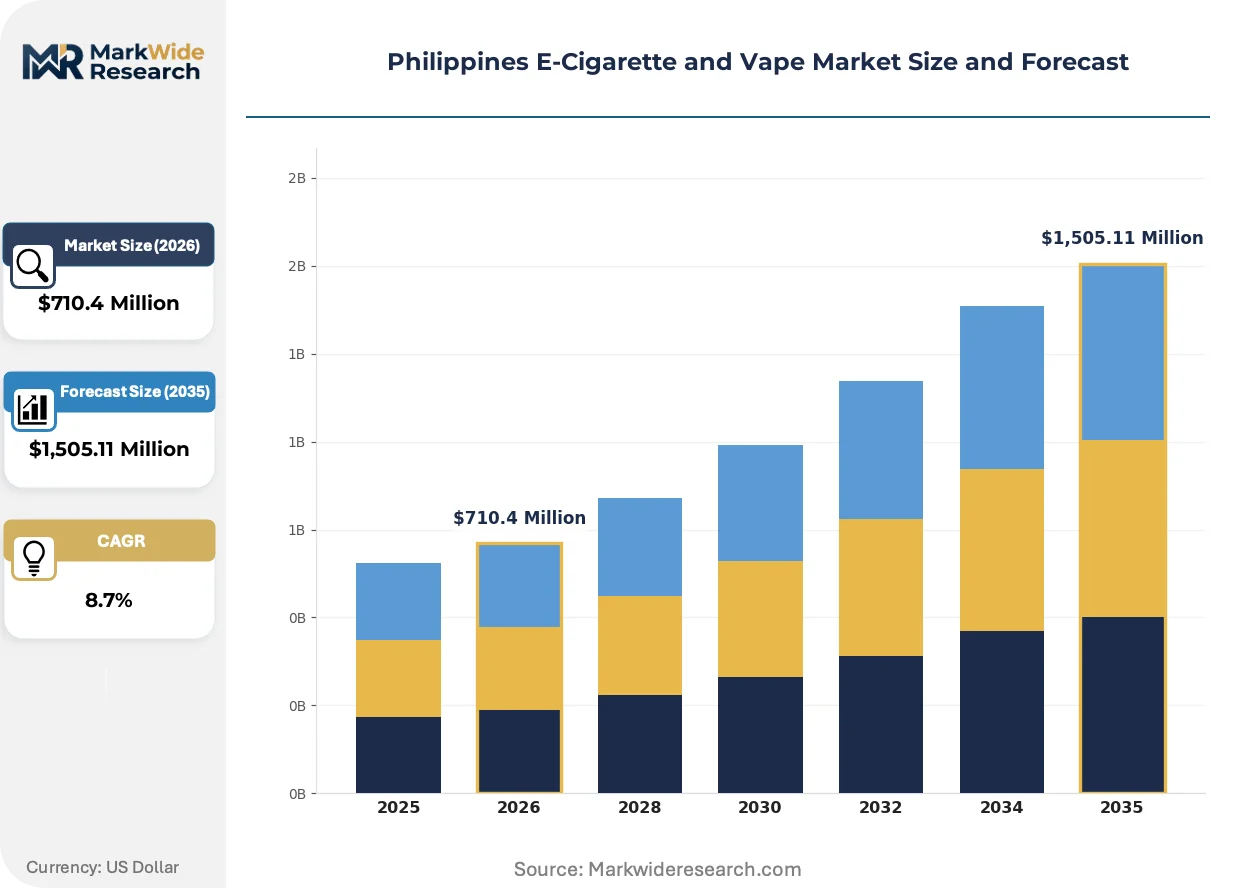
| Market Size in 2026 | $710.4 Million |
| Market Size in 2035 | $1,505.11 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pod Systems, Vape Mods, E-Liquids, Disposable Vapes Delivery Mode: Online Retail, Specialty Stores, Pharmacies, Convenience Stores Customer Type: Adult Smokers, Former Smokers, Young Adults, New Users Price Tier: Premium, Mid-Range, Budget, Value Packs |
| Companies Covered | Altria Group Inc., RELX International Enterprise HK Limited, Philip Morris International Inc., Geekvape, Voopoo, British American Tobacco plc, Imperial Brands plc, Juul Labs, Inc., Japan Tobacco Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines E-Cigarette and Vape Market Trends and Innovations
Product format evolution and channel restructuring are actively reshaping competitive positioning in the Philippine vapor market, with technology and regulatory forces operating in parallel.
Ceramic coil atomization is electrifying flavor delivery consistency in premium pod systems. Urban professional smokers are adopting these devices at accelerating rates. This technology is compressing the performance gap between rechargeable and disposable formats.
Republic Act No. 11900's age-verification mandates are restructuring retail access protocols. Licensed specialty stores must deploy biometric or ID-scanning infrastructure. Metro Manila vape shops are responding by consolidating into mall-based locations with standardized compliance systems.
Specialty store foot traffic is fragmenting toward hands-on education and after-sales support. Convenience stores are losing share to licensed vape retailers that offer coil replacement and troubleshooting services. This shift is most visible in Quezon City and Cebu metropolitan clusters.
Philippines E-Cigarette and Vape Market Segmentation
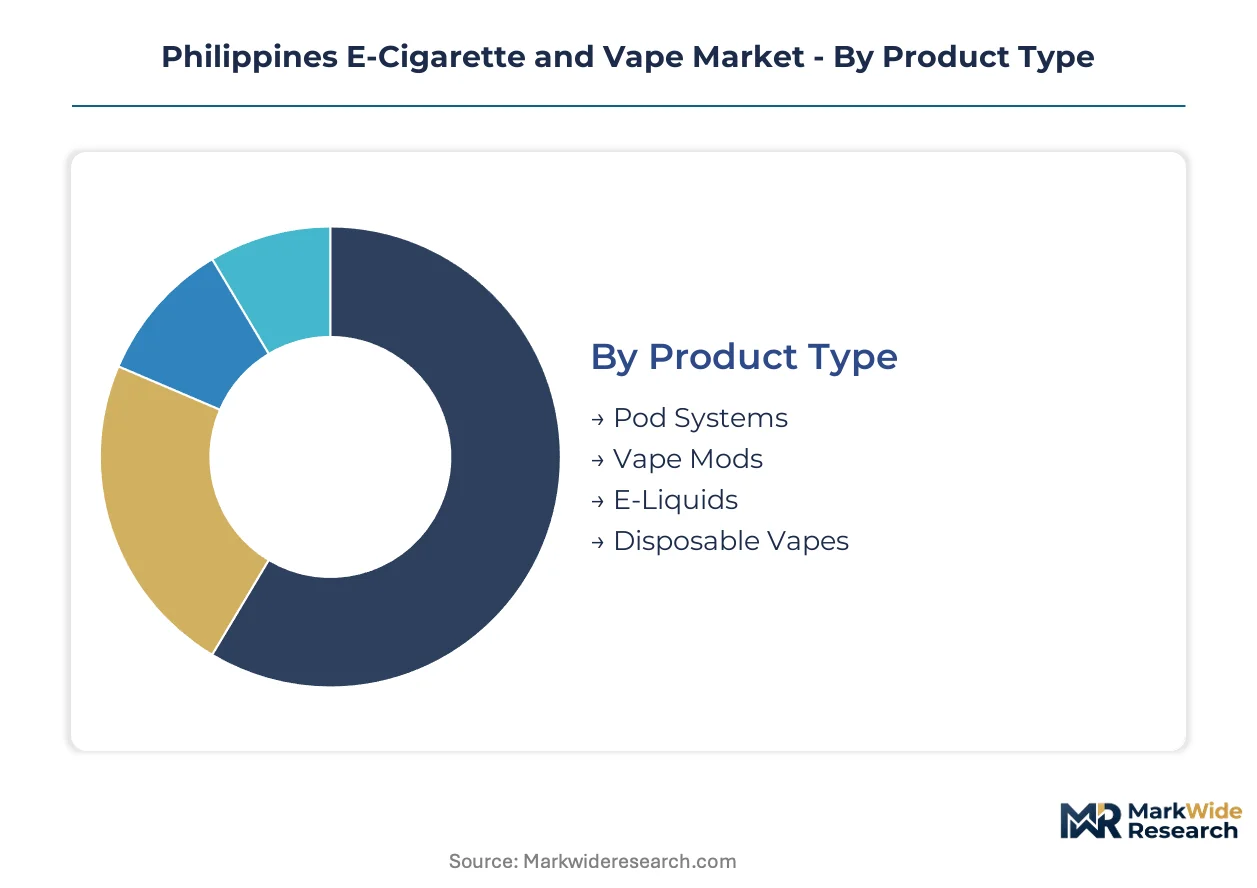
Philippine vapor product segmentation reveals distinct capital requirements and margin profiles across hardware formats, distribution channels, and consumer cohorts. Regulatory compliance under Republic Act No. 11900 intensifies differentiation between licensed specialty operators and informal retail networks. Understanding segment-specific investment thresholds enables stakeholders to allocate resources toward formats with sustainable competitive moats.
Product Type:
Disposable vapes demand minimal manufacturing capital but compress lifetime value capture, while pod systems require higher upfront R&D spend for cartridge-platform development.
- Pod Systems:Rechargeable devices with proprietary or universal cartridge interfaces generate recurring revenue through e-liquid replenishment. Metro Manila adult smokers favor ceramic coil variants for flavor consistency, though FDA registration timelines delay new model launches.
- Disposable Vapes:Single-use devices with integrated batteries and pre-filled e-liquid reservoirs dominate trial-phase adoption among young adults in Quezon City and Cebu. Low price points accelerate volume, yet environmental disposal regulations threaten format longevity.
- Vape Mods:High-wattage customizable hardware targets enthusiast segments with coil-building capabilities and variable power settings.
- E-Liquids:Refill solutions span freebase nicotine and nicotine salt formulations, with flavor portfolios facing pending legislative restriction risks.
Pod systems absorb the bulk of installed manufacturing capacity; disposable vapes are expanding most quickly among first-time adopters.
Delivery Mode:
Channel selection determines compliance infrastructure costs, with licensed specialty stores bearing biometric verification investments that convenience channels avoid.
- Specialty Stores:Licensed vape retailers in Metro Manila malls deploy ID-scanning systems mandated by Republic Act No. 11900 age-verification protocols. Hands-on coil replacement and troubleshooting services sustain premium positioning against mass-market alternatives.
- Online Retail:Direct-to-consumer platforms capture urban young adults through discrete purchasing and subscription cartridge replenishment. Philippine FDA product registration requirements complicate cross-border e-commerce fulfillment.
- Convenience Stores:Traditional tobacco retail networks lose share to licensed channels but retain accessibility in CALABARZON provinces with limited specialty store penetration.
- Pharmacies:Healthcare-adjacent positioning appeals to former smokers seeking smoking cessation credibility, though regulatory ambiguity constrains product assortment.
Specialty stores command the highest compliance capital allocation; online retail channels demonstrate steepest expansion trajectory among digital-native demographics.
Customer Type:
Customer acquisition economics vary sharply between combustible tobacco converts and nicotine-naive entrants, with the former offering superior retention and lower education costs.
- Adult Smokers:Combustible tobacco users transitioning to reduced-harm alternatives constitute the core revenue base in Metro Manila and surrounding provinces. Measurable switching velocity supports pod system investments with higher customer lifetime value.
- Former Smokers:Abstinent individuals maintaining nicotine consumption through vapor products demonstrate platform loyalty but face attrition from complete cessation efforts.
- Young Adults:Urban demographic segments aged 18-30 drive disposable format demand through social usage occasions and flavor experimentation.
- New Users:Nicotine-naive entrants without prior tobacco exposure present regulatory scrutiny risks and uncertain long-term retention profiles.
Adult smokers represent the most capital-efficient target segment; young adults are gaining share fastest among emerging customer cohorts.
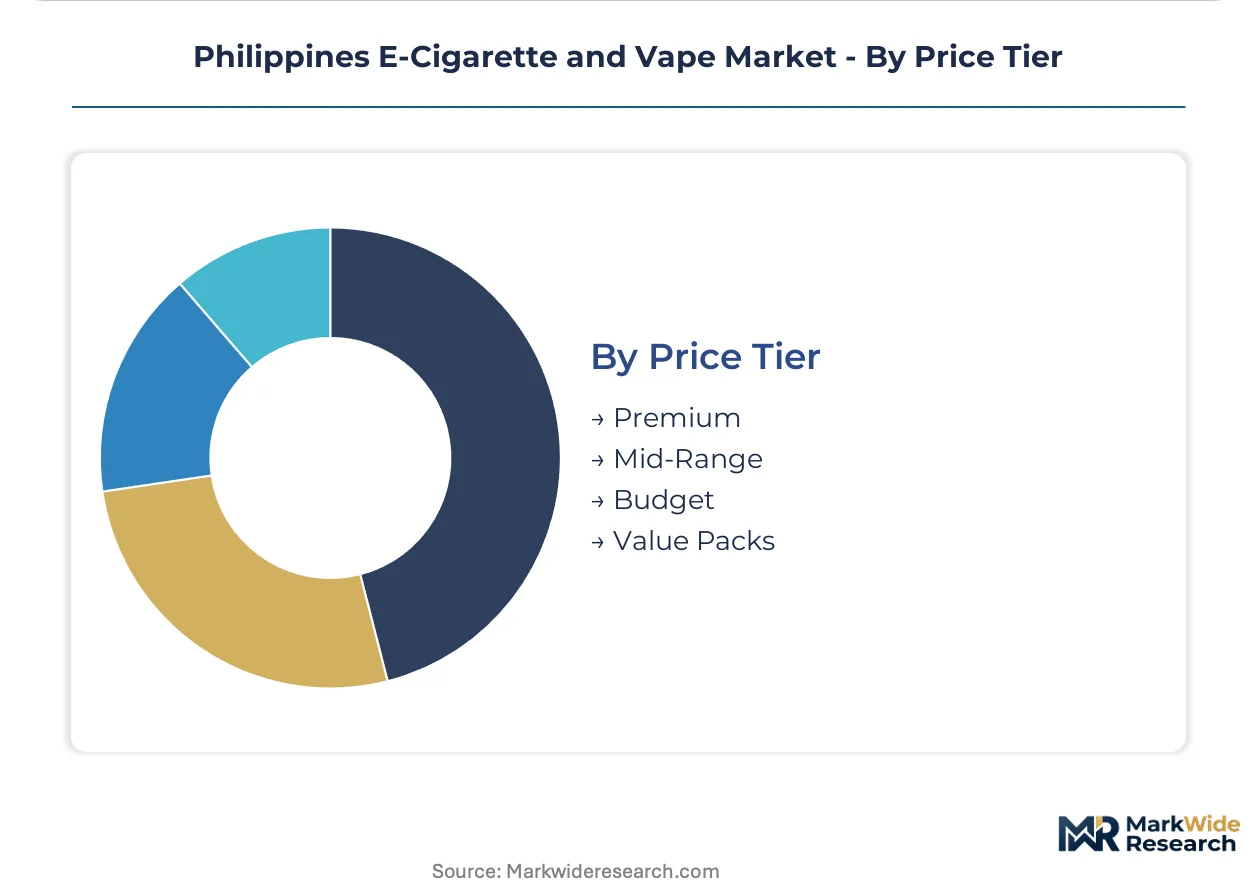
Price Tier:
Pricing stratification aligns with distribution channel economics, with premium tiers subsidizing specialty store compliance costs and budget segments competing on convenience store turnover velocity.
- Premium:Ceramic coil devices and imported e-liquid portfolios target Metro Manila professionals through mall-based specialty retailers. Quality certification programs and extended warranties justify price positioning.
- Mid-Range:Rechargeable pod systems with domestic assembly balance performance accessibility against recurring cartridge affordability for CALABARZON working smokers.
- Budget:Entry-level disposables and basic pod configurations compete on absolute price point for price-sensitive trial users.
- Value Packs:Multi-unit bundling and subscription discounts reduce per-use costs for high-volume consumers with established brand preferences.
Mid-range tiers capture the broadest manufacturing scale; premium segments demonstrate the steepest margin expansion trajectory as ceramic coil adoption accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metro Manila concentrates the bulk of Philippine vapor product demand, with CALABARZON provinces forming the secondary consumption cluster. Adult smoker transition rates in these areas outpace provincial markets by measurable margins. Regulatory enforcement intensity varies sharply across the archipelago's three main island groups.
Metro Manila
Licensed specialty vape retailers in Quezon City and Makati deploy biometric age-verification systems mandated by Republic Act No. 11900. The Philippine Food and Drug Administration maintains its headquarters here, accelerating product registration processing for distributors with established compliance teams. Mall-based consolidation is displacing street-level vape shops as operators seek standardized security infrastructure.
CALABARZON
Working-class adult smokers in Cavite and Laguna provinces drive mid-range pod system adoption through factory-adjacent retail networks. The Department of Trade and Industry regional offices enforce packaging and labeling standards with escalating inspection frequency. Batangas City anchors the southern Luzon distribution corridor with bonded warehousing facilities serving importers.
Central Visayas
Cebu City's metropolitan cluster sustains the strongest specialty store penetration outside Luzon, with young adult consumers favoring disposable formats for social usage occasions. Local government units here experiment with municipal licensing requirements beyond national mandates. Mandaue City hosts emerging logistics hubs for inter-island product movement.
Davao Region
Mindanao's economic capital shows accelerating combustible tobacco switching velocity among urban professional demographics. The Philippine Food and Drug Administration's southern field office maintains stricter documentary requirements for product registration submissions. Davao City's retail landscape remains fragmented between licensed operators and informal channel competitors.
Philippines E-Cigarette and Vape Market Competitive Landscape
Chinese manufacturers anchor the hardware supply tier; multinational tobacco conglomerates hold the branded distribution tier. The Philippine market structure concentrates around five to seven entities with FDA registration certificates and established retail licensing relationships. Three strategic archetypes dominate: tobacco incumbents leveraging heated-tobacco infrastructure, dedicated vape specialists with quality certification programs, and disposable-format pure-plays competing on price-accessibility. Capacity expansion through licensed retail footprint growth and portfolio diversification across nicotine salt and freebase formulations represent the dominant competitive moves.
Within the tobacco incumbent tier, Philip Morris International and British American Tobacco occupy positions defined by dual-track investments in both next-generation nicotine delivery and traditional vapor hardware. Among dedicated vape specialists, RELX International exemplifies the quality-certification archetype through specialty store partnerships. Altria Group sits within the transitional positioning segment, navigating between combustible decline and vapor opportunity.
| Leading Market Players |
|---|
| Altria Group Inc. |
| RELX International Enterprise HK Limited |
| Philip Morris International Inc. |
| Geekvape |
| Voopoo |
| British American Tobacco plc |
| Imperial Brands plc |
| Juul Labs, Inc. |
| Japan Tobacco Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned Chinese manufacturing clusters anchor hardware supply, translating concentrated production control into asymmetric pricing power over Philippine distributors navigating Republic Act No. 11900 compliance costs. This ownership pattern compresses margin pools for importers while elevating procurement leverage for integrated multinationals with direct factory relationships.
Pricing Analysis
Short lead-time premiums dominate procurement negotiations, with spot inventory from Shenzhen warehouses commanding 15-25% markups over contract-scheduled shipments. Three-tier pricing structure across premium, standard, and economy levels reflects ceramic coil certification grade and FDA registration status. Pricing pressure stems from pending excise duty restructuring threatening budget-tier viability. Adult smokers in Metro Manila demonstrate lowest price sensitivity, while young adult trial users in Cebu concentrate in economy disposables.
Supply Chain Analysis
Freight cost volatility from China-Philippine maritime lanes is reshaping inventory holding strategies among Batangas bonded warehouse operators. Hardware supply concentrates in Guangdong and Shenzhen manufacturing zones, with lithium-ion battery cells sourcing from South Korean and Japanese producers. Single-source vulnerability runs through ceramic coil substrate suppliers. Distribution runs through licensed specialty retailers with biometric verification infrastructure, displacing traditional convenience store networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as players pursue captive e-liquid manufacturing to secure flavor formulation control ahead of pending legislative restrictions. Upstream integration into cartridge-platform R&D represents the dominant competitive lever.
For Market Incumbents: Lock in ceramic coil supply agreements with Shenzhen manufacturers to defend premium positioning against disposable-format pure-plays. Secure FDA registration certificates for next-generation pod systems before ingredient disclosure mandates tighten. Channel control through mall-based specialty retail consolidation neutralizes informal competitor encroachment in Metro Manila.
For New Entrants and Emerging Players: Ceramic coil technology-first wedges open penetration paths among Metro Manila professionals dissatisfied with inconsistent flavor delivery in legacy devices. Visayas specialty store networks remain the most penetrable geography, with Cebu City's young adult demographic showing disposable-format trial velocity unmatched by licensed retail coverage. Direct-to-consumer subscription models bypass incumbent distributor relationships.
For Investors and Strategic Acquirers: Distressed-cycle entries favor FDA-registered mid-cap specialists with compliant retail licensing in CALABARZON provinces amid regulatory documentation bottlenecks. Five-to-ten-year viability hinges on flavor portfolio endurance under legislative amendment scenarios. Monitor Philippine Food and Drug Administration registration queue velocity as inflection indicator for competitive moat durability.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Registration Acceleration | Compresses time-to-market for ceramic coil pod systems ahead of flavor restriction implementation. |
| Specialty Store Licensing Expansion | Extends compliant retail footprint into Visayas and Mindanao provinces with biometric verification infrastructure. |
| Ceramic Coil Technology Licensing | Secures flavor consistency IP differentiation against commodity disposable competitors in Metro Manila. |
| Backward Integration into E-Liquid Manufacturing | Captures margin pools and insulates flavor formulation capabilities from supply disruption risks. |
| Direct-to-Consumer Platform Launch | Displaces traditional convenience store distribution among digital-native young adult demographics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving vape retail operators, FDA compliance consultants, e-liquid manufacturing executives, and logistics specialists at Batangas port facilities. Philippine Food and Drug Administration product registration databases, Department of Trade and Industry enforcement bulletins, Bureau of Customs import manifests, and industry association membership directories supplied quantitative foundations. Bottom-up channel volume estimates triangulated against top-down consumer expenditure benchmarks.
Granularity-level modeling operated at product-type, delivery-mode, customer-cohort, and regional-cluster dimensions across the analysis window. CAGRs derived from segment-level growth trajectory extrapolation, with adult smoker transition rates and disposable-format adoption curves as primary demand-side inputs. Regulatory timeline assumptions incorporated pending legislative amendment probability weightings.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated flavor ban implementation or excise duty restructuring scenarios. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tobacco Products
GCC E-Cigarette Market
Tobacco Products
Handmade Cigars Market
Tobacco Products
Cigarettes Filter Market
Tobacco Products
Flavored Cigar Market
Tobacco Products
US E-Cigarette and Vape Market
Tobacco Products
Latin America E-Cigarette Market
Tobacco Products
Europe Cigarette Vending Machine Market
Tobacco Products
Europe Cigarette Market
Tobacco Products
E-Cigarette and Vape Market
Tobacco Products
Electronic Cigarette Atomizer Market
Tobacco Products
Cigar Tubes Market
Tobacco Products
Middle East and Africa E-Cigarettes Market
Tobacco Products
Premium Tobacco Products Market
Tobacco Products
Asia-Pacific E Cigarettes Market
Tobacco Products
Roll-Your-Own Tobacco Products Market
Tobacco Products
E-Cigarette and Vaping Market