
 5G Equipment Market | 2026-2036
5G Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
5G Equipment Market Analysis
Buyer concentration among telecom operators is hardening as carriers consolidate procurement budgets around fewer national-scale vendors. Huawei Technologies Co., Ltd. leverages its integrated chipset-to-antenna portfolio to sustain pricing leverage in markets where geopolitical restrictions do not apply. Telefonaktiebolaget LM Ericsson anchors its position through deep operator relationships in Western Europe and North America, while Nokia Corporation competes on Open RAN interoperability credentials to differentiate against vertically integrated rivals.
5G equipment encompasses radio access network infrastructure, core network elements, and transport systems operating across sub-6 GHz and millimeter-wave spectrum bands with latency targets below one millisecond. This infrastructure enables enhanced mobile broadband, ultra-reliable low-latency communications, and massive machine-type connectivity for industrial automation and autonomous systems. Small cells are capturing disproportionate capital allocation as dense urban deployments outpace macro cell additions in mature markets. Massive MIMO arrays dominate base station shipments by volume, though beamforming subsystems command premium pricing due to active antenna integration complexity. Cloud RAN architectures are displacing traditional distributed baseband configurations where fiber fronthaul density permits centralized processing.
The FCC in the United States, ETSI in Europe, and MIIT in China each enforce distinct spectrum allocation frameworks and equipment certification regimes that fragment vendor compliance obligations across major economies. REACH and RoHS directives in Europe restrict hazardous substance use in radio hardware, while the EU AI Act introduces algorithmic transparency requirements for network automation functions. Stakeholders must monitor evolving Open RAN security standards and national subsidy programs that tilt procurement toward domestic suppliers.
Market Dynamics
Radio access network disaggregation is compressing vendor margins while fragmenting procurement across specialized component suppliers, fundamentally altering how carriers evaluate total cost of ownership for infrastructure deployments.
Growth Catalysts
- Open RAN Mandates:Regulators in Germany, Japan, and India now require interoperability certifications that break incumbent lock-in. This forces multi-vendor sourcing and accelerates qualification timelines for specialized radio unit suppliers.
- Industrial Automation:Manufacturing facilities in South Korea and Germany are deploying private 5G networks for robotic coordination. These deployments demand ultra-reliable low-latency configurations that standard public infrastructure cannot satisfy.
- Spectrum Auction Velocity:India's 2022 mid-band allocation and Brazil's 2021 3.5 GHz sale unlocked capital commitments from carriers previously constrained by licensing uncertainty.
Market Restraints
- Gallium Nitride Supply Concentration:Power amplifier substrate fabrication concentrates among Japanese and Chinese foundries. Geopolitical friction threatens input access for European and North American base station manufacturers.
- Millimeter-Wave Propagation Physics:Signal attenuation through building materials limits indoor penetration. This technical constraint forces expensive dense small cell overlays in urban cores where spectrum licenses command premium valuations.
- REACH Substance Restrictions:European ECHA regulations on flame retardants and heavy metals in printed circuit boards extend certification timelines and disqualify legacy component suppliers lacking reformulation capabilities.
Strategic Opportunities
- Rural Indonesia and Philippines:Archipelago geography and limited fiber backhaul create demand for satellite-integrated 5G fixed wireless solutions. Vendors with non-terrestrial network capabilities can establish early positioning before terrestrial infrastructure matures.
- Network-as-a-Service Models:Hyperscale cloud providers are entering managed private network contracts. This channel innovation allows equipment vendors to bypass direct carrier procurement and capture recurring revenue streams.
- EU AI Act Compliance:Automated network optimization functions now face algorithmic transparency requirements. Vendors with explainable AI architectures gain preferential positioning in European public infrastructure tenders.
Industry Challenges
- Beamforming Algorithm Talent Scarcity:Active antenna systems require specialized signal processing expertise concentrated among semiconductor designers. Carriers and vendors compete for limited pools of phased array engineers.
- Multi-Generational Integration Complexity:5G non-standalone deployments must interoperate with existing 4G core elements. This operational burden extends commissioning timelines and strains carrier technical integration teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Equipment Market |
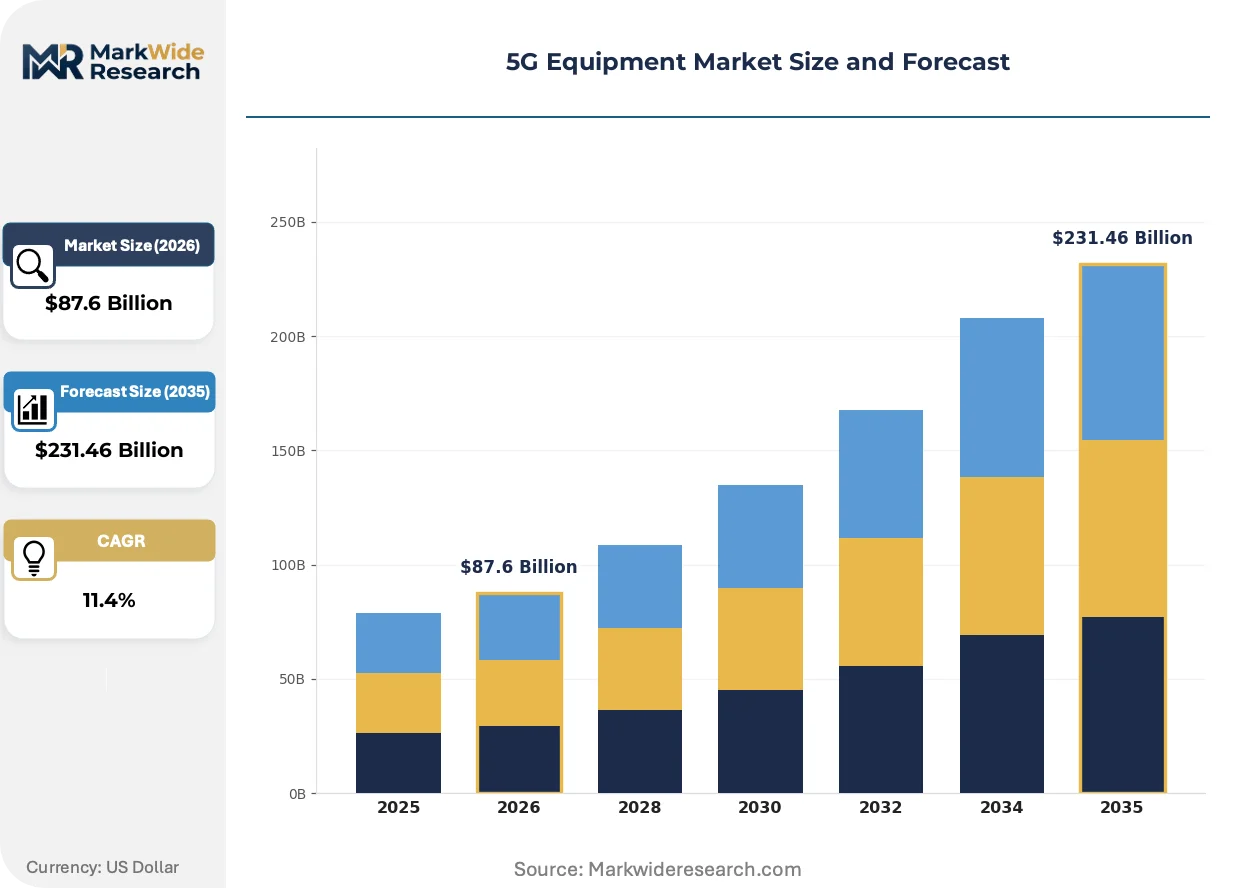
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antennas, Routers, Small Cells, Macro Cells Technology: Massive MIMO, Beamforming, Cloud RAN, Software-Defined Networking End User: Telecom Operators, Enterprises, Government, OEMs Installation: On-Premises, Cloud-Based, Hybrid, Distributed |
| Companies Covered | Huawei Technologies Co., Ltd., Telefonaktiebolaget LM Ericsson, Nokia Corporation, Samsung Electronics Co., Ltd., ZTE Corporation, Cisco Systems, Inc., Qualcomm Technologies, Inc., NEC Corporation, Fujitsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Equipment Market Emerging Trajectories
Intelligent network automation and spectrum-efficient architectures are redefining infrastructure economics. Three developments are compressing deployment timelines while elevating performance requirements.
Intelligent Reflecting Surfaces are programmable metamaterial panels that manipulate signal propagation without active amplification. Telecom operators in urban Japan and the United Arab Emirates are piloting these installations for coverage extension in dense corridors. The technology is electrifying base station economics by reducing transmit power requirements and enabling simpler radio unit designs.
The EU AI Act introduces mandatory documentation for machine learning models governing network slicing and traffic prioritization. Equipment vendors must now maintain algorithmic audit trails and bias assessment protocols. European carriers are responding by inserting compliance clauses into procurement specifications that disqualify black-box automation systems.
Consolidated national-scale procurement is displacing regional carrier purchasing autonomy. Verizon, Deutsche Telekom, and Reliance Jio now centralize infrastructure decisions at headquarters level, compressing vendor negotiation cycles. This concentration is most visible in India's urban corridor deployments where single-source national agreements have replaced circle-level contracting.
5G Equipment Market Segmentation
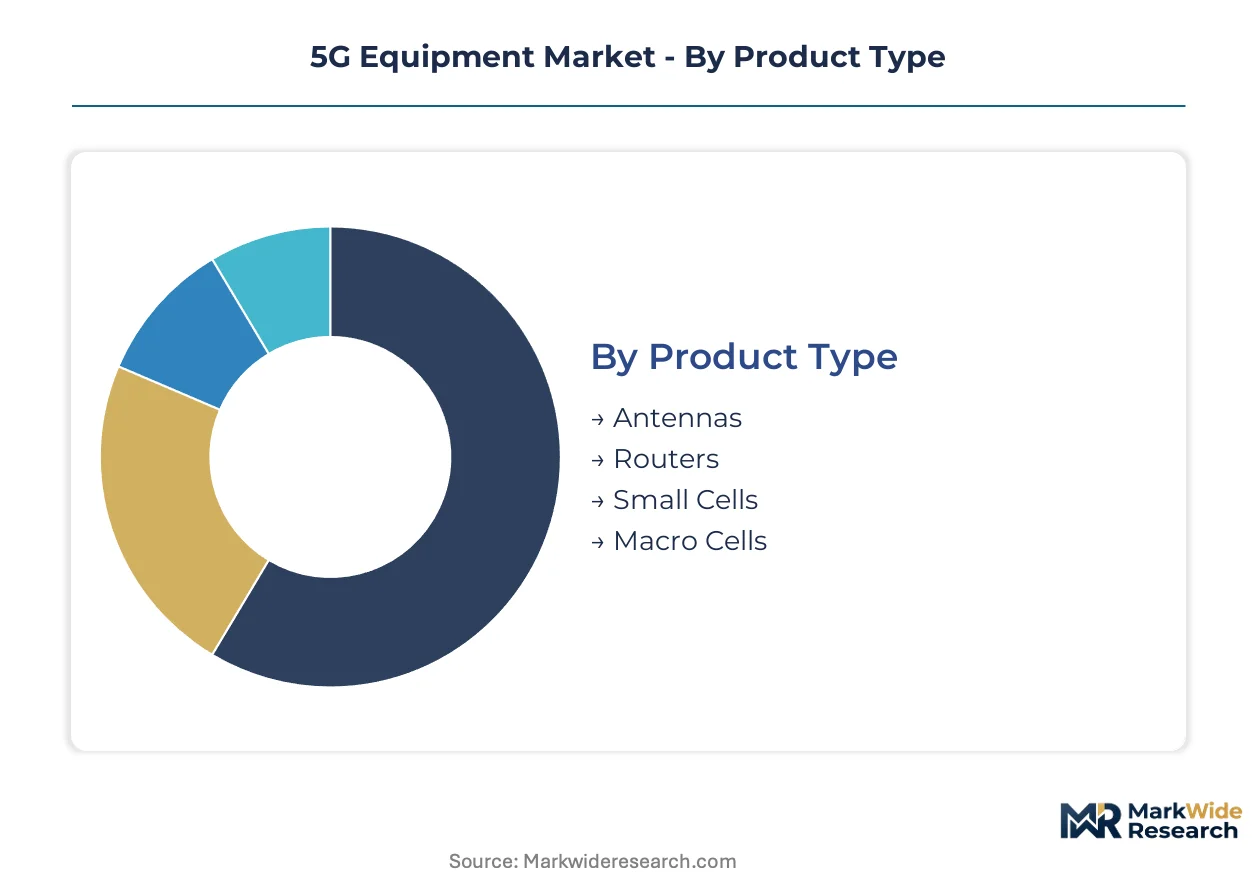
5G equipment segmentation reveals divergent upgrade cycles across infrastructure layers, with radio access hardware demanding more frequent refresh than core network elements. Understanding these replacement rhythms helps vendors align R&D pipelines with carrier capital allocation patterns and anticipate procurement timing windows.
Product Type:
Upgrade cycles vary dramatically across physical infrastructure categories, with outdoor macro assets requiring decade-long depreciation schedules while indoor small cell deployments refresh every three to four years.
- Small Cells:Compact low-power base stations designed for dense urban coverage extension and indoor penetration. Demand concentrates in Seoul and Tokyo metropolitan corridors where building density frustrates macro signal propagation and zoning restrictions complicate tower siting.
- Macro Cells:High-power outdoor base stations serving wide geographic footprints through elevated antenna mounting. Carriers in India and Brazil prioritize these deployments where suburban sprawl and limited fiber backhaul favor fewer, more powerful radio sites over dense small cell grids.
- Antennas:Passive radiating elements and active antenna arrays converting electrical signals to electromagnetic waves. Indian tower companies drive volume through multi-tenant shared infrastructure mandates.
- Routers:Packet-forwarding equipment interconnecting radio access, core, and transport network segments. Enterprise private 5G deployments in German manufacturing zones accelerate edge routing demand.
Macro Cells sits at the top of the volume ranking, with Small Cells climbing the fastest.
Technology:
Technology selection follows a cost-tier logic, with premium active antenna systems commanding multiples over passive configurations and software-based architectures disrupting traditional hardware procurement.
- Massive MIMO:Antenna arrays incorporating 64+ radiating elements with independent signal paths for spatial multiplexing. South Korean operators deploy these aggressively in spectrum bands where beamforming gains justify hardware premiums.
- Beamforming:Signal processing techniques directing radiated energy toward specific user equipment rather than broadcasting omnidirectionally. Urban corridors in the United Arab Emirates and Saudi Arabia favor this technology for capacity-constrained millimeter-wave spectrum.
- Cloud RAN:Centralized baseband processing architectures virtualizing radio functions on commodity compute platforms. German operators lead adoption where fiber fronthaul density permits pooling gains.
- Software-Defined Networking:Control plane abstraction enabling programmable traffic engineering across multi-vendor transport infrastructure. Japanese carriers integrate SDN for network slicing automation in industrial IoT contracts.
Massive MIMO dominates current shipment volumes, though Cloud RAN is expanding most quickly among greenfield deployments.
End User:
Customer type segmentation tracks procurement autonomy, with national-scale telecom operators centralizing decisions while enterprise buyers fragment across vertical-specific requirements.
- Telecom Operators:Licensed spectrum holders building public infrastructure for consumer and business subscription services. Reliance Jio and Verizon anchor global demand through consolidated national procurement programs.
- Enterprises:Private network deployers serving confined industrial, logistics, or campus environments. Manufacturing facilities in Germany and South Korea drive this segment through robotic coordination requirements.
- Government:Public safety and defense agencies requiring hardened, sovereign-controlled communications infrastructure. India's defense corridors and Saudi smart city initiatives concentrate this demand.
- OEMs:Equipment manufacturers integrating 5G modules into vehicles, industrial machinery, and consumer devices. Automotive suppliers in Germany and Japan source embedded connectivity for autonomous system telemetry.
Telecom Operators maintain the volume lead, with Enterprises gaining share fastest as private network regulations mature.
Installation:
Deployment architecture selection hinges on fiber availability and latency requirements, with distributed models dominating where backhaul constraints prevent centralization.
- On-Premises:Equipment deployed at customer-owned facilities with dedicated physical infrastructure. German automotive plants and Japanese semiconductor fabs favor this model for deterministic latency control.
- Cloud-Based:Network functions hosted on hyperscaler or carrier cloud platforms with subscription economics. Indian urban corridors adopt this for rapid scaling without capital-intensive hardware procurement.
- Hybrid:Architectures combining edge processing for latency-sensitive workloads with cloud offload for batch analytics. South Korean smart factory deployments blend on-site radio units with centralized core management.
- Distributed:Disaggregated baseband and radio deployments minimizing fronthaul distance through geographic spreading. Brazilian operators favor this where fiber deployment lags behind spectrum licensing.
Distributed architectures lead current deployment volumes, with Cloud-Based models showing the steepest expansion trajectory where fiber infrastructure permits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's urban corridors concentrate deployment capital unlocked by spectrum auctions, while South Korean operators accelerate infrastructure buildouts with government-backed industrial automation mandates. Regulatory fragmentation across major economies shapes distinct vendor qualification requirements and compliance obligations.
United States
Verizon and AT&T consolidate procurement around national-scale vendors as the FCC enforces distinct spectrum allocation frameworks. The FCC's equipment certification regimes fragment compliance obligations for base station manufacturers. Dense urban deployments in New York and Los Angeles outpace macro cell additions, driving disproportionate capital allocation toward small cells.
Germany
Deutsche Telekom centralizes infrastructure decisions at headquarters level, compressing vendor negotiation cycles. The EU AI Act introduces algorithmic transparency requirements for network automation functions that disqualify black-box systems. Manufacturing facilities in Bavaria deploy private 5G networks for robotic coordination, demanding ultra-reliable low-latency configurations.
India
Reliance Jio anchors global demand through consolidated national procurement programs replacing circle-level contracting. TRAI spectrum auctions unlocked capital commitments from carriers previously constrained by licensing uncertainty. Urban corridors in Maharashtra and Karnataka concentrate demand where dense small cell overlays address millimeter-wave propagation constraints.
South Korea
SK Telecom and KT Corporation accelerate infrastructure buildouts with government-backed smart factory initiatives. METI-aligned industrial policy supports manufacturing facility deployments requiring deterministic latency control. The Seoul Capital Area and Busan-Ulsan corridor lead massive MIMO deployment in spectrum bands where beamforming gains justify hardware premiums.
Japan
NTT Docomo integrates software-defined networking for network slicing automation in industrial IoT contracts. METI spectrum frameworks favor interoperability certifications that break incumbent lock-in. Tokyo and Osaka metropolitan corridors pilot intelligent reflecting surfaces for coverage extension in dense urban environments.
5G Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure hardening around consolidated national-scale procurement. Buyer concentration among telecom operators intensifies as carriers reduce vendor lists to fewer qualified suppliers. Three archetypes dominate: vertically integrated chipset-to-antenna portfolios, Open RAN interoperability specialists, and cloud-native software vendors. Strategic moves center on multi-vendor sourcing partnerships and centralized baseband processing architectures.
Within the integrated portfolio tier, Huawei Technologies Co., Ltd. and Telefonaktiebolaget LM Ericsson occupy positions shaped by geopolitical market access rather than pure technical differentiation. Nokia Corporation exemplifies the interoperability-focused archetype competing on Open RAN credentials. These three companies represent distinct responses to regulatory fragmentation: China-based vertical integration, Sweden-based Western operator relationships, and Finland-based multi-vendor compatibility positioning.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Telefonaktiebolaget LM Ericsson |
| Nokia Corporation |
| Samsung Electronics Co., Ltd. |
| ZTE Corporation |
| Cisco Systems, Inc. |
| Qualcomm Technologies, Inc. |
| NEC Corporation |
| Fujitsu Ltd. |
| Others |
Supply Flow & Price Mechanics
Consolidated national-scale procurement by Reliance Jio and Verizon is forcing specialized radio unit suppliers to absorb volume discounts while maintaining GaN substrate access from Japanese foundries. This buyer concentration is reshaping contract structures toward multi-year framework agreements with escalating penalty clauses for supply disruption.
Pricing Analysis
Capacity additions in South Korea are reshaping price floors for massive MIMO arrays as domestic foundries expand GaN-on-SiC wafer output. Three-tier pricing structure across premium active antenna systems, standard passive configurations, and economy small cell units dominates procurement. Cost compression in the economy tier is intensifying because Indian tower companies enforce multi-tenant shared infrastructure mandates. Enterprise private network deployers in Germany exhibit the lowest price sensitivity, while Brazilian regional carriers facing fiber backhaul constraints represent the most price-pressured segment.
Supply Chain Analysis
Regional distribution centers in Singapore and Rotterdam anchor hub-and-spoke patterns for European and Asia-Pacific carrier fulfillment. Manufacturing concentrates in China, South Korea, and Taiwan for baseband silicon, radio frequency front-end modules, and antenna substrate materials. The ecosystem draws from gallium nitride wafers, high-frequency laminates, and precision machined housings as critical inputs. Single-source vulnerability around Japanese GaN foundries threatens input access for European base station manufacturers. Distribution runs through carrier-direct fulfillment for macro infrastructure and channel partners for enterprise small cell deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where premium beamforming subsystems and Open RAN interoperability certifications command widening valuation spreads over commodity radio units.
For Market Incumbents: To counter margin compression from disaggregated procurement, Telefonaktiebolaget LM Ericsson and Nokia Corporation should deepen captive supply of active antenna chipsets through backward integration into GaN foundry partnerships. Channel control over centralized baseband processing architectures in German fiber-dense corridors represents a secondary defensive lever against cloud-native software entrants. For New Entrants and Emerging Players: Explainable AI architectures for network automation compliance offer a technology-first wedge into European public infrastructure tenders governed by EU AI Act algorithmic transparency requirements. Rural Indonesia and Philippines present the most penetrable geography for satellite-integrated fixed wireless solutions before terrestrial infrastructure matures. Go-to-market execution should prioritize managed private network contracts with hyperscale cloud providers to bypass direct carrier procurement barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with Open RAN interoperability specialists possessing multi-vendor certification credentials and established relationships with Indian tower companies. Over a multi-year deployment window, acquisition targets should demonstrate defensible positioning in beamforming algorithm talent pools and active antenna integration capabilities. The signal to watch is TRAI spectrum auction velocity and subsequent capital commitment announcements from carriers previously constrained by licensing uncertainty.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Certification Investment | MIIT and ETSI interoperability mandates in China and Europe fragment vendor qualification requirements. |
| GaN Foundry Backward Integration | Japanese and Chinese substrate concentration threatens input access for European base station manufacturers. |
| Managed Private Network Partnership | Hyperscale cloud providers enable equipment vendors to bypass direct carrier procurement channels. |
| Explainable AI Architecture Development | EU AI Act compliance requirements disqualify black-box automation systems from European tenders. |
| Satellite-Integrated Fixed Wireless Launch | Archipelago geography in Indonesia and Philippines creates demand before terrestrial infrastructure matures. |
Methodological Framework
Bottom-up telecom operator procurement modeling reconciled against top-down semiconductor shipment tracking forms the analytical core of this study. Primary interviews with carrier network planning executives, Open RAN integration specialists, tower company procurement managers, and GaN foundry technical directors combined with secondary validation from FCC equipment authorization databases, ETSI standardization filings, TRAI spectrum auction records, and MIIT radio transmission equipment certifications. Triangulation across these sources ensures segmentation outputs align with observed capital allocation patterns.
Input-output matrices map radio access network infrastructure, core network elements, and transport systems against end-user deployment models across the projection horizon. Segmentation dimensions modeled include product type, technology architecture, end-user category, and installation topology. CAGRs were derived from carrier capex trajectory analysis and replacement cycle assumptions for macro versus small cell assets. Forecast inputs incorporate spectrum auction timing, fiber fronthaul density thresholds, and industrial automation mandate velocity from METI and German federal programs.
The model holds under sustained carrier consolidation and Open RAN regulatory momentum; deviation in gallium nitride supply disruption or geopolitical market access restrictions would shift volume and value outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Colombia Telecom Market
Telecommunications
Prepaid Communication Market
Telecommunications
Kuwait Telecom Market
Telecommunications
Czech Republic Telecom Market
Telecommunications
Virtual CPE (Vcpe) Market
Telecommunications
Digital Mobile Radio (DMR) Market
Telecommunications
Global B2B Telecommunication Market
Telecommunications
CDMA Mobile Phone Market
Telecommunications
Spain ICT Market
Telecommunications
India Optical Transport Network (OTN) Market
Telecommunications
LTE and LTE Advance Market
Telecommunications
Europe Mobile Virtual Network Operator (MVNO) Market
Telecommunications
GSM Mobile Phone Market
Telecommunications
Global Virtual PBX Market
Telecommunications
Malaysia Telecom Market
Telecommunications
Hungary ICT Market