
 Automated Feeding System Market | 2026-2036
Automated Feeding System Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Feeding System Market Analysis
Market Context
Smallholder cooperatives is collapsing as the dominant buyer archetype as large integrated livestock producers capture procurement volume. GEA Group Aktiengesellschaft leverages its dairy processing heritage to anchor robotic feeding lines across Northern European farm estates. DeLaval competes through embedded sensor networks that synchronize feeding with milk-yield data. Big Dutchman International GmbH dominates pig and poultry automation, extending its feeder controls into ruminant systems via channel partnerships.
Technical Definition and Segment Structure
An automated feeding system integrates mechanical conveyors, pneumatic distribution networks, and programmable logic controllers to deliver precise rations of forage, concentrate, or compound feed to livestock at scheduled intervals, typically achieving dispensing accuracy within one to two percent by weight. Gravimetric feeders command premium positioning because load-cell calibration supports pharmaceutical-grade traceability that food manufacturers now require. Continuous feeders lead volume in aquaculture applications where round-the-clock nutrient delivery sustains stock density, while batch feeders retain margin pools in research institutions running controlled dietary trials.
Regulatory Framework and Outlook
The EU Machinery Directive and F-Gas Regulation constrain motor specifications and refrigerant choices in feeder-mounted cooling systems, forcing redesign cycles among European suppliers. The EPA's Clean Water Act provisions in the United States shape manure-management integrations that automated feeders must accommodate. Stakeholders should monitor how carbon-accounting standards restructure contract terms between equipment financiers and livestock operators.
Market Dynamics
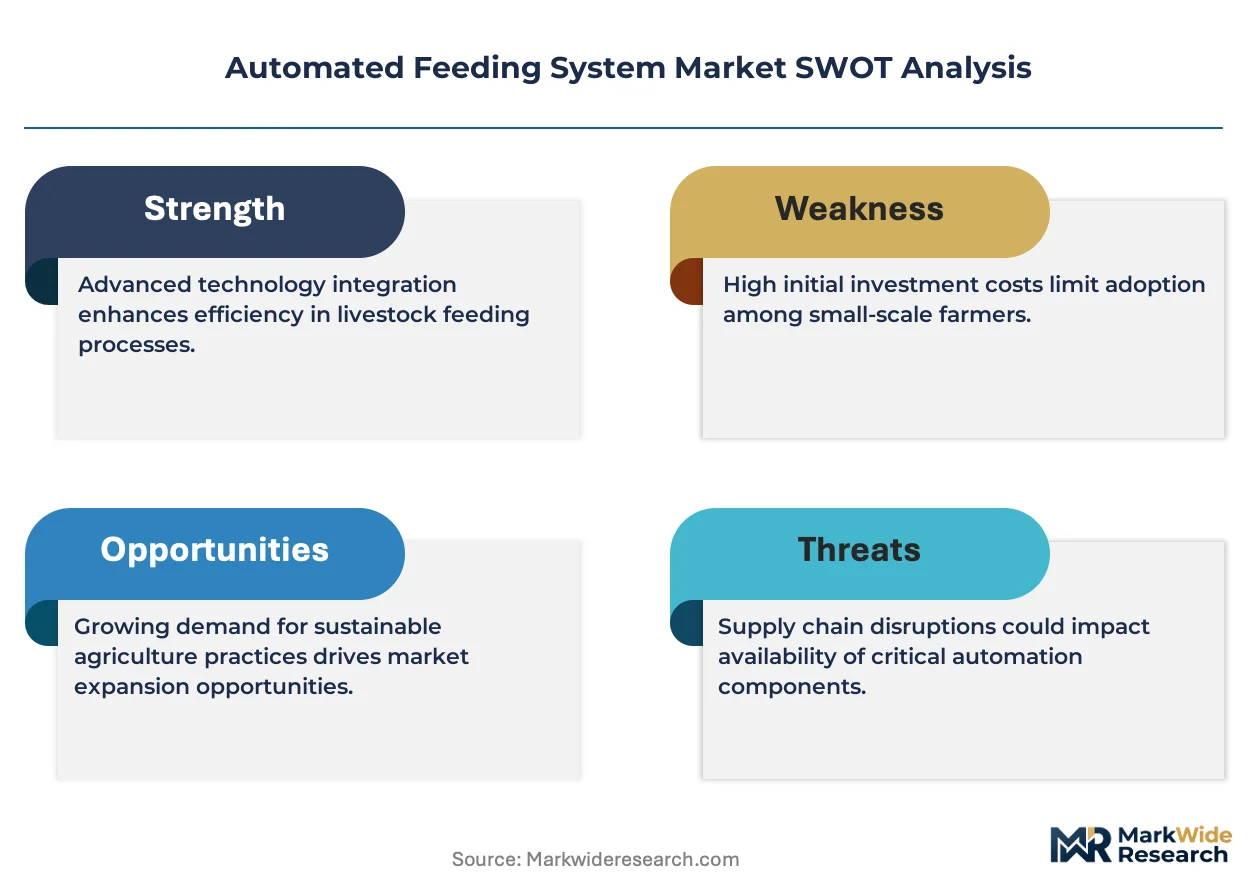
Farm consolidation across Northern Europe is compressing the buyer base into fewer, larger livestock estates that demand integrated feeding-to-milk-yield data architectures, forcing equipment suppliers to bundle hardware with predictive analytics subscriptions rather than sell standalone conveyors.
Growth Catalysts
- Labor Cost Escalation:Dutch dairy cooperatives are accelerating robotic feeding station procurement as agricultural wage floors rise under collective bargaining agreements, creating immediate replacement demand for manual feeding routines.
- F-Gas Regulation Motor Mandates:The EU Machinery Directive's tightened efficiency standards for on-farm equipment are compelling feeder manufacturers to redesign drivetrain architectures, opening upgrade cycles across Germany's Bavarian dairy belt.
- Pharmaceutical-Grade Traceability:Food manufacturers now require load-cell calibrated gravimetric feeders to satisfy supply chain audit protocols, pulling premium equipment into compound feed operations that previously used volumetric systems.
Market Restraints
- Stainless Steel Input Volatility:Feeder fabrication depends on 304-grade stainless for corrosion resistance in manure-heavy environments, exposing manufacturers to nickel price swings that compress margin pools on mid-tier equipment lines.
- Controller Chip Supply Concentration:Programmable logic controller supply chains concentrate in East Asian foundries, creating lead-time vulnerability for European feeder assemblers during semiconductor allocation cycles.
- CE Certification Friction:The EU Machinery Directive's evolving safety standards for autonomous on-farm robotics extend type-approval timelines, delaying product launches and freezing R&D amortization schedules.
Strategic Opportunities
- Carbon Accounting Integration:Emerging Scope 3 livestock emissions tracking standards in the Netherlands are creating demand for feeders that log ration composition data for automated carbon footprint calculations, enabling outcome-based equipment financing models.
- Aquaculture Continuous Feeding White Space:Round-the-clock nutrient delivery systems remain underpenetrated in Mediterranean sea bass and bream operations, where batch feeding still dominates high-density offshore cages.
- Sensor-to-Cloud Convergence:Combining embedded near-infrared spectroscopy with edge computing architectures allows real-time forage quality adjustment, opening subscription revenue streams in research institution dietary trial contracts.
Industry Challenges
- Mechatronics Talent Scarcity:Feeder manufacturers struggle to recruit control systems engineers capable of integrating pneumatic distribution networks with dairy herd management software, extending commissioning timelines on large farm estates.
- Legacy Barn Infrastructure Mismatch:Retrofitting robotic feeding lines into 1970s-era Dutch stall layouts requires custom conveyor routing that erodes standardization economies and complicates service parts forecasting.
Report Scope
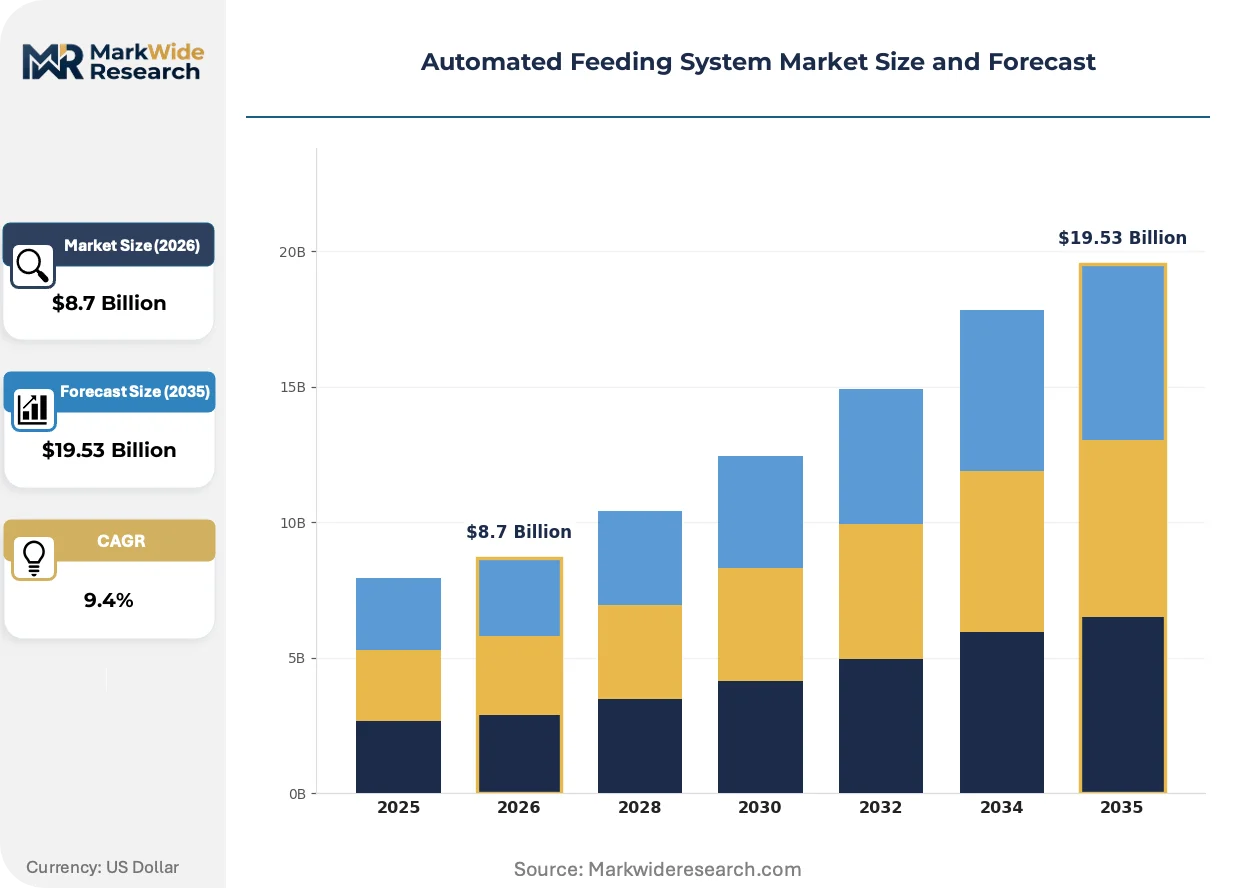
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Feeding System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Feeders, Continuous Feeders, Volumetric Feeders, Gravimetric Feeders Application: Agriculture, Aquaculture, Food Processing, Animal Husbandry End User: Farmers, Food Manufacturers, Livestock Producers, Research Institutions Technology: Mechanical, Pneumatic, Electrical, Hydraulic |
| Companies Covered | Tetra Laval International S.A., Trioliet B.V., GEA Group Aktiengesellschaft, Schauer Agrotronic GmbH, BouMatic, Lely Holding S.à r.l., Big Dutchman International GmbH, DAIRYMASTER, DeLaval, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Feeding System Market Emerging Trajectories
Feeding system architecture is pivoting from mechanical precision toward data-centric ration optimization, with hardware margins compressing as software-defined feeding protocols capture contract value. Three developments are restructuring competitive positioning.
Near-infrared spectroscopy is decomposing traditional forage testing workflows by embedding real-time dry-matter analysis directly into mixer wagons, allowing Danish dairy estates to adjust rations batch-by-batch rather than relying on weekly lab analysis. Large integrated producers in Jutland are adopting these sensor-integrated feeders at replacement cycle pace. This technology is decomposing the standalone nutrition consulting model, as equipment OEMs capture recurring advisory revenue through embedded analytics subscriptions.
REACH chemical authorization protocols are restricting lubricant formulations used in feeder-mounted bearings and gearboxes, forcing European suppliers to reformulate greases for food-contact compliance without sacrificing load-bearing capacity in cold barn environments. The regulation's substance evaluation timelines are compressing product development windows. German equipment manufacturers are responding by consolidating lubricant supplier relationships to secure pre-certified formulation pipelines.
Cooperative procurement desks are consolidating feeder purchasing decisions across multiple farm estates, replacing individual farm manager autonomy with centralized technical specification committees that demand standardized telemetry protocols. This buyer concentration is displacing regional equipment dealers who previously customized configurations farm-by-farm. The shift is most visible in the Netherlands, where FrieslandCampina-aligned cooperatives now issue collective tenders for robotic feeding infrastructure.
Automated Feeding System Market Segmentation
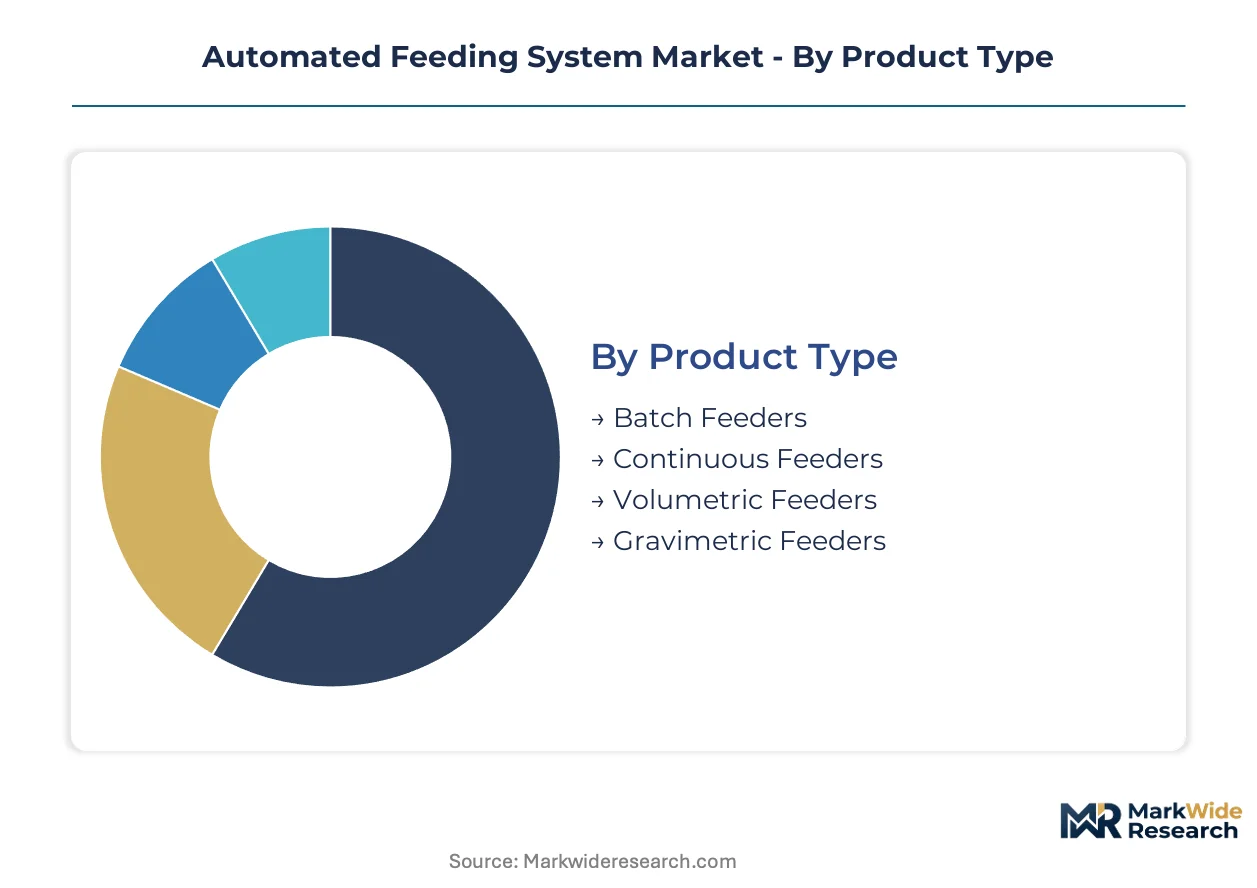
Automated feeding system architectures diverge sharply across product types and end-use contexts, with margin capture shifting from mechanical hardware toward data-integrated service bundles. Suppliers must align R&D allocation with where procurement authority is concentrating among consolidated livestock estates and institutional buyers.
Product Type:
Premium positioning clusters around gravimetric precision, while volume manufacturing concentrates on simpler mechanical systems serving cost-sensitive farm segments.
- Gravimetric Feeders:Load-cell calibration enables dispensing accuracy within one to two percent by weight, satisfying pharmaceutical-grade traceability mandates that compound feed manufacturers now enforce. Food manufacturers in Germany's Bavarian dairy belt specify gravimetric systems to satisfy supply chain audit protocols, pulling premium equipment into operations that previously relied on volumetric alternatives.
- Continuous Feeders:Round-the-clock nutrient delivery architectures sustain stock density in high-throughput aquaculture operations, particularly Mediterranean sea bass and bream cages where batch feeding creates growth-rate variability. Danish integrated producers are adopting sensor-integrated continuous systems at replacement cycle pace to synchronize feeding with real-time water quality data.
- Batch Feeders:Retain margin pools in research institutions running controlled dietary trials where precise interval feeding supports reproducible study conditions.
- Volumetric Feeders:Dominate smallholder farm procurement in price-sensitive segments where capital constraints override precision requirements.
Continuous feeders hold installed capacity in aquaculture. Gravimetric feeders are rotating up the share rankings in compound feed operations.
Application:
Revenue concentration tilts toward animal protein production, with food processing representing an emerging adjacency for precision dosing equipment.
- Aquaculture:Offshore cage operations in the Mediterranean and North Atlantic drive demand for corrosion-resistant feeding systems capable of withstanding salt spray and wave motion. Continuous feeding architectures here reduce labor exposure on exposed platforms while sustaining biomass growth rates through algorithmic nutrient delivery.
- Agriculture:Dairy farm cooperatives in the Netherlands anchor procurement volume as labor costs climb under collective bargaining agreements, accelerating robotic feeding station deployment across Northern European farm estates.
- Animal Husbandry:Pig and poultry automation extends feeder control architectures into ruminant systems through channel partnerships, consolidating equipment purchasing decisions across species.
- Food Processing:Ingredient dosing applications in bakery and confectionery operations adopt adapted livestock feeding technologies for precise additive delivery.
Agriculture retains the deepest installed base. Aquaculture is climbing the fastest as offshore cage densities intensify.
End User:
Buyer consolidation is compressing the customer base into fewer, larger procurement desks with standardized technical specifications.
- Livestock Producers:Large integrated estates in Jutland and the Netherlands now demand bundled hardware-with-analytics contracts rather than standalone conveyors, forcing equipment suppliers to embed predictive feeding optimization as a subscription service.
- Research Institutions:Controlled dietary trial contracts require programmable batch feeders with telemetry logging for reproducibility documentation, opening niche margin pools for specialized equipment manufacturers.
- Farmers:Smallholder cooperatives are losing procurement autonomy as centralized technical committees at cooperative desks issue collective tenders for robotic feeding infrastructure.
- Food Manufacturers:Compound feed operations specify gravimetric feeders to satisfy carbon-accounting traceability requirements emerging under Dutch Scope 3 livestock emissions standards.
Livestock producers command the largest procurement volume. Food manufacturers are rotating up the share rankings as traceability mandates tighten.
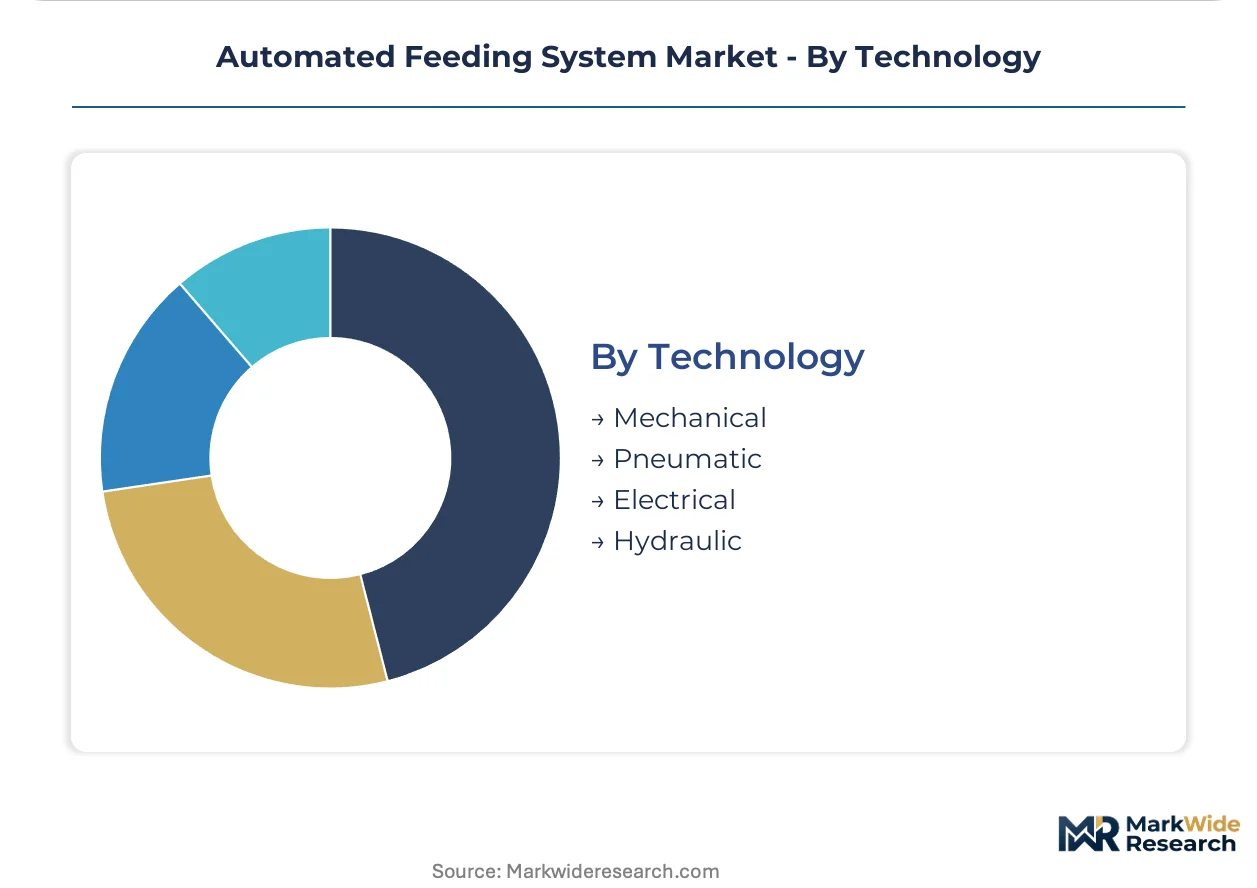
Technology:
Supply chain vulnerability concentrates in controller chip sourcing, with pneumatic and electrical architectures commanding premium positioning over mechanical alternatives.
- Electrical:Programmable logic controllers enable real-time ration adjustment through embedded sensor networks, though semiconductor allocation cycles in East Asian foundries create lead-time exposure for European feeder assemblers.
- Pneumatic:Distribution networks achieve precise flow control in large-scale dairy operations where mechanical conveyors would require excessive barn footprint, particularly in retrofitted 1970s-era Dutch stall layouts.
- Mechanical:Simpler conveyor architectures serve cost-constrained smallholder segments where capital recovery periods override precision requirements.
- Hydraulic:Heavy-load applications in industrial-scale feed mills where torque requirements exceed electrical motor specifications.
Electrical systems hold installed capacity. Pneumatic architectures are rotating up the share rankings in large estate consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment supply for automated feeding systems concentrates in Northern European engineering clusters where dairy automation heritage meets precision manufacturing capability. Regulatory pressure from Brussels on motor efficiency and refrigerant specifications is accelerating replacement cycles across multiple national markets simultaneously.
Germany
The EU Machinery Directive's tightened efficiency standards are compelling feeder manufacturers to redesign drivetrain architectures, opening upgrade cycles across the Bavarian dairy belt. Farm consolidation accelerates automation uptake as fewer, larger livestock estates demand integrated feeding-to-milk-yield data architectures. GEA Group Aktiengesellschaft anchors robotic feeding lines across Northern European farm estates from its engineering base.
Netherlands
Dutch dairy cooperatives are expanding procurement of robotic feeding stations as labor costs climb under collective bargaining agreements. Emerging Scope 3 livestock emissions tracking standards create demand for feeders that log ration composition data for automated carbon footprint calculations. FrieslandCampina-aligned cooperatives now issue collective tenders for robotic feeding infrastructure, displacing regional equipment dealers.
Denmark
Large integrated producers in Jutland are adopting sensor-integrated continuous feeding systems at replacement cycle pace to synchronize feeding with real-time water quality data. Danish estates adjust rations batch-by-batch through embedded near-infrared spectroscopy rather than weekly lab analysis. Equipment OEMs capture recurring advisory revenue through embedded analytics subscriptions.
United States
The EPA's Clean Water Act provisions shape manure-management integrations that automated feeders must accommodate across Midwestern dairy operations. Feedlot operators in the Corn Belt face nutrient discharge permitting that drives precision feeding adoption to reduce excess phosphorus output. Dairy processors specify gravimetric systems to satisfy supply chain audit protocols from downstream food manufacturers.
China
GB standards for agricultural mechanization are tightening performance specifications for imported feeding equipment, creating compliance friction for European suppliers. Pig and poultry automation extends feeder control architectures into ruminant systems through channel partnerships with domestic distributors. Yangtze River Delta livestock estates pilot robotic feeding infrastructure as labor migration to urban manufacturing constrains rural workforce availability.
Automated Feeding System Market Vendor Landscape
Concentration sits with diversified agricultural equipment conglomerates that leverage dairy processing heritage to anchor robotic feeding lines across Northern European farm estates. The competitive structure fragments between precision-engineered gravimetric specialists and volume manufacturers serving cost-sensitive smallholder segments. Three archetypes dominate: integrated dairy technology providers, pig and poultry automation specialists extending into ruminant systems, and sensor-integrated precision feeding platform builders. M&A activity targets embedded analytics capabilities, while strategic partnerships secure semiconductor supply for programmable logic controllers.
Among diversified European engineering groups, GEA Group Aktiengesellschaft represents the integrated dairy technology archetype, leveraging processing heritage into farm automation. Big Dutchman International GmbH exemplifies the cross-species automation specialist, with its GmbH structure signaling German engineering origins. DeLaval occupies a position within the sensor-integrated platform tier, competing through data synchronization capabilities rather than standalone mechanical hardware.
| Leading Market Players |
|---|
| Tetra Laval International S.A. |
| Trioliet B.V. |
| GEA Group Aktiengesellschaft |
| Schauer Agrotronic GmbH |
| BouMatic |
| Lely Holding S.à r.l. |
| Big Dutchman International GmbH |
| DAIRYMASTER |
| DeLaval |
| Others |
Supply Flow & Price Mechanics
CE marking requirements under the EU Machinery Directive gate both supplier qualification and price differentiation, forcing feeder manufacturers to absorb certification costs into premium-tier positioning while excluding uncertified competitors from compound feed procurement channels.
Pricing Analysis
The EU Machinery Directive dictates the pricing tier structure by mandating efficiency-graded motor specifications that stratify equipment into premium, standard, and economy levels. Price differentiation rests on CE certification grade and embedded sensor density, with pharmaceutical-grade gravimetric systems commanding substantial premiums over volumetric alternatives. Cost compression in mid-tier lines is intensifying because nickel price volatility in 304-grade stainless steel erodes fabrication margins. Smallholder cooperatives exhibit highest price sensitivity, while integrated livestock estates prioritize total-cost-of-ownership metrics over upfront capital expenditure.
Supply Chain Analysis
Controller chip inventory cycles extending sixteen to twenty-four months create lead-time vulnerability for European feeder assemblers sourcing programmable logic units. Supply concentrates in Taiwan, South Korea, and China for semiconductor components, while Germany and the Netherlands anchor mechanical fabrication clusters. Raw material dependencies center on 304-grade stainless steel, nickel alloys, and food-contact lubricants subject to REACH authorization protocols. Single-source vulnerability in East Asian foundries threatens production continuity during allocation cycles. Distribution runs through cooperative procurement desks consolidating multi-estate tenders in the Netherlands and Denmark.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Farm consolidation across Northern Europe is compressing buyer power into fewer procurement desks, forcing equipment suppliers to restructure pricing and service models around large integrated livestock estates rather than fragmented smallholder networks.
For Market Incumbents: Shield installed base relationships by embedding predictive analytics subscriptions that synchronize feeding protocols with milk-yield data, neutralizing price competition from standalone conveyor manufacturers. Deepen backward integration into sensor-integrated control systems to secure semiconductor allocation priority during East Asian foundry constraints. Prioritize CE certification maintenance as the EU Machinery Directive evolves safety standards for autonomous barn robotics. For New Entrants and Emerging Players: Embedded carbon-accounting software layers represent an underserved service gap where incumbent equipment OEMs lack specialized emissions-tracking capabilities. Penetrate Dutch dairy cooperatives first, where FrieslandCampina-aligned procurement desks seek feeders with automated Scope 3 footprint calculations. Deploy outcome-based financing models that tie equipment payments to verified methane reduction metrics, bypassing capital-constrained smallholder resistance. For Investors and Strategic Acquirers: Emerging Dutch Scope 3 livestock emissions standards reshape the acquisition landscape by elevating data-integrated feeding platforms over pure hardware manufacturers. Target sensor-integrated precision feeding specialists with established cloud analytics infrastructure, positioned for five-to-ten year contract value capture as carbon-accounting mandates proliferate. Monitor CE certification timeline extensions as the inflection signal indicating regulatory friction that will consolidate vendor ranks toward pre-certified incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Cloud Platform Integration | Combines near-infrared spectroscopy with edge computing to capture recurring advisory revenue from Danish dairy estates. |
| Backward Integration into Controller Manufacturing | Secures semiconductor supply continuity for European assemblers facing East Asian foundry allocation cycles. |
| Carbon Accounting Software Development | Enables outcome-based equipment financing tied to Dutch Scope 3 livestock emissions verification protocols. |
| Cooperative Procurement Desk Partnerships | Aligns technical specifications with FrieslandCampina-aligned collective tenders displacing regional dealers. |
| REACH-Compliant Lubricant Pipeline Consolidation | Secures pre-certified grease formulations maintaining load-bearing capacity in cold German barn environments. |
Methodological Framework
Operator-level perspectives from dairy farm managers, cooperative procurement directors, equipment maintenance engineers, and compound feed manufacturing technicians anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation against EU Machinery Directive compliance filings, F-Gas Regulation substance databases, SEC 10-K disclosures from listed agricultural equipment manufacturers, and Dutch agricultural cooperative financial reports. Bottom-up equipment shipment estimates triangulated against top-down addressable market calculations across the analysis window.
Sensitivity analysis tested forecast robustness against nickel price volatility scenarios and semiconductor allocation cycle disruptions. The quantitative framework modeled product type segmentation across gravimetric, continuous, batch, and volumetric architectures; application segmentation spanning aquaculture, dairy, and research institutions; and technology segmentation distinguishing electrical, pneumatic, mechanical, and hydraulic drive systems. CAGRs derived from replacement cycle timing, farm consolidation trajectories, and regulatory compliance deadline clustering. Industry-specific inputs included labor cost escalation indices from Dutch collective bargaining agreements and carbon-accounting standard adoption curves.
Forecasts assume regulatory continuity in EU Machinery Directive motor-efficiency tiers and F-Gas refrigerant phase-down schedules; material policy shifts would require re-modeling equipment replacement timelines and certification cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Horse Grain Feeders Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Hydraulic Squeeze Chute Market
Livestock Equipment
Canada Horse Riding Equipment Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Egg Incubator Market
Livestock Equipment
Automatic Cattle Waterer Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Cattle Supplies Market
Livestock Equipment
Goat Creep Feeder Market
Livestock Equipment
Horse Bell Boots Market
Livestock Equipment
Livestock Panel Gates Market