
 Chicken Feeder and Drinkers Market | 2026-2036
Chicken Feeder and Drinkers Market Size, Share, and Industry Trends Forecast 2026-2036
Chicken Feeder and Drinkers Market Outlook
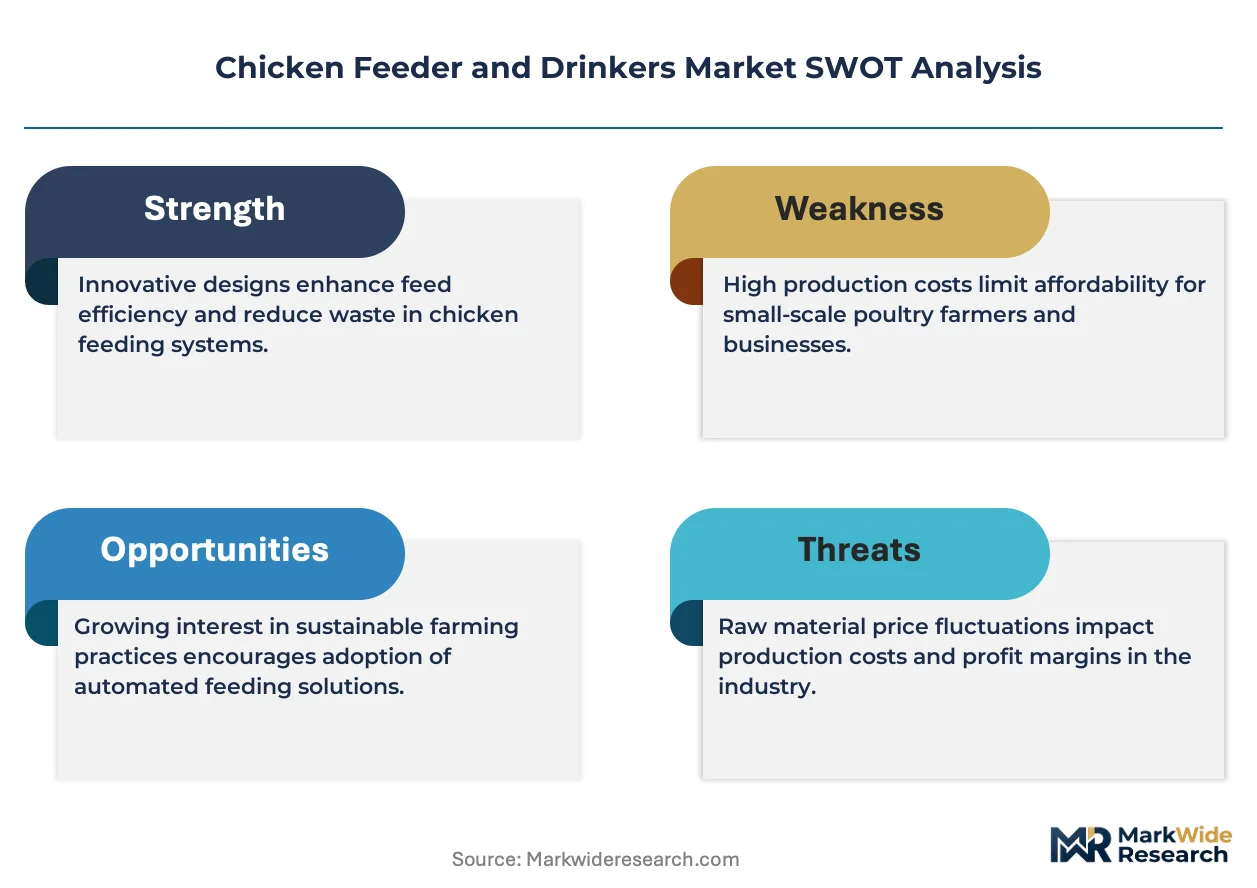
Equipment leasing and managed-service contracts is rewriting competitive entry barriers for mid-scale poultry operators. Big Dutchman leverages its full-line automation portfolio to anchor premium positioning across European and Latin American accounts. Roxell BVBA specializes in precision-controlled drinking systems that sustain margin pools in antibiotic-free production environments. Kenpoly Manufacturers Limited competes on rotational-molded plastic durability, dominating price-sensitive smallholder segments in East Africa.
Chicken feeders and drinkers constitute engineered dispensing systems that regulate feed distribution and water access across broiler, layer, and breeder operations, typically fabricated from UV-stabilized polypropylene or 304-grade stainless steel to withstand cyclic chemical sanitation and mechanical abrasion. Their primary commercial purpose centers on optimizing feed conversion ratios, reducing microbial contamination vectors, and automating labor-intensive husbandry workflows. Automatic feeders and nipple drinkers command the largest installed base, though organic poultry producers are driving faster growth in medium-capacity stainless-steel configurations that satisfy third-party welfare-certification audit protocols. Plastic remains the dominant material by unit volume, yet galvanized steel is retreating to replacement-part niches as biosecurity standards harden against porous corrosion sites.
USDA facility-inspection requirements and EPA Clean Water Act discharge permits shape equipment specifications for American integrators, while REACH compliance and CE machinery directives govern material composition and electrical safety for European suppliers. Brazil's ANVISA veterinary-residue monitoring and state-level environmental licensing in São Paulo further filter which feeder and drinker designs gain market authorization. Stakeholders must track how evolving antibiotic-stewardship mandates and carbon-accounting frameworks for scope-three agricultural emissions will redefine equipment-upgrade cycles and supplier qualification criteria.
Market Dynamics
Automated feeding and drinking systems are displacing manual husbandry workflows across commercial poultry operations, driven by labor cost inflation and biosecurity mandates that penalize human-animal contact points.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbon refrigerants is accelerating corrosion-resistant alloy specifications in climate-controlled poultry houses across Germany, France, and the Netherlands.
- Nipple drinker precision engineering:Reduced water spillage and contamination vectors are cutting antibiotic dependency in Brazilian integrated grow-out facilities.
- Smallholder mechanization:Rotational-molded plastic durability is unlocking equipment finance penetration among Kenya's layer cooperatives.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings are compressing margin pools for 304-grade feeder fabricators serving premium antibiotic-free segments.
- Replacement-part supply concentration:Galvanized steel component sourcing clusters in Chinese foundries expose European integrators to tariff and logistics friction.
- Electrical integration complexity:CE machinery directive compliance for sensor-activated feeding systems extends product qualification timelines by eight to fourteen months.
Strategic Opportunities
- India's layer sector consolidation:Contract farming mandates in Telangana and Andhra Pradesh are creating fleet-upgrade demand for automated drinker systems.
- IoT-enabled feed optimization:Convergence of weight-scale sensors and cloud analytics is opening subscription revenue streams for equipment-as-a-service providers.
- Carbon-accounting frameworks:Scope-three agricultural emission disclosure requirements in the EU are positioning precision-feeding technology as a verified mitigation pathway.
Industry Challenges
- Veterinary equipment technician scarcity:Cross-functional skill gaps in mechatronics and avian health are slowing automated system commissioning across mid-scale Brazilian farms.
- Antibiotic-free certification timelines:Third-party welfare audit protocols require six to eighteen months of equipment operational data before accreditation, freezing upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chicken Feeder and Drinkers Market |
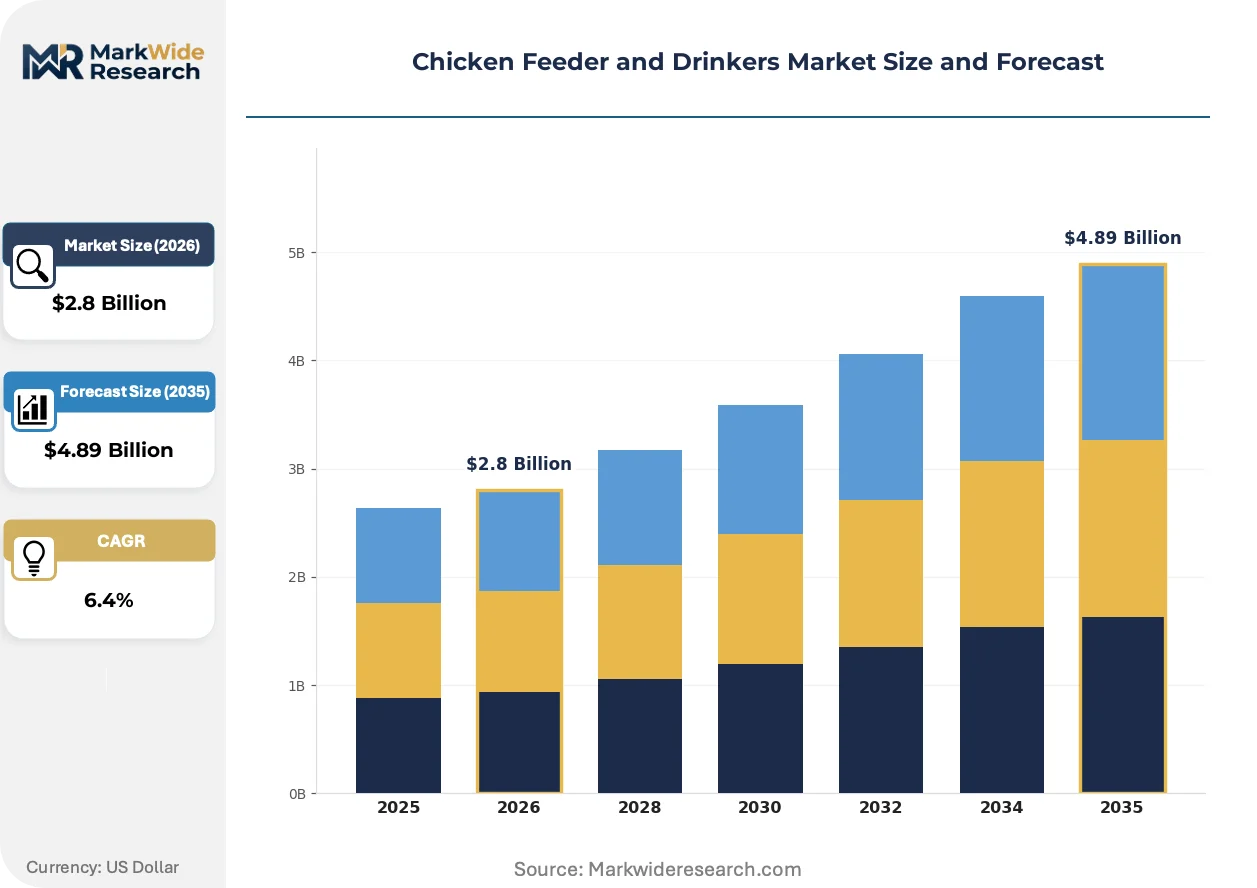
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Manual Feeders, Nipple Drinkers, Trough Drinkers Material: Plastic, Stainless Steel, Galvanized Steel, Wood End User: Commercial Poultry Farms, Backyard Poultry Keepers, Organic Poultry Producers, Agribusiness Capacity: Small Capacity, Medium Capacity, Large Capacity, Custom Capacity |
| Companies Covered | Big Dutchman, SKA Poultry Equipment, Chore-Time, INDIV USA, AZA International SRL, Roxell BVBA, Exafan, Retech Farming, Kenpoly Manufacturers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chicken Feeder and Drinkers Market Strategic Shifts
Sensor-integrated feeding systems and corrosion-resistant material specifications are compressing equipment replacement cycles while elevating supplier qualification thresholds across protein supply chains.
UV-stabilized polypropylene formulations with embedded antimicrobial additives are extending service intervals in high-sanitation environments. Brazilian integrators in São Paulo state are deploying these specifications at scale in new-build facilities. Traditional galvanized steel drinker lines are rendering obsolete in antibiotic-free production zones where porous corrosion sites trigger audit failures.
REACH compliance amendments on polymer additive safety are forcing reformulation of legacy plastic feeder components across European supply chains. German and Dutch equipment fabricators are accelerating migration to FDA-grade material certifications to maintain cross-Atlantic market access. Layer operations pursuing EU organic certification represent the most affected segment, with retrofit demand concentrated in Denmark and northern Italy.
Managed-service contracts with uptime guarantees are displacing capital purchase models among mid-scale operators. Equipment lessors in Brazil's Paraná state are bundling preventive maintenance with telemetry-based performance monitoring. This shift is most visible among broiler growers supplying integrated protein processors seeking to offload balance-sheet exposure.
Chicken Feeder and Drinkers Market Segmentation
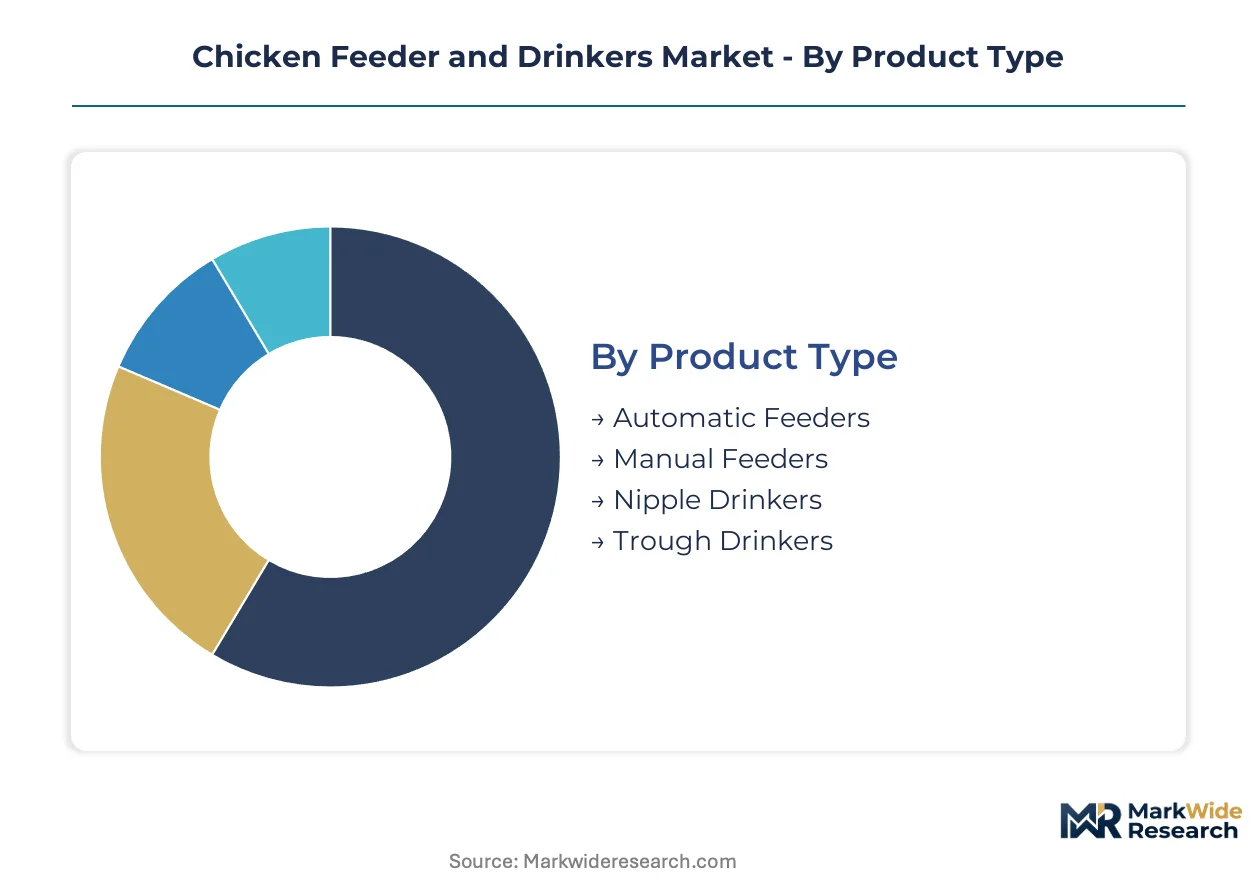
Equipment heterogeneity across poultry operation scales demands precise segmentation mapping. Technical specifications, material durability thresholds, and biosecurity compliance requirements vary sharply between backyard installations and integrated commercial facilities.
Product Type:
After-sales-service intensity diverges sharply across automation tiers, with sensor-integrated systems requiring specialized technician networks and preventive maintenance contracts.
- Automatic Feeders:Programmable dispensing mechanisms with load-cell weight monitoring and cloud-connected telemetry optimize feed conversion ratios in climate-controlled houses. Demand concentrates among Brazilian integrators in Paraná state modernizing grow-out facilities to meet ANVISA veterinary-residue monitoring protocols.
- Nipple Drinkers:Precision-engineered valve assemblies deliver metered water volumes while eliminating spillage vectors that harbor bacterial colonization. German and Dutch fabricators dominate specification-setting for EU organic certification compliance, where reduced antibiotic dependency mandates contamination-free hydration systems.
- Manual Feeders:Gravity-fed hopper designs with mechanical agitation suit smallholder capital constraints and limited electrical infrastructure.
- Trough Drinkers:Open-channel water delivery persists in replacement-part markets and transitional facilities upgrading from galvanized steel legacy lines.
Automatic feeders hold the largest share; momentum sits with nipple drinkers.
Material:
Cost tier stratification separates premium corrosion-resistant specifications from price-sensitive commodity alternatives.
- Plastic:UV-stabilized polypropylene formulations with embedded antimicrobial additives dominate unit volume through rotational molding economies. Kenyan layer cooperatives drive finance penetration for durable molded configurations that withstand cyclic chemical sanitation.
- Stainless Steel:304-grade fabrication satisfies antibiotic-free audit protocols by eliminating porous corrosion sites that trigger third-party welfare-certification failures. Nickel and chromium input volatility compresses margin pools for European premium-segment suppliers.
- Galvanized Steel:Zinc-coated mild steel retreats to replacement-part niches as biosecurity standards harden against oxidation-induced surface degradation.
- Wood:Traditional carpentry persists in backyard and heritage-breed operations where aesthetic and tactile preferences override sanitation efficiency.
Plastic commands volume leadership; stainless steel gains share fastest in certified antibiotic-free channels.
End User:
Application intensity determines equipment durability specifications and automation integration depth.
- Commercial Poultry Farms:High-density housing configurations mandate precision-engineered dispensing systems with telemetry integration and centralized monitoring dashboards. São Paulo state environmental licensing requirements filter which automated designs gain operational authorization.
- Organic Poultry Producers:Third-party welfare audit protocols specify medium-capacity stainless-steel configurations with six to eighteen months of operational data requirements before accreditation. Danish and northern Italian layer operations concentrate retrofit demand.
- Backyard Poultry Keepers:Small-batch husbandry sustains demand for manually operated gravity-fed systems with minimal capital outlay.
- Agribusiness:Vertically integrated protein processors deploy fleet-standardized equipment across contracted grow-out networks to ensure supply-chain traceability.
Commercial farms anchor installed base; organic producers show steepest expansion trajectory.
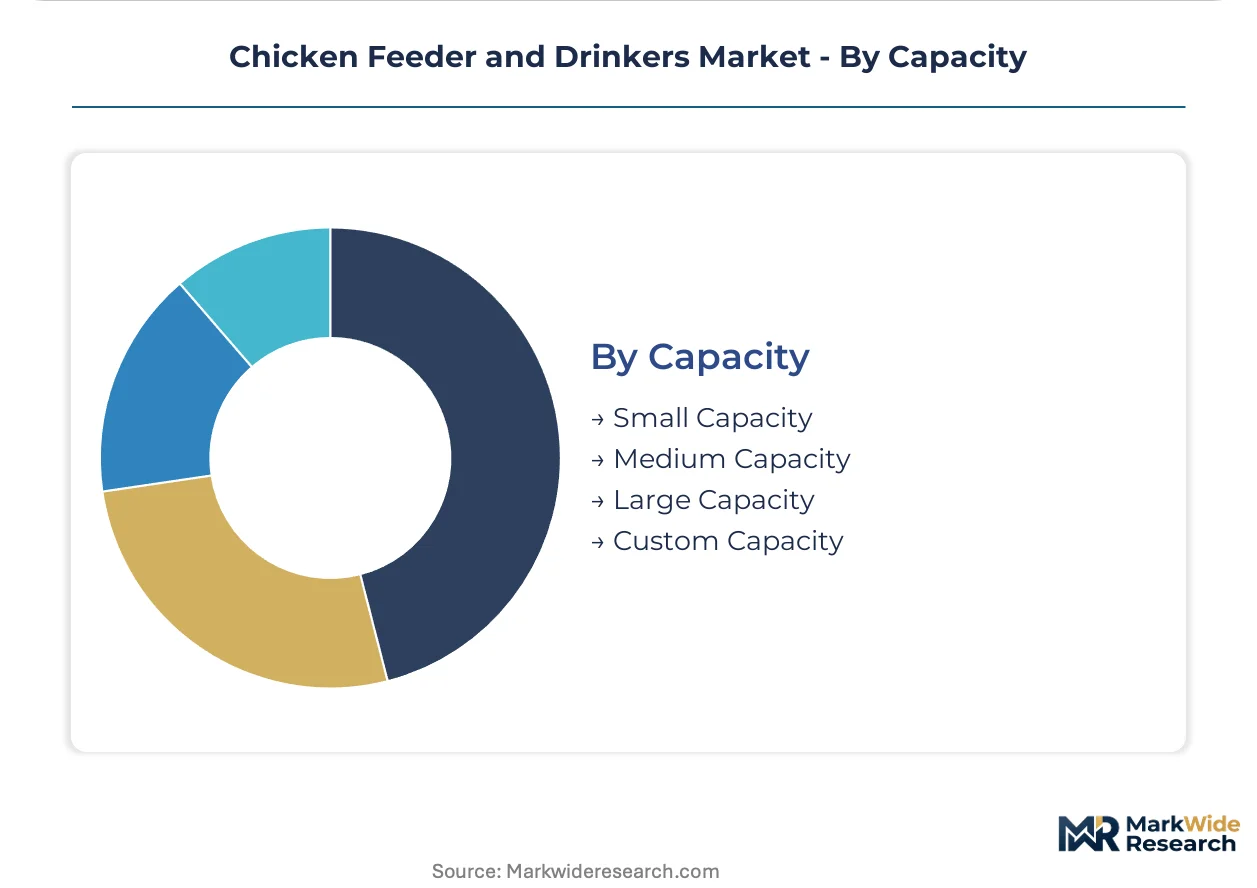
Capacity:
Volume tier alignment with flock density and house dimensions shapes procurement patterns.
- Large Capacity:Bulk hopper and reservoir systems serve integrated broiler operations with ten-thousand-plus bird houses requiring continuous feed and water availability.
- Medium Capacity:Modular configurations balance automation benefits with flexibility for expanding layer cooperatives in Telangana and Andhra Pradesh contract farming zones.
- Small Capacity:Compact units address backyard and trial-farm installations with limited floor space and manual handling workflows.
- Custom Capacity:Engineered-to-order specifications accommodate non-standard house geometries and specialty breed requirements.
Large capacity dominates revenue; medium capacity unlocks mechanization in consolidating markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA veterinary-residue monitoring and state-level environmental licensing are accelerating automated equipment deployments across Brazilian poultry belts. The EU F-Gas Regulation and ammonia-emission ceilings are forcing material upgrades in climate-controlled houses from Germany to the Netherlands.
Brazil
Integrated protein processors in São Paulo and Paraná states are modernizing grow-out facilities with precision-engineered nipple drinkers. ANVISA protocols filter which automated designs gain operational authorization. Equipment lessors in Paraná bundle preventive maintenance with telemetry monitoring for contracted broiler growers.
Germany
REACH compliance amendments and CE machinery directives govern material composition for climate-controlled poultry houses. The EU F-Gas Regulation accelerates corrosion-resistant alloy specifications in automated feeding systems. Bavarian fabricators dominate specification-setting for organic certification compliance.
United States
USDA facility-inspection requirements and EPA Clean Water Act discharge permits shape equipment specifications for poultry integrators. Layer operations in Iowa and Arkansas pursue antibiotic-free certification requiring stainless-steel configurations. Southeast broiler belts concentrate demand for large-capacity automated systems.
India
Contract farming mandates in Telangana and Andhra Pradesh create fleet-upgrade demand for automated drinker systems. BIS standards and state-level agricultural mechanization subsidies filter procurement patterns. Layer cooperatives in Karnataka and Tamil Nadu drive finance penetration for medium-capacity modular configurations.
Kenya
Rotational-molded plastic durability unlocks equipment finance penetration among layer cooperatives in the Rift Valley and Central Province. National agricultural extension programs promote mechanization for smallholder productivity. Nairobi-based distributors anchor supply chains for UV-stabilized polypropylene configurations.
Chicken Feeder and Drinkers Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered automation categories. The vendor base organizes around three strategic archetypes: full-line automation integrators, precision-component specialists, and regional price-competitive fabricators. Dominant competitive moves include strategic partnerships for IoT-enabled feed optimization and geographic expansion through equipment-as-a-service leasing models.
Among European-based specialists, Roxell BVBA and Big Dutchman occupy premium positioning across precision-controlled drinking systems and full-line automation portfolios. Kenpoly Manufacturers Limited exemplifies the regional durability-focused archetype serving price-sensitive smallholder segments. These three anchors illustrate how competitive positioning fragments across certification-grade tiers rather than consolidating around scale alone.
| Leading Market Players |
|---|
| Big Dutchman |
| SKA Poultry Equipment |
| Chore-Time |
| INDIV USA |
| AZA International SRL |
| Roxell BVBA |
| Exafan |
| Retech Farming |
| Kenpoly Manufacturers Limited |
| Others |
Value Chain & Pricing Dynamics
Chinese foundry concentration for galvanized steel replacement components funnels pricing power toward European integrators sourcing corrosion-resistant alloys, compressing margin pools for mid-tier fabricators serving price-sensitive smallholder segments.
Pricing Analysis
Certification level (CE/FDA-grade material compliance) creates the primary spread between premium stainless-steel configurations and commodity plastic alternatives. Three-tier pricing structure separates antibiotic-free audit-grade specifications from standard automated systems and manual equipment for backyard operations. Cost compression in the stainless-steel tier is intensifying because nickel and chromium input volatility erodes fabricator margins. Smallholder cooperatives in East Africa exhibit highest price sensitivity, while integrated protein processors in Brazil show lowest sensitivity due to fleet-standardization mandates.
Supply Chain Analysis
Tariff exposure between Chinese component foundries and European assembly facilities dominates supply chain risk profiles for galvanized steel drinker lines. Raw material sourcing draws from German specialty alloy producers, Indian rotational molding compound suppliers, and Chinese zinc-coated steel fabricators. Single-source vulnerability concentrates in precision valve assemblies for nipple drinker systems. Distribution runs through veterinary equipment distributors in Brazil, agricultural extension networks in Kenya, and OEM-direct channels for large-scale integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment heterogeneity across certification tiers fragments competitive space, with antibiotic-free audit protocols creating defendable niches for precision-engineered suppliers.
For Market Incumbents: Entrench specification-setting authority by deepening backward integration into corrosion-resistant alloy supply and anchoring managed-service contracts with telemetry-based uptime guarantees. Sensor-activated feeding system complexity extends qualification timelines, creating a moat against fast-follower competition. Capacity expansion in Paraná state captures Brazilian integrator fleet-upgrade cycles. For New Entrants and Emerging Players: Pursue medium-capacity modular configurations for India's consolidating layer cooperatives in Telangana and Andhra Pradesh, where contract farming mandates outstrip established supplier coverage. IoT-enabled feed optimization subscriptions offer a service-based entry angle with lower capital barriers than equipment manufacturing. For Investors and Strategic Acquirers: Capital is best deployed toward precision-component specialists with FDA-grade material certifications and established technician networks for preventive maintenance. Long-term viability hinges on positioning against scope-three agricultural emission disclosure requirements. The signal to watch is carbon-accounting framework adoption velocity in EU protein supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corrosion-Resistant Alloys | Captive supply of 304-grade stainless steel insulates margin pools from nickel price volatility. |
| IoT-Enabled Feed Optimization Platform | Cloud analytics convergence with weight-scale sensors opens recurring revenue streams. |
| Managed-Service Contract Expansion | Uptime guarantees with telemetry monitoring displace capital purchase models among mid-scale operators. |
| CE Machinery Directive Pre-Certification | Early compliance investment compresses competitor product qualification timelines by eight to fourteen months. |
| Regional Equipment Leasing Network | Paraná state bundling of preventive maintenance with performance monitoring captures contracted grow-out demand. |
Study Parameters
Cross-validation between equipment fabricator interviews and regulatory filing analysis anchors the qualitative findings. Primary fieldwork engaged poultry operations managers, veterinary equipment technicians, agricultural extension officers, and integrated protein processor procurement leads. Secondary sources included ANVISA veterinary-residue monitoring protocols, EU F-Gas Regulation implementation guidance, USDA facility-inspection requirement documents, and REACH compliance amendment notices. Bottom-up segment sizing triangulated against top-down protein production forecasts across the analysis window.
Calibration against historical replacement-cycle data and documented fleet-upgrade timelines shaped the projection framework. Segmentation dimensions modeled encompass automation tier, material specification grade, end-user scale category, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to equipment penetration rates and mechanization subsidy disbursement patterns. Forecast inputs incorporated ammonia-emission ceiling compliance deadlines and antibiotic-stewardship mandate phase-in schedules.
Sensitivities concentrate around nickel price volatility, tariff friction in Chinese component sourcing, and veterinary technician scarcity slowing automated system commissioning. Forecasts reflect documented assumptions on subsidy continuity and certification timeline stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Livestock Equipment
Livestock Identification Market
Livestock Equipment
Animal Cage Market
Livestock Equipment
Animal Feed Mixer Market
Livestock Equipment
Starter Feed Market
Livestock Equipment
Horse Stable Supplies Market
Livestock Equipment
Chicken Coop Market
Livestock Equipment
Cattle Farm Equipment Market
Livestock Equipment
Automatic Goat Waterer Market
Livestock Equipment
Bird Feeding and Watering Suppliers Market
Livestock Equipment
Livestock Monitoring System Market
Livestock Equipment
Horse Corral Panels Market
Livestock Equipment
Sheep Tilt Table Market
Livestock Equipment
Sheep Creep Feeder Market
Livestock Equipment
Cattle Blower Market
Livestock Equipment
Sheep Handling Equipment Market
Livestock Equipment
Rabbit Hutches Market