
 Global Reporting Software Market | 2026-2036
Global Reporting Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reporting Software Market Foresight
Modular unbundling of enterprise reporting suites is restructuring how mid-market buyers evaluate vendors. SAP sustains dominance in ERP-embedded reporting through deep integration hooks into financial workflows. Oracle leverages its database footprint to anchor on-premise customers during hybrid cloud transitions. Datadog competes by extending observability data into operational dashboards for DevOps teams.
Reporting software encompasses applications that collect, process, and visualize structured business data through parameterized queries, scheduled generation engines, and multi-format export protocols including XBRL, PDF, and interactive HTML5 renderers. Its primary commercial purpose is transforming raw transactional records into decision-ready intelligence for executives, regulators, and operational managers. Cloud-based deployment captures the fastest expansion as organizations abandon capital-intensive server maintenance for consumption-priced SaaS models. Financial reporting solutions command the deepest margin pools due to mandatory audit trails and SOX-aligned control requirements that justify premium pricing. ERP integration capability functions as the primary gating factor in procurement decisions, with buyers prioritizing pre-built connectors over custom API development.
The US SEC mandates XBRL-tagged financial disclosures through its EDGAR filing system, directly shaping product roadmaps for compliance-oriented vendors. EU GDPR and the EU AI Act impose data lineage and algorithmic transparency requirements that reporting platforms must encode into their audit architectures. ISO 27001 certification has become a non-negotiable threshold for vendor shortlists in regulated industries. Stakeholders must weigh sovereignty requirements against cloud agility when selecting deployment architectures for multi-jurisdiction operations.
Market Dynamics
Cloud migration among banking institutions is compressing procurement cycles as institutions abandon spreadsheet workflows for auditable SaaS infrastructure. The EU AI Act and GDPR compliance obligations are forcing enterprises to rebuild reporting architectures around data lineage requirements.
Growth Catalysts
- XBRL Mandates:The US SEC requires machine-readable financial disclosures through its EDGAR filing system. Compliance vendors must embed tagging engines directly into generation workflows.
- Banking Cloud Migration:Financial institutions are replacing on-premise servers with consumption-priced SaaS models. This shift accelerates replacement of legacy spreadsheet dependencies.
- ISO 27001 Certification:Regulated industries now treat this security standard as a non-negotiable vendor threshold. Procurement teams filter shortlists exclusively around certified providers.
Market Restraints
- Hybrid Integration Costs:Organizations maintaining on-premise Oracle databases face expensive API development to connect cloud reporting layers. Database footprint lock-in delays full SaaS transitions.
- Skills Concentration:DevOps teams capable of configuring observability-to-dashboard pipelines remain concentrated in North American and Western European labor markets. Talent scarcity inflates implementation timelines.
- GDPR Data Sovereignty:EU requirements restrict cross-border data flows to non-adequate jurisdictions. Multi-national enterprises must deploy region-segregated instances, duplicating infrastructure spend.
Strategic Opportunities
- India BFSI Expansion:RBI guidelines on digital lending transparency create demand for auditable reporting infrastructure. Domestic banks lack mature vendor relationships, opening white space for compliant entrants.
- AI-Act Algorithmic Transparency:EU mandates for automated decision documentation require new audit trail modules. Reporting platforms can embed explainability engines as premium feature sets.
- Embedded Analytics Convergence:Operational technology data streams from manufacturing sensors are merging with financial reporting systems. Vendors bridging IT/OT data silos capture cross-functional budgets.
Industry Challenges
- XBRL Taxonomy Expertise:Financial reporting teams lack personnel trained in regulatory tagging standards. Hiring accountants with both domain and technical fluency extends implementation cycles.
- Legacy ERP Entanglement:SAP-embedded reporting users face complex data extraction when evaluating standalone alternatives. Deep integration hooks create switching friction that vendors struggle to overcome.
- Multi-Jurisdiction Certification:Providers must maintain concurrent ISO 27001, SOC 2 Type II, and regional banking regulator approvals. Audit calendar coordination across frameworks consumes operational bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reporting Software Market |
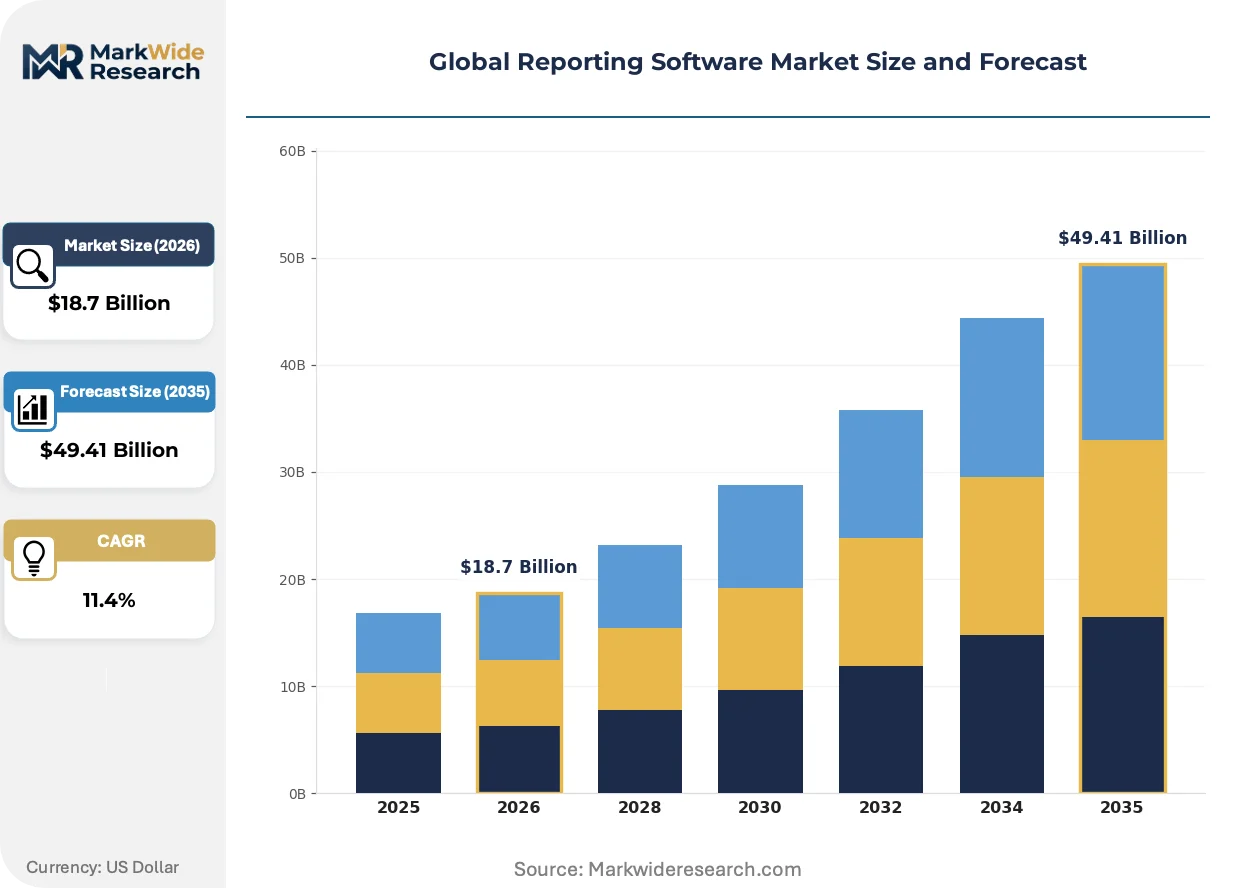
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Hosted Solution Type: Financial Reporting, Compliance Reporting, Operational Reporting, Sales Performance End User Industry: Banking, Manufacturing, Telecommunications, Education Integration Capability: ERP Integration, CRM Compatibility, Business Intelligence, Data Warehousing |
| Companies Covered | IBM, Oracle, SAP, Microsoft, Datadog, Qlik, InsightSquared, Jet Reports, JReport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reporting Software Market Shifts & Advancements
Natural language interfaces are compressing the distance between business users and database queries. Three converging developments are restructuring how reporting capabilities are packaged and consumed.
Generative AI query builders are consolidating the report authoring workflow into conversational interfaces. Business analysts at mid-market manufacturers are adopting these tools faster than traditional BI training cycles allowed. The technology is consolidating demand previously fragmented between self-service visualization platforms and IT-managed reporting queues.
EU CSRD sustainability disclosure requirements are mandating double materiality assessments across listed entities. Industrial conglomerates must now report environmental impact data with the same audit rigor as financial statements. European automotive suppliers are responding by embedding ESG data collection directly into operational reporting infrastructure.
Consumption-based pricing models are displacing perpetual license structures in enterprise procurement. Finance teams at North American healthcare systems now evaluate vendors on per-query cost predictability rather than upfront capital expenditure. This behavioral shift favors platforms with granular usage metering over bundled capacity tiers.
Global Reporting Software Market Segmentation
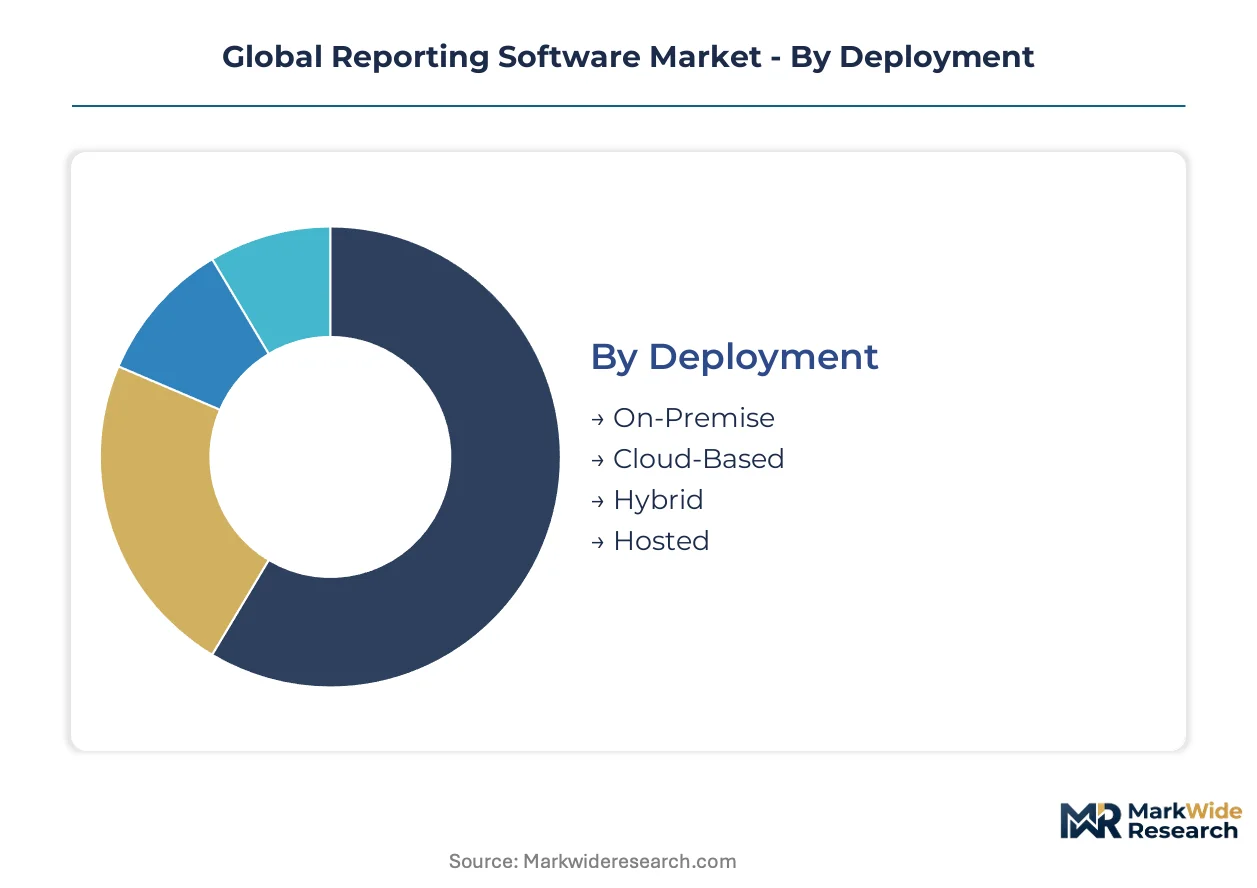
Deployment architecture determines compliance posture and total cost of ownership for reporting infrastructure. Solution specialization reflects divergent audit requirements across financial, regulatory, and operational domains.
Deployment:
Technology architecture governs data residency, latency, and capital expenditure profiles for enterprise buyers.
- Cloud-Based:Multi-tenant SaaS architectures deliver consumption-priced scalability without server maintenance overhead. Banking institutions in the United States and Germany are migrating core reporting workloads here to satisfy SEC and BaFin audit trail requirements while eliminating spreadsheet dependencies.
- On-Premise:Dedicated hardware installations maintain physical data sovereignty and sub-millisecond query performance for high-frequency trading floors. Japanese megabanks and Swiss private wealth managers retain these deployments to satisfy FINMA and FSA data localization mandates.
- Hybrid:Split architectures route sensitive PII through on-premise nodes while pushing anonymized analytics to cloud layers. German automotive suppliers deploy this pattern to reconcile GDPR data sovereignty with AI-driven forecasting demands.
- Hosted:Single-tenant managed services in third-party data centers offer dedicated infrastructure without capital ownership. Mid-market manufacturers in India select this model to bypass internal IT capacity constraints.
Mature deployment sits with On-Premise. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Application specialization tracks regulatory intensity and margin capture across functional domains.
- Financial Reporting:XBRL-tagged disclosure engines with SOX-aligned control matrices command premium pricing. United States SEC EDGAR mandates and EU CSRD sustainability disclosures are compressing procurement cycles for listed entities.
- Compliance Reporting:Audit trail modules encoding GDPR data lineage and EU AI Act algorithmic transparency requirements. European banking supervisors are expanding mandatory documentation scope for automated credit decisions.
- Operational Reporting:Real-time dashboarding of manufacturing sensor streams and supply chain KPIs. German industrial conglomerates embed these tools to merge IT and OT data silos under unified governance.
- Sales Performance:Territory-based quota management and pipeline forecasting for distributed field organizations. Telecommunications providers in India deploy these solutions to track subscriber acquisition costs across 22 licensed service areas.
Revenue concentration clusters in Financial Reporting. Compliance Reporting is climbing the fastest as regulatory scope expands.
End User Industry:
Vertical demand patterns reflect audit sophistication and data volume intensity.
- Banking:Basel III liquidity coverage ratio calculations and stress testing documentation dominate procurement specifications. RBI guidelines on digital lending transparency are accelerating infrastructure investment among Indian domestic banks.
- Manufacturing:Shop-floor-to-boardroom data pipelines integrating MES, ERP, and ESG disclosure requirements. European automotive suppliers must now report environmental impact data with financial-statement audit rigor under CSRD.
- Telecommunications:Subscriber analytics and network performance monitoring across distributed infrastructure. Indian operators face TRAI-mandated quality of service reporting with quarterly penalty exposure.
- Education:Student outcome tracking and federal funding compliance for accredited institutions. United States Department of Education gainful employment rules drive enrollment reporting automation.
Procurement volume concentrates in Banking. Manufacturing is expanding most quickly as ESG disclosure mandates proliferate.
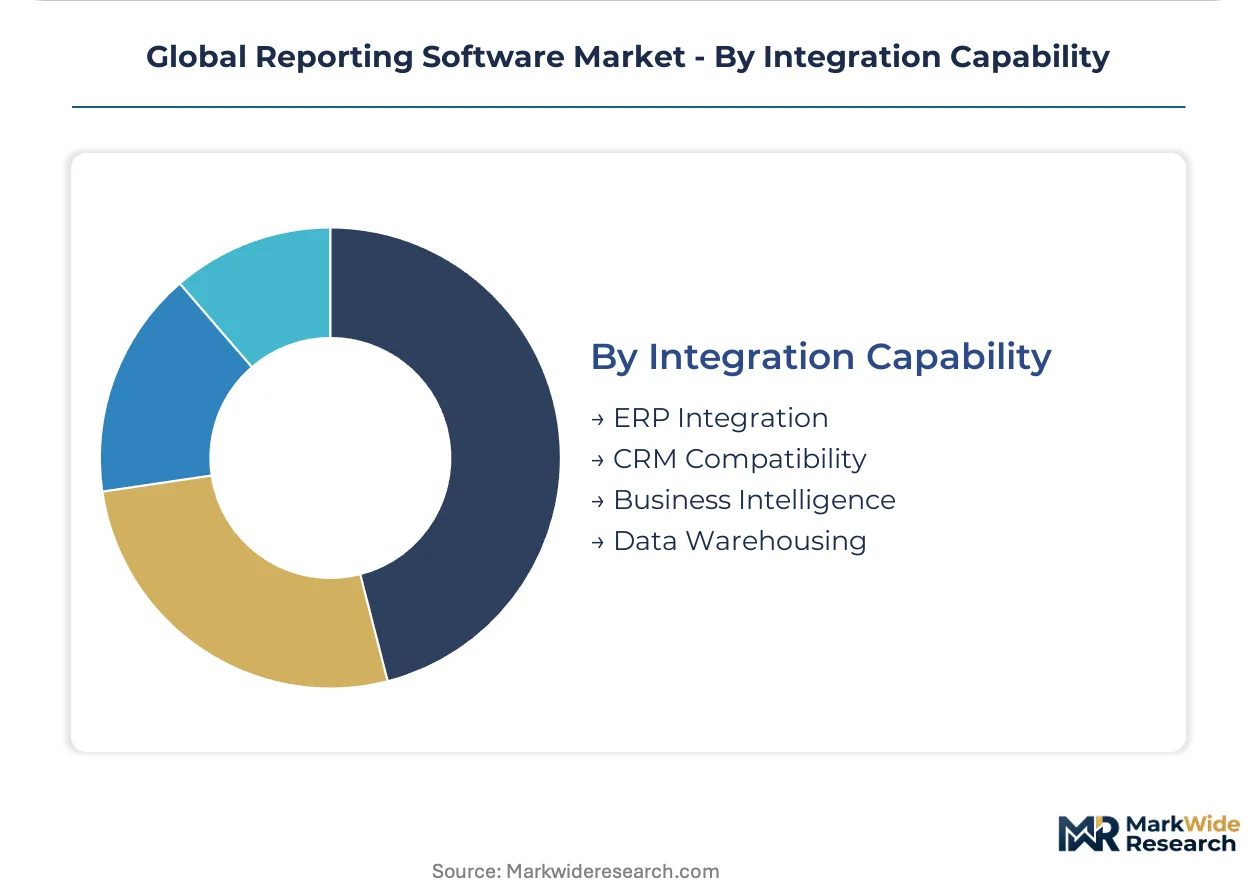
Integration Capability:
Connectivity depth determines implementation timeline and switching friction for enterprise buyers.
- ERP Integration:Pre-built connectors to SAP S/4HANA and Oracle Fusion eliminate custom API development. German industrial buyers prioritize these hooks over standalone alternatives despite 40% pricing premiums.
- Business Intelligence:Semantic layer unification across Tableau, Power BI, and Looker visualization environments. United States healthcare systems demand this capability to consolidate fragmented departmental analytics.
- Data Warehousing:Native connectivity to Snowflake, Databricks, and Google BigQuery for cloud-native query federation. DevOps teams at North American technology firms configure these pipelines to compress observability-to-dashboard latency.
- CRM Compatibility:Salesforce and Microsoft Dynamics synchronization for revenue operations reporting. Indian BFSI sales teams rely on these integrations to track lead-to-cash cycles across digital lending workflows.
Procurement priority sits with ERP Integration. Data Warehousing is gaining share fastest as cloud-native architectures displace on-premise warehouses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Germany while consumption spreads across banking centers in India and manufacturing hubs in Japan. Cloud infrastructure investment in North America outpaces deployment elsewhere by a significant margin. European regulatory complexity creates specialized demand for compliance-oriented architectures.
United States
Financial services firms in New York and Chicago drive SaaS procurement for SEC-mandated XBRL disclosures. The SEC's EDGAR filing system shapes product roadmaps for compliance vendors. Silicon Valley technology clusters incubate natural language query builders that compress report authoring workflows.
Germany
Automotive suppliers in Stuttgart and Munich embed ESG data collection into operational reporting infrastructure under CSRD mandates. BaFin audit trail requirements push banking institutions toward auditable cloud architectures. Industrial conglomerates in Baden-Württemberg merge IT and OT data silos under unified governance frameworks.
India
Domestic banks in Mumbai and Bangalore lack mature vendor relationships, opening white space for compliant entrants. RBI guidelines on digital lending transparency create demand for auditable reporting infrastructure. Telecommunications providers across 22 licensed service areas deploy sales performance solutions to track subscriber acquisition costs.
Japan
Megabanks in Tokyo retain on-premise deployments to satisfy FSA data localization mandates for wealth management operations. Manufacturing sensor integration drives operational reporting demand in Nagoya industrial corridors. METI guidance on supply chain transparency accelerates shop-floor-to-boardroom data pipeline investment.
United Kingdom
London-based financial institutions navigate post-Brexit regulatory divergence while maintaining EU compliance compatibility. The FCA's emphasis on operational resilience drives investment in real-time dashboarding infrastructure. Fintech clusters in Manchester and Edinburgh adopt embedded analytics for revenue operations reporting.
Global Reporting Software Market Competitive Landscape
The competitive structure tilts toward ERP-embedded incumbents with deep integration hooks into financial workflows. Database vendors leverage on-premise footprints to anchor customers during hybrid cloud transitions. Three archetypes dominate: legacy ERP extenders, cloud-native observability platforms, and standalone visualization specialists. M&A activity concentrates on API connectivity assets while portfolio diversification targets ESG disclosure modules.
Within the ERP-embedded tier, SAP and Oracle represent the integration-heavy incumbents that mid-market buyers evaluate against standalone alternatives despite pricing premiums. Datadog occupies a position among observability-native platforms extending operational data into DevOps dashboards. These three exemplify the tension between workflow depth and cloud agility that structures procurement decisions across banking and manufacturing verticals.
| Leading Market Players |
|---|
| IBM |
| Oracle |
| SAP |
| Microsoft |
| Datadog |
| Qlik |
| InsightSquared |
| Jet Reports |
| JReport |
| Others |
Supply & Pricing Matrix
Cloud-native SaaS architectures are displacing perpetual license models while simultaneously concentrating vendor bargaining power among hyperscaler-backed platforms. This technology transition compresses marginal costs for scaled providers while fragmenting pricing discipline across legacy on-premise incumbents.
Pricing Analysis
Margin tightening in mid-market tiers reflects consumption-based pricing displacement of perpetual licenses. Three-tier pricing structure across premium, standard, and economy levels stratifies by ERP integration depth and audit certification grade. Cost-down pressure on standalone visualization tools accelerates because hyperscaler bundling erodes standalone value propositions. Banking procurement teams exhibit lowest price sensitivity due to mandatory SOX compliance requirements, while mid-market manufacturers prioritize per-query cost predictability.
Supply Chain Analysis
Refurbishment flows for on-premise hardware assets create secondary supply channels as banks migrate to cloud. Software development concentrates in the United States, Germany, and India, with cloud infrastructure provisioning anchored in US and EU hyperscaler regions. Raw material dependencies center on semiconductor fabrication for data center equipment, undersea cable capacity for transatlantic latency, and specialized XBRL taxonomy expertise for compliance modules. Single-source vulnerability sits with hyperscaler concentration in Western cloud regions. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural language query interfaces are replacing traditional BI training workflows, compressing implementation timelines and reshaping competitive moats around conversational UX rather than report authoring complexity.
For Market Incumbents: Deploy API connectivity assets as defensive bulwarks against standalone challengers. Deepen pre-built ERP integration hooks into SAP S/4HANA and Oracle Fusion to increase switching friction. Invest in EU AI Act algorithmic transparency modules before regulatory deadlines force reactive development sprints.
For New Entrants and Emerging Players: Digital-channel self-service onboarding routes bypass entrenched procurement committees at mid-market manufacturers. White space concentrates in India BFSI digital lending transparency compliance and embedded analytics for operational technology convergence. Lead with consumption-priced pilots that demonstrate per-query cost predictability against bundled legacy alternatives.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by hyperscalers seeking ERP integration depth. Long-term viability favors platforms with concurrent ISO 27001, SOC 2 Type II, and banking regulator certifications that create procurement friction for challengers. Monitor RBI guideline enforcement intensity and EU CSRD audit scope expansion as demand inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built SAP connectors capture German industrial procurement budgets despite premium positioning. |
| Acquisition of Specialist Firm | XBRL taxonomy expertise targets address SEC EDGAR compliance capability gaps. |
| Strategic Partnership | Hyperscaler alliances deliver consumption-priced scalability without capital ownership burdens. |
| Product Launch | EU AI Act explainability engines open premium pricing for algorithmic transparency modules. |
| Geographic Expansion | India BFSI presence exploits domestic bank vendor relationship immaturity under RBI guidelines. |
Research Methodology
SEC EDGAR filings, EU regulatory bulletins, and hyperscaler capex disclosures formed the secondary backbone for market sizing validation. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists at banking and manufacturing enterprises informed demand-side assumptions. Bottom-up and top-down triangulation cross-validated segment-level estimates against aggregate vendor revenue disclosures.
Bottom-up modeling anchored forecasts in deployment architecture adoption curves and solution type procurement intensity across the analysis window. Segmentation dimensions included deployment model, organization size, vertical specialization, integration complexity, and regional regulatory cluster. CAGRs derived from fitted adoption curves incorporating EU AI Act implementation timelines and XBRL mandate enforcement phases.
The model holds under steady regulatory enforcement; deviation in EU AI Act audit scope expansion or RBI digital lending guideline acceleration would shift demand timing. Practitioners should monitor CSRD double materiality assessment rollout and SEC climate disclosure rulemaking for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Charity Accounting Software Market
Software & Services
Global Cinema Software Market
Software & Services
BIM Objects Software Market
Software & Services
HR Tech Market
Software & Services
Sales Compensation Software Market
Software & Services
Global Screen Mirroring Apps Market
Software & Services
Proxy Services and Software Market
Software & Services
PLM and Engineering Software Market
Software & Services
Sales Force Automation Software Market
Software & Services
Federal Government Software Market
Software & Services
Global SAP S-4HANA Application Market
Software & Services
Gym Management Software Market
Software & Services
Global Customer Journey Mapping Software Market
Software & Services
Preventive Maintenance Software Market
Software & Services
Weather Forecast Software Market
Software & Services
Email Checker Tools Market