
 Global Invoice Automation Software Market | 2026-2036
Global Invoice Automation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Invoice Automation Software Market Foresight
API-first data exchange is rebalancing the economics of invoice automation by displacing legacy EDI and paper-based ingestion. Tipalti leverages multi-entity payment orchestration to anchor mid-market SaaS adoption across North America and Europe. HighRadius competes through AI-native cash application and collections modules that extend its invoice automation footprint into working capital optimization.
Invoice automation software encompasses platforms that digitize, validate, route, and post supplier invoices through optical character recognition, robotic process automation, and machine learning algorithms, typically achieving extraction accuracy above 95 percent for structured documents while reducing manual touchpoints in accounts-payable workflows. Cloud-based deployment leads adoption due to faster implementation cycles and lower total cost of ownership, while machine learning and analytics segments capture disproportionate margin pools as buyers prioritize predictive cash-flow forecasting over basic digitization. On-premise solutions retain share in highly regulated manufacturing and financial services verticals where data sovereignty requirements constrain SaaS migration.
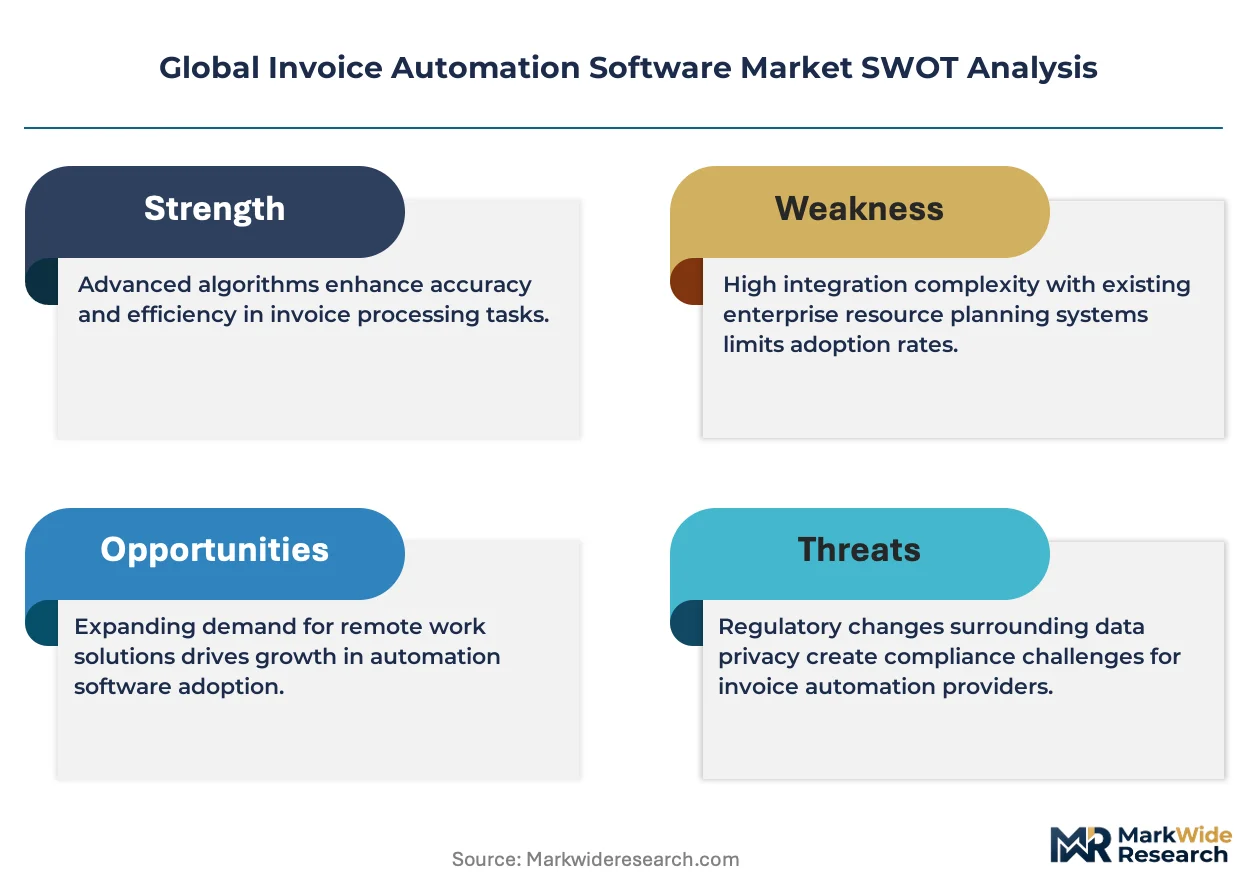
The European Union's GDPR and the U.S. Sarbanes-Oxley Act shape product architecture by mandating audit trails, access controls, and data residency safeguards that elevate compliance-module attach rates. India's Reserve Bank and Germany's Federal Financial Supervisory Authority impose supplementary documentation standards on cross-border payment reconciliation, creating regional customization requirements for vendors. Stakeholders must weigh the trade-off between platform consolidation and best-of-breed specialization as buyers demand tighter integration between invoice automation and broader treasury management ecosystems.
Market Dynamics
API-first architectures are compressing implementation timelines for invoice automation platforms, forcing legacy EDI providers to restructure pricing models or cede mid-market share to cloud-native entrants.
Growth Catalysts
- GDPR audit mandates:European treasuries must maintain immutable invoice trails, accelerating replacement of paper-based workflows with automated compliance modules.
- Optical character recognition:Extraction accuracy above 95 percent for structured supplier documents eliminates manual data entry bottlenecks in high-volume accounts-payable departments.
- Accountant shortages in India:Mid-market firms in Mumbai and Bangalore face acute talent gaps, driving SaaS adoption to maintain payable processing capacity without headcount expansion.
Market Restraints
- Data sovereignty requirements:German manufacturers bound by Federal Financial Supervisory Authority documentation standards cannot migrate fully to multi-tenant cloud architectures.
- Legacy ERP integration costs:Custom API development for SAP and Oracle on-premise instances consumes 40-60 percent of implementation budgets, extending payback periods.
- Substitution by native treasury modules:ERP vendors embed basic invoice capture into core financial suites, compressing standalone software addressable market at the low end.
Strategic Opportunities
- Working capital convergence:Platforms combining invoice automation with AI-native cash application and collections capture margin pools beyond basic digitization.
- India's digital payment infrastructure:UPI integration and RBI-mandated e-invoicing standards create greenfield demand among unpenetrated mid-market enterprises.
- Carbon accounting linkage:CSRD disclosure requirements position invoice data as a procurement emissions tracking source, opening sustainability software adjacencies.
Industry Challenges
- Machine learning model drift:Supplier document format variations degrade extraction accuracy over time, requiring continuous retraining investments.
- Cross-border reconciliation complexity:India's Reserve Bank and Germany's BaFin impose non-harmonized documentation standards, forcing vendors to maintain region-specific compliance modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Invoice Automation Software Market |
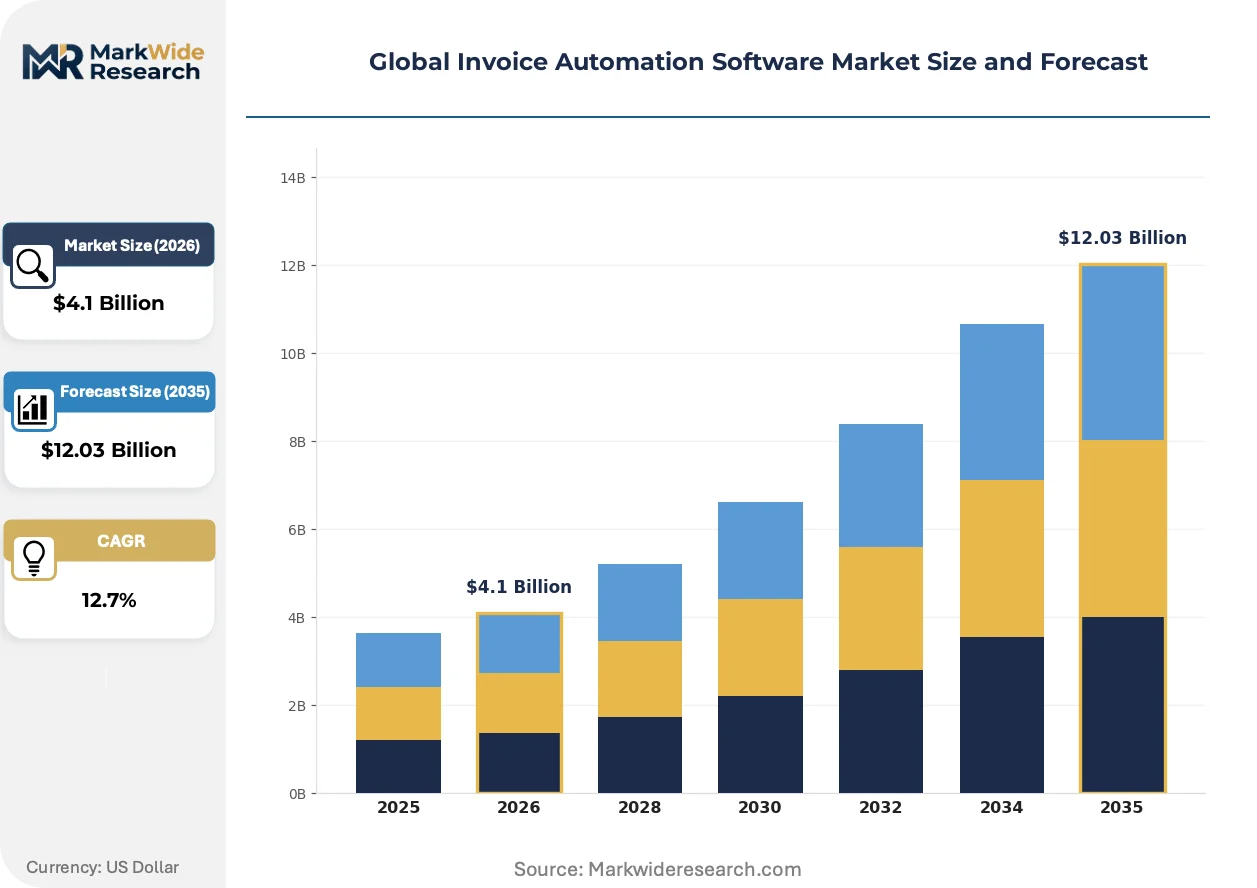
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $12.03 Billion |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Hosted Solution Type: Optical Character Recognition, Robotic Process Automation, Machine Learning, Business Process Management, Analytics Application: Invoice Processing, Payment Reconciliation, Expense Management, Vendor Management, Audit & Compliance End User Industry: Manufacturing, Financial Services, Telecommunications, Hospitality, Education |
| Companies Covered | Tipalti, HighRadius, Basware, Airwallex, Rossum, AvidXchange, Medius, Oracle NetSuite, Rillion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Invoice Automation Software Market Shifts & Advancements
Generative AI is rewriting the competitive architecture of invoice automation, compressing the gap between structured document extraction and contextual exception handling that previously required human intervention.
Large language models trained on multimodal document corpora are electrifying exception resolution workflows, enabling straight-through processing rates above 90 percent for semi-structured supplier invoices. North American financial services firms are deploying these systems to eliminate manual review queues for non-PO matched transactions. The technology is compressing headcount requirements in shared service centers while elevating platform switching costs through embedded learning curves.
Europe's CSRD mandates granular supply chain emissions disclosure, transforming invoice data into mandatory sustainability reporting inputs. Industrial buyers in Germany and France now require carbon footprint fields in supplier e-invoices to satisfy audit requirements. Procurement software vendors are responding by embedding emissions calculation engines directly into accounts-payable workflows, blurring boundaries between financial and ESG data infrastructure.
Mid-market treasury departments are consolidating vendor relationships, demanding unified platforms spanning invoice capture through payment execution rather than best-of-breed point solutions. SaaS providers in the United States and Germany are bundling foreign exchange hedging and supplier financing into core automation suites. This preference compression is marginalizing standalone OCR vendors unable to extend into working capital optimization.
Global Invoice Automation Software Market Segmentation
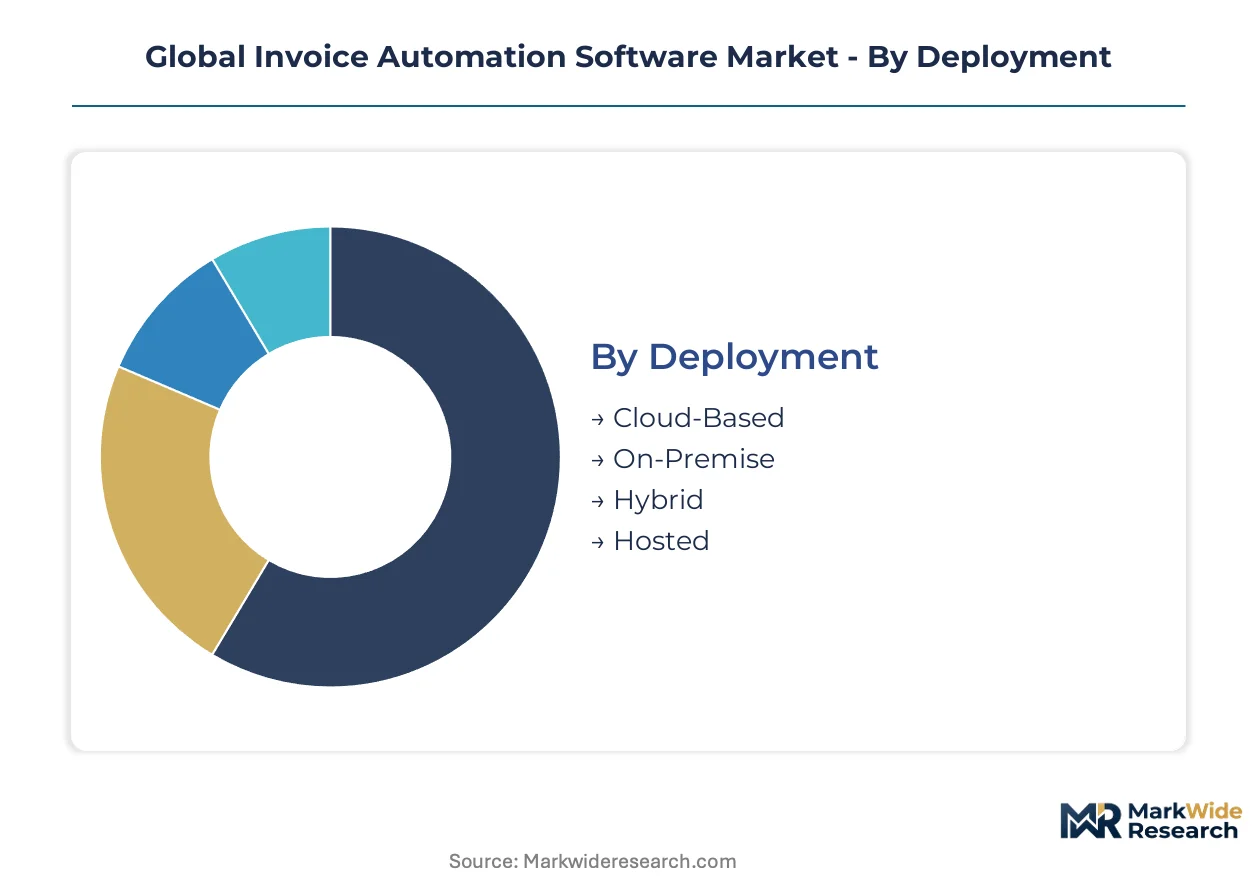
Segmentation reveals how compliance architecture and extraction technology drive purchasing decisions across treasury departments. Buyers select deployment modes and solution stacks based on audit mandates from regulators like GDPR and SOX, while end-user industry determines integration depth with legacy ERP systems.
Deployment:
GDPR and SOX compliance frameworks impose distinct data residency requirements that shape deployment preferences across European and North American treasuries.
- Cloud-Based:Multi-tenant SaaS architectures deliver sub-90-day implementation cycles and subscription economics that appeal to mid-market firms in the United States and Germany. Immutable audit trails satisfy GDPR Article 5 requirements while eliminating on-premise infrastructure overhead.
- On-Premise:Single-tenant installations within corporate data centers preserve full data sovereignty for German manufacturers bound by Federal Financial Supervisory Authority documentation standards. Custom security configurations accommodate air-gapped environments in defense and critical infrastructure verticals.
- Hybrid:Split architectures process sensitive supplier data on-premise while routing non-critical workflows through cloud infrastructure. Financial services firms in India deploy this model to satisfy RBI cross-border payment reconciliation rules without sacrificing scalability.
- Hosted:Dedicated private cloud instances managed by vendors offer middle-ground control for European enterprises navigating CSRD emissions disclosure mandates. Single-tenant isolation addresses data localization requirements without capital expenditure burdens.
Cloud-Based deployments command the volume ranking, with Hybrid climbing the fastest as compliance complexity fragments infrastructure decisions.
Solution Type:
Margin concentration follows extraction accuracy and predictive capability, with advanced modules capturing disproportionate pricing power over basic digitization tools.
- Optical Character Recognition:Template-based extraction engines achieve above-95 percent accuracy for structured supplier invoices, forming the foundational layer of accounts-payable automation. Manufacturing procurement departments in the United States deploy OCR to eliminate manual data entry for high-volume purchase order matching.
- Machine Learning:Self-improving models adapt to supplier document format variations without template reconfiguration, reducing continuous retraining investments. North American financial services firms prioritize ML modules for contextual exception handling that compresses straight-through processing rates toward 90 percent.
- Robotic Process Automation:Rule-based bots execute repetitive validation and routing tasks across ERP systems without cognitive adaptation. Mid-market enterprises in India deploy RPA to maintain payable processing capacity amid acute accountant shortages.
- Business Process Management:Workflow orchestration engines configure multi-step approval hierarchies and escalation rules for complex organizational structures. Hospitality chains leverage BPM to route invoices across distributed property management systems.
- Analytics:Predictive cash-flow forecasting modules transform historical payable data into liquidity optimization insights. Treasury departments pay premium attach rates for analytics that extend automation value beyond operational efficiency into working capital management.
Optical Character Recognition retains the highest deployment base, though Machine Learning is expanding most quickly as generative AI compresses implementation barriers.
Application:
Functional breadth determines platform stickiness, with vendors bundling adjacent modules to defend against ERP-native substitution.
- Invoice Processing:Core digitization, validation, and posting workflows represent the entry-point purchase for accounts-payable modernization. Universal demand across manufacturing and financial services verticals makes this the largest application category by deployment count.
- Payment Reconciliation:Automated matching of supplier payments against bank statements and open obligations. India's UPI infrastructure and RBI e-invoicing standards create greenfield demand for reconciliation automation among unpenetrated mid-market enterprises.
- Expense Management:Employee reimbursement workflows with receipt capture and policy enforcement. Telecommunications firms deploy integrated expense-invoice platforms to consolidate vendor and employee spend visibility.
- Vendor Management:Supplier onboarding, performance scoring, and risk monitoring capabilities. Procurement departments embed vendor management within payable automation to satisfy CSRD supply chain emissions disclosure requirements.
- Audit & Compliance:Immutable trail generation and regulatory reporting modules mandated by GDPR and SOX frameworks. German and French industrial buyers require carbon footprint fields in supplier e-invoices to satisfy CSRD audit requirements.
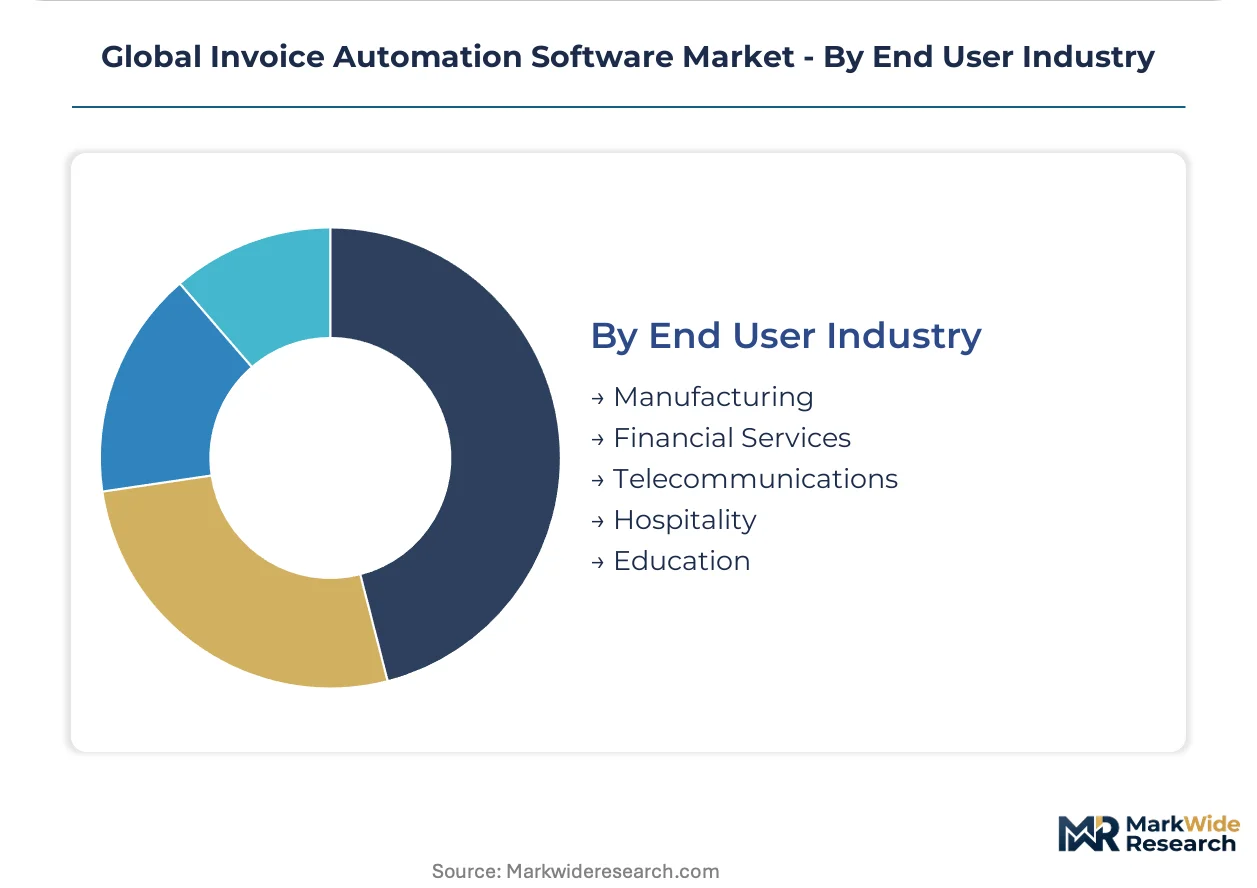
Invoice Processing dominates current deployment volumes, while Audit & Compliance shows the steepest expansion trajectory as regulatory disclosure burdens intensify.
End User Industry:
Industry-specific integration requirements and document complexity create divergent technology preferences across vertical markets.
- Manufacturing:High-volume, multi-currency supplier ecosystems with complex three-way matching requirements. German manufacturers retain on-premise solutions due to Federal Financial Supervisory Authority data sovereignty constraints.
- Financial Services:Stringent audit mandates and exception-heavy non-PO matched transactions drive demand for AI-native platforms. North American banks deploy generative AI to eliminate manual review queues in shared service centers.
- Telecommunications:Distributed infrastructure spend and recurring subscription billing patterns favor unified expense-invoice platforms. Mid-market carriers consolidate vendor relationships to reduce point solution fragmentation.
- Hospitality:Property-level procurement autonomy combined with corporate treasury oversight requirements. Chains deploy BPM-heavy solutions to route invoices across geographically dispersed operations.
- Education:Grant-funded procurement with restricted-use compliance and donor reporting obligations. Public and private institutions prioritize audit trail capabilities for fund accountability.
Manufacturing leads by deployment volume, with Financial Services gaining share fastest as AI-native cash application modules penetrate working capital optimization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai's financial services corridor drives concentrated invoice automation demand as mid-market firms replace manual accounts-payable workflows with cloud-native platforms. Compliance mandates from GDPR in Europe, SOX in the United States, and RBI e-invoicing standards in India are forcing treasury departments across major economies to modernize legacy infrastructure.
United States
North American financial services firms deploy AI-native cash application modules to eliminate manual review queues in shared service centers. SOX audit mandates require immutable invoice trails, accelerating replacement of paper-based workflows with automated compliance modules. New York and Chicago anchor enterprise adoption as banks prioritize predictive cash-flow forecasting over basic digitization.
Germany
German manufacturers bound by Federal Financial Supervisory Authority documentation standards retain on-premise solutions due to strict data sovereignty requirements. CSRD mandates transform invoice data into mandatory supply chain emissions reporting inputs, blurring boundaries between financial and ESG infrastructure. Industrial buyers in Bavaria and Baden-Württemberg now require carbon footprint fields in supplier e-invoices.
India
Mid-market enterprises in Mumbai and Bangalore face acute accountant shortages, driving SaaS adoption to maintain payable processing capacity without headcount expansion. RBI-mandated e-invoicing standards and UPI integration create greenfield demand among previously unpenetrated firms. Telangana and Karnataka host the fastest-growing deployment clusters as digital payment infrastructure matures.
United Kingdom
London's treasury management ecosystem demands unified platforms spanning invoice capture through payment execution rather than fragmented point solutions. GDPR Article 5 requirements elevate compliance-module attach rates as firms migrate from legacy EDI systems. Fintech corridors in Manchester and Edinburgh accelerate API-first adoption among mid-market professional services firms.
Japan
Tokyo-based enterprises consolidate vendor relationships around platforms bundling foreign exchange hedging and supplier financing into core automation suites. METI digital transformation incentives compress implementation timelines for cloud-native entrants displacing legacy providers. Osaka and Nagoya manufacturing clusters prioritize hybrid deployments to satisfy data localization requirements without sacrificing scalability.
Global Invoice Automation Software Market Competitive Landscape
Global majors compete with regional champions across compliance architecture and extraction technology, creating a tiered structure where scale-driven platforms face specialization pressure from AI-native entrants. The vendor base separates into three strategic archetypes: ERP-integrated suites, standalone OCR specialists, and working capital convergence platforms. Consolidation pressure intensifies as buyers demand tighter integration between invoice automation and broader treasury ecosystems. Dominant competitive moves include M&A to acquire machine learning capabilities and strategic partnerships to embed payment orchestration.
Within the working capital convergence tier, Tipalti and HighRadius exemplify platform strategies that extend beyond basic digitization into cash application and collections optimization. Basware anchors the European compliance-specialist position. These three occupy distinct competitive spaces—Tipalti through multi-entity payment orchestration, HighRadius through AI-native modules, and Basware through regional regulatory depth—while facing common pressure from ERP vendors embedding native capture functionality.
| Leading Market Players |
|---|
| Tipalti |
| HighRadius |
| Basware |
| Airwallex |
| Rossum |
| AvidXchange |
| Medius |
| Oracle NetSuite |
| Rillion |
| Others |
Supply & Pricing Matrix
Machine learning engineer concentrations in Bangalore and Hyderabad compress development costs for AI-native extraction modules, widening pricing spreads between premium cloud suites and economy-tier OCR tools. Indian SaaS vendors leverage this labor-cost arbitrage to undercut North American and European pricing by 40-60 percent while maintaining comparable extraction accuracy.
Pricing Analysis
Input-cost pass-through from cloud infrastructure and compliance certification expenses shapes vendor pricing architecture. Three-tier pricing structure across premium, standard, and economy levels separates AI-native platforms with predictive analytics from template-based OCR tools. Price differentiation rests on extraction accuracy thresholds and GDPR certification status. Pricing pressure stems from ERP vendors embedding native capture functionality into core financial suites. Mid-market enterprises in India exhibit highest price sensitivity, while North American financial services firms prioritize accuracy over cost.
Supply Chain Analysis
Dual-sourcing requirements from enterprise buyers mandate multi-supplier qualification for cloud infrastructure and data residency compliance. Software development concentrates in India, the United States, and Germany, with implementation services anchored in regional delivery centers. Raw material dependencies include GPU compute capacity, open-source ML frameworks, and API connectivity infrastructure. Supply chain risk centers on single-source vulnerability for specialized compliance modules in highly regulated verticals. Distribution runs through direct enterprise sales, channel partners, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between Indian development costs and North American compliance premiums creates margin expansion opportunities for vendors with dual-shore delivery models. RBI e-invoicing mandates and GDPR audit requirements impose divergent product architecture investments that favor regionally specialized players.
For Market Incumbents: Hedge against ERP-native substitution by deepening working capital convergence capabilities. Acquire machine learning specialists to defend extraction accuracy leadership against generative AI entrants. Expand compliance-module attach rates through CSRD emissions disclosure bundling.
For New Entrants and Emerging Players: Enter via India's unpenetrated mid-market tier where accountant shortages and UPI infrastructure create greenfield demand. Target hybrid deployment architectures for German manufacturers constrained by Federal Financial Supervisory Authority data sovereignty rules. Pursue API-first positioning to compress implementation timelines against legacy EDI providers.
For Investors and Strategic Acquirers: Cloud-native ERP vendors are the most active acquirer in this space, seeking invoice automation capabilities to complete treasury suite coverage. Long-term viability hinges on working capital optimization adjacencies beyond basic digitization. Monitor generative AI adoption rates in North American financial services as inflection indicator for platform switching cost erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies invoice automation with cash application and collections modules for working capital convergence. |
| Acquisition of Specialist Firm | Adds machine learning capabilities to defend extraction accuracy against generative AI entrants. |
| Strategic Partnership | Embeds payment orchestration through UPI and real-time rail integration in India. |
| Geographic Expansion | Establishes compliance-certified operations in Germany to serve Federal Financial Supervisory Authority-bound manufacturers. |
| Product Launch | Introduces CSRD-aligned emissions calculation engines for procurement sustainability reporting. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with treasury department heads, accounts-payable managers, ERP integration specialists, and compliance officers informed demand-side dynamics. Secondary sources include SEC filings, RBI regulatory circulars, GDPR implementation guidance, and hyperscaler partnership disclosures. Bottom-up deployment estimates triangulated against top-down software spend benchmarks.
Rate-of-change decomposition across deployment models, solution types, organization size tiers, vertical adoption patterns, and regional compliance clusters structured the analytical framework. CAGRs were derived from segment-level growth rate reconciliation across the analysis window. Forecast inputs incorporated cloud migration timelines, accountant shortage projections, and e-invoicing mandate implementation schedules.
Inputs from regulatory filings and vendor partnership announcements were available through the study window; gaps in private mid-market deployment data introduce uncertainty bands around India and Germany growth trajectories. Forecasts reflect assumptions regarding compliance deadline adherence and generative AI adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mainframe Software Market
Software & Services
Chatbot Builder Software Market
Software & Services
Stock Footage Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
Product Optimization Software Market
Software & Services
Low Code Development Platform Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Nonconformance Management Software Market
Software & Services
Global Order Management Software Market
Software & Services
Global Florist Software Market
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Batch Management Software Market
Software & Services
Federal Government Software Market
Software & Services
Global Log Management Software Market
Software & Services
Global CMMS Software Market
Software & Services
Global Architecture Design Software Market