
 Lenticular Sheet Market | 2026-2036
Lenticular Sheet Market Size, Share, and Industry Trends Forecast 2026-2036
Lenticular Sheet Market Foresight
Buyer concentration across large-format printing houses and retail brand procurement departments is decoupling from traditional sheet distributors as direct sourcing from Asian manufacturers accelerates. ORAFOL Fresnel Optics GmbH leverages its German precision optics heritage to dominate European quality-tier supply. Micro Lens Technology specializes in micro-lens arrays for security applications, sustaining niche margins that commodity converters cannot match. Hangzhou Donghuang Chemical anchors volume production for Asia-Pacific promotional markets through integrated PET resin-to-sheet operations.
Lenticular sheet denotes an extruded or cast polymer substrate embossed with an array of cylindrical or hemispherical lenses, typically manufactured from polyethylene terephthalate or polypropylene at lens densities ranging from 10 to 200 lines per inch, enabling autostereoscopic 3D effects, image flip, or animation without auxiliary eyewear. Custom Lenticular Sheets command premium positioning in limited-edition packaging and collector promotions where brand differentiation justifies tooling investment. Standard Lenticular Sheets retain volume leadership in mass-market advertising displays, though margin compression intensifies as Chinese extruders expand capacity. Holographic Lenticular Sheets represent the fastest-growing product type, fueled by anti-counterfeiting demand from pharmaceutical and luxury goods packaging sectors.
EPA guidelines on volatile organic compound emissions from solvent-based printing processes and REACH restrictions on certain plasticizers constrain material formulation choices for converters serving North American and European brand owners. China's GB standards for food-contact plastics and packaging safety, enforced by SAMR, dictate substrate compliance thresholds for domestic and export-bound sheet production. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or unified global product platforms yield superior compliance economics.
Market Dynamics
Direct sourcing from Hangzhou and Chengdu manufacturing clusters by large-format printing houses is decoupling procurement from traditional sheet distributors, compressing margin capture at intermediary tiers while accelerating price transparency across Asia-Pacific supply chains.
Growth Catalysts
- REACH compliance evolution:ECHA's tightening restrictions on phthalate plasticizers in PET substrates force converters toward certified resin streams, creating premium tier demand for compliant sheet supply.
- Pharmaceutical anti-counterfeiting mandates:Drug packaging security requirements from FDA and EMA drive holographic lenticular adoption for authentication features on high-value medication labels.
- Lens density advancement:Micro-lens array manufacturing at 150-200 LPI enables photorealistic autostereoscopy without eyewear, opening collector merchandise and limited-edition packaging applications.
Market Restraints
- Petrochemical input volatility:Purified terephthalic acid and ethylene glycol price swings from naphtha cracking economics transmit directly to sheet extrusion margins.
- Single-source tooling risk:Cylindrical lens master engraving equipment concentrates among German and Japanese precision optics suppliers, creating bottleneck vulnerability for new market entrants.
- Digital display substitution:LED video walls and e-paper signage capture share in retail advertising deployments where animation requirements previously favored lenticular displays.
Strategic Opportunities
- India packaging modernization:BIS standards alignment with ISO specifications for food-contact plastics creates compliant substrate demand from domestic FMCG brand owners.
- Security document convergence:Integration of micro-lens arrays with holographic foils and UV-fluorescent inks opens passport and currency substrate contracts.
- Direct-to-brand digital platforms:Alibaba and Made-in-China.com enable converter bypass of regional distributors for prototype and short-run orders.
Industry Challenges
- Color registration precision:Interlaced image alignment tolerances below 0.01mm demand skilled press operators scarce in emerging manufacturing regions.
- Multi-jurisdiction certification lag:Simultaneous FDA, EFSA, and GB standard compliance testing extends product launch timelines by 8-14 months for food-contact applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lenticular Sheet Market |
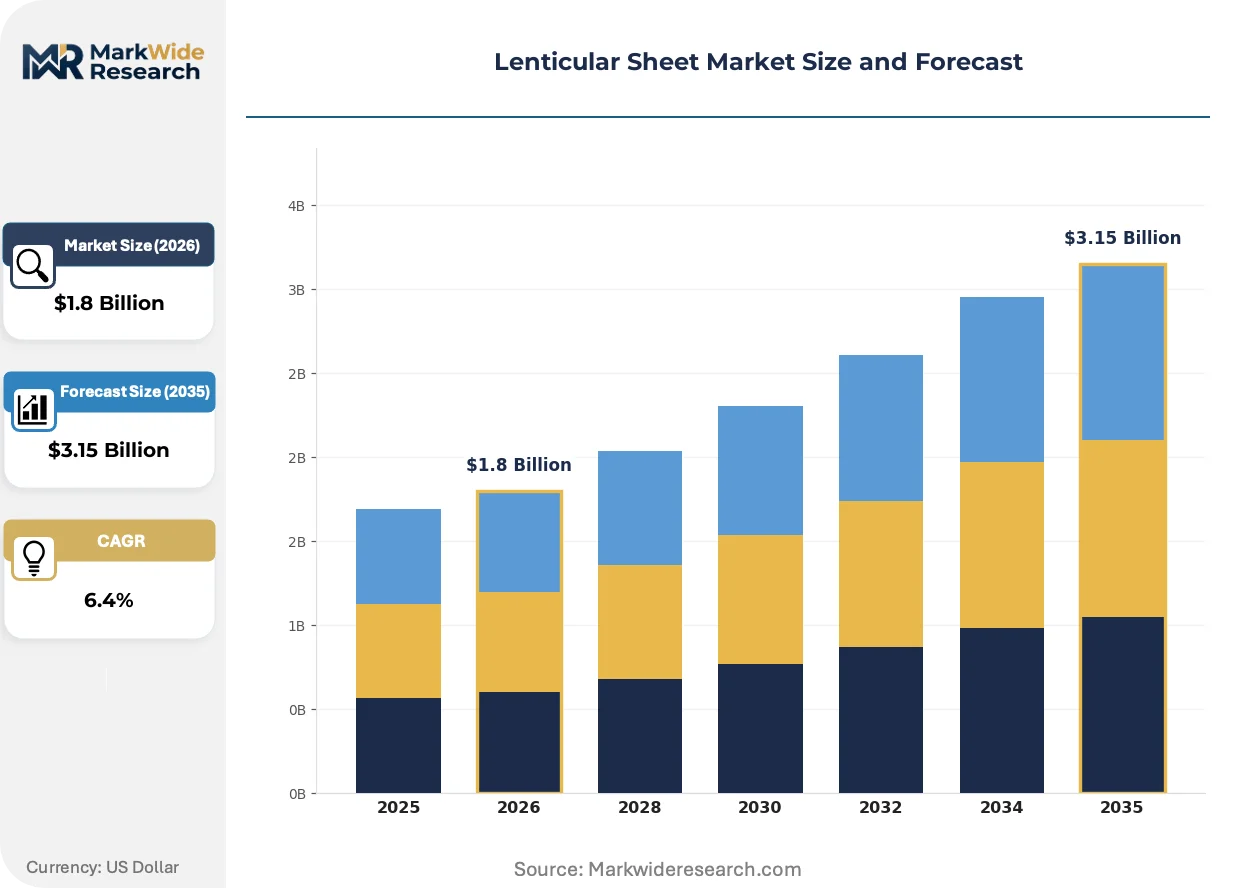
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lenticular Sheets, Custom Lenticular Sheets, 3D Lenticular Sheets, Holographic Lenticular Sheets Application: Advertising, Packaging, Greeting Cards, Promotions End User: Retail, Media, Entertainment, Manufacturing Size: A2, A3, A4, Custom Size |
| Companies Covered | ORAFOL Fresnel Optics GmbH, DPLenticular, Micro Lens Technology, Hangzhou Donghuang Chemical, NTKJ Co., Ltd., Pacur, 3M, Chengdu Kanglongxin Plastic, JacoTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lenticular Sheet Market Shifts & Advancements
Extrusion and printing process convergence is compressing the traditional separation between substrate manufacturing and finished display production, enabling integrated converters to capture value previously distributed across three supply chain tiers.
UV-curable inkjet interlacing is expanding into high-mix, low-volume promotional production. Brand marketing teams at beverage and cosmetics companies adopt this technology for campaign-specific prototypes with sub-48-hour turnaround. The elimination of physical printing plates collapses setup economics, enabling batch sizes below 500 sheets that rotary offset processes cannot address profitably.
EPA guidelines on volatile organic compound emissions from solvent-based lithographic processes now constrain North American converter operations. Brand owners serving California and Northeast markets face procurement restrictions that favor water-based and UV-cured alternatives. European sheet suppliers with pre-certified low-VOC coating lines capture displaced volume from domestic competitors lacking compliant finishing capacity.
Retail brand procurement departments now consolidate specification authority previously held by regional marketing managers. Centralized buying at headquarters level demands standardized substrate certifications across all geographic deployments, favoring sheet suppliers with multi-jurisdiction compliance documentation. This concentration compresses the qualified vendor base while extending contract durations for approved suppliers.
Lenticular Sheet Market Segmentation
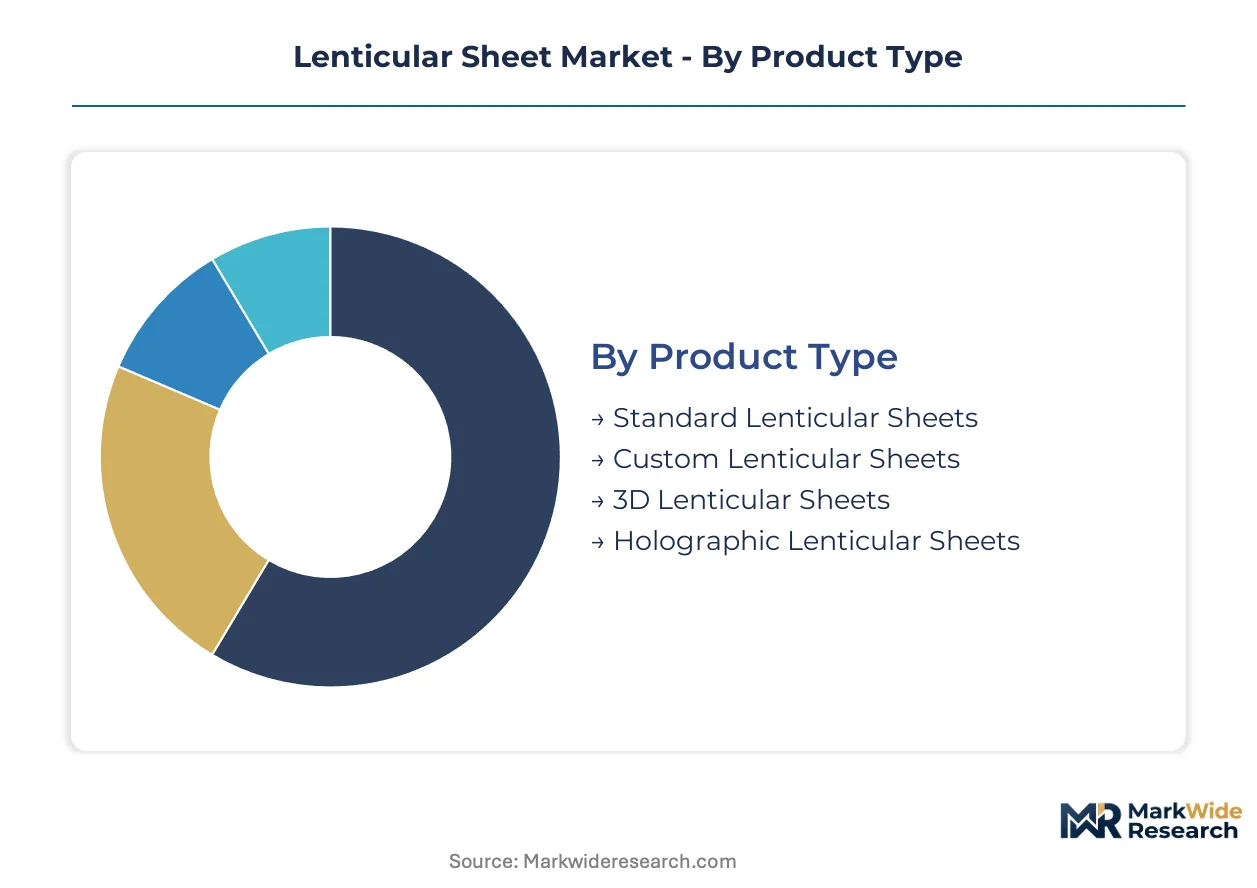
Lenticular sheet procurement splits sharply between commodity volume plays and precision-engineered premium tiers. Converters must align substrate specifications with end-use performance thresholds and regulatory compliance requirements across advertising, packaging, and security applications.
Product Type:
Volume leadership sits with standardized extrusions, while premium capture concentrates in customized and security-grade variants.
- Standard Lenticular Sheets:Mass-produced PET and PP substrates at 40-75 LPI serve high-volume advertising displays and retail signage. Procurement from Hangzhou and Chengdu manufacturing clusters compresses margins as direct sourcing bypasses traditional distributors.
- Holographic Lenticular Sheets:Micro-lens arrays integrated with diffractive optical elements enable authentication features for pharmaceutical and luxury goods packaging. FDA and EMA anti-counterfeiting mandates for high-value medication labels accelerate adoption faster than commodity segments.
- Custom Lenticular Sheets:Tooling-intensive production for limited-edition packaging and collector promotions where brand differentiation justifies per-project investment.
- 3D Lenticular Sheets:Autostereoscopic substrates at 100-150 LPI enable photorealistic depth effects without eyewear for entertainment and promotional applications.
Today's leader: Standard Lenticular Sheets. Tomorrow's challenger: Holographic Lenticular Sheets.
Application:
Advertising retains volume dominance, though packaging security requirements reshape growth trajectories.
- Advertising:Large-format displays and point-of-sale installations consume the majority of extruded sheet tonnage. LED video walls and e-paper signage now capture share in retail deployments where animation requirements previously favored lenticular solutions.
- Packaging:Pharmaceutical authentication labels and luxury goods protection drive holographic substrate demand. REACH compliance evolution and ECHA restrictions on phthalate plasticizers force converters toward certified resin streams for European-bound shipments.
- Promotions:Campaign-specific prototypes with sub-48-hour turnaround now feasible through UV-curable inkjet interlacing, collapsing traditional plate-based setup economics.
- Greeting Cards:Seasonal volume concentrated in mass-market retail channels with limited premium tier penetration.
Advertising commands current volume. Packaging security applications are climbing the fastest.
End User:
Retail procurement centralization is decoupling specification authority from regional marketing managers.
- Retail:Brand headquarters now consolidate buying decisions, demanding standardized substrate certifications across all geographic deployments. This concentration compresses qualified vendor bases while extending contract durations.
- Media:Entertainment promotions and collector merchandise drive micro-lens array adoption at 150-200 LPI for photorealistic autostereoscopy.
- Manufacturing:Integrated converters capture value across substrate production and finished display fabrication, compressing traditional three-tier supply chains.
- Entertainment:Limited-edition releases and franchise merchandise sustain custom tooling demand despite higher per-unit costs.
Retail dominates procurement scale. Media applications show steepest technology advancement.
Size:
Standard formats anchor volume, though custom dimensions capture premium positioning in specialized deployments.
- A2:Large-format substrates dominate outdoor advertising and retail window displays where visual impact at distance determines specification.
- A4:Document-scale sheets serve greeting cards, promotional mailers, and packaging inserts with standardized finishing equipment compatibility.
- A3:Mid-format applications span point-of-sale displays and medium-run promotional materials.
- Custom Size:Non-standard dimensions for architectural installations and specialized packaging prototypes command tooling premiums.
A2 leads in tonnage throughput. Custom Size commands highest margin per square meter.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled optics technicians and precision extrusion specialists concentrate in German industrial corridors and Chinese manufacturing clusters, anchoring regional supply capabilities for lenticular substrate production.
United States
Pharmaceutical packaging security requirements from FDA drive holographic lenticular adoption for high-value medication authentication labels. EPA guidelines on volatile organic compound emissions from solvent-based printing processes constrain converter operations in California and Northeast markets. Large-format printing houses in Chicago and Los Angeles now source directly from Asian manufacturers, bypassing traditional distributors.
Germany
REACH compliance evolution and ECHA restrictions on phthalate plasticizers in PET substrates force converters toward certified resin streams. Precision optics heritage sustains premium-tier supply for European quality-demanding applications. ORAFOL Fresnel Optics GmbH leverages its German manufacturing base to dominate regional high-specification segments.
China
GB standards for food-contact plastics and packaging safety, enforced by SAMR, dictate substrate compliance thresholds for domestic and export production. Promotional display demand from advertising agencies concentrates volume procurement. Hangzhou and Chengdu manufacturing clusters supply converters across Asia-Pacific through integrated PET resin-to-sheet operations.
Japan
Micro-lens array manufacturing at 150-200 LPI enables photorealistic autostereoscopy for entertainment and collector merchandise applications. METI industrial standards govern precision optics equipment deployment. Tokyo-Osaka industrial corridors host cylindrical lens master engraving capabilities concentrated among precision optics suppliers.
India
BIS standards alignment with ISO specifications for food-contact plastics creates compliant substrate demand from domestic FMCG brand owners. Packaging modernization across beverage and cosmetics sectors accelerates promotional display procurement. Maharashtra and Gujarat industrial zones attract converter investment for regional distribution hub development.
Lenticular Sheet Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base separates into three strategic archetypes: integrated resin-to-sheet operators capturing upstream margin, precision optics specialists commanding premium positioning, and regional converters serving localized promotional demand. Dominant competitive moves include backward integration into PET resin production and strategic partnerships with large-format printing houses for direct supply relationships.
Within the precision optics tier, ORAFOL Fresnel Optics GmbH exemplifies European quality-tier supply anchored in German manufacturing heritage. Among Chinese integrated operators, Hangzhou Donghuang Chemical occupies a position representing volume-scale resin-to-sheet production for Asia-Pacific promotional markets. Micro Lens Technology sits within the security-specialist archetype, sustaining niche margins through micro-lens array capabilities that commodity converters cannot match.
| Leading Market Players |
|---|
| ORAFOL Fresnel Optics GmbH |
| DPLenticular |
| Micro Lens Technology |
| Hangzhou Donghuang Chemical |
| NTKJ Co., Ltd. |
| Pacur |
| 3M |
| Chengdu Kanglongxin Plastic |
| JacoTech |
| Others |
Supply & Pricing Matrix
Retail brand procurement centralization demands standardized substrate certifications across geographic deployments, forcing sheet suppliers to absorb multi-jurisdiction compliance costs or forfeit contract eligibility, which compresses margin capture at intermediary tiers while accelerating direct sourcing from Asian manufacturers.
Pricing Analysis
Capacity additions in China are reshaping price floors across Asia-Pacific promotional markets. Three-tier pricing structure across premium, standard, and economy levels separates ORAFOL Fresnel Optics GmbH's REACH-certified European supply from Hangzhou Donghuang Chemical's volume-grade extrusions and unbranded commodity converters. Price differentiation hinges on certification tier and lens density precision. Cost compression in standard-grade PET substrates is intensifying because direct procurement bypasses traditional distributor markups. Mass-market advertising agencies exhibit highest price sensitivity, while pharmaceutical brand owners prioritize anti-counterfeiting performance over unit economics.
Supply Chain Analysis
Purified terephthalic acid supply rests on naphtha cracking economics in China, South Korea, and Saudi Arabia. Raw material dependencies include ethylene glycol, PET resin pellets, and cylindrical lens master engraving equipment. Geographic supply concentration in Hangzhou and Chengdu manufacturing clusters creates single-source vulnerability for high-volume converters. Distribution runs through direct digital platforms including Alibaba and Made-in-China.com, enabling converter bypass of regional distributors for prototype and short-run orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Lenticular Sheet Market functions as a stable compounder, with pharmaceutical anti-counterfeiting mandates providing non-cyclical demand insulation against digital display substitution in advertising segments.
For Market Incumbents: Deepen backward integration into PET resin production to capture upstream margin and insulate against purified terephthalic acid price volatility. Prioritize multi-jurisdiction certification investment—simultaneous FDA, EFSA, and GB standard compliance—to defend contract eligibility as retail procurement centralization compresses qualified vendor bases. LED video walls and e-paper signage substitution in retail advertising represents the primary demand threat requiring defensive portfolio repositioning toward security applications. For New Entrants and Emerging Players: Domestic FMCG brand owners in India represent an underserved buyer archetype with packaging modernization requirements and BIS standards alignment creating compliant substrate demand. Security document convergence—integrating micro-lens arrays with holographic foils and UV-fluorescent inks—offers the most penetrable white-space for passport and currency substrate contracts. Pursue UV-curable inkjet interlacing technology partnerships to enable sub-48-hour prototype turnaround for campaign-specific promotional orders. For Investors and Strategic Acquirers: Asymmetric upside sits with precision optics specialists possessing cylindrical lens master engraving capabilities concentrated among German and Japanese equipment suppliers. The five-to-ten-year viability window favors acquisition targets with captive micro-lens array manufacturing at 150-200 LPI, as pharmaceutical and luxury goods packaging security requirements harden demand for authentication-grade substrates. Watch ECHA's evolving REACH restrictions on phthalate plasticizers as the inflection signal that determines which resin-to-sheet operators capture displaced premium-tier volume.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Resin | Hangzhou Donghuang Chemical's captive supply of purified terephthalic acid insulates margin from naphtha cracking volatility. |
| Multi-Jurisdiction Certification Investment | Simultaneous FDA, EFSA, and SAMR compliance documentation extends contract duration with centralized retail procurement departments. |
| Micro-Lens Array Capacity Expansion | 150-200 LPI manufacturing enables photorealistic autostereoscopy for pharmaceutical authentication labels under FDA mandates. |
| Direct Digital Platform Enablement | Alibaba and Made-in-China.com integration captures prototype and short-run orders previously lost to traditional distributors. |
| Security Document Convergence Partnership | Integration with holographic foil and UV-fluorescent ink suppliers opens passport and currency substrate contract access. |
Research Methodology
Direct dialogue with sheet extrusion plant managers, procurement leads at large-format printing houses, brand marketing directors at pharmaceutical and luxury goods companies, and distribution channel partners across Asia-Pacific and Europe grounded the qualitative foundation. Secondary validation drew from customs and trade data, SEC 10-K filings of diversified materials conglomerates, SAMR enforcement notices on GB standards, and ECHA regulatory guidance documents. Bottom-up and top-down triangulation reconciled volume estimates from converter capacity utilization with demand-side procurement surveys.
Bottom-up modeling segmented the market by product type, application, end user, and geographic production hub across the analysis window. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity buildout schedules. Industry-specific forecast inputs included lens density advancement trajectories from precision optics equipment suppliers and pharmaceutical packaging security mandate implementation timelines from FDA and EMA.
Inputs from primary interviews and regulatory filings were available through the study window; gaps in real-time converter inventory data and proprietary lens master engraving equipment utilization rates introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions on REACH compliance evolution and digital display substitution rates. A small set of named triggers—ECHA plasticizer restrictions, LED video wall cost curves, and India BIS enforcement intensity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Polyvinyl Alcohol (PVA) Market
Chemicals & Materials
Propionic Acid Market
Chemicals & Materials
Wood Fiber Insulation Market
Chemicals & Materials
Global Caffeic Acid Market
Chemicals & Materials
Inhibited Propylene Glycol Market
Chemicals & Materials
Sulphur Recovery Technologies Market
Chemicals & Materials
Canada Methanol Market
Chemicals & Materials
Laboratory Centrifuge and Accessories Market
Chemicals & Materials
Rare Earth Magnet Market
Chemicals & Materials
Ethyl Polysilicate Market
Chemicals & Materials
Global Thin Papers Market
Chemicals & Materials
Potassium Feldspar Market
Chemicals & Materials
Global Industrial Denox Systems and Services Market
Chemicals & Materials
Diethylhydroxylamine (DEHA) Market
Chemicals & Materials
Green Composites Market
Chemicals & Materials
Europe Lime Market