
 Polyhedral Oligomeric Silsesquioxanes (POSS) Market | 2026-2036
Polyhedral Oligomeric Silsesquioxanes (POSS) Market Size, Share, and Industry Trends Forecast 2026-2036
Polyhedral Oligomeric Silsesquioxanes (POSS) Market Analytics
Aerospace end-use is consolidating share within the POSS consumption matrix as thermal management requirements intensify for next-generation airframes. Hybrid Plastics leverages its Mississippi-based production footprint to dominate North American supply of cage-structured silsesquioxanes. Shin-Etsu Chemical sustains technology leadership through proprietary hydrolytic condensation processes that yield high-purity monomer grades.
Polyhedral oligomeric silsesquioxanes are nanostructured hybrid materials with empirical formula RSiO1.5, where R denotes organic substituents; their 1-3 nm cage frameworks embed within polymer matrices to enhance thermal stability, mechanical strength, and flame retardancy without sacrificing processability. Functionalized POSS variants command premium positioning due to tailored surface chemistry that enables covalent grafting to thermoset and thermoplastic hosts. The coatings application segment anchors volume demand, while composites applications exhibit the fastest specification growth as automotive and aerospace OEMs validate structural lightweighting protocols.
EPA oversight governs nanomaterial reporting obligations in the United States, while REACH registration requirements in Europe mandate extensive toxicological dossiers for silsesquioxane substances imported above one-tonne thresholds. FDA engagement with nanotechnology-enabled medical devices creates additional compliance pathways for healthcare-grade POSS formulations. Stakeholders must monitor evolving regulatory thresholds for molecular-scale additives across multiple jurisdictions to preserve market access and avoid reformulation costs.
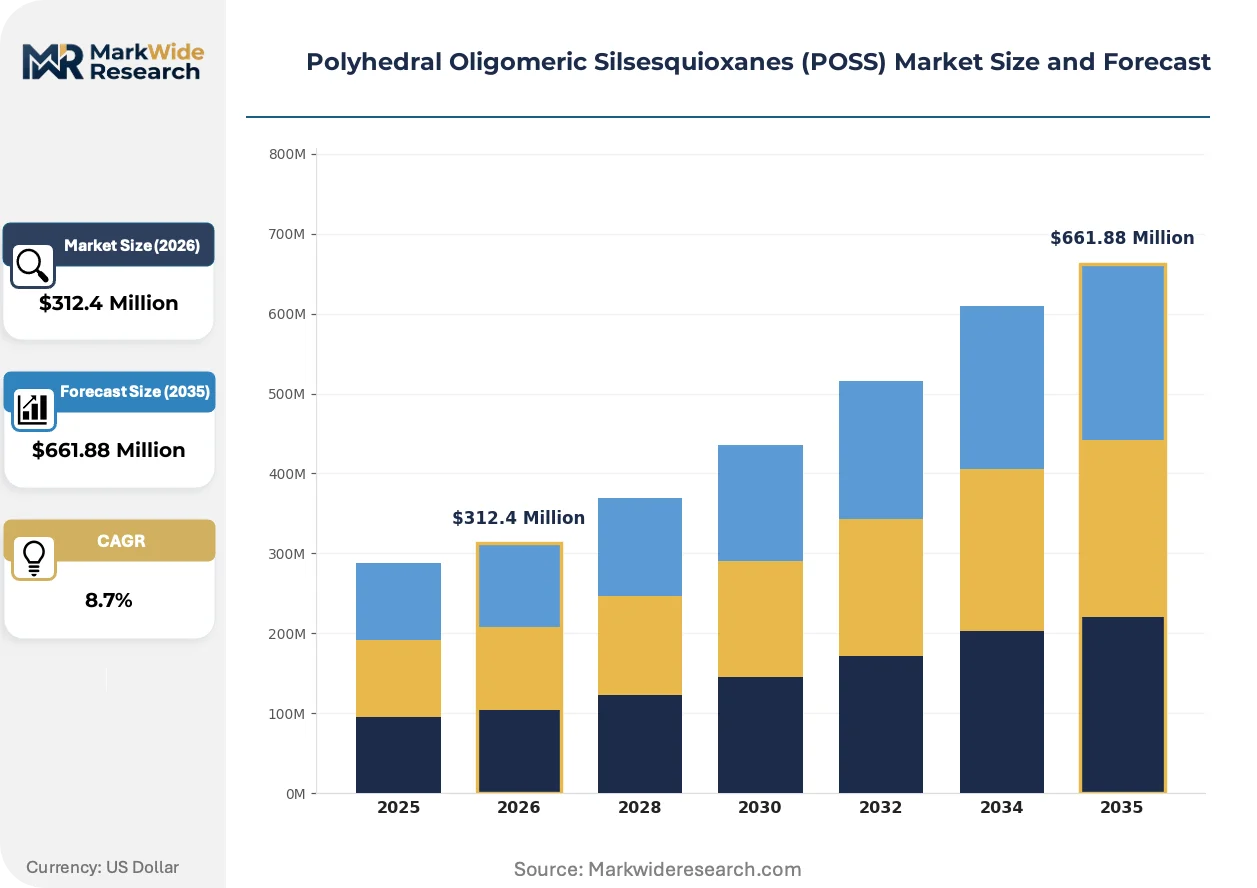
Market Dynamics
Aerospace OEMs are consolidating thermal management specifications around cage-structured silsesquioxanes as next-generation airframes demand materials that withstand 300°C operational thresholds without weight penalties. This specification pull is compressing qualification timelines and forcing raw material suppliers to synchronize R&D cycles with platform development schedules.
Growth Catalysts
- Thermal barrier mandates:FAA airworthiness directives for engine nacelle fire protection are accelerating specification-grade POSS adoption in propulsion systems. Composite manufacturers must demonstrate 15-minute flame resistance to secure platform qualification.
- REACH registration thresholds:ECHA's one-tonne silsesquioxane import requirement is consolidating supply relationships around dossier-compliant producers. German automotive OEMs now require REACH-compliant certificates for all nanostructured additives in interior applications.
- Hydrolytic condensation advances:Proprietary condensation processes are yielding monodisperse cage distributions that reduce batch-to-batch variability. Electronics packaging engineers specify these grades for underfill applications requiring precise viscosity control.
Market Restraints
- Chlorosilane feedstock volatility:Price swings in methyltrichlorosilane and phenyltrichlorosilane compress formulation margins unpredictably. POSS producers lack backward integration into chlorosilane supply, exposing them to petrochemical derivative cycles.
- Mississippi supply concentration:North American cage-structured silsesquioxane production clusters in a single Gulf Coast corridor. Hurricane disruption risk concentrates with each season, forcing buyers to maintain six-month safety stocks.
- Epoxy-amine substitution threat:Graphene oxide and carbon nanotube dispersions compete for thermal conductivity enhancement in aerospace prepregs. These alternatives avoid cage synthesis complexity and offer comparable in-plane conductivity at lower loading levels.
Strategic Opportunities
- India specialty chemical expansion:PLI scheme incentives for advanced materials are attracting formulation joint ventures near Pune and Vadodara clusters. Domestic automotive OEMs seek localized POSS supply for EV battery module encapsulation.
- Medical device convergence:FDA nanotechnology guidance for implantable devices creates a compliance pathway for healthcare-grade silsesquioxanes. Orthopedic coating manufacturers are evaluating POSS-grafted polyethylene for wear resistance in joint replacements.
- 3D printing resin integration:Photocurable POSS macromers enable voxel-level thermal management in additive manufacturing. Aerospace maintenance organizations are qualifying these materials for on-demand heat shield fabrication.
Industry Challenges
- Organosilicon synthesis expertise scarcity:Hydrolytic condensation process optimization requires chemists trained in sol-gel transition kinetics. Universities have shuttered dedicated silsesquioxane research programs, forcing producers to develop in-house apprenticeship pipelines.
- Multijurisdictional dossier maintenance:REACH, EPA TSCA, and FDA submissions demand parallel toxicological studies with non-overlapping protocols. Regulatory affairs teams must track substance identity definitions that diverge across agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyhedral Oligomeric Silsesquioxanes (POSS) Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monomers, Oligomers, Functionalized POSS, Silane-Modified POSS End Use Industry: Electronics, Aerospace, Automotive, Healthcare Application: Coatings, Composites, Adhesives, Sealants Sales Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Hybrid Plastics, Shin-Etsu Chemical, Sigma-Aldrich, Wacker Chemie, Dow Inc., Evonik Industries, Reade International, Alfa Chemistry, Nanoshel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyhedral Oligomeric Silsesquioxanes (POSS) Market Evolving Landscape
Functionalization chemistry is bifurcating into two development tracks: covalent grafting for thermoset matrices and physical dispersion for thermoplastic hosts. This technical divergence is fragmenting R&D budgets and creating distinct supplier qualification pathways.
Fluorinated POSS variants are electrifying aerospace radome applications by delivering dielectric constants below 2.5 with hydrophobic surface energies. Boeing and Airbus specification teams have accelerated validation protocols for these materials in nose cone assemblies. The technology is compressing traditional PTFE-based laminate designs out of next-generation platforms.
ECHA's 2023 update to REACH Annex XVII restrictions on persistent organic pollutants is forcing reformulation of legacy silsesquioxane catalyst residues. European coating formulators must demonstrate complete removal of tin-based condensation catalysts to maintain import authorization. German automotive Tier-1 suppliers are auditing their additive supply chains for compliance documentation gaps.
Specification-driven procurement is consolidating buying power among aerospace primes and automotive OEMs. Smaller compounders now face technical service demands that exceed their analytical capabilities, pushing them toward toll manufacturing arrangements. This pattern is most visible in Germany, where Volkswagen and BMW have centralized nanostructured additive qualification within their materials engineering centers.
Polyhedral Oligomeric Silsesquioxanes (POSS) Market Segmentation
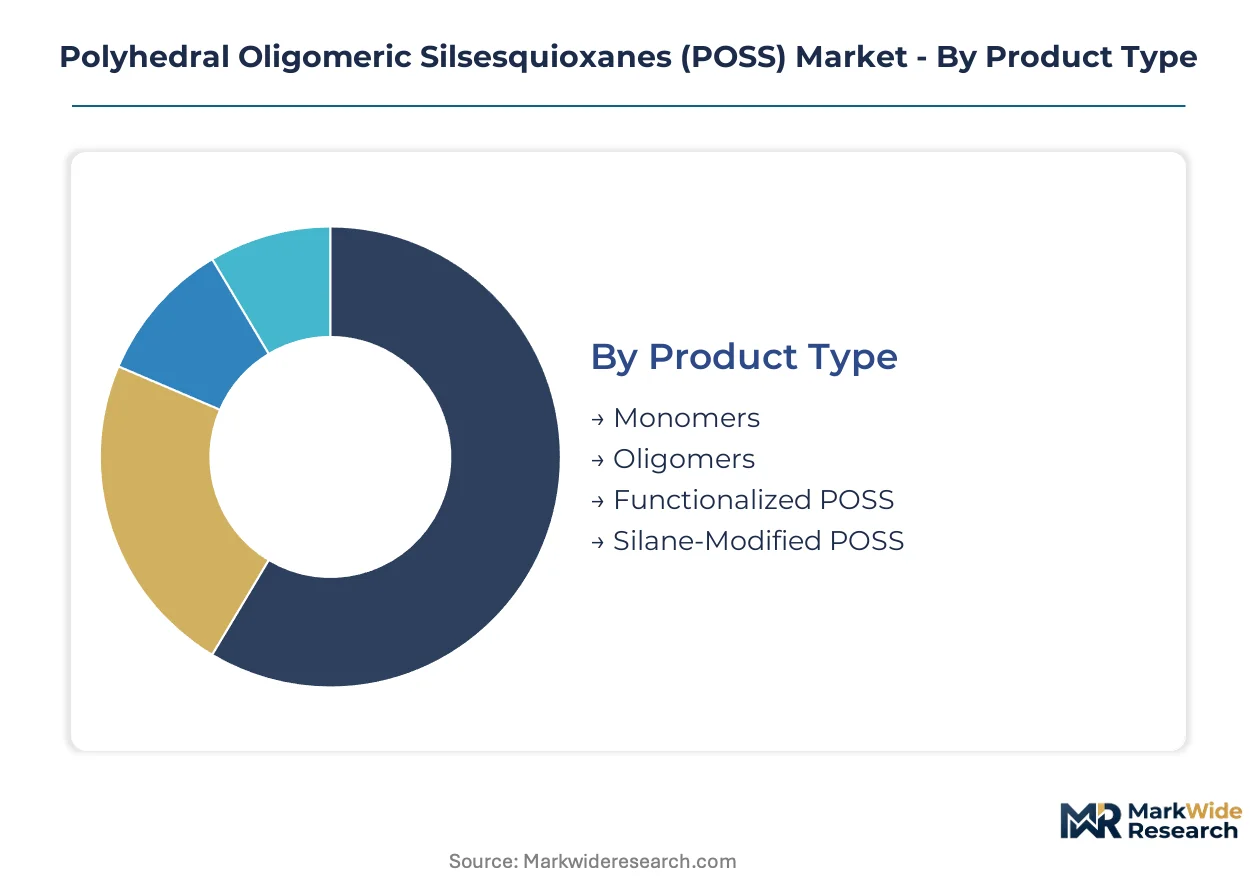
POSS segmentation reflects divergent technical requirements across cage architectures and functional chemistries. Specification-grade buyers demand validated dossiers for each variant, fragmenting supplier qualification pathways.
Product Type:
Standardization intensity varies sharply across this category, from commodity monomer streams to bespoke functionalized architectures requiring synthesis-to-order protocols.
- Monomers:These RSiO1.5 building blocks feed captive condensation operations at major polymer compounders. German automotive OEMs specify monomer purity grades above 99.5% for interior composite applications governed by REACH dossier requirements.
- Functionalized POSS:Tailored surface chemistries enable covalent grafting to thermoset matrices through epoxy, methacrylate, or thiol reactive groups. Aerospace qualification timelines for these variants compress to 18 months as Boeing and Airbus consolidate thermal barrier specifications.
- Oligomers:Partially condensed frameworks bridge monomer and fully formed cage properties.
- Silane-Modified POSS:Hydrophobic surface treatments target moisture-sensitive electronics packaging.
Leading the category by volume: Monomers. Growing fastest: Functionalized POSS.
End Use Industry:
Margin profiles diverge across this category based on regulatory burden intensity and qualification cycle length.
- Aerospace:FAA airworthiness mandates for 300°C thermal stability and 15-minute flame resistance dominate specification development. Mississippi-based producers synchronize R&D cycles with Gulf Coast aerospace cluster platform schedules.
- Electronics:Underfill and encapsulation applications demand monodisperse cage distributions for precise viscosity control. Japanese semiconductor packaging engineers specify hydrolytic condensation grades for flip-chip reliability.
- Automotive:EV battery module encapsulation drives specification-grade consumption near Pune and Vadodara clusters under India's PLI scheme incentives.
- Healthcare:FDA nanotechnology guidance for implantable devices creates compliance pathways for orthopedic coating applications.
Highest margin capture: Aerospace. Steepest expansion trajectory: Healthcare.
Application:
Volume concentration versus value capture splits this category between mature coating formulations and emerging composite architectures.
- Coatings:Thermal barrier and corrosion-resistant formulations anchor baseline demand. ECHA's 2023 REACH Annex XVII update forces tin-based catalyst residue removal, auditing European formulator supply chains for compliance documentation.
- Composites:Structural lightweighting protocols in next-generation airframes validate cage-structured silsesquioxanes at loadings below 5% by weight. German automotive Tier-1 suppliers centralize nanostructured additive qualification within materials engineering centers.
- Adhesives:High-temperature joint bonding applications leverage POSS-enhanced thermal stability without plasticization.
- Sealants:Hydrophobic cage frameworks improve moisture resistance in electronics and aerospace gasket applications.
Volume anchor: Coatings. Climbing the fastest: Composites.
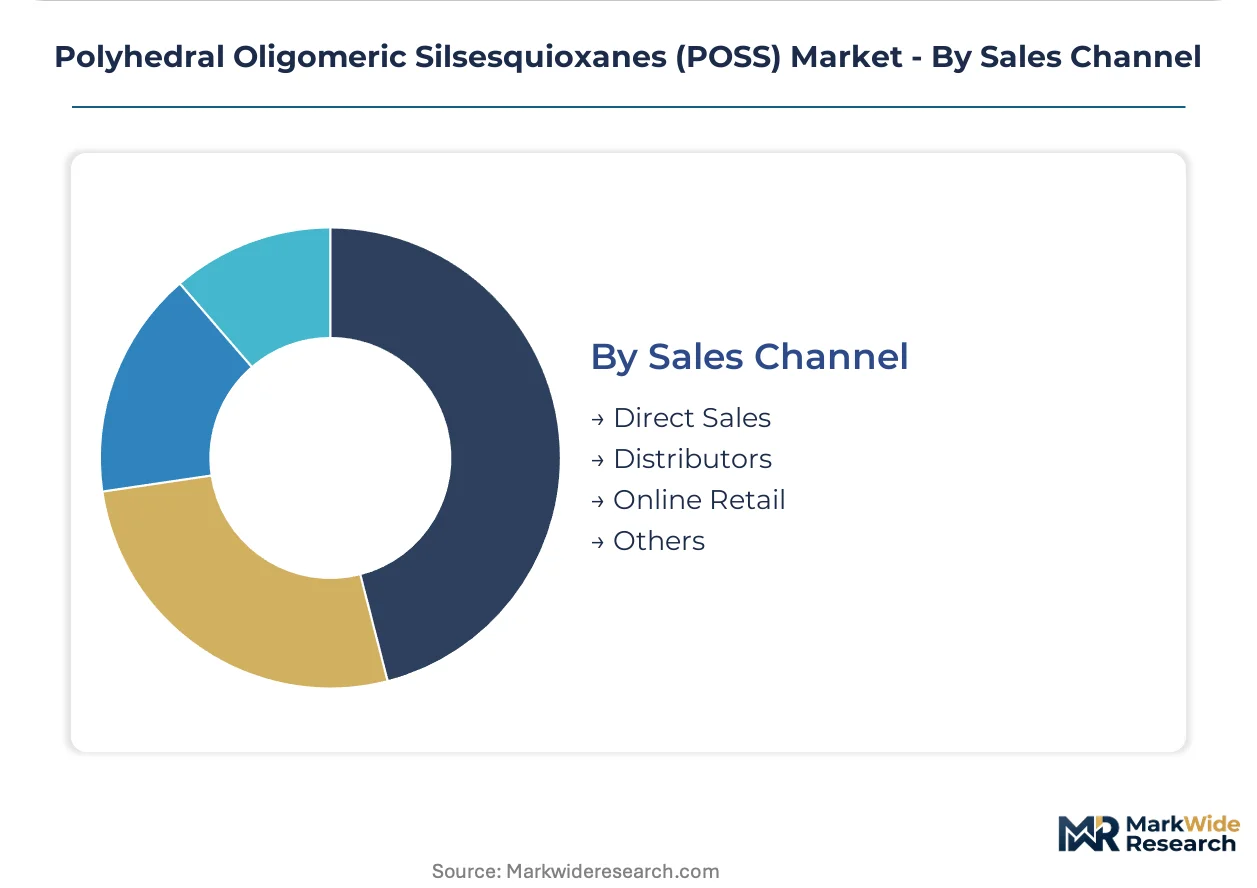
Sales Channel:
Relationship intensity and technical service depth define channel selection across customer tiers.
- Direct Sales:Aerospace primes and automotive OEMs mandate dedicated account teams for specification development. Hybrid Plastics maintains direct relationships with Gulf Coast composite manufacturers for cage-structured supply security.
- Distributors:Regional chemical distributors serve mid-tier compounders lacking internal analytical capabilities for nanomaterial characterization.
- Online Retail:Catalog sales concentrate in research-grade quantities for university and startup R&D programs.
- Others:Toll manufacturing arrangements emerge as smaller compounders face technical service demands exceeding internal capabilities.
Dominant channel by value: Direct Sales. Gaining share fastest: Toll manufacturing arrangements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in the United States Gulf Coast corridor, while consumption fragments across German automotive clusters, Japanese electronics packaging hubs, and Indian EV battery corridors. This geographic mismatch forces buyers to manage transoceanic supply security and hurricane disruption risk.
United States
Aerospace OEMs in the Gulf Coast cluster drive specification-grade demand for thermal barrier applications in engine nacelles. FAA airworthiness directives mandate 15-minute flame resistance for composite structures. Mississippi-based producers synchronize R&D cycles with Boeing and Gulfstream platform development schedules.
Germany
Automotive OEMs and specialty chemical clusters anchor European consumption of REACH-compliant silsesquioxane grades. ECHA's one-tonne import threshold consolidates supply relationships around dossier-compliant producers. Volkswagen and BMW centralize nanostructured additive qualification within their materials engineering centers in Bavaria and Baden-Württemberg.
Japan
Semiconductor packaging engineers specify hydrolytic condensation grades for flip-chip underfill applications requiring precise viscosity control. METI's advanced materials initiatives support domestic production of monodisperse cage distributions. Osaka-based electronics manufacturers validate these materials for high-reliability consumer devices.
India
Domestic automotive OEMs seek localized POSS supply for EV battery module encapsulation under PLI scheme incentives. BIS standards for advanced materials create compliance frameworks for imported nanostructured additives. Formulation joint ventures concentrate near Pune and Vadodara specialty chemical clusters.
China
Electronics manufacturing scale drives consumption of silane-modified POSS for moisture-sensitive packaging applications. MIIT's dual carbon goals pressure domestic producers to reduce chlorosilane synthesis emissions. Yangtze River Delta coating formulators audit supply chains for tin-based catalyst residue compliance.
Polyhedral Oligomeric Silsesquioxanes (POSS) Market Competitive Landscape
Top-tier vendors anchor specification-grade supply, while mid-tier compounders face technical service demands exceeding internal analytical capabilities. The vendor base stratifies across cage synthesis specialists, diversified chemical conglomerates with organosilicon divisions, and research-grade distributors serving university programs. Dominant competitive moves include toll manufacturing arrangements for smaller compounders and REACH dossier consolidation among European producers.
Within the cage synthesis specialist tier, Hybrid Plastics and Shin-Etsu Chemical exemplify production-scale capability anchored in distinct geographies. Sigma-Aldrich occupies a position bridging research-grade distribution and specification development support. Wacker Chemie and Dow Inc. represent diversified chemical conglomerates leveraging backward integration into chlorosilane feedstocks.
| Leading Market Players |
|---|
| Hybrid Plastics |
| Shin-Etsu Chemical |
| Sigma-Aldrich |
| Wacker Chemie |
| Dow Inc. |
| Evonik Industries |
| Reade International |
| Alfa Chemistry |
| Nanoshel |
| Others |
Value Network & Pricing Analysis
REACH Annex XVII catalyst residue mandates gate qualified supply and premium-tier pricing access for European coating formulators. German automotive OEMs now audit supply chains for tin-based condensation catalyst documentation, compressing margins for non-compliant producers while elevating dossier-validated grades.
Pricing Analysis
Margin tightening in specification-grade monomers reflects chlorosilane feedstock volatility and REACH compliance certification costs. Three-tier pricing structure across aerospace-qualified, automotive-grade, and research-tier separates buyers by validation burden and volume scale. Cost-down pressure on standard monomer streams accelerates because phenyltrichlorosilane spot markets swing with petrochemical derivative cycles. Mid-tier compounders exhibit highest price sensitivity; aerospace primes absorb premium tiers for platform qualification security.
Supply Chain Analysis
India's PLI scheme domestic-content mandates reshape sourcing for EV battery encapsulation grades near Pune and Vadodara. Production gravity centers on the United States Gulf Coast, Germany's specialty chemical corridor, and Japan's electronics packaging hub. Chlorosilane feedstocks, hydrolytic condensation catalysts, and purification solvents anchor raw material dependencies. Hurricane disruption risk concentrates Mississippi supply, forcing six-month safety stock maintenance. Distribution runs through direct account teams for specification-grade buyers and regional distributors for mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where chlorosilane feedstock control determines margin sustainability. Players pursue backward integration into methyltrichlorosilane supply to escape petrochemical derivative volatility.
For Market Incumbents: Anticipate graphene oxide and carbon nanotube substitution threats in aerospace thermal conductivity applications by accelerating REACH dossier consolidation and locking long-term supply agreements with German automotive OEMs. Deepen captive chlorosilane production to compress formulation margins against non-integrated competitors. For New Entrants and Emerging Players: Capture white-space in India's EV battery module encapsulation segment under PLI scheme incentives, where domestic automotive OEMs seek localized supply. Target toll manufacturing arrangements for European coating formulators facing ECHA catalyst residue audits. Lead with technical service capabilities exceeding mid-tier compounder analytical limits. For Investors and Strategic Acquirers: FAA airworthiness directive acceleration for 15-minute flame resistance is the leading indicator that aerospace specification-grade capacity will command scarcity premiums. Frame long-term viability around hydrolytic condensation process expertise as university silsesquioxane programs shutter. Monitor organosilicon synthesis apprenticeship pipeline development as inflection signal for producer moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstocks | Captive methyltrichlorosilane supply insulates margins from petrochemical derivative cycles. |
| REACH Dossier Consolidation | ECHA-compliant producers secure exclusive supply relationships with German automotive OEMs. |
| Hydrolytic Condensation Process Scale-Up | Monodisperse cage distributions command premium positioning in electronics underfill applications. |
| Joint Venture in India PLI Corridors | Localized production captures EV battery encapsulation demand near Pune and Vadodara clusters. |
| Medical Device Grade Certification Pathway | FDA nanotechnology guidance compliance opens orthopedic coating applications for joint replacements. |
Research Methodology
Trade databases, ECHA registration filings, and SEC chemical company disclosures formed the secondary backbone for this analysis. Primary interviews with plant managers at cage synthesis facilities, procurement leads at aerospace composite manufacturers, technical R&D directors at coating formulators, and regulatory affairs specialists at automotive OEMs validated demand-side assumptions. Bottom-up segment sizing and top-down cross-checks triangulated volume estimates across the analysis window.
Historical trendline analysis of silsesquioxane import volumes and chlorosilane price indices anchored the forecast framework. Segmentation dimensions modeled include cage architecture type, functional chemistry tier, end-use industry vertical, application format, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualification timeline compression and platform adoption rates. Forecast inputs incorporated FAA airworthiness directive implementation schedules and ECHA Annex XVII enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance identity definition changes and hurricane disruption frequency in the Gulf Coast corridor. Forecasts reflect documented assumptions around platform development cycle synchronization and chlorosilane supply stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals & Materials
Perfluoroalkoxy Alkane (PFA) Market
Chemicals & Materials
Mica Sheet Market
Chemicals & Materials
Coumarin Market
Chemicals & Materials
Europe Lubricants Market
Chemicals & Materials
Asia-Pacific Epoxy Powder Coatings Market
Chemicals & Materials
Glycerine Market
Chemicals & Materials
Global UV Curable Resins Market
Chemicals & Materials
Electronic Chemicals Market
Chemicals & Materials
Isobutyraldehyde Market
Chemicals & Materials
Activated Carbon for Sugar Decolorization Market
Chemicals & Materials
General Industrial Oils Market
Chemicals & Materials
Middle-East and Africa Waterborne Adhesives Market
Chemicals & Materials
Mixed Acetic and Tartaric Acid Esters of Mono and Diglycerides of Fatty Acids Market
Chemicals & Materials
Atelocollagen Market
Chemicals & Materials
Polyimide Varnish Market
Chemicals & Materials
Global Soft Magnetic Alloys Market