
 Laurel Oil Market | 2026-2036
Laurel Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Laurel Oil Market Analytics
Skilled distillation craftsmanship in traditional laurel-growing regions is redrawing competitive boundaries as mechanized extraction struggles to replicate cold-pressed oil profiles. doTERRA International leverages direct sourcing partnerships with Moroccan cooperatives to secure consistent Laurus nobilis feedstock. Young Living Essential Oils anchors its supply through vertically integrated farms in the Mediterranean basin. Biolandes competes by specializing in pharmaceutical-grade extraction protocols that meet European pharmacopeia standards.
Laurel oil is an essential oil steam-distilled from Laurus nobilis leaves, yielding a pale yellow liquid with eucalyptol and linalool as dominant constituents, traditionally employed for antimicrobial, anti-inflammatory, and aromatic applications in personal care and therapeutic formulations. Essential oils command the dominant value share due to concentrated therapeutic positioning, while carrier oils represent the fastest-expanding category as clean-label cosmetic brands dilute actives into skin-safe bases. The aromatherapy application segment sustains premium pricing power, whereas medicinal use segments face tighter pharmacopeial compliance costs that compress margins for non-specialized processors.
REACH registration requirements in Europe and FDA cosmetic ingredient guidelines in the United States shape formulation standards and market access protocols for laurel oil imports. EFSA novel food evaluations and USDA organic certification further segment commercial viability between food-grade and cosmetic-grade supply chains. Stakeholders must monitor evolving botanical ingredient disclosure mandates across multiple jurisdictions to anticipate reformulation costs and sourcing redirections.
Market Dynamics
Traditional distillation craftsmanship in Morocco and Turkey is redrawing competitive boundaries as mechanized extraction struggles to replicate cold-pressed oil profiles with equivalent eucalyptol and linalool signatures. This supply-side concentration shapes pricing power and quality differentiation across cosmetic and pharmaceutical channels.
Growth Catalysts
- Cosmetic formulator demand:Clean-label brands dilute actives into skin-safe bases, expanding carrier oil uptake for sensitive-skin formulations.
- REACH registration:European pharmacopeia standards tighten specifications, rewarding processors with compliant extraction protocols.
- Aromatherapy premium positioning:Therapeutic-grade volumes command sustained price premiums in wellness and spa distribution channels.
Market Restraints
- Raw material concentration:Laurus nobilis leaf supply clusters in Mediterranean sourcing corridors, exposing buyers to Moroccan and Turkish harvest volatility.
- Pharmacopeial compliance costs:EFSA novel food evaluations compress margins for non-specialized processors entering food-grade segments.
- Synthetic antimicrobial substitutes:Petrochemical preservatives compete on cost in mass-market personal care, limiting natural oil penetration in price-sensitive tiers.
Strategic Opportunities
- USDA organic certification tailwind:North American certification shifts reward processors with verified supply chain documentation.
- Pharmaceutical-grade extraction convergence:Supercritical CO2 methods combined with traditional steam distillation unlock higher-purity therapeutic fractions.
- Direct-to-formulator channels:Bypassing traditional distributors, Moroccan cooperatives sell bulk volumes directly to European cosmetic manufacturers.
Industry Challenges
- Distiller skill scarcity:Cold-pressed oil expertise concentrates in aging artisan networks across traditional growing regions.
- Multi-jurisdictional disclosure mandates:Botanical ingredient labeling requirements in the US, EU, and Japan force parallel compliance investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laurel Oil Market |
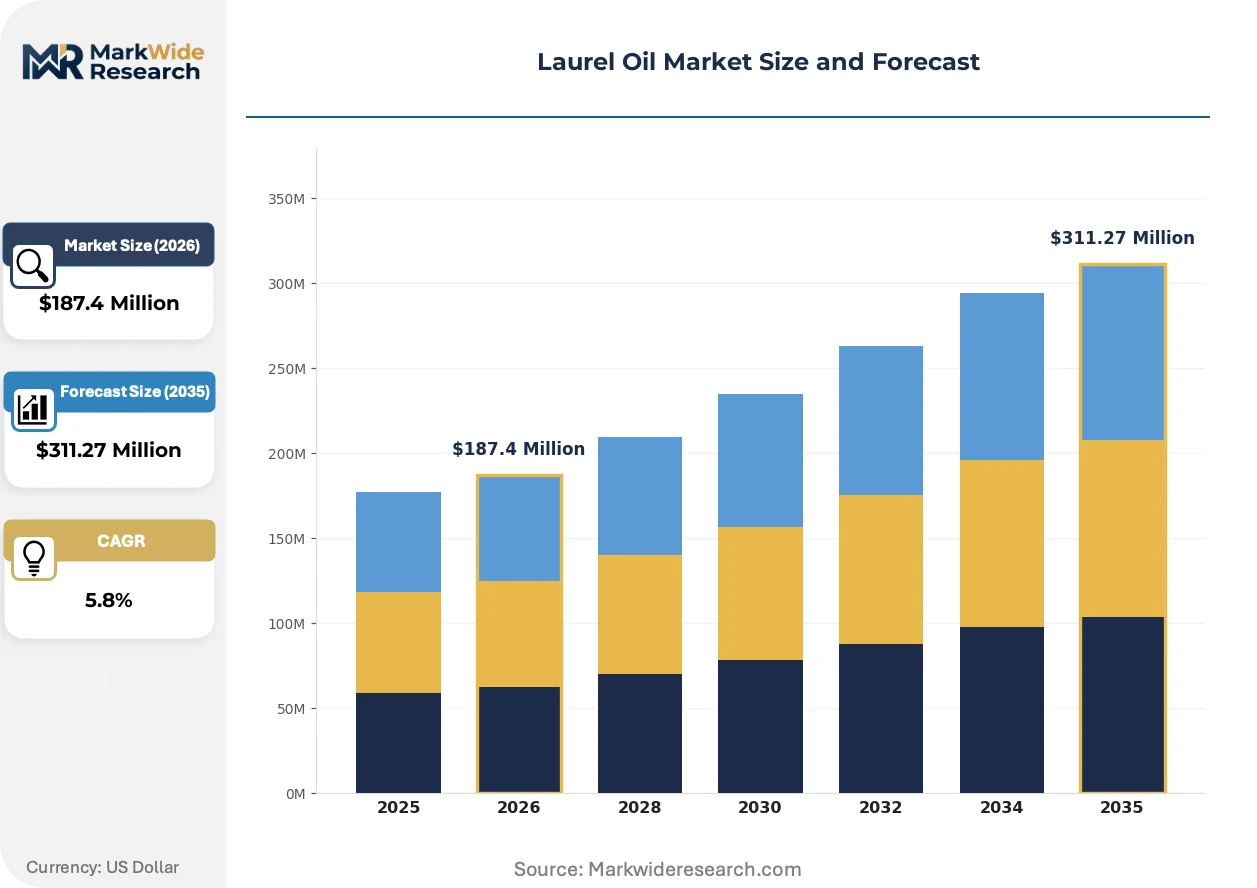
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Carrier Oils, Fragrance Oils, Flavor Oils End User: Cosmetics, Food & Beverage, Pharmaceuticals, Household Products Application: Aromatherapy, Culinary Use, Medicinal Use, Cleaning Products Packaging Type: Bottles, Jars, Drums, Sachets |
| Companies Covered | doTERRA International, Young Living Essential Oils, Biolandes, Plant Therapy Essential Oils, NOW Foods, Flavex Naturextrakte GmbH, Aromatics International, Albert Vieille, Berje, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laurel Oil Market Evolving Landscape
Extraction technology evolution, regulatory disclosure tightening, and procurement model restructuring are converging to reshape how laurel oil moves from leaf to formulation. These forces compress traditional intermediaries while rewarding traceable quality.
Supercritical CO2 extraction is decomposing the dominance of conventional steam distillation by preserving heat-sensitive terpenoid profiles that degrade under thermal stress. Pharmaceutical manufacturers in Switzerland and Germany are adopting this method for API-grade volumes. The technology is decomposing margin structures for processors unable to upgrade from legacy equipment.
EFSA novel food evaluations are extending approval timelines for laurel oil food-grade applications, forcing suppliers to maintain dual cosmetic-food supply chains. European processors face reformulation costs as disclosure thresholds tighten. The medicinal use segment bears the heaviest compliance burden, redirecting investment toward cosmetic-grade capacity.
Cosmetic formulators are consolidating supplier relationships around certified organic traceability, displacing spot-market purchasing. Moroccan cooperatives and Turkish farm networks now contract directly with brand R&D departments. This pattern concentrates procurement volume with verified Mediterranean suppliers possessing USDA and EU organic documentation.
Laurel Oil Market Segmentation
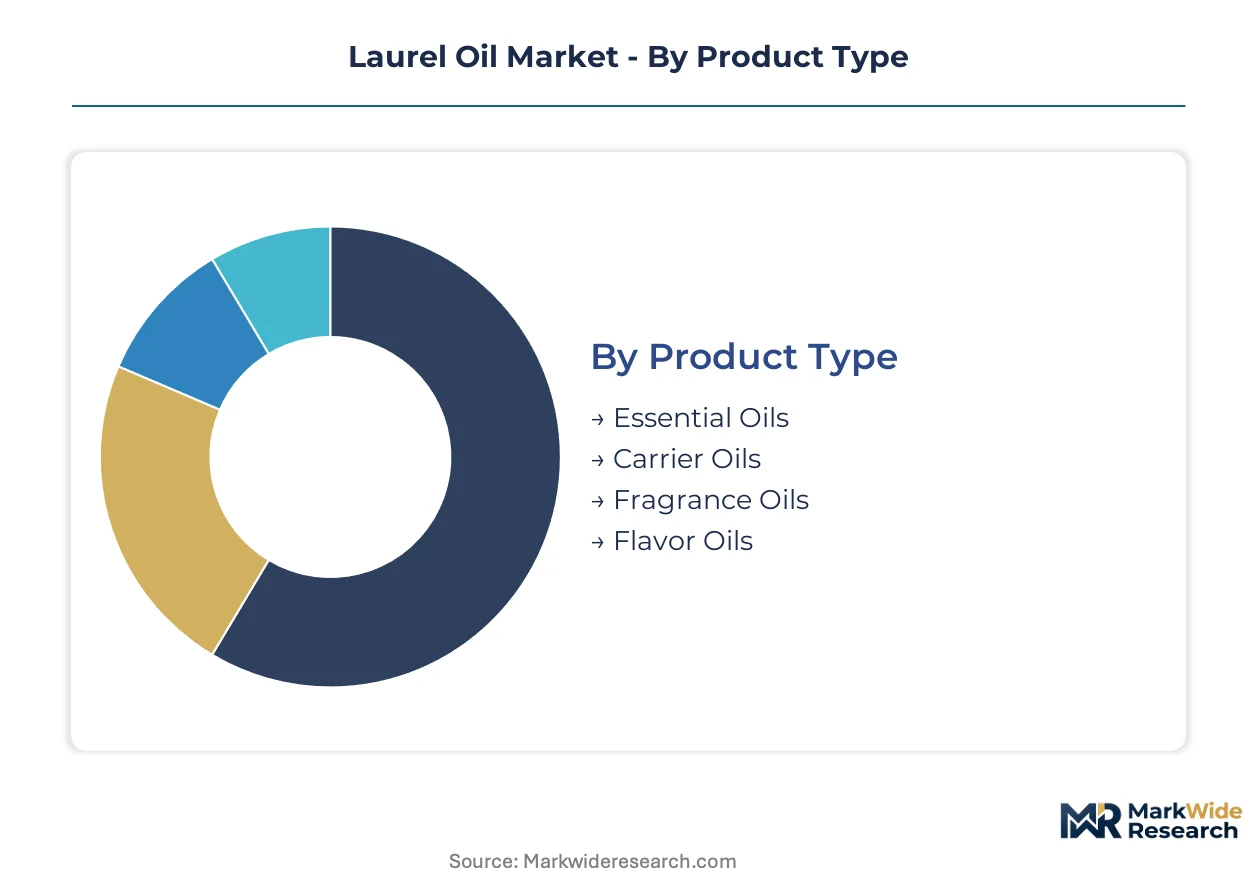
Laurel oil segmentation reveals how extraction grade and therapeutic positioning determine channel access and margin capture. Product type and end-use alignment dictate whether volumes flow through cosmetic formulators, pharmaceutical compounders, or food-grade distributors.
Product Type:
Channel mix varies sharply by extraction method and purity tier, with pharmaceutical and cosmetic buyers demanding certified grades while fragrance houses absorb lower-specification volumes.
- Essential Oils:Steam-distilled concentrates with eucalyptol and linalool as dominant actives, commanding premium positioning in therapeutic and aromatherapy channels. Moroccan and Turkish artisan networks supply bulk volumes to European cosmetic formulators seeking REACH-compliant feedstock, though cold-pressed expertise scarcity limits scalable output.
- Carrier Oils:Diluted bases enabling skin-safe application of concentrated actives in sensitive-skin formulations. Clean-label cosmetic brands in North America are expanding procurement fastest as USDA organic certification requirements tighten, displacing conventional diluents.
- Fragrance Oils:Standardized aromatic compounds for mass-market personal care and ambient scent applications.
- Flavor Oils:Food-grade distillates facing extended EFSA novel food evaluation timelines that compress processor margins.
Essential oils dominate installed base. Carrier oils are where expansion concentrates.
End User:
Customer-type concentration shapes pricing power, with pharmaceutical and cosmetic buyers demanding documentation depth that household product manufacturers rarely match.
- Cosmetics:Formulators dilute actives into skin-safe bases for sensitive-skin lines, consolidating supplier relationships around certified organic traceability. Direct contracting between Moroccan cooperatives and brand R&D departments is displacing traditional distributor intermediaries.
- Pharmaceuticals:API-grade volumes require supercritical CO2 extraction preserving heat-sensitive terpenoid profiles, with Swiss and German manufacturers adopting this method for European pharmacopeia compliance.
- Food & Beverage:Dual supply chain maintenance costs burden processors navigating EFSA approval delays.
- Household Products:Synthetic antimicrobial substitutes compete on cost, limiting natural oil penetration in price-sensitive tiers.
Cosmetics commands revenue concentration. Pharmaceuticals offers the steepest expansion trajectory for certified processors.
Application:
Use-case maturity determines margin structure, with established therapeutic applications defending price premiums while emerging food-grade segments absorb compliance investments.
- Aromatherapy:Therapeutic-grade volumes sustain premium pricing in wellness and spa distribution channels. Mediterranean sourcing corridors supply bulk volumes through traditional distillation networks, with quality differentiation hinging on artisan cold-pressed expertise.
- Medicinal Use:Pharmacopeial compliance costs compress margins for non-specialized processors, redirecting investment toward cosmetic-grade capacity as EFSA disclosure thresholds tighten.
- Culinary Use:Novel food evaluation timelines extend market access barriers.
- Cleaning Products:Petrochemical preservatives dominate cost-sensitive mass-market tiers.
Aromatherapy dominates installed base. Medicinal use is where certified processors are gaining share fastest.
Packaging Type:
Volume scale and customer touchpoint determine format selection, with bulk pharmaceutical and cosmetic procurement favoring industrial containers while direct-to-consumer channels demand retail-ready units.
- Drums:Industrial-scale containment for bulk pharmaceutical and cosmetic manufacturing inputs, with Moroccan cooperatives shipping directly to European formulators.
- Bottles:Retail and professional-use formats for aromatherapy and spa channels.
- Jars:Solid and semi-solid product containment for cosmetic applications.
- Sachets:Single-use sampling and travel formats.
Drums dominate installed base. Bottles is where channel diversification concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Morocco consumes laurel oil predominantly for therapeutic-grade aromatherapy exports, while the United States channels volumes into certified organic cosmetics—this consumption-mix differential shapes sourcing priorities and compliance investments across supplier networks.
Morocco
Artisan cooperatives in the Rif Mountains supply cold-pressed essential oils to European cosmetic formulators seeking REACH-compliant feedstock. The country's national agricultural regulator enforces organic certification standards for export-bound volumes. Casablanca serves as the primary consolidation hub where traditional distillation networks interface with international bulk buyers.
Turkey
Mediterranean coastal provinces harvest Laurus nobilis leaves for both domestic aromatherapy consumption and pharmaceutical-grade extraction. Turkish Ministry of Agriculture and Forestry protocols govern wild-collection permits and sustainable harvesting quotas. Antalya and Mersin host processing clusters where steam-distillation expertise concentrates among multi-generational family operations.
United States
Clean-label cosmetic brands in California and New York drive carrier oil procurement for sensitive-skin formulations. FDA cosmetic ingredient guidelines and USDA organic certification requirements shape import documentation and supplier verification. Los Angeles and New York City anchor distribution networks linking Mediterranean exporters to North American formulator R&D departments.
Germany
Pharmaceutical compounders in Bavaria and Baden-Württemberg absorb API-grade volumes for European pharmacopeia-compliant applications. ECHA REACH registration requirements and EMA quality standards tighten specifications for imported feedstock. Munich and Stuttgart host supercritical CO2 extraction facilities serving Swiss and German therapeutic manufacturers.
France
Luxury fragrance houses in Grasse and Paris integrate laurel oil into high-end personal care lines. ANSM cosmetic safety regulations and CNIL data governance requirements apply to supply chain traceability systems. The Provence-Alpes-Côte d'Azur region maintains distillation heritage while adapting to mechanized extraction for scale-sensitive fragrance applications.
Laurel Oil Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former commanding direct-to-formulator channels and the latter competing on extraction-method differentiation. The market structure rewards processors possessing both traditional cold-pressed expertise and modern pharmacopeia compliance capabilities. Three archetypes dominate: Mediterranean-origin cooperatives with artisan networks, North American distributors with certification infrastructure, and European specialists with pharmaceutical-grade extraction protocols. Competitive moves concentrate on backward integration into Moroccan and Turkish leaf supply, plus technology licensing for supercritical CO2 capacity expansion.
Within the integrated-leader tier, doTERRA International and Young Living Essential Oils exemplify companies leveraging direct sourcing partnerships to secure consistent Laurus nobilis feedstock. Biolandes occupies a position representing the European specialist archetype, with its French S.A. structure signaling pharmaceutical-grade extraction focus. These three entities anchor competitive positioning across distinct geographic and regulatory vectors—North American certification-driven distribution, Mediterranean artisan-network control, and European pharmacopeia compliance.
| Leading Market Players |
|---|
| doTERRA International |
| Young Living Essential Oils |
| Biolandes |
| Plant Therapy Essential Oils |
| NOW Foods |
| Flavex Naturextrakte GmbH |
| Aromatics International |
| Albert Vieille |
| Berje |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between Moroccan cooperatives and European cosmetic formulators lock in supply access and price visibility across REACH-compliant supply chains, insulating premium-grade volumes from spot-market volatility while compressing margins for non-contracted processors.
Pricing Analysis
Contract-based long-term offtake dominates procurement between Mediterranean suppliers and European pharmaceutical compounders, with price differentiation resting on organic certification tier and extraction method sophistication. Cost compression in fragrance-grade tiers is intensifying because synthetic antimicrobial substitutes compete on unit economics. Household product manufacturers exhibit highest price sensitivity, whereas Swiss and German API-grade buyers accept sustained premiums for pharmacopeia-compliant documentation.
Supply Chain Analysis
Morocco and Turkey anchor Laurus nobilis leaf supply through artisan cooperatives and multi-generational family operations, with raw material dependencies centering on wild-collection permits, sustainable harvesting quotas, and cold-pressed expertise scarcity. Single-source vulnerability concentrates in aging distiller networks across the Rif Mountains and Mediterranean coastal provinces. Distribution runs through Casablanca consolidation hubs interfacing directly with European cosmetic R&D departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic traceability services attach recurring revenue layers expanding faster than base oil volumes, as North American clean-label brands consolidate supplier relationships around verified documentation rather than spot-market purchasing.
For Market Incumbents: Fortify backward integration into Moroccan and Turkish leaf supply through cooperative equity stakes, while deepening supercritical CO2 extraction capabilities to defend against pharmaceutical-grade specialists. Synthetic antimicrobial substitutes threaten mass-market personal care penetration, making REACH compliance investment the priority lever for European channel control. For New Entrants and Emerging Players: USDA organic certification fast-track unlocks white-space access in North American carrier oil procurement for sensitive-skin formulations, where clean-label cosmetic brands displace conventional diluents. Direct-to-formulator channels bypassing traditional distributors offer the most penetrable go-to-market angle, with Moroccan cooperative partnership models replicable for Turkish farm networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors possessing dual traditional-artisan and modern-pharmacopeia capabilities across the analysis window. Acquisition targets should concentrate on Mediterranean-origin cooperatives with verified organic documentation and aging distiller succession plans. EFSA novel food approval timelines serve as the critical inflection signal distinguishing cosmetic-grade from food-grade investment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Leaf Supply | Equity stakes in Moroccan cooperatives secure captive feedstock for REACH-compliant volumes. |
| Supercritical CO2 Capacity Expansion | Swiss and German pharmaceutical manufacturers adopt this method for API-grade terpenoid preservation. |
| USDA Organic Certification Investment | North American clean-label brands consolidate procurement around verified supply chain documentation. |
| Direct-to-Formulator Channel Development | Moroccan cooperatives bypass distributors to contract directly with European cosmetic R&D departments. |
| Distiller Apprenticeship Programs | Aging artisan networks in Rif Mountains require succession planning to sustain cold-pressed expertise. |
Research Methodology
Initial hypotheses were tested against primary input from distillation cooperative managers, cosmetic formulator procurement leads, pharmaceutical compounder quality directors, and essential oil distribution channel partners and refined through secondary validation against customs trade data, ECHA REACH registration databases, USDA organic certification records, and SEC filings from publicly traded processors. Bottom-up volume triangulation across Mediterranean sourcing corridors converged with top-down value estimates from European pharmacopeia compliance cost structures.
Variance decomposition across extraction method, certification tier, end-use industry, and regional regulatory cluster shaped analytical framework development over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against historical volume trajectories in aromatherapy and pharmaceutical channels, with forecast inputs incorporating EFSA novel food evaluation timelines and supercritical CO2 adoption curves among Swiss and German manufacturers.
Decision-makers should treat outputs as directional under sustained REACH registration stringency and Moroccan harvest stability assumptions; material deviation in synthetic substitute pricing or distiller skill availability would warrant model refresh. Recalibration cycles align with material shifts in EFSA disclosure thresholds and USDA organic certification penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Medicinal Plant Extracts Market
Extracts
Pectin Powder Market
Extracts
Global Ginseng Extracts Market
Extracts
Hibiscus Flower Powder Market
Extracts
Herba Houttuyniae Extract Market
Extracts
Aloe Vera Extract Market
Extracts
Organic Herbal Extracts Market
Extracts
Sandalwood Oil Market
Extracts
Cosmetic Grade Portulaca Oleracea Extract Market
Extracts
Corn Steep Powder Market
Extracts
Herb and Spice Extracts Market
Extracts
Asia-Pacific Mineral Turpentine Market
Extracts
Copaiba Essential Oil Market
Extracts
Lavender Oil Market
Extracts
Gum Turpentine Oil Market
Extracts
Floral Extract Market