
 Leisure Travel Market | 2026-2036
Leisure Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Leisure Travel Market Analysis
Package tour margins is narrowing as direct booking platforms and mobile apps capture a larger share of traveler spending. Booking Holdings leverages its global online travel agency network to sustain price transparency and inventory breadth. Trip.com Group anchors its position in Asia-Pacific through integrated flight-hotel bundling and localized payment systems.
Leisure travel encompasses discretionary trips undertaken for recreation, relaxation, or personal enrichment rather than business purposes, typically involving pre-arranged transportation, accommodation, and activity components with booking lead times ranging from days to months. The sector generates economic value through destination services, hospitality operations, and experience curation across international and domestic routes. Adventure travel and city breaks command premium pricing due to specialized guide services and limited-season access, while beach holidays represent a mature, volume-driven category with heavy reliance on charter flight capacity. Mobile apps as a distribution channel are expanding fastest among solo travelers and younger demographics seeking real-time itinerary modifications.
FAA regulations govern commercial aviation safety standards that underpin international leisure connectivity from the United States, while EASA's operational rules shape European carrier networks and airport slot allocations. GDPR compliance requirements in Europe impose data-handling obligations on online travel agencies collecting passenger information for personalized marketing. Stakeholders must monitor how carbon border adjustments and sustainable aviation fuel mandates reshape route economics and traveler destination choices.
Market Dynamics
Biometric verification infrastructure is compressing passenger processing times at airports and hotels, redistributing value from traditional ground handling services toward integrated identity-tech platforms that capture traveler data across touchpoints.
Growth Catalysts
- EU Green Deal aviation mandates:Sustainable aviation fuel requirements are redirecting carrier capex toward fleet renewal, opening retrofit opportunities for regional airports in Eastern Europe and the Baltic states.
- Mobile-first solo traveler segment:Real-time itinerary modification tools embedded in native apps are capturing booking share from legacy package tour operators across Southeast Asian markets.
- Thailand's smart visa framework:Extended-stay digital nomad permits are creating sustained accommodation demand outside traditional peak seasons in Chiang Mai and Phuket corridors.
Market Restraints
- Jet fuel price volatility:Carrier hedging strategies face margin compression when crude benchmarks swing, forcing route cancellations on thin-margin leisure destinations.
- GDPR data localization:European online travel agencies face architectural costs to segment passenger databases, slowing personalized marketing deployment.
- Short-term rental supply caps:Barcelona and Lisbon municipal ordinances restrict Airbnb density in historic cores, constraining inventory growth in high-yield urban zones.
Strategic Opportunities
- Vietnam's coastal secondary cities:Da Nang and Nha Trang lack integrated resort infrastructure, presenting greenfield development potential for experiential hospitality operators.
- Biometric-hotel key convergence:Facial recognition check-in systems merging with property management platforms eliminate front-desk labor and accelerate guest throughput.
- Indonesia's e-visa liberalization:Simplified ASEAN entry protocols for Indian and Chinese passport holders expand addressable traveler pools for Balinese and Javanese operators.
Industry Challenges
- Multilingual guide certification:Adventure travel operators in Vietnam and Thailand face acute shortages of Mandarin and Korean-speaking field staff for premium trekking products.
- Legacy property management system integration:Independent hotels struggle to connect 1990s-era on-premise software with cloud-based distribution channels without middleware costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leisure Travel Market |
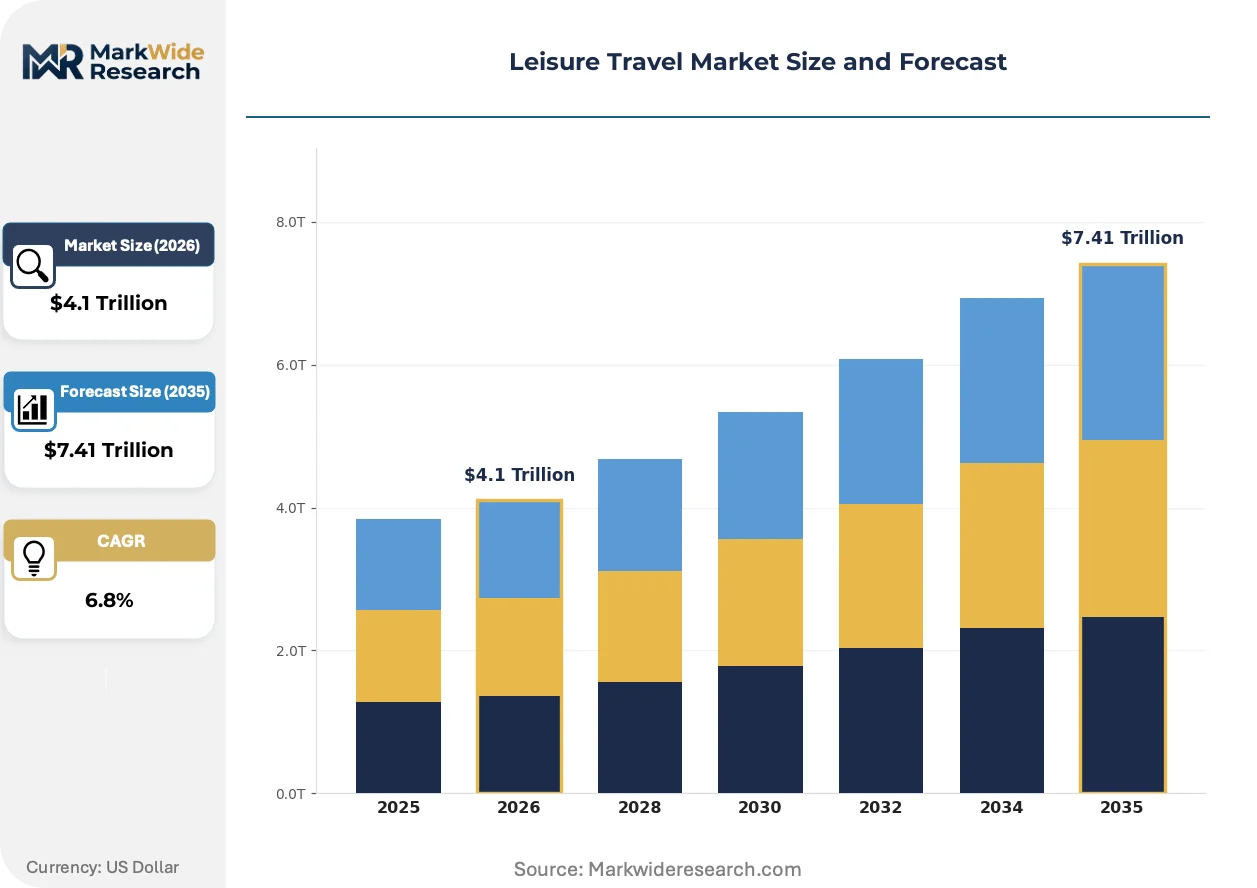
| Market Size in 2026 | $4.1 Trillion |
| Market Size in 2035 | $7.41 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Package Tours, Adventure Travel, Beach Holidays, City Breaks Customer Type: Families, Couples, Solo Travelers, Groups Distribution Channel: Online Travel Agencies, Offline Travel Agents, Direct Booking, Mobile Apps Price Tier: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | Booking Holdings, Marriott Vacations Worldwide, Travel + Leisure Co., Disney Parks Experiences and Products, Hilton Grand Vacations, Travel Leaders Network, Trip.com Group, Carnival Corporation, Expedia Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leisure Travel Market Emerging Trajectories
Three interconnected shifts are restructuring how leisure inventory reaches travelers: identity verification is becoming the new check-in, regulatory carbon accounting is rewriting route economics, and direct booking tools are fragmenting the travel agency channel.
Virtual reality destination preview tools are virtualizing the pre-purchase experience for high-consideration adventure products. Solo travelers and younger demographics deploy these immersive walkthroughs to assess trekking difficulty and accommodation standards before committing. The technology is virtualizing the traditional role of travel agents as experiential curators, compressing commission pools toward content production platforms.
The EU's Corporate Sustainability Reporting Directive extends disclosure obligations to large travel operators, mandating scope-three emissions tracking across supplier networks. Carriers and hotel chains must now audit ground transportation and catering partners for carbon intensity. French and German tour operators are responding by shortening average itinerary distances and prioritizing rail-connected destinations over fly-in beach resorts.
Solo travelers increasingly construct itineraries through unbundled app ecosystems rather than packaged products. Real-time flight-hotel-activity APIs allow dynamic rebooking when weather or events disrupt plans. This behavioral shift is most visible in Indonesia's domestic market, where Gen Z travelers combine Gojek transport, TikTok-discovered homestays, and Instagram-booked experiences into self-assembled trips.
Leisure Travel Market Segmentation
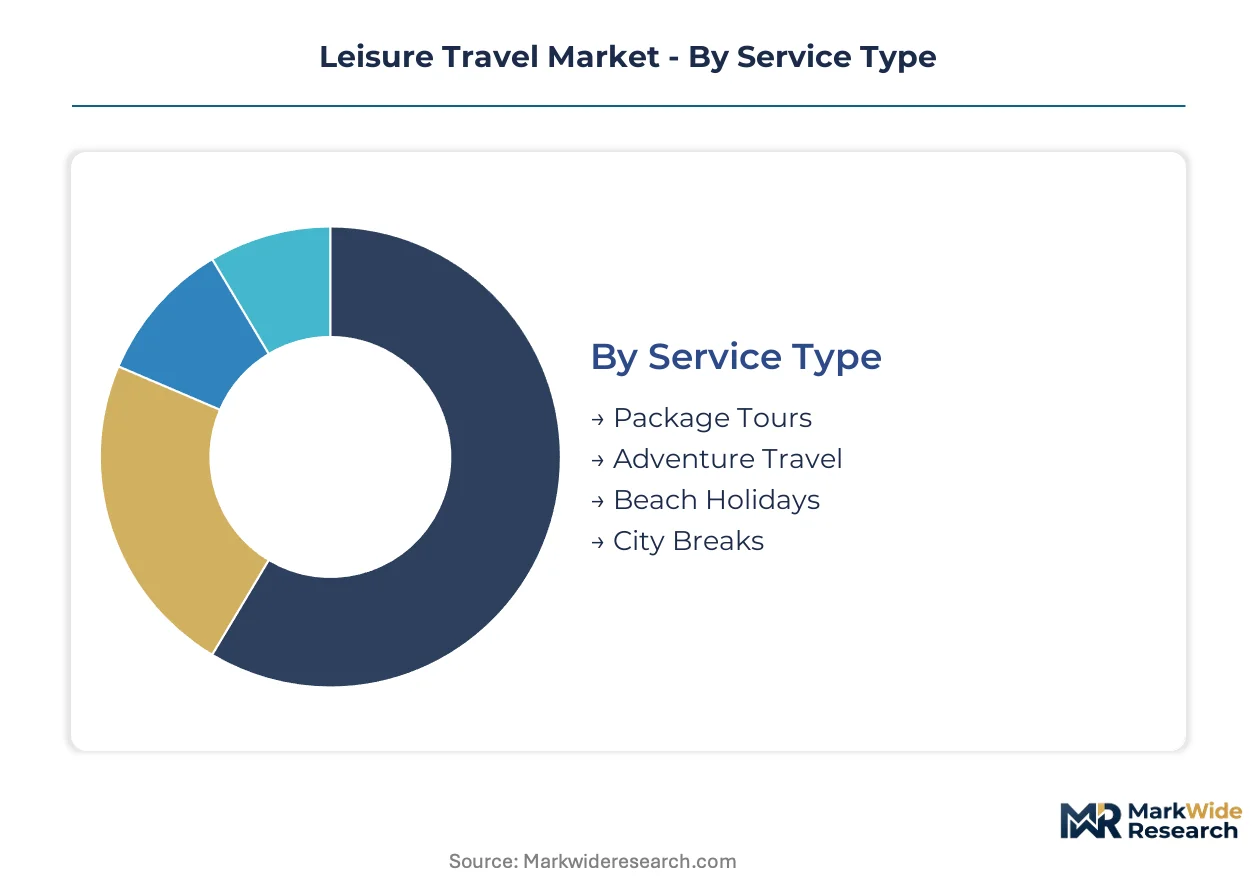
Segmentation in leisure travel separates high-frequency, low-margin volume from low-frequency, high-margin specialization. Cycle times vary dramatically: mobile app bookings complete in minutes while adventure travel products require months of lead time and guide coordination.
Service Type:
Cycle times compress from months to minutes across this spectrum, with pre-packaged inventory turning fastest and bespoke adventure products slowest.
- Package Tours:Pre-assembled flight-hotel-activity bundles with fixed departure dates and bulk inventory commitments. Demand concentrates in European source markets for Mediterranean and Caribbean destinations, constrained by charter flight capacity and deposit refund policies.
- Adventure Travel:Specialized itineraries requiring certified guides, equipment logistics, and physical fitness assessments. Trekking demand in Nepal, Patagonia, and New Zealand commands premium pricing due to limited-season permits and guide scarcity.
- Beach Holidays:Volume-driven resort stays with standardized room inventory and all-inclusive pricing.
- City Breaks:Short-haul urban tourism with flexible duration and dynamic hotel pricing.
Beach holidays anchors the volume base while adventure travel gains share at the steepest rate.
Customer Type:
Booking behavior diverges sharply by party composition, with solo travelers exhibiting the highest digital adoption and shortest decision windows.
- Solo Travelers:Individual bookers utilizing mobile apps for real-time itinerary modifications and single-occupancy room inventory. Southeast Asian markets including Thailand and Vietnam capture disproportionate demand from this segment due to safety infrastructure and social hostel networks.
- Families:Multi-generational parties requiring connecting rooms, child-care services, and activity coordination. European and North American source markets drive demand for Orlando, Dubai, and Bali resort clusters with integrated kids' programming.
- Couples:Dual-occupancy bookings prioritizing romantic amenities and privacy.
- Groups:Coordinated multi-room blocks for celebrations or affinity travel.
Families anchors the volume base while solo travelers expand most quickly through mobile channels.
Distribution Channel:
Commission structures and data ownership rights separate legacy intermediaries from direct digital platforms.
- Mobile Apps:Native applications enabling real-time rebooking, push-notification pricing, and embedded payment wallets. Solo travelers and younger demographics in Indonesia and Vietnam deploy Gojek, Grab, and localized super-apps to construct unbundled itineraries.
- Online Travel Agencies:Web-based aggregators with price comparison tools and loyalty programs. Booking Holdings and Trip.com Group capture search-driven demand through inventory breadth and localized payment systems.
- Direct Booking:Supplier-owned websites bypassing intermediary commissions.
- Offline Travel Agents:Human advisors serving complex multi-destination itineraries and corporate leisure accounts.
Online travel agencies anchors the volume base while mobile apps climbs the fastest among younger demographics.
Price Tier:
Margin structures and cancellation flexibility separate tiers more than physical amenities alone.
- Luxury:Properties and experiences with staff-to-guest ratios above 1:1, private transfers, and bespoke concierge services. Maldives overwater villas, safari lodges in Kenya and Tanzania, and urban palace hotels in Paris and Tokyo command rate premiums through scarcity and service intensity.
- Mid-Range:Three-to-four-star properties with standardized amenities and loyalty program integration.
- Budget:Hostels, economy hotels, and basic transportation with minimal service layers.
- Discounted:Flash sales, opaque inventory, and last-minute distressed capacity.
Mid-range anchors the volume base while luxury gains share at the steepest rate through experience premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Leisure travel consumption patterns diverge sharply by geography. Southeast Asian markets favor mobile-app-assembled itineraries, European travelers prioritize rail-connected low-carbon destinations, and North American demand concentrates in integrated resort clusters with bundled entertainment programming.
United States
Orlando and Las Vegas anchor domestic leisure volume through theme park and casino-integrated resort complexes. FAA safety standards govern commercial aviation connectivity to these hubs. Miami serves as the primary embarkation point for Caribbean cruise itineraries, with Carnival Corporation and Royal Caribbean operating dedicated terminal facilities.
Thailand
Chiang Mai and Phuket corridors capture extended-stay digital nomad demand through smart visa frameworks permitting 180-day stays. The Tourism Authority of Thailand coordinates with immigration authorities on permit processing infrastructure. Bangkok's Suvarnabhumi Airport deploys biometric entry gates compressing passenger processing times for inbound leisure traffic.
Germany
Bavarian Alpine regions and Baltic Sea coastlines command premium pricing for hiking and wellness-oriented domestic travel. EASA operational rules shape carrier network configurations serving leisure destinations from Munich and Frankfurt hubs. The EU Green Deal aviation mandates redirect Lufthansa Group capex toward sustainable aviation fuel procurement.
Indonesia
Bali and Lombok absorb inbound leisure demand from Australian and Chinese source markets, with Denpasar Airport handling over 20 million annual passengers. E-visa liberalization for Indian and Chinese passport holders expands addressable traveler pools. Jakarta-based super-app Gojek enables unbundled itinerary construction across transport, accommodation, and experience booking.
Vietnam
Da Nang and Nha Trang present greenfield development opportunities for experiential hospitality operators targeting Korean and Mandarin-speaking source markets. The Ministry of Culture, Sports and Tourism administers guide certification programs addressing acute multilingual field staff shortages. Phu Quoc island operates under specialized visa-exemption protocols stimulating resort investment.
Leisure Travel Market Vendor Landscape
Capability concentration sits with integrated resort and experience operators; scale advantage sits with online travel agency platforms. The market structures around three tiers: global inventory aggregators, vertically integrated hospitality operators, and niche experience curators. Strategic moves center on mobile-first platform development and biometric identity integration across touchpoints.
Within the global OTA tier, Booking Holdings and Trip.com Group exemplify scale-driven inventory breadth, while Expedia Group occupies a position emphasizing loyalty program density. Disney Parks Experiences and Products represents the integrated resort archetype, anchoring competitive positioning through captive entertainment programming and on-property spend capture.
| Leading Market Players |
|---|
| Booking Holdings |
| Marriott Vacations Worldwide |
| Travel + Leisure Co. |
| Disney Parks Experiences and Products |
| Hilton Grand Vacations |
| Travel Leaders Network |
| Trip.com Group |
| Carnival Corporation |
| Expedia Group |
| Others |
Supply Flow & Price Mechanics
Bali's integrated resort corridor concentrates hospitality inventory and compresses pricing power for independent operators during peak Australian and Chinese travel windows. Contract structures across the leisure travel sector segment sharply between long-term charter commitments and spot-market dynamic pricing.
Pricing Analysis
Long-term offtake agreements dominate package tour inventory with fixed charter flight commitments and bulk hotel blocks, while adventure travel products operate on project-based pricing tied to guide availability and permit windows. Pricing stratifies across premium, standard, and economy tiers based on certification level of field staff and vertical integration of ground services. Cost compression in mid-range beach holidays is intensifying because direct booking platforms disintermediate traditional tour operators. Families exhibit highest price sensitivity due to multi-passenger coordination costs, while solo travelers accept premium single-occupancy surcharges for flexibility.
Supply Chain Analysis
Extended payment terms from European tour operators strain Vietnamese and Thai ground handler cash cycles, accelerating adoption of supply-chain finance facilities. Inventory concentration rests on Thailand, Indonesia, and Vietnam for experiential hospitality capacity, with raw material dependencies on aviation fuel procurement, certified guide labor pools, and localized food and beverage sourcing. Single-source vulnerability runs through Mandarin and Korean-speaking guide networks for premium trekking products. Distribution runs through mobile super-apps in Southeast Asian markets and legacy online travel agency platforms in European source markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The leisure travel market sits at a high-growth inflection as biometric identity verification and EU Green Deal aviation mandates simultaneously reshape operational economics and traveler routing preferences.
For Market Incumbents: Pre-empt platform disintermediation by consolidating mobile-first booking infrastructure and embedding real-time rebooking APIs that match Gen Z traveler expectations. Incumbent operators must secure sustainable aviation fuel offtake agreements before EU mandates tighten carrier slot allocations. Biometric-hotel key convergence investments will eliminate front-desk labor costs and accelerate guest throughput against asset-light competitors.
For New Entrants and Emerging Players: Build out experiential hospitality capacity in Vietnam's Da Nang and Nha Trang corridors where integrated resort infrastructure remains underdeveloped. The most penetrable white-space sits in multilingual guide certification programs addressing acute Mandarin and Korean-speaking field staff shortages. A direct-to-solo-traveler go-to-market angle through TikTok-discovered homestays and Instagram-booked experiences bypasses legacy commission structures.
For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because mobile app ecosystems are fragmenting the travel agency channel and capturing traveler data across touchpoints. Acquisition targets should emphasize biometric identity-tech platforms with property management system integration capabilities. The signal to watch is carrier hedging strategy disclosures as jet fuel volatility forces route cancellations on thin-margin leisure destinations.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Identity Platform Integration | Facial recognition check-in systems merge with property management platforms to eliminate front-desk labor at Thai and Indonesian resorts. |
| Sustainable Aviation Fuel Procurement | Lufthansa Group capex redirection under EU Green Deal mandates reshapes route economics for European carrier networks. |
| Mobile Super-App Ecosystem Expansion | Gojek and Grab enable unbundled itinerary construction across transport, accommodation, and experience booking in Indonesian markets. |
| Multilingual Guide Certification Investment | Vietnam's Ministry of Culture administers programs addressing acute field staff shortages for premium Korean and Mandarin-speaking trekking products. |
| Extended-Stay Visa Infrastructure | Thailand's smart visa framework creates sustained accommodation demand outside traditional peak seasons in Chiang Mai and Phuket corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with airline route planners, resort revenue managers, adventure tour operators, and online travel agency platform engineers. Secondary validation drew from FAA safety filings, EASA operational rulemakings, Tourism Authority of Thailand visitor statistics, and EU Green Deal aviation mandate documentation. Bottom-up triangulation across individual property inventory and top-down carrier capacity analysis anchored volume estimates.
Calibration against historical booking pattern shifts and regulatory implementation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, customer composition, distribution channel, and price tier alongside regional regulatory cluster variations. CAGRs were derived from trend extrapolation adjusted for policy inflection points. Industry-specific forecast inputs incorporated biometric adoption curves and sustainable aviation fuel mandate phase-in schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by asset-light mobile platforms or carbon-border adjustment accelerators would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Africa Wellness Tourism Market
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Global Golf Travel Market
Travel and Tourism
France Culinary Tourism Market
Travel and Tourism
Water Park Market
Travel and Tourism
Europe Tourism Vehicle Rental Market
Travel and Tourism
Flower Delivery Services Market
Travel and Tourism
Wedding Tourism Market
Travel and Tourism
India Sports Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Japan Sports Tourism Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
France Outbound Tourism Market