
 Europe Tourism Vehicle Rental Market | 2026-2036
Europe Tourism Vehicle Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tourism Vehicle Rental Market Foresight
Driver shortages across licensed commercial transport pools is redrawing fleet deployment economics for rental operators. Sixt SE leverages its German headquarters and dense airport presence to sustain premium positioning across business hubs. Europcar Mobility Group anchors its network through urban mobility partnerships and rail-station density. Green Motion International differentiates through an all-electric fleet commitment that competes for sustainability-minded travelers.
Europe tourism vehicle rental denotes the short-term commercial provision of passenger automobiles to non-resident travelers, typically governed by mileage limits, insurance bundling, and cross-border usage clauses with vehicles maintained to commercial safety specifications. The primary purpose centers on enabling flexible, destination-independent ground transportation for leisure and corporate visitors without capital ownership. SUVs and convertibles command peak seasonal margins in coastal Mediterranean markets where family and tourist segments generate concentrated demand during summer windows. Online and mobile app booking channels are displacing traditional travel agency intermediation, compressing commission structures while expanding direct customer data capture for yield management.
EU Green Deal emission targets and REACH chemical standards for vehicle interiors shape fleet composition decisions, with ECHA oversight extending to material compliance for upholstery and cabin components. CE marking requirements for onboard telematics and navigation systems influence technology procurement across member states. National regulators in France, Germany, and Italy layer additional urban access restrictions that favor low-emission vehicle categories. Stakeholders must weigh electrification capital intensity against tightening municipal access rules and shifting traveler channel preferences.
Market Dynamics
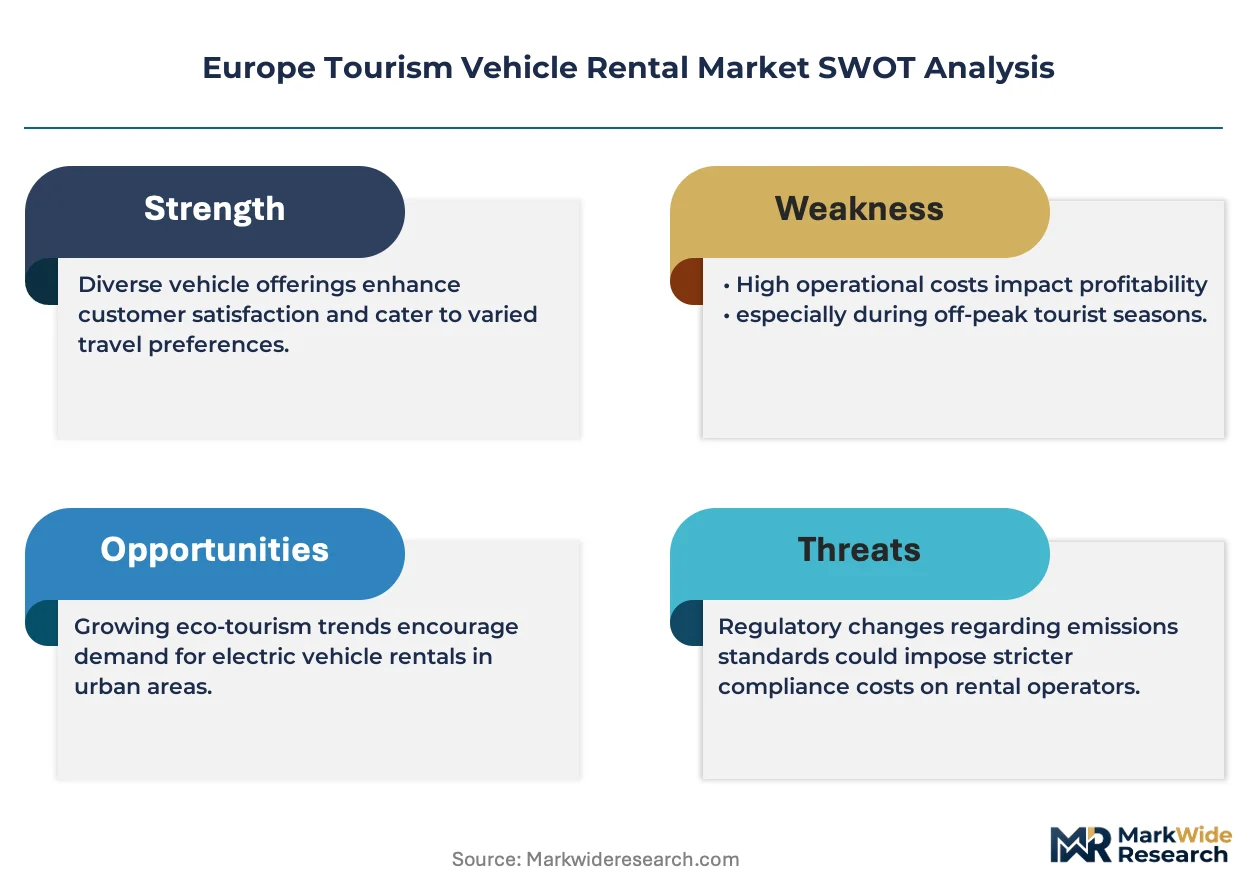
EU Green Deal emission benchmarks are pressuring rental operators to reconstitute fleets around electrified powertrains while driver shortages across licensed commercial transport pools compress operational flexibility. This dual squeeze is redrawing capital deployment priorities and partnership structures across Mediterranean tourism corridors.
Growth Catalysts
- EU Green Deal fleet mandates:Binding emission targets for commercial vehicle pools are accelerating electrification procurement timelines and opening subsidy windows for charging infrastructure deployment.
- Leisure travel from North America and Asia:Cross-continental visitor flows into Spain, Italy, and France are sustaining premium utilization rates during concentrated summer demand windows.
- Telematics integration:CE-marked onboard diagnostics and GPS-enabled fleet management systems are enabling real-time yield optimization and predictive maintenance scheduling.
Market Restraints
- Lithium-ion battery supply concentration:Cell manufacturing bottlenecks in East Asian supplier networks are inflating acquisition costs for electric fleet vehicles and extending delivery lead times.
- REACH chemical compliance:ECHA oversight of upholstery materials and cabin interior components is imposing reformulation costs and supplier qualification burdens across fleet refurbishment cycles.
- Licensed driver scarcity:Commercial transport licensing backlogs in France, Germany, and Italy are constraining fleet deployment flexibility during peak seasonal windows.
Strategic Opportunities
- Rail-station mobility hubs:Underutilized intermodal connection points in secondary Italian and Spanish cities offer density for automated pickup-dock installations and subscription rental models.
- Vehicle-to-grid integration:Bidirectional charging infrastructure at tourism lodging clusters can monetize idle fleet capacity as distributed energy storage during overnight hours.
- CE marking for autonomous valet:Emerging regulatory pathways for self-parking and retrieval systems at airport terminals promise labor cost compression and turnaround velocity gains.
Industry Challenges
- High-voltage technician certification:Commercial EV maintenance requires specialized training programs that remain undersupplied across Southern European service networks.
- Cross-border insurance harmonization:Fragmented national liability frameworks complicate fleet utilization across Schengen tourism routes and inflate administrative overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tourism Vehicle Rental Market |
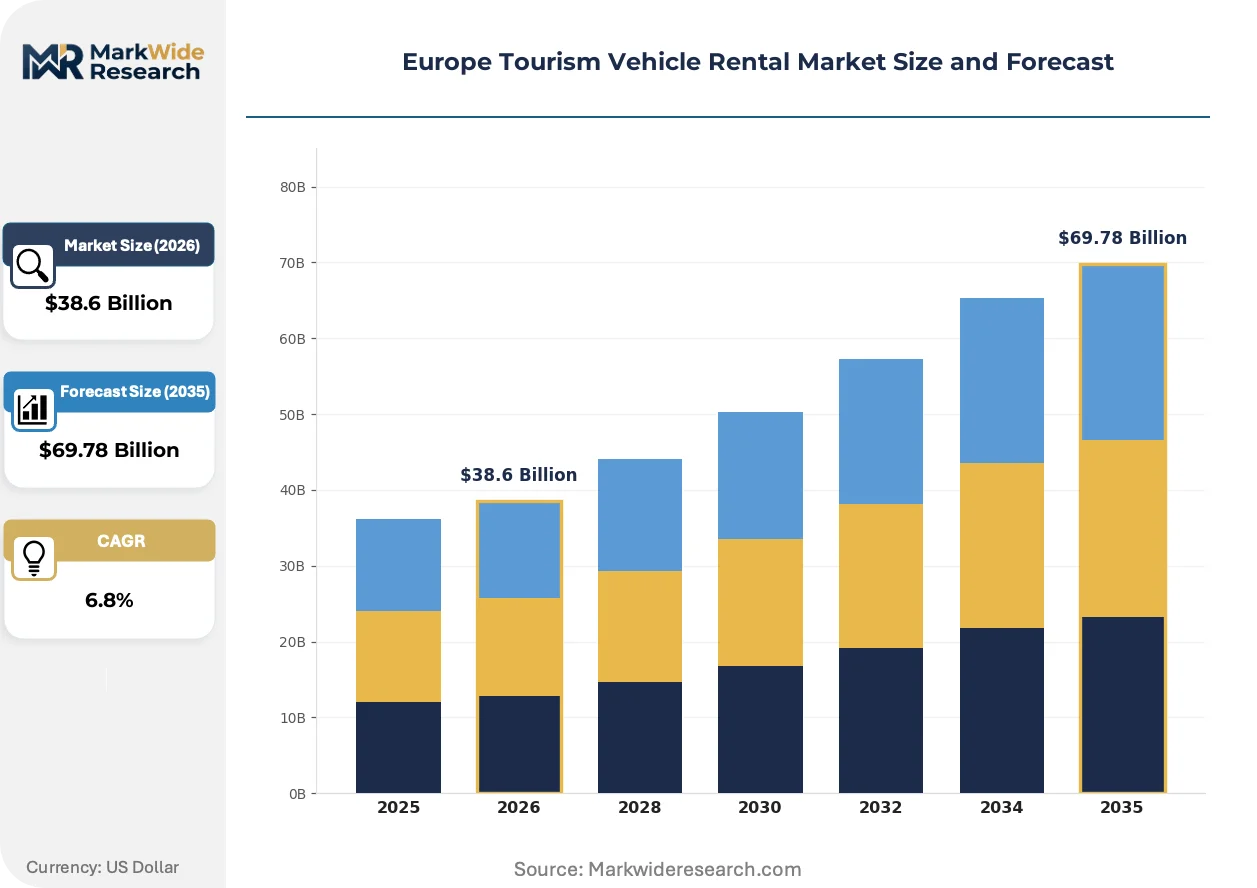
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: SUV, Sedan, Convertible, Minivan Rental Duration: Daily, Weekly, Monthly, Long-term Customer Segment: Tourists, Business Travelers, Family, Backpackers Booking Channel: Online, Travel Agency, Direct, Mobile App |
| Companies Covered | Enterprise Holdings, Auto Europe, Sixt SE, Booking Holdings, OK Mobility, Avis Budget Group, Europcar Mobility Group, Green Motion International, Hertz Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tourism Vehicle Rental Market Shifts & Advancements
Digital booking channels are compressing traditional travel agency intermediation while telematics and electrification technologies reshape fleet economics. Three developments are actively restructuring competitive positioning across European tourism corridors.
Connected fleet management platforms integrating real-time location data with dynamic pricing algorithms are bifurcating operator capabilities between data-rich yield optimizers and legacy rate-card dependents. Mediterranean-focused rental pools are adopting these systems fastest, using granular demand signals to reposition vehicles between airport hubs and coastal resort clusters ahead of arrival surges. The technology is compressing margin dispersion between premium and standard fleet tiers by exposing underutilized inventory to last-minute price discovery.
France's ANSM and Germany's KBA are layering urban low-emission zone access restrictions atop EU-wide Green Deal benchmarks, creating municipal-level compliance complexity for cross-border fleet operators. These national regulations are forcing vehicle homologation strategies that prioritize zero-emission categories for airport and city-center locations while retaining combustion options for rural tourism routes. Italian operators face the steepest adaptation curve given concentration of historic city centers with impending diesel bans.
Mobile-native booking interfaces are displacing traditional travel agency intermediation among North American and Asian visitor segments, compressing commission structures from fifteen to twenty percent down to direct payment processing fees. This channel shift is expanding first-party data capture for rental operators, enabling personalized upsell targeting for insurance bundles and ancillary services. Spain and Portugal exhibit the most advanced displacement patterns, where aggregator app penetration among inbound leisure travelers now exceeds traditional agency bookings during peak summer months.
Europe Tourism Vehicle Rental Market Segmentation
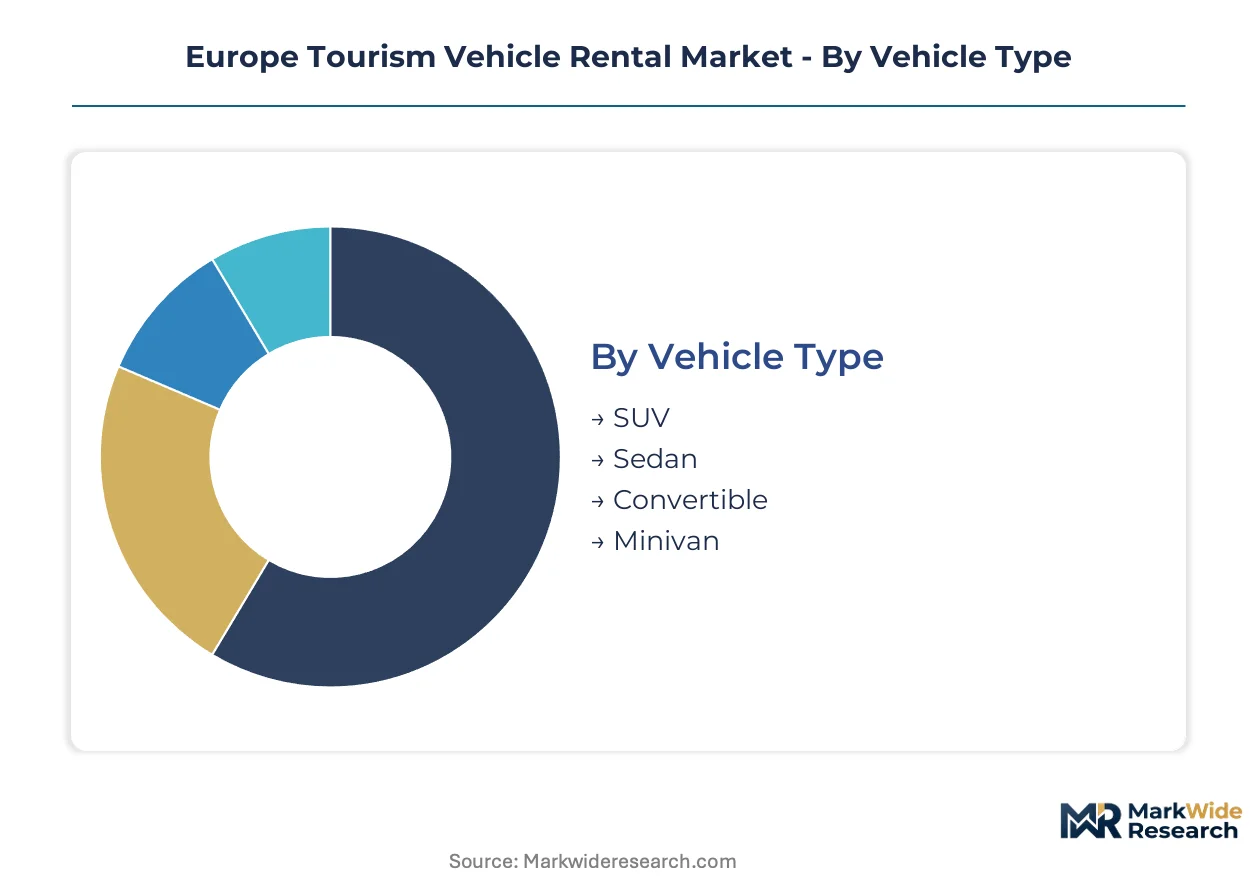
Segmentation in the Europe tourism vehicle rental market reveals how margin pools concentrate across vehicle categories, duration windows, and booking interfaces. Rental operators calibrate fleet composition and pricing architecture around these divisions to capture premium yields during Mediterranean seasonal peaks.
Vehicle Type:
Margin pools concentrate in versatile body styles that command peak-season premiums across coastal tourism corridors.
- SUV:Mid-size and full-size sport utility vehicles dominate family segment bookings with elevated ground clearance and cargo capacity suited to Alpine routes and rural exploration. Spain and France sustain premium daily rates during summer demand windows where multi-generational travel parties prioritize cabin space over fuel economy.
- Convertible:Open-top configurations capture peak margins along Mediterranean coastal roads where leisure travelers from North America and Asia seek experiential driving. Italian operators command the steepest seasonal premiums for two-seat and four-seat soft-top variants across Amalfi and Côte d'Azur routes.
- Sedan:Three-box passenger cars serve cost-conscious business travelers and urban tourism circuits with standardized fleet economics.
- Minivan:Multi-passenger vans address group charter substitution and extended family logistics across airport-resort corridors.
SUV holds installed capacity across German and French operator fleets. Convertible is rotating up the share rankings as experiential tourism demand climbs fastest.
Rental Duration:
Yield optimization depends on matching vehicle utilization cycles to traveler itinerary patterns and municipal access restrictions.
- Daily:Single-day rentals concentrate at airport hubs and rail terminals where inbound tourists seek immediate ground transportation flexibility. Italian operators deploy daily-rate inventory strategically around high-speed rail connections in Rome and Milan to intercept intermodal transfer demand.
- Weekly:Seven-day blocks align with traditional vacation package structures and sustain utilization continuity across resort-to-resort itineraries. Spanish Mediterranean islands exhibit the strongest weekly booking concentration where fly-drive packages dominate leisure inflows.
- Monthly:Extended-term agreements serve remote workers and seasonal residents seeking transportation without ownership commitment.
- Long-term:Multi-month contracts address corporate relocation and academic exchange programs with fleet management outsourcing.
Weekly holds installed capacity as the baseline leisure tourism contract. Daily is rotating up the share rankings as mobile-native booking enables impulse reservation behavior.
Customer Segment:
Service configuration and ancillary attachment rates diverge sharply across traveler motivation and party composition.
- Tourists:Leisure visitors from outside Europe generate the highest ancillary service attachment for insurance bundles and navigation equipment. French operators target this segment with multilingual concierge interfaces at Paris Charles de Gaulle and Nice Côte d'Azur hubs.
- Business Travelers:Corporate account holders demand streamlined pickup protocols and expense management integration. German operators anchor premium positioning through airport lounge partnerships and guaranteed vehicle class availability.
- Family:Multi-passenger parties prioritize child safety seat availability and flexible cancellation terms.
- Backpackers:Budget-oriented independent travelers seek minimum viable transportation with manual transmission options and cross-border permit inclusion.
Tourists holds installed capacity as the volume foundation. Business Travelers is rotating up the share rankings as hybrid work patterns extend corporate mobility programs.
Booking Channel:
Commission structures and customer data ownership are restructuring around interface preferences of inbound leisure segments.
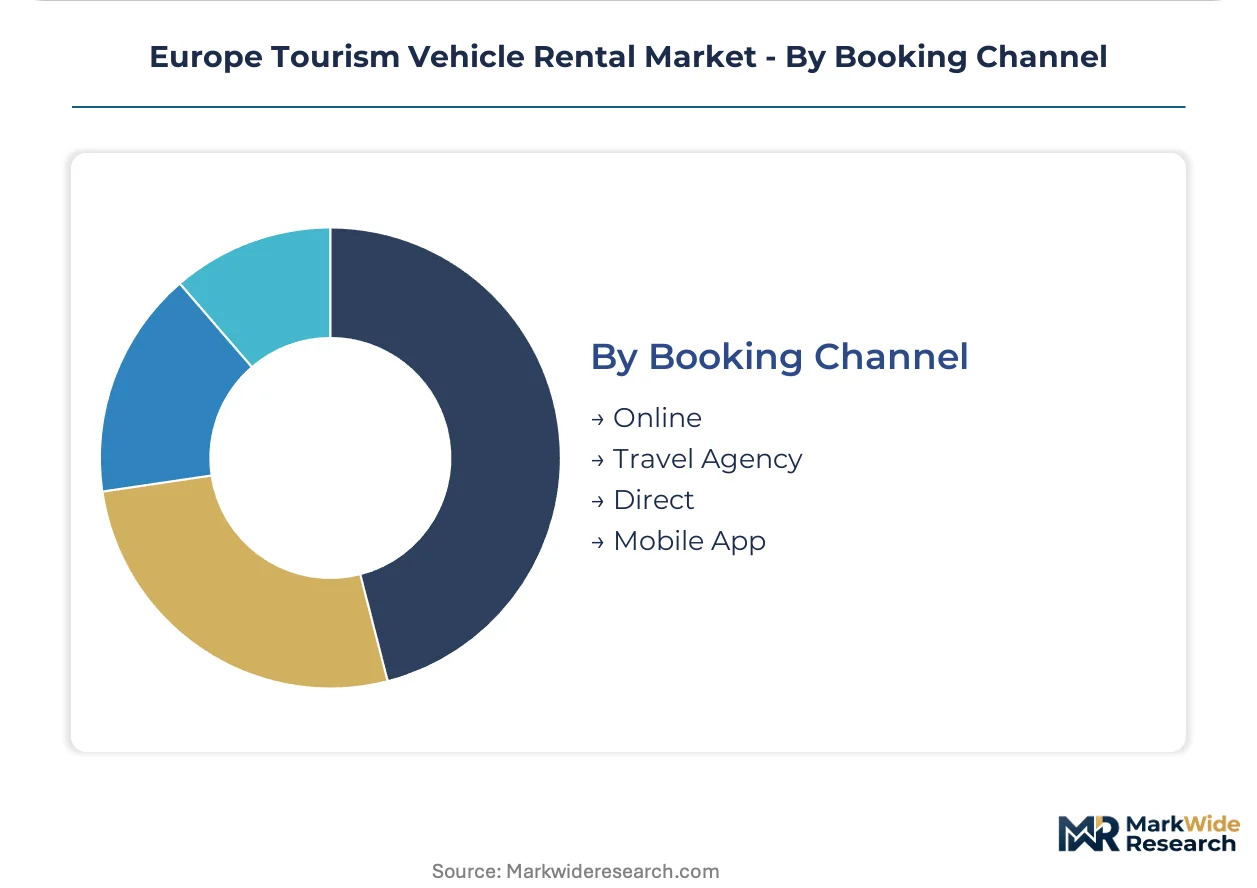
- Online:Web-based reservation platforms displace traditional intermediation with direct operator websites and aggregator marketplaces. Spanish operators exhibit the most advanced online penetration where inbound leisure travelers now book predominantly through browser interfaces.
- Mobile App:Smartphone-native interfaces enable geofenced pickup coordination and real-time fleet repositioning. Italian operators deploy app-exclusive pricing to build first-party data assets for yield management optimization.
- Travel Agency:Traditional intermediaries retain residual share in package tour bundling and corporate travel management.
- Direct:Walk-up counter and telephone reservations persist for last-minute itinerary changes and complex multi-leg routing.
Online holds installed capacity as the dominant reservation pathway. Mobile App is rotating up the share rankings as younger traveler demographics bypass browser interfaces entirely.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across European tourism corridors diverge sharply between Mediterranean leisure hubs and Alpine business routes, with fleet utilization rates and vehicle class preferences mapping closely to inbound visitor origin markets and seasonal density windows.
Spain
Coastal tourism clusters along the Costa del Sol and Balearic Islands sustain peak-season SUV and convertible demand from North American and British leisure segments. Municipal low-emission zones in Barcelona and Madrid enforce EU Green Deal-aligned access restrictions that favor electrified fleet deployment at airport hubs. Madrid-Barajas and Palma de Mallorca anchor the densest rental infrastructure, where operators reposition inventory dynamically between urban and resort corridors.
Italy
Amalfi Coast and Tuscany routes generate premium pricing for open-top configurations among experiential travelers from Asia-Pacific markets. ANSM oversight of urban access restrictions in Rome, Florence, and Milan compounds compliance complexity for cross-border fleet operators. Milan Malpensa and Rome Fiumicino concentrate capacity, with rail-station pickup density expanding through Trenitalia partnership networks.
France
Business traveler demand at Paris Charles de Gaulle and Lyon Saint-Exupéry sustains sedan and premium SUV utilization outside peak leisure windows. KBA-aligned technical standards for onboard telematics intersect with national Crit'Air emission classification systems that govern city-center access. Nice Côte d'Azur anchors Mediterranean leisure positioning, where seasonal margin compression is offset by ancillary attachment rates.
Germany
Corporate account density and airport-hub routing sustain premium fleet economics across Munich, Frankfurt, and Berlin corridors. CE marking requirements for connected vehicle systems and KBA homologation protocols shape technology procurement timelines. Bavaria and Baden-Württemberg concentrate fleet maintenance infrastructure, where high-voltage technician certification programs remain undersupplied relative to electrification targets.
United Kingdom
London Heathrow and Edinburgh gateways channel inbound tourism demand toward self-drive exploration of Scottish Highlands and Cotswolds circuits. Post-EU regulatory divergence complicates cross-border fleet utilization for operators serving both UK and continental routes. Manchester and Birmingham emerge as secondary density points where rail-air intermodal connectivity expands addressable market reach.
Europe Tourism Vehicle Rental Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating among operators maintaining dense airport and rail-station networks across Mediterranean tourism corridors. The competitive field stratifies into three archetypes: legacy multinational fleet operators with diversified mobility platforms, sustainability-focused specialists committing to electrified vehicle pools, and digital-native intermediaries leveraging aggregator positioning to capture booking flow without asset ownership. Dominant competitive moves include rail-station hub expansion to intercept intermodal transfer demand and vehicle-to-grid infrastructure partnerships that monetize idle fleet capacity.
Among legacy multinational operators, Enterprise Holdings and Avis Budget Group exemplify scale-driven positioning through dense airport presence and corporate account infrastructure. Sixt SE and Europcar Mobility Group occupy differentiated positions within the integrated tier, with German headquarters anchoring premium service configurations across business travel corridors. Green Motion International represents the sustainability-specialist archetype, competing through all-electric fleet commitments that align with EU Green Deal emission benchmarks and municipal low-emission zone access requirements.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Auto Europe |
| Sixt SE |
| Booking Holdings |
| OK Mobility |
| Avis Budget Group |
| Europcar Mobility Group |
| Green Motion International |
| Hertz Corporation |
| Others |
Supply & Pricing Matrix
CE marking requirements for onboard telematics and navigation systems simultaneously gate supplier qualification and enable price differentiation between connected fleet tiers and legacy rate-card operators across European tourism corridors.
Pricing Analysis
Contract structures bifurcate between long-term corporate fleet agreements with fixed daily rates and dynamic spot pricing for leisure segments booked through mobile-native interfaces. Three-tier pricing structure across premium, standard, and economy levels separates airport hub convenience from rail-station density and off-airport secondary locations. Cost compression in the economy tier intensifies as aggregator apps expose inventory to last-minute price discovery. Corporate account holders exhibit the lowest price sensitivity due to expense management integration, while backpacker segments drive aggressive rate competition.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg inflates inbound logistics costs for vehicle shipments from East Asian battery cell suppliers and German OEM assembly plants. Fleet procurement draws from Germany, France, and Spain for vehicle sourcing, with lithium-ion cells and semiconductor components feeding from South Korea and China. Single-source vulnerability concentrates in high-voltage battery management systems where qualified suppliers remain limited. Distribution runs through airport hub density and rail-station partnerships that reposition inventory between Mediterranean seasonal clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Insurance bundling and telematics-enabled ancillary services represent a service-attach opportunity expanding faster than base rental revenue across European tourism corridors.
For Market Incumbents: Consolidate rail-station hub density to intercept intermodal transfer demand before digital-native competitors establish automated pickup-dock installations. Acquire high-voltage technician certification capacity in Southern European service networks to defend against electrification-driven maintenance bottlenecks. Deepen backward integration into vehicle-to-grid infrastructure partnerships that monetize idle fleet capacity at tourism lodging clusters.
For New Entrants and Emerging Players: Mobile-native booking interface gaps in secondary Italian and Spanish cities offer white-space entry points where incumbents under-serve impulse reservation behavior. Target rail-station mobility hubs in tertiary markets with subscription rental models and automated pickup-dock density. Pursue geofenced app-exclusive pricing to build first-party data assets for yield management optimization.
For Investors and Strategic Acquirers: EU Green Deal emission benchmarks reshape the acquisition landscape by privileging operators with electrified fleet commitments and municipal low-emission zone access credentials. Long-term viability centers on asset-light platform models with subscription recurring revenue and charging infrastructure partnerships. Monitor ANSM and KBA urban access restriction announcements as inflection indicators for fleet homologation strategy shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Rail-Station Hub Expansion | Intermodal transfer density at Trenitalia and Renfe partnerships captures Mediterranean leisure flows. |
| Vehicle-to-Grid Infrastructure Partnership | Bidirectional charging at Costa del Sol lodging clusters monetizes overnight idle capacity. |
| High-Voltage Technician Certification Program | Bavaria and Baden-Württemberg training capacity addresses Southern European service network gaps. |
| Mobile-Native Booking Platform Launch | Geofenced pickup coordination builds first-party data assets for dynamic pricing algorithms. |
| CE Marking for Autonomous Valet Systems | Self-parking retrieval at Charles de Gaulle and Malpensa terminals compresses turnaround labor costs. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with fleet operations directors, yield management specialists, and rail-station partnership leads at rental operators across Spain, Italy, and France; and secondary validation through EU vehicle registration databases, airport authority traffic statistics, and ECHA REACH compliance filings. Bottom-up triangulation cross-referenced fleet size disclosures with utilization rate assumptions, while top-down approaches anchored total addressable market estimates against inbound tourism arrival patterns.
Across the analysis window, forecasts model vehicle type, rental duration, customer segment, and booking channel dimensions alongside charging infrastructure penetration and municipal low-emission zone expansion schedules. CAGRs derive from segment-level growth rate assumptions weighted by installed capacity and share rotation dynamics. Forecast inputs incorporate EU Green Deal subsidy windows, lithium-ion battery supply lead times, and licensed commercial driver availability constraints.
Underlying assumptions cover stable cross-continental leisure travel flows and REACH chemical compliance cost trajectories, with deviation risk concentrated in East Asian battery supply disruptions and municipal diesel ban acceleration timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Educational Tourism Market
Travel and Tourism
South Korea Sports Tourism Market
Travel and Tourism
US and Canada Travel Market
Travel and Tourism
Singapore Travel Retail Market
Travel and Tourism
Halal Tourism Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Asia Pacific Wellness Travel Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Cycle Tourism Market
Travel and Tourism
Singapore Tourism Market
Travel and Tourism
Tourism Market
Travel and Tourism
Wellness Tourism Market
Travel and Tourism
Middle East and Africa Travel Retail Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
China Outbound Travel Market