
 France Outbound Tourism Market | 2026-2036
France Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
France Outbound Tourism Market Foresight
Multi-source destination contracting is repositioning how French tour operators assemble inventory. Evaneos leverages its local-agent network across six continents to offer customizable itineraries. Intrepid Travel anchors its France outbound portfolio with small-group adventure tours to emerging destinations. Audley Travel specializes in tailor-made journeys to long-haul markets, competing on depth of in-country expertise.
France outbound tourism encompasses residents departing France for temporary stays abroad, typically spanning one to thirty nights, with trip composition determined by purpose, transport mode, and lodging selection. The sector serves commercial objectives including foreign exchange outflow, airline seat utilization, and cross-border hospitality revenue generation. Leisure travel dominates volume within the Travel Purpose dimension, while Medical and Adventure categories capture premium pricing per departure. Air transport leads the Transportation Mode segment for intercontinental routes, though Rail retains structural importance for intra-European movement.
ANSM oversees travel health advisories and vaccination requirements for French citizens visiting endemic regions, while CNIL governs passenger data processing under GDPR frameworks that constrain airline and operator CRM practices. The EU Green Deal's transport emissions benchmarks are forcing carriers to reconfigure short-haul networks and adjust slot allocations. Stakeholders must monitor how carbon border adjustments on aviation fuel reshape route economics and traveler price sensitivity before committing fleet or capacity investments.
Market Dynamics
EU Green Deal carbon reporting mandates are forcing French tour operators to restructure short-haul inventory sourcing and recalibrate destination portfolios toward rail-accessible corridors.
Growth Catalysts
- GDPR-compliant data frameworks:CNIL guidelines enable French operators to leverage first-party traveler data for personalization without cross-border compliance friction.
- Spain-Italy corridor concentration:High-frequency rail connections and shared cultural-linguistic ties sustain repeat booking velocity among French leisure travelers.
- Adventure travel infrastructure:Specialized outfitters in Morocco, Jordan, and Vietnam now offer French-language guiding capacity that unlocks premium-margin departures.
Market Restraints
- Aviation fuel cost volatility:Jet kerosene price swings compress margin on long-haul packages where air transport dominates trip economics.
- Carbon border adjustment exposure:EU Green Deal transport benchmarks threaten slot allocations on high-emission short-haul routes to Mediterranean beach destinations.
- Medical travel substitution:Domestic telehealth expansion and same-day surgery centers in Lyon and Toulouse reduce outbound elective procedure volumes.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur rail hubs:TGV station upgrades enable operators to originate ski-train packages directly from Marseille and Nice, bypassing Paris congestion.
- Regenerative tourism certification:EU Green Deal-aligned eco-labels create pricing power for operators who verify carbon-negative accommodations in Portugal and Slovenia.
- AI-native itinerary builders:Natural-language interfaces trained on French travel corpora compress quote-to-booking cycles for complex multi-stop journeys.
Industry Challenges
- Carbon accounting skill scarcity:Tour operators lack in-house capacity to verify Scope 3 emissions across fragmented supplier networks in emerging destinations.
- Legacy reservation system integration:Mid-size agencies struggle to connect GDPR-compliant CRM layers with decades-old GDS terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Outbound Tourism Market |
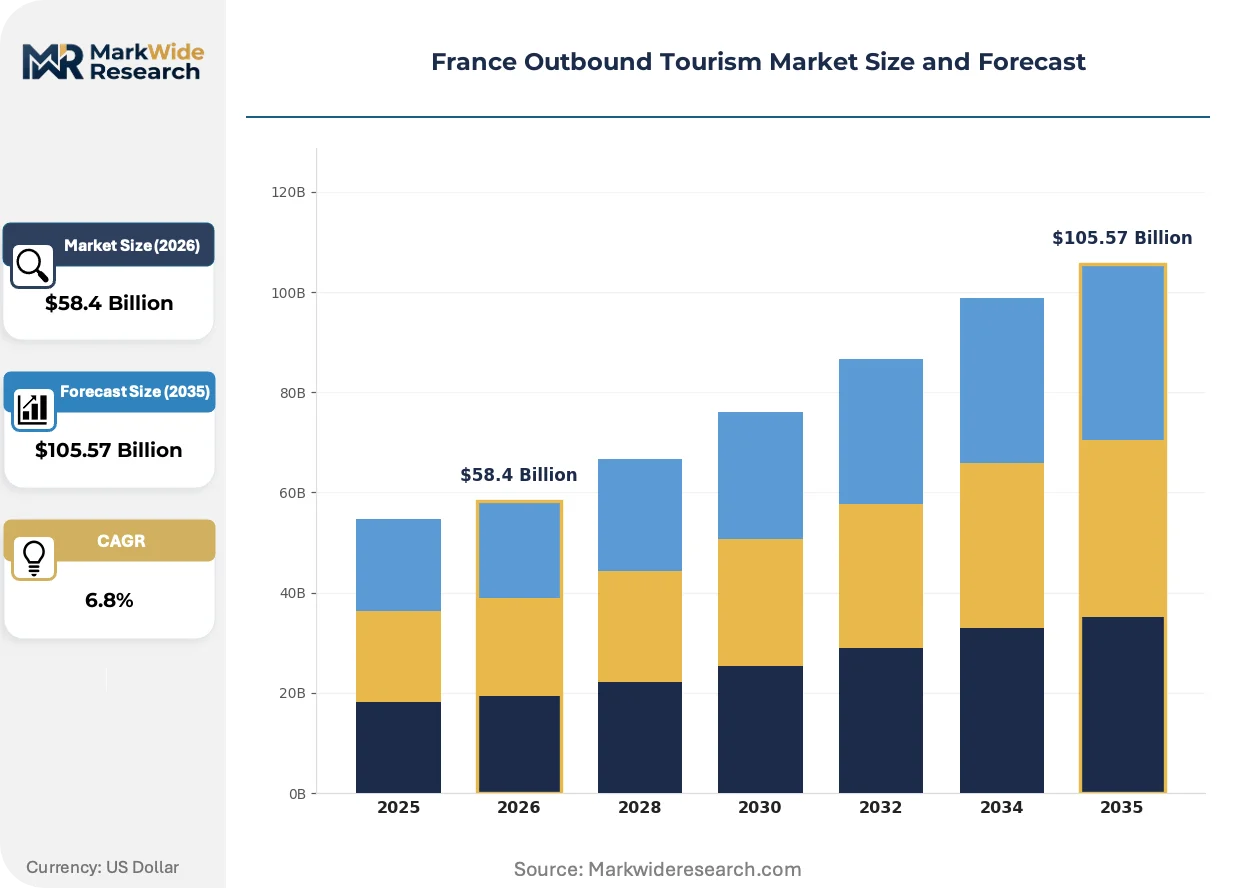
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $105.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Purpose: Leisure, Business, Education, Visiting Friends, Medical, Adventure Transportation Mode: Air, Rail, Cruise, Coach, Private Vehicle, Bicycle Accommodation Type: Hotels, Hostels, Vacation Rentals, Resorts, Bed & Breakfast, Boutique Customer Demographics: Millennials, Families, Seniors, Students, Solo Travelers, Couples |
| Companies Covered | Evaneos, Emerald Cruises, Intrepid Travel, Audley Travel, G Adventures, Exodus Adventure Travels, Colette, France Travel Solutions, Trafalgar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Outbound Tourism Market Shifts & Advancements
Digitization of the booking journey and regulatory pressure on transport emissions are converging to reshape how French travelers discover, purchase, and experience outbound trips.
AI-powered dynamic packaging engines are electrifying the traditional tour operator model. These systems ingest real-time inventory from rail, lodging, and activity APIs to assemble bespoke itineraries in seconds. French millennials and Gen Z travelers adopt these tools at three times the rate of older cohorts. The technology is electrifying price transparency and compressing the role of human agents to complex exception-handling only.
EU Green Deal transport emissions benchmarks are forcing carriers to reconfigure short-haul networks. Airlines serving French regional airports must now justify slot retention against rail alternatives on routes under four hours. The policy most affects summer charter operations to Spanish islands, where operators are responding by substituting TGV-Barcelona ferry combinations.
French travelers are fragmenting their booking behavior across single-purpose apps rather than consolidating with full-service agencies. Rail-only platforms capture intra-European trips; specialized medical travel brokers handle Tunisia and Turkey procedures; peer-to-peer lodging networks displace packaged accommodation in Portugal. This unbundling is most visible among Île-de-France residents under 35, who maintain four to six active travel subscriptions versus one traditional agency relationship.
France Outbound Tourism Market Segmentation
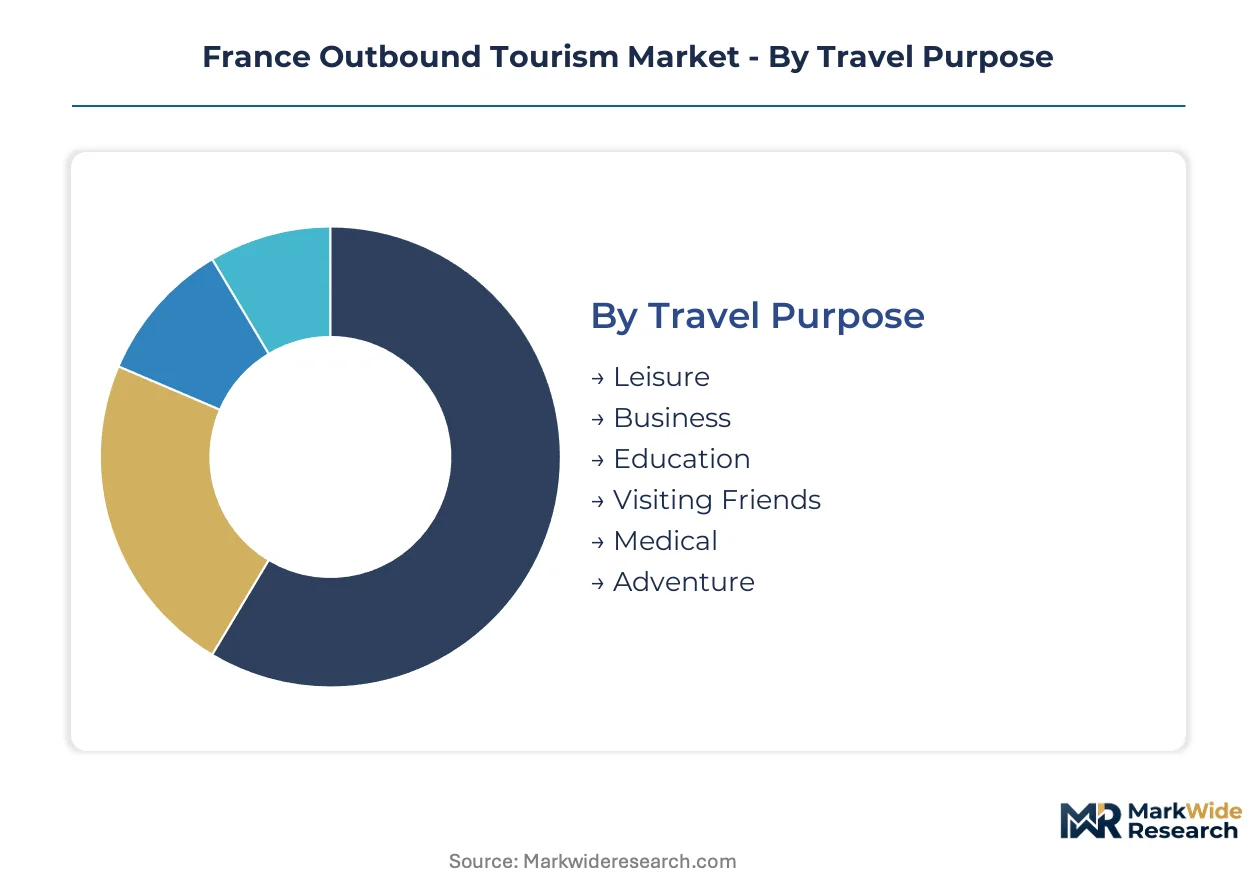
Outbound tourism from France fragments across four distinct dimensions that determine pricing power, distribution strategy, and regulatory exposure. Tour operators calibrate inventory sourcing and marketing spend differently for each intersection of purpose, transport, lodging, and traveler profile.
Travel Purpose:
Upgrade cycles in traveler motivation follow generational wealth accumulation and life-stage transitions, with younger cohorts prioritizing experience accumulation over asset ownership.
- Leisure:Beach holidays and city breaks dominate departure volumes, with French travelers concentrating demand in Spain and Italy during peak summer windows. Rail connectivity and short-haul flight density sustain repeat booking patterns across the Mediterranean basin.
- Business:Corporate travel procurement has shifted toward blended trips combining meetings with leisure extensions. The segment commands premium pricing per departure but faces permanent compression from virtual collaboration tools.
- Education:Language immersion programs and university exchanges generate extended-stay demand concentrated in UK, Ireland, and German-speaking markets.
- Visiting Friends:Diaspora connections to North Africa and Portugal drive seasonal peaks around religious holidays and summer reunions.
- Medical:Elective procedures in Tunisia and Turkey attract price-sensitive travelers from Provence-Alpes-Côte d'Azur seeking dental and cosmetic treatments outside French reimbursement frameworks.
- Adventure:Trekking, diving, and expedition travel to Morocco, Jordan, and Vietnam captures the steepest margin per departure through specialized French-language guiding infrastructure.
Leisure sits at the top of the volume ranking, with Adventure climbing the fastest.
Transportation Mode:
Modal choice correlates directly with journey distance and EU Green Deal carbon intensity thresholds that now govern slot allocations at French regional airports.
- Air:Jet transport retains dominance on intercontinental routes exceeding six hours, though carriers face mounting pressure to justify emissions on short-haul legs under four hours where TGV alternatives exist.
- Rail:High-speed connections to Spain, Italy, Belgium, and Germany displace aviation on business corridors under three hours. SNCF and Renfe interoperability investments are accelerating modal shift among corporate travel managers.
- Cruise:Mediterranean and Caribbean itineraries attract family and senior segments with bundled pricing that obscures transport costs within overall package value.
- Coach:Budget operators serve price-sensitive leisure travelers to Eastern European destinations where rail infrastructure remains underdeveloped.
- Private Vehicle:Car-dependent departures concentrate in cross-border trips to Italy, Switzerland, and Belgium where toll and fuel costs compete with rail pricing.
- Bicycle:Self-supported cycle touring generates niche demand for luggage transfer services and specialized accommodation along EuroVelo corridors.
Air transport maintains volume leadership, though Rail is expanding most quickly on routes where EU emissions benchmarks disadvantage aviation.
Accommodation Type:
Lodging selection reflects traveler age, trip purpose, and platform sophistication, with digital-native cohorts fragmenting bookings across specialized applications rather than consolidating with full-service agencies.
- Hotels:Branded properties dominate business travel procurement through negotiated corporate rates, while independent properties compete on location and character for leisure segments.
- Hostels:Shared lodging captures student and solo traveler demand in urban destinations where price sensitivity intersects with social experience seeking.
- Vacation Rentals:Platform-mediated apartments and villas displace packaged accommodation in Portugal and Spanish islands, particularly among Île-de-France families seeking space and kitchen facilities.
- Resorts:All-inclusive properties in Morocco and Tunisia attract package tour bookings from families and seniors preferring predictable budgeting and on-site activity programming.
- Bed & Breakfast:Small-scale rural lodging supports slow tourism initiatives in France's neighboring regions, with Auvergne-Rhône-Alpes and Occitanie origins driving demand.
- Boutique:Design-focused properties in Lisbon, Copenhagen, and Berlin attract millennial couples prioritizing aesthetic documentation and differentiated experience.
Hotels retain the highest departure share, yet Vacation Rentals are gaining share fastest among digital-native booking cohorts.
Customer Demographics:
Age and household structure determine platform adoption, destination risk tolerance, and sensitivity to carbon disclosure in travel purchasing decisions.
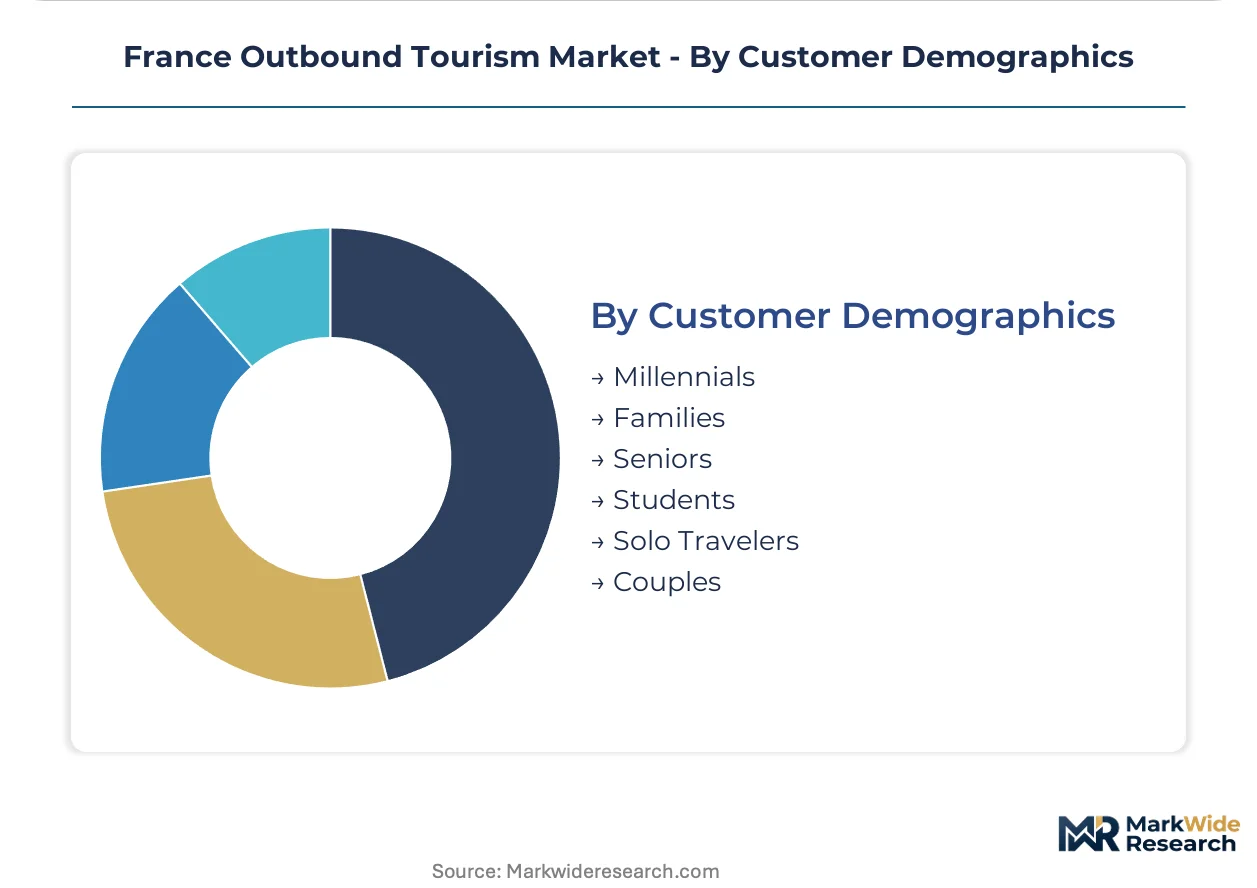
- Millennials:Digital-native travelers aged 28-43 drive adoption of AI-powered itinerary builders and dynamic packaging engines, with threefold higher platform switching rates than older cohorts.
- Families:Multi-generational departures concentrate in school holiday windows, with accommodation selection prioritizing kitchen facilities, pool access, and proximity to medical services.
- Seniors:Retiree travelers generate extended-stay demand in shoulder seasons, with cruise and coach tour operators capturing volume through accessibility-assured packaging.
- Students:Budget-constrained departures leverage rail passes, hostel networks, and low-cost carriers, with booking behavior concentrated in mobile-first platforms.
- Solo Travelers:Individual departures have expanded beyond business necessity into deliberate lifestyle choice, with specialized operators now offering single-supplement-free departures to emerging destinations.
- Couples:Dual-traveler bookings prioritize romantic positioning and dining experience, with boutique accommodation and premium rail cabins capturing disproportionate share.
Millennials lead absolute departure volumes, while Solo Travelers are expanding most quickly as social stigma around independent journeying dissipates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provence-Alpes-Côte d'Azur generates the densest concentration of France outbound departures, with Marseille and Nice airports serving as primary gateways for Mediterranean-bound leisure travelers.
Spain
High-frequency AVE and TGV connections to Barcelona and Madrid sustain rail-dominant booking patterns for city breaks and coastal holidays. Spanish tourism authorities enforce sustainability certification requirements under EU Green Deal alignment. Barcelona's port infrastructure anchors ferry-rail combinations that operators substitute for short-haul aviation to Balearic destinations.
Italy
Cultural proximity and shared Alpine access drive consistent demand for ski, gastronomy, and heritage itineraries across all French traveler demographics. Italian rail infrastructure investments under EU Cohesion Policy accelerate modal shift on Milan and Turin corridors. Florence and Rome concentrate boutique accommodation inventory that captures premium-couple segments from Île-de-France.
Portugal
Lisbon and Porto attract millennial travelers seeking design-forward urban experiences and Atlantic coastal alternatives to Mediterranean saturation. Portuguese tourism board incentives for carbon-neutral lodging align with EU Green Deal reporting frameworks. The Algarve region concentrates vacation rental inventory displacing traditional packaged accommodation among family segments.
Morocco
Proximity and French linguistic infrastructure sustain adventure and cultural tourism demand across trekking, desert expedition, and heritage segments. Moroccan aviation agreements with EU regulators govern slot allocations on Paris-Casablanca and Marseille-Marrakech routes. Marrakech and Fes anchor specialized French-language guiding networks that unlock premium-margin departures for adventure operators.
United Kingdom
Educational travel and diaspora connections generate extended-stay demand concentrated in London, Edinburgh, and university towns. Post-Brexit border documentation requirements administered by UK Visas and Immigration reshape booking lead times for French educational institutions. Eurostar's London terminal anchors rail-dominant business and leisure movements from Paris and Lille.
France Outbound Tourism Market Competitive Landscape
Established operators occupy the standard tier; emerging entrants pursue AI-native personalization and regenerative certification positioning. The vendor base clusters around three archetypes: rail-integrated platform specialists, adventure-focused small-group operators, and legacy full-service agencies with corporate travel heritage. Consolidation pressure concentrates among mid-size agencies struggling to connect GDPR-compliant CRM infrastructure with legacy reservation terminals. Portfolio diversification into medical travel brokerage and single-supplement-free solo departures represents the dominant competitive moves.
Within the platform-native tier, Evaneos exemplifies local-agent network aggregation across customizable long-haul itineraries. Intrepid Travel and G Adventures anchor the adventure-specialist segment with small-group expedition positioning to emerging destinations. These three operators collectively represent the shift from packaged inventory toward modular, experience-first trip construction that French millennials adopt at elevated rates.
| Leading Market Players |
|---|
| Evaneos |
| Emerald Cruises |
| Intrepid Travel |
| Audley Travel |
| G Adventures |
| Exodus Adventure Travels |
| Colette |
| France Travel Solutions |
| Trafalgar |
| Others |
Supply & Pricing Matrix
Jet kerosene price benchmarks cascade through French tour operator economics, compressing margins on long-haul packages where aviation dominates trip costs and forcing repricing across premium, standard, and economy tier structures. Carbon border adjustment exposure on Mediterranean short-haul routes further distorts inventory sourcing decisions, with rail-ferry combinations substituting for charter aviation on Spanish island departures.
Pricing Analysis
Input-cost pass-through from aviation fuel volatility reshapes package economics most acutely on intercontinental adventure itineraries to Morocco and Vietnam. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EU Green Deal-aligned eco-labels commanding measurable premiums. Cost compression in the standard tier intensifies because legacy operators struggle to verify Scope 3 emissions across fragmented supplier networks. Student and solo traveler segments exhibit highest price sensitivity, while adventure travelers demonstrate lowest elasticity due to specialized French-language guiding scarcity.
Supply Chain Analysis
Direct-to-consumer platforms and rail-integrated specialists now handle hyperscale booking demand previously captured by full-service agencies. Inventory sourcing concentrates in Spain, Italy, and Portugal for short-haul leisure, with Morocco and Vietnam anchoring adventure expedition supply. Accommodation procurement draws from vacation rental platforms, boutique property networks, and carbon-certified lodge operators. Single-source vulnerability pervades the local-agent network layer where Evaneos-style aggregation depends on fragmented in-country expertise. Distribution runs through API-connected dynamic packaging engines, mobile-first rail platforms, and legacy GDS terminals serving corporate travel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Outbound Tourism Market functions as a stable compounder, with millennial digital adoption and EU Green Deal regulatory alignment generating predictable reinvestment cycles across the forecast horizon.
For Market Incumbents: Anticipate margin compression on Mediterranean short-haul aviation by accelerating TGV-ferry package development and securing regenerative tourism certification for Portuguese and Slovenian inventory. Channel control through direct API connections to rail operators and vacation rental platforms defends against platform-native disintermediation. Certification investment in carbon-negative accommodation verification creates pricing power as EU Green Deal disclosure mandates harden. For New Entrants and Emerging Players: Launch via AI-native itinerary builders targeting millennial and Gen Z cohorts in Île-de-France, where platform switching rates run threefold above older demographics. White-space concentration sits in single-supplement-free solo departures to emerging destinations and medical travel brokerage for Tunisian and Turkish elective procedures. The most penetrable segment comprises rail-only intra-European city breaks where SNCF-Renfe interoperability investments have lowered modal friction. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-size agencies lack technical capacity to connect GDPR-compliant CRM layers with decades-old GDS infrastructure. Long-term viability favors operators with demonstrated carbon accounting competency and established local-agent networks across multiple continents. Acquisition target archetype: platform-native specialists with AI-powered dynamic packaging engines and verified regenerative tourism supply chains. The signal to watch is EU Green Deal transport emissions benchmark enforcement intensity on French regional airport slot allocations.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Itinerary Platform Launch | Natural-language interfaces trained on French travel corpora compress quote-to-booking cycles for complex multi-stop journeys. |
| Regenerative Tourism Certification Program | EU Green Deal-aligned eco-labels create pricing power for operators verifying carbon-negative accommodations in Portugal and Slovenia. |
| Rail-Integrated Inventory Sourcing | TGV station upgrades in Provence-Alpes-Côte d'Azur enable ski-train packages bypassing Paris congestion. |
| GDPR-Compliant CRM Modernization | CNIL guidelines enable first-party data leverage for personalization without cross-border compliance friction. |
| Adventure Travel Infrastructure Partnership | French-language guiding capacity in Morocco, Jordan, and Vietnam unlocks premium-margin expedition departures. |
Research Methodology
Bottom-up traveler segmentation modeling reconciled against top-down transport capacity tracking forms the analytical core of this study. Primary interviews with tour operator product directors, rail network planners, accommodation procurement managers, and CNIL compliance officers combined with secondary validation from SNCF operational data, EU Green Deal regulatory filings, and airport authority slot allocation records. Customs departure statistics, hospitality industry association reports, and digital platform transaction disclosures provided cross-referencing anchors for volume estimation.
Historical trendline analysis across departure volumes, modal share shifts, and accommodation type preferences established baseline growth patterns. The projection framework models travel purpose, transportation mode, lodging selection, and customer demographic dimensions throughout the forecast period. CAGRs derive from regression analysis against macroeconomic indicators, regulatory implementation schedules, and generational wealth transfer trajectories. Carbon intensity benchmarks and rail infrastructure investment pipelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Green Deal enforcement or prolonged aviation fuel price volatility. Outputs reflect documented assumptions regarding regulatory implementation timelines, generational platform adoption curves, and infrastructure completion schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
North America Travel Retail Market
Travel and Tourism
Solo Ecotourism Market
Travel and Tourism
Global Duty-Free and Travel Retail Market
Travel and Tourism
Japan Travel Retail Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Canada Travel and Tourism Market
Travel and Tourism
Japan Outbound Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
North America Pet Travel Services Market
Travel and Tourism
Tourism Vehicle Rental Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
Digital Travel Market
Travel and Tourism
Europe Wellness Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
Agritourism Market
Travel and Tourism
US and Canada Travel Market