
 Travel Agency Services Market | 2026-2036
Travel Agency Services Market Size, Share, and Industry Trends Forecast 2026-2036
Travel Agency Services Market Analytics
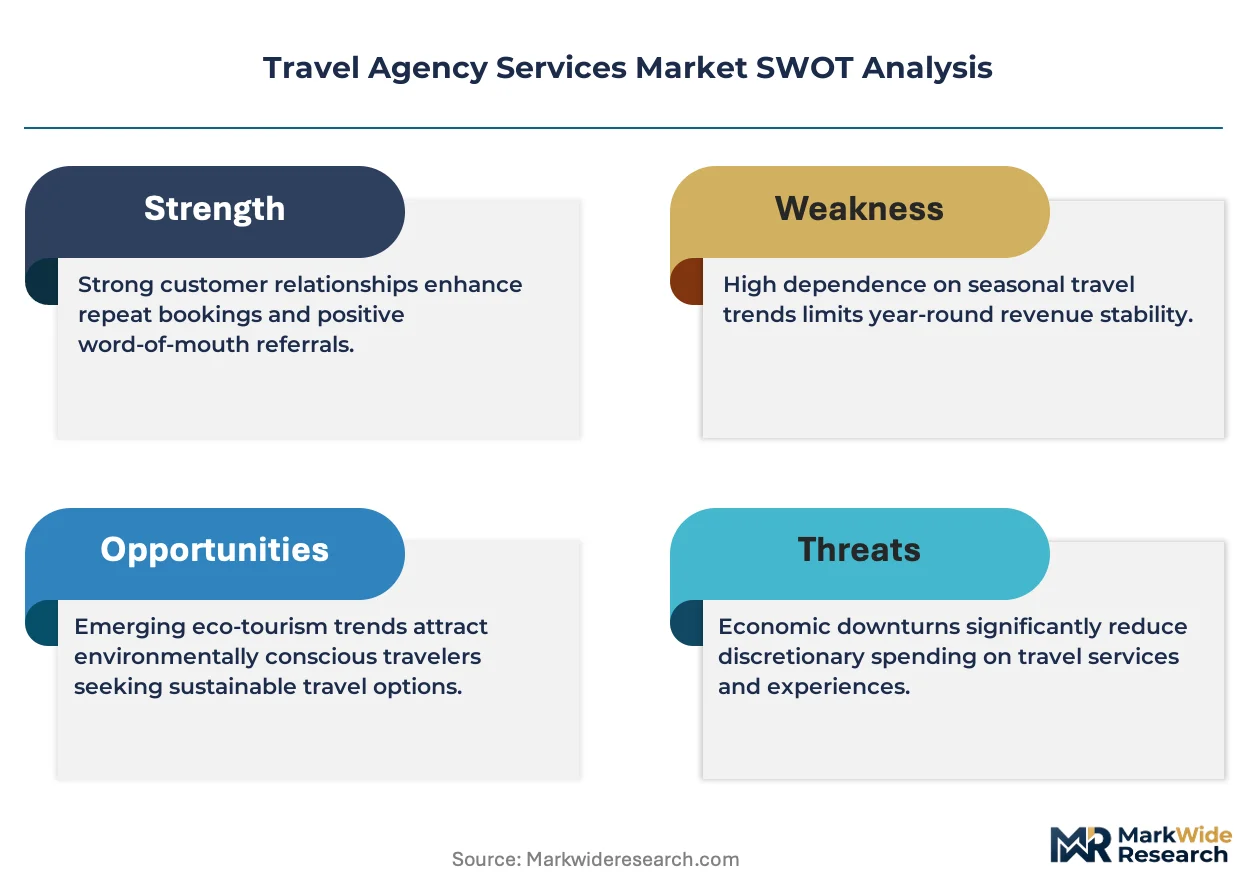
IATA's New Distribution Capability certification is collapsing the barrier between traditional agencies and digital retail platforms, forcing intermediaries to modernize technical infrastructure or lose airline content access. Booking Holdings leverages its proprietary API investments to sustain direct carrier connectivity, while American Express Global Business Travel anchors its position through captive corporate relationships and integrated expense management. Expedia Group competes on leisure packaging scale, controlling inventory breadth across hotels, flights, and activities.
Travel agency services encompass intermediation, itinerary design, booking execution, and post-purchase support for individual and group mobility, typically delivered through Global Distribution System connections, proprietary aggregation platforms, or direct supplier integrations that handle real-time inventory, fare rules, and payment settlement. The primary commercial purpose is reducing search friction and transaction complexity for travelers while extracting commissions or service fees from suppliers. Leisure travel dominates transaction volume but corporate travel commands superior per-booking margins and recurring contract structures; online platforms capture share from traditional travel agents through self-service automation, though high-touch segments including luxury and complex multi-city itineraries preserve agency relevance. Mobile apps represent the fastest-growing booking channel, displacing desktop interfaces as smartphone-native travelers expect seamless trip management.
FAA regulations governing charter broker disclosures and DOT consumer protection rules on refund timelines shape US agency operational compliance, while EU261 passenger rights mandates across European jurisdictions impose compensation liability chains that affect agency-seller relationships. GDPR data handling requirements constrain how European agencies profile customers and retarget prospects across digital channels. Stakeholders must monitor how NDC rollout timelines and carbon disclosure obligations rewrite supplier access economics and commission structures.
Market Dynamics
IATA's New Distribution Capability certification is collapsing the technical barrier between traditional travel agencies and digital retail platforms, forcing intermediaries to modernize infrastructure or lose direct airline content access. This structural shift rewrites supplier access economics and commission structures across the intermediation layer.
Growth Catalysts
- Corporate Hybrid Mobility:Enterprise travel buyers are expanding agency partnerships as hybrid work normalizes business mobility, sustaining recurring contract structures and per-booking margins.
- EU Green Deal Carbon Mandates:Transport providers face new carbon reporting obligations that reshape supplier qualification criteria, creating demand for agencies with verified sustainability credentials.
- Mobile-First Booking Migration:Smartphone-native travelers expect seamless trip management, driving platform investments in native app interfaces that displace desktop channels.
Market Restraints
- NDC Infrastructure Costs:Traditional agencies face prohibitive technical upgrade expenses to achieve IATA certification, squeezing smaller intermediaries from airline direct content.
- GDPR Data Constraints:European customer profiling and retargeting restrictions limit how agencies monetize behavioral data across digital marketing channels.
- Supplier Commission Compression:Airlines and hotels reduce intermediary payouts through direct booking incentives, eroding the core revenue model for transaction-dependent agencies.
Strategic Opportunities
- Luxury High-Touch Segmentation:Complex multi-city itineraries and ultra-high-net-worth leisure travel preserve agency relevance where automation fails, commanding premium service fees.
- Integrated Expense Management Convergence:Corporate travel agencies can deepen captive relationships by embedding spend control, reconciliation, and policy compliance into unified platforms.
- Post-Purchase Support Unbundling:Disruption management, real-time rebooking, and 24/7 traveler assistance emerge as standalone revenue streams distinct from transaction commissions.
Industry Challenges
- Legacy GDS Integration Complexity:Agencies operating on decades-old Global Distribution System architectures struggle to synchronize real-time inventory with modern API-driven retail interfaces.
- EU261 Compensation Liability Chains:European passenger rights mandates impose opaque accountability between airlines, agencies, and travelers when flight disruptions trigger automatic compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Travel Agency Services Market |
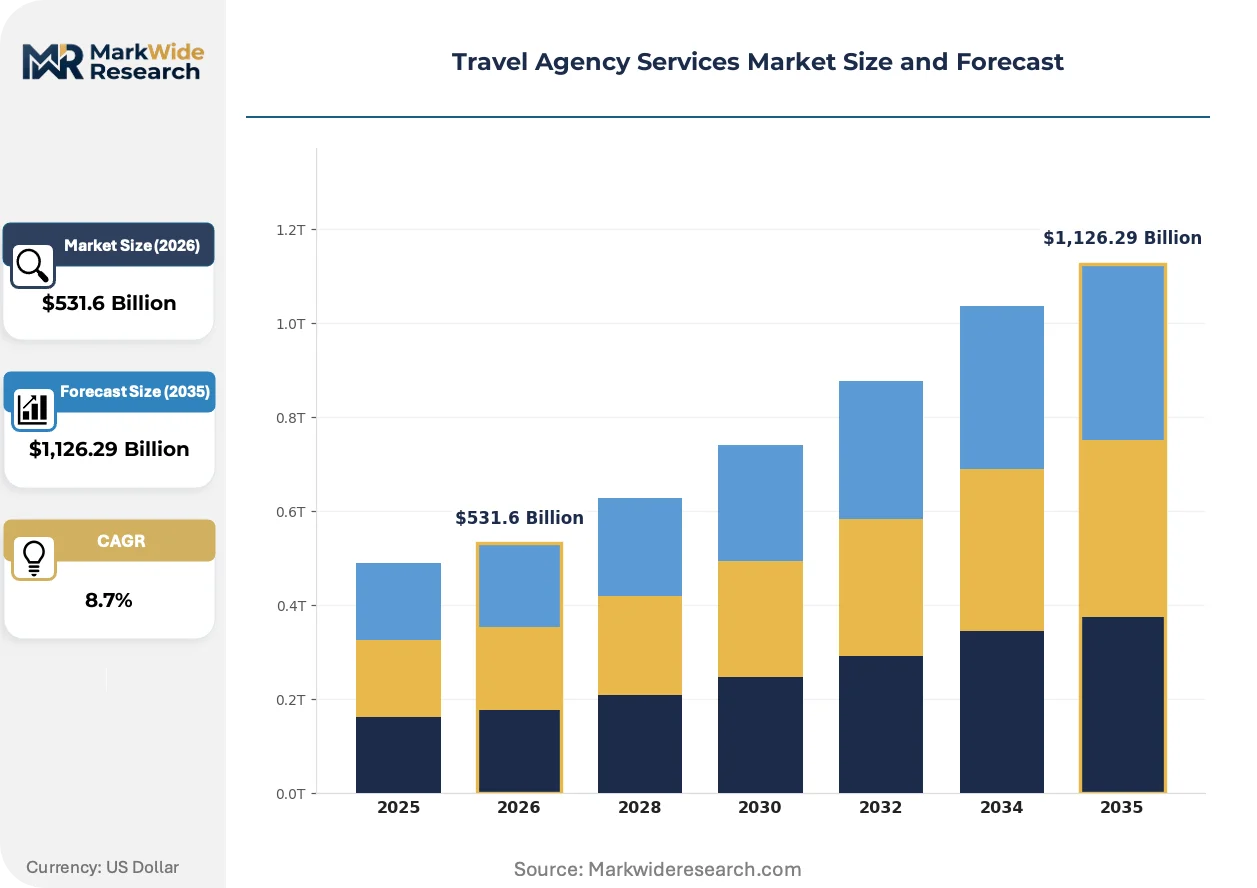
| Market Size in 2026 | $531.6 Billion |
| Market Size in 2035 | $1,126.29 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Leisure Travel, Corporate Travel, Event Planning, Group Tours Customer Type: Individual Travelers, Businesses, Families, Seniors Booking Channel: Online Platforms, Direct Booking, Travel Agents, Mobile Apps Price Tier: Luxury, Mid-Range, Budget, Discounted |
| Companies Covered | American Automobile Association, American Express Global Business Travel, Booking Holdings, Navan, BCD Travel, Expedia Group, Trip.com Group, SAP Concur, Internova Travel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Travel Agency Services Market Evolving Landscape
Technical modernization and regulatory compliance are converging to reshape how travel intermediaries capture value, with automation and transparency mandates rewriting competitive requirements across service tiers.
Artificial intelligence-powered itinerary optimization is supplanting rule-based fare search engines across online platforms. Leisure travelers now expect dynamic bundling of flights, hotels, and activities in single transactions. This compression of search friction is eliminating the traditional agency role in simple point-to-point bookings.
The EU Green Deal's carbon disclosure obligations for transport providers are mandating emissions transparency at the point of sale. Corporate procurement departments now require verified sustainability metrics in supplier qualification. European managed travel programs are prioritizing agencies with integrated carbon accounting over legacy intermediaries lacking environmental data capabilities.
Self-service mobile interfaces are capturing booking volume from voice and email channels in corporate travel programs. Procurement departments at mid-market enterprises are unbundling after-hours support from core transaction fees, paying only for disruption intervention. This shift is most pronounced in United States technology and professional services sectors where traveler autonomy reduces administrative overhead.
Travel Agency Services Market Segmentation
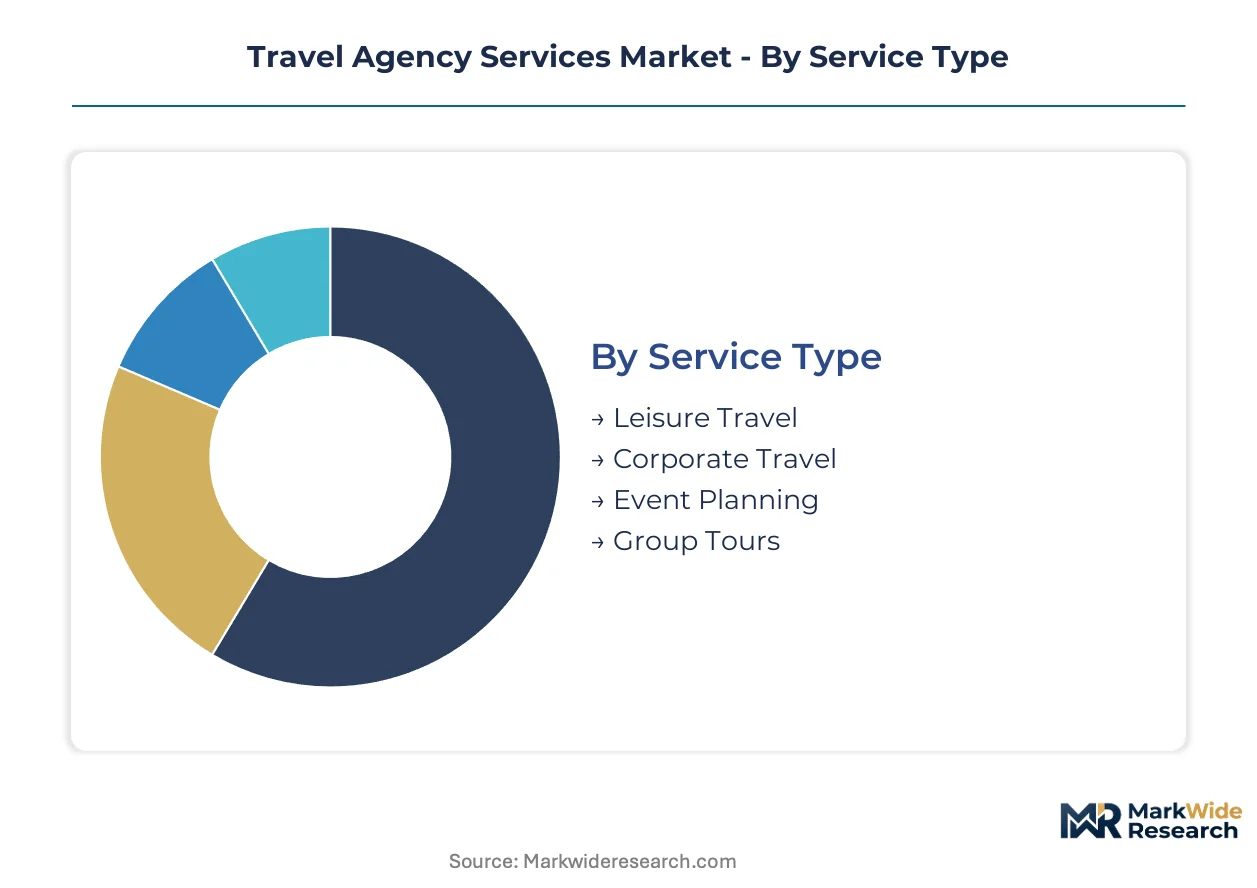
Segmentation in travel agency services reveals divergent margin economics across service tiers and customer profiles. Corporate contracts and luxury leisure command premium pricing power, while digital channels reshape cost-to-serve structures across all segments.
Service Type:
Margin pools concentrate in recurring corporate engagements and complex itinerary design where automation fails to displace human expertise.
- Leisure Travel:Transaction-heavy segment spanning packaged vacations, cruise bookings, and independent trip planning. Demand clusters in experiential and adventure sub-categories as travelers seek differentiated destinations beyond standardized resort offerings.
- Corporate Travel:Managed travel programs with embedded policy compliance and expense integration. United States enterprise buyers sustain this segment through hybrid work normalization and recurring contract structures that lock in agency relationships.
- Event Planning:MICE coordination combining venue sourcing, attendee logistics, and group air procurement.
- Group Tours:Curated multi-passenger itineraries with fixed departure schedules and volume-negotiated rates.
Corporate Travel holds installed capacity. Leisure Travel is rotating up the share rankings through mobile-first booking migration.
Customer Type:
Volume distribution skews toward digitally autonomous segments, though high-touch customer categories preserve fee-based revenue streams resistant to commission compression.
- Individual Travelers:Solo and couple bookings dominated by self-service platform usage. Smartphone-native expectations for seamless trip management are displacing traditional agent consultation for simple point-to-point itineraries.
- Businesses:SME and enterprise accounts with negotiated rate agreements and duty-of-care obligations. EU Green Deal carbon reporting mandates are reshaping supplier qualification criteria for this segment.
- Families:Multi-generational bookings requiring coordination complexity that preserves agency relevance.
- Seniors:Demographic segment favoring voice-channel support and comprehensive insurance packaging.
Businesses anchor contract value. Individual Travelers are climbing the fastest through app-native booking adoption.
Booking Channel:
Channel economics are inverting as infrastructure investments shift from GDS maintenance to direct API connectivity and native mobile development.
- Online Platforms:Aggregator websites with self-service search and dynamic packaging capabilities. IATA NDC certification requirements are collapsing technical barriers between these platforms and traditional agency content access.
- Mobile Apps:Smartphone-native interfaces capturing share from desktop channels. United States technology sector procurement departments are unbundling after-hours support from core transaction fees in this channel.
- Travel Agents:Human-intermediated booking with consultation and customization services.
- Direct Booking:Supplier-owned channels bypassing intermediary commission structures.
Online Platforms hold installed capacity. Mobile Apps are gaining share fastest through smartphone-native traveler expectations.
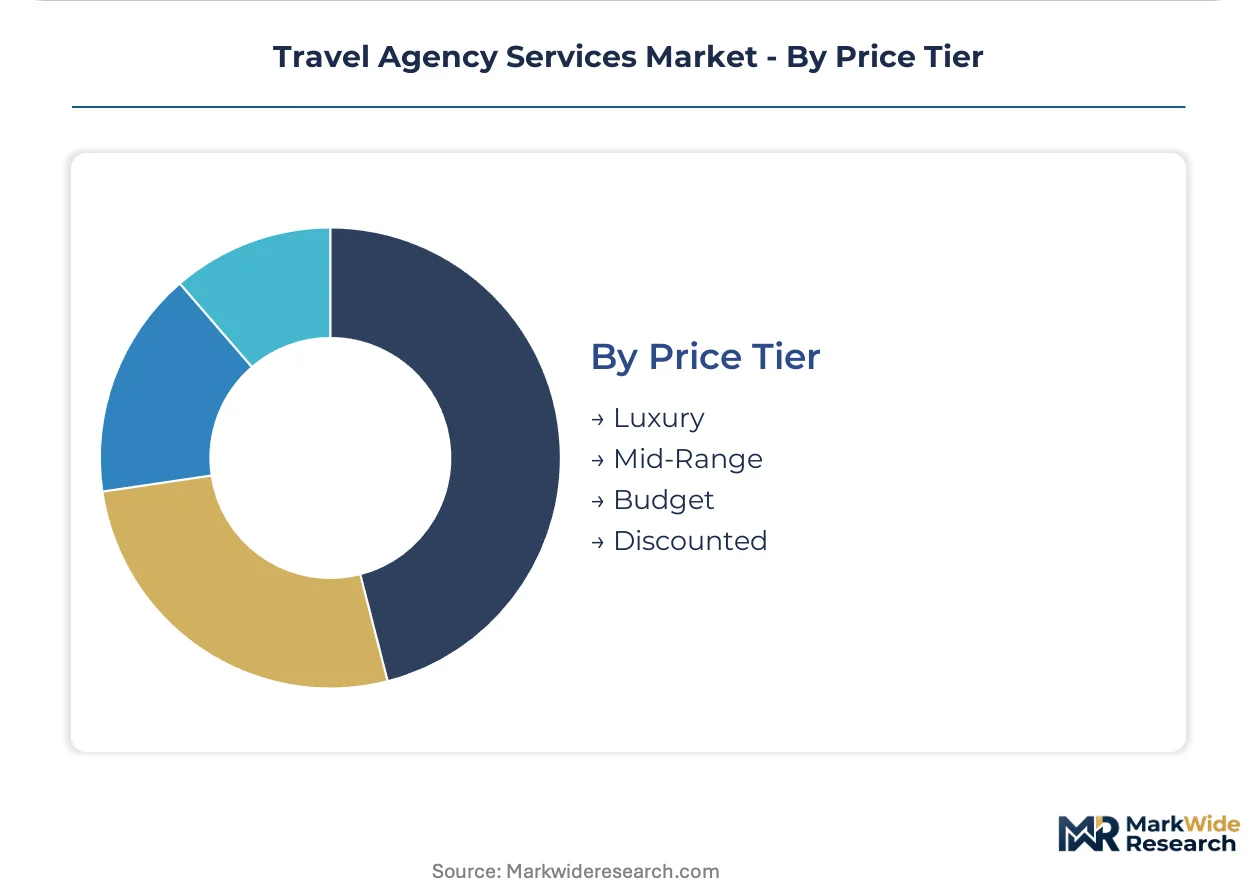
Price Tier:
Premium positioning correlates with service complexity and traveler risk tolerance, creating defendable margin zones above automated retail.
- Luxury:Ultra-high-net-worth segment with bespoke itinerary design and 24/7 concierge support. Complex multi-city arrangements and exclusive access requirements preserve agency relevance where automation fails.
- Mid-Range:Standardized leisure and corporate bookings with moderate customization. GDPR data constraints in European markets limit behavioral profiling and retargeting capabilities for this tier.
- Budget:Price-sensitive leisure with minimal service wrap and self-service fulfillment.
- Discounted:Opaque inventory and flash sale mechanisms with thin margins.
Luxury holds installed capacity. Mid-Range is rotating up the share rankings through corporate hybrid mobility expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon reporting mandates are reshaping supplier qualification criteria across European managed travel programs, while hybrid work normalization sustains corporate agency partnerships in the United States. Mobile-first booking migration concentrates in technology-forward urban clusters where smartphone-native travelers dominate.
United States
Enterprise managed travel programs sustain recurring contract structures as hybrid work normalizes business mobility. FAA regulations governing charter broker disclosures and DOT consumer protection rules on refund timelines shape operational compliance. Corporate procurement departments in the San Francisco Bay Area and New York Metro unbundle after-hours support from core transaction fees.
Germany
Industrial Mittelstand firms sustain corporate travel agency relationships with embedded policy compliance requirements. EU261 passenger rights mandates impose compensation liability chains affecting agency-seller relationships. Frankfurt and Munich anchor business travel volume concentration in the Rhine-Main and Bavarian economic corridors.
United Kingdom
Financial services sector procurement drives demand for integrated expense management platforms. GDPR data handling requirements constrain customer profiling and retargeting across digital channels. London's City and Canary Wharf clusters sustain premium corporate travel agency penetration despite commission compression pressures.
China
Domestic leisure travel volume surges through mobile-native booking platforms serving smartphone-first consumers. MIIT data localization requirements shape how international agencies operate cloud-based reservation infrastructure. Shanghai and Beijing metropolitan areas concentrate outbound travel agency services for high-net-worth segments.
India
Small and medium enterprise travel procurement expands as digital platforms reduce search friction for price-sensitive segments. RBI payment settlement regulations govern how agencies handle foreign exchange transactions for international bookings. Mumbai and Bangalore technology corridors drive corporate travel program adoption among SaaS and fintech firms.
Travel Agency Services Market Competitive Landscape
Player mix skews toward integrated platform operators with captive corporate relationships and proprietary technical infrastructure. Consolidation pressures squeeze transaction-dependent intermediaries lacking direct airline content access. Three archetypes dominate: expense-integrated managed travel providers, leisure packaging aggregators with inventory breadth, and high-touch luxury specialists. Competitive moves center on NDC certification achievement and strategic API investments that bypass legacy GDS dependencies.
Within the integrated platform tier, American Express Global Business Travel and SAP Concur exemplify expense-embedded corporate travel management. Booking Holdings and Expedia Group occupy positions as leisure packaging aggregators with proprietary inventory aggregation capabilities. Trip.com Group anchors the Asia-Pacific expansion vector for mobile-first booking platforms.
| Leading Market Players |
|---|
| American Automobile Association |
| American Express Global Business Travel |
| Booking Holdings |
| Navan |
| BCD Travel |
| Expedia Group |
| Trip.com Group |
| SAP Concur |
| Internova Travel Group |
| Others |
Value Network & Pricing Analysis
Scale economies in Global Distribution System maintenance create fixed-cost barriers that concentrate intermediary capacity among platform operators with proprietary API infrastructure, compressing price floors for transaction-dependent agencies while elevating fee-based service premiums for certified NDC-compliant intermediaries.
Pricing Analysis
Certification level (IATA NDC-compliant vs. legacy GDS-dependent) creates the primary spread between premium service fees and commodity transaction margins. Pricing stratifies across premium, standard, and economy tiers, with luxury high-touch segments commanding bespoke itinerary design fees while budget self-service platforms compete on minimal markup. Cost compression in mid-range corporate travel is intensifying because procurement departments unbundle after-hours support from core transaction fees. SME buyers exhibit highest price sensitivity, whereas ultra-high-net-worth leisure travelers demonstrate minimal elasticity for complex multi-city arrangements.
Supply Chain Analysis
Real-time inventory synchronization demands compress lead times from days to milliseconds across airline-hotel-activity bundling platforms. Supply concentration rests on proprietary API investments in the United States, GDS infrastructure in Germany and the United Kingdom, and mobile-native aggregation platforms in China. Raw material dependencies include airline direct content feeds, hotel property management system integrations, and payment settlement rails. Single-source vulnerability emerges from IATA NDC certification bottlenecks that gate direct carrier access. Distribution runs through hybrid models combining self-service platforms with human-intermediated consultation for complex segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Travel agency services fragmentation creates acquisition opportunities as NDC certification requirements and carbon disclosure mandates splinter competitive positioning across specialized service tiers. Hybrid work normalization generates niche demand for integrated expense management platforms serving mid-market enterprises.
For Market Incumbents: Shield recurring corporate contract structures by embedding SAP Concur-grade expense reconciliation and policy compliance into unified platforms. Accelerate proprietary API investments that bypass legacy GDS dependencies to secure direct airline content access before NDC rollout timelines squeeze uncertified intermediaries from supplier relationships.
For New Entrants and Emerging Players: Anchor in post-purchase support unbundling as a standalone revenue stream, targeting United States technology sector procurement departments that now pay separately for disruption intervention and 24/7 traveler assistance. Penetrate the SME managed travel segment through mobile-first booking interfaces with transparent carbon accounting features that satisfy EU Green Deal supplier qualification criteria.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors expense-integrated managed travel providers with captive corporate relationships and proprietary technical infrastructure over transaction-dependent leisure aggregators. Long-term viability hinges on NDC certification achievement and strategic API investments that secure direct carrier connectivity. Monitor IATA certification timelines as the critical inflection signal distinguishing sustainable platform operators from stranded legacy intermediaries.
| Strategic Initiative | Industry Significance |
|---|---|
| NDC Certification Achievement | IATA certification secures direct airline content access and rewrites supplier commission economics for intermediaries. |
| Proprietary API Investment | Direct carrier connectivity bypasses legacy GDS dependencies and reduces third-party platform fees. |
| Integrated Expense Management Convergence | SAP Concur-style spend control embedding deepens captive corporate relationships and policy compliance. |
| Carbon Accounting Integration | EU Green Deal verification capabilities reshape supplier qualification criteria for European managed travel programs. |
| Mobile-First Platform Development | Smartphone-native interfaces capture booking volume from desktop channels in United States technology corridors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of corporate travel procurement databases, IATA NDC implementation filings, EU Green Deal regulatory disclosures, and mobile platform usage analytics. Primary interviews engaged travel management company executives, corporate procurement officers at technology and financial services firms, airline distribution strategy leads, and hotel chain revenue management directors. Bottom-up transaction volume estimates triangulate against top-down market sizing from customs records and platform commission disclosures.
Segmentation dimensions modeled include service type (leisure, corporate, event planning, group tours), customer type (individual, business, family, senior), booking channel (online platforms, mobile apps, travel agents, direct booking), and price tier (luxury, mid-range, budget, discounted). CAGRs derive from trend extrapolation of mobile-first adoption curves, hybrid work normalization patterns, and NDC rollout penetration across the projection horizon. Industry-specific inputs incorporate corporate travel program renewal rates and leisure packaging bundling coefficients.
Material uncertainties — IATA NDC timeline acceleration, EU261 compensation liability rulings, airline direct booking incentive intensification — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance cost trajectories and technology adoption S-curves. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hospitality and Tourism
South Africa Sports Tourism Market
Hospitality and Tourism
River Cruises Market
Hospitality and Tourism
Europe Casino Management Market
Hospitality and Tourism
Safari Tourism Market
Hospitality and Tourism
Hotel Ice Dispensers Market
Hospitality and Tourism
Saudi Arabia Wedding Services Market
Hospitality and Tourism
Singapore Hospitality Market
Hospitality and Tourism
Corporate Travel Agency Market
Hospitality and Tourism
Germany Outbound Tourism Market
Hospitality and Tourism
Global Offshore Catering Services Market
Hospitality and Tourism
Golf Tourism Market
Hospitality and Tourism
US Recreational and Vacation Camp Market
Hospitality and Tourism
Spain HRI Market
Hospitality and Tourism
Vacation Ownership Market
Hospitality and Tourism
Asia-Pacific Travel Retail Market
Hospitality and Tourism
Asia-Pacific Wedding Services Market