
 Japan Outbound Tourism Market | 2026-2036
Japan Outbound Tourism Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Outbound Tourism Market Outlook
Platform licensing revenue from dynamic packaging engines is reshaping how Japanese travel distributors capture margin from international hotel inventory. JTB Corporation leverages its century-old agency network to sustain offline-to-online conversion among senior demographics. HIS Co., Ltd. anchors its competitive position through in-house charter operations and destination management subsidiaries across Asia-Pacific. Rakuten Travel differentiates via super-app integration, bundling outbound flights with domestic e-commerce loyalty points.
Japan outbound tourism encompasses residents departing for temporary stays exceeding twenty-four hours, involving air and sea transport, accommodation procurement, and destination services across foreign jurisdictions. The sector operates through a dual-structure of packaged tour products and independent FIT arrangements, with real-time inventory connectivity replacing static allotment contracts. Leisure travel purpose commands the dominant margin pool, particularly in multi-city European itineraries and resort-focused Southeast Asian bookings. Solo traveler demographics within the travel segmentation are expanding fastest, driven by retired baby boomers and female professionals seeking structured yet unescorted experiences. Online travel agencies within booking channel segmentation are displacing storefront agents for short-haul routes, though complex long-haul products retain agent-mediated sales.
METI enforces consumer protection standards under the Travel Agency Act, mandating escrow arrangements and disclosure requirements that elevate compliance costs for digital entrants. JIS standards for travel service quality certification shape supplier qualification protocols for Japanese tour operators sourcing overseas ground services. PMDA oversight of travel health advisories and vaccination documentation influences destination accessibility during health security events. Stakeholders must monitor how Japan's digital platform governance evolves to determine whether super-app consolidation or specialized niche portals capture the next wave of booking migration.
Market Dynamics
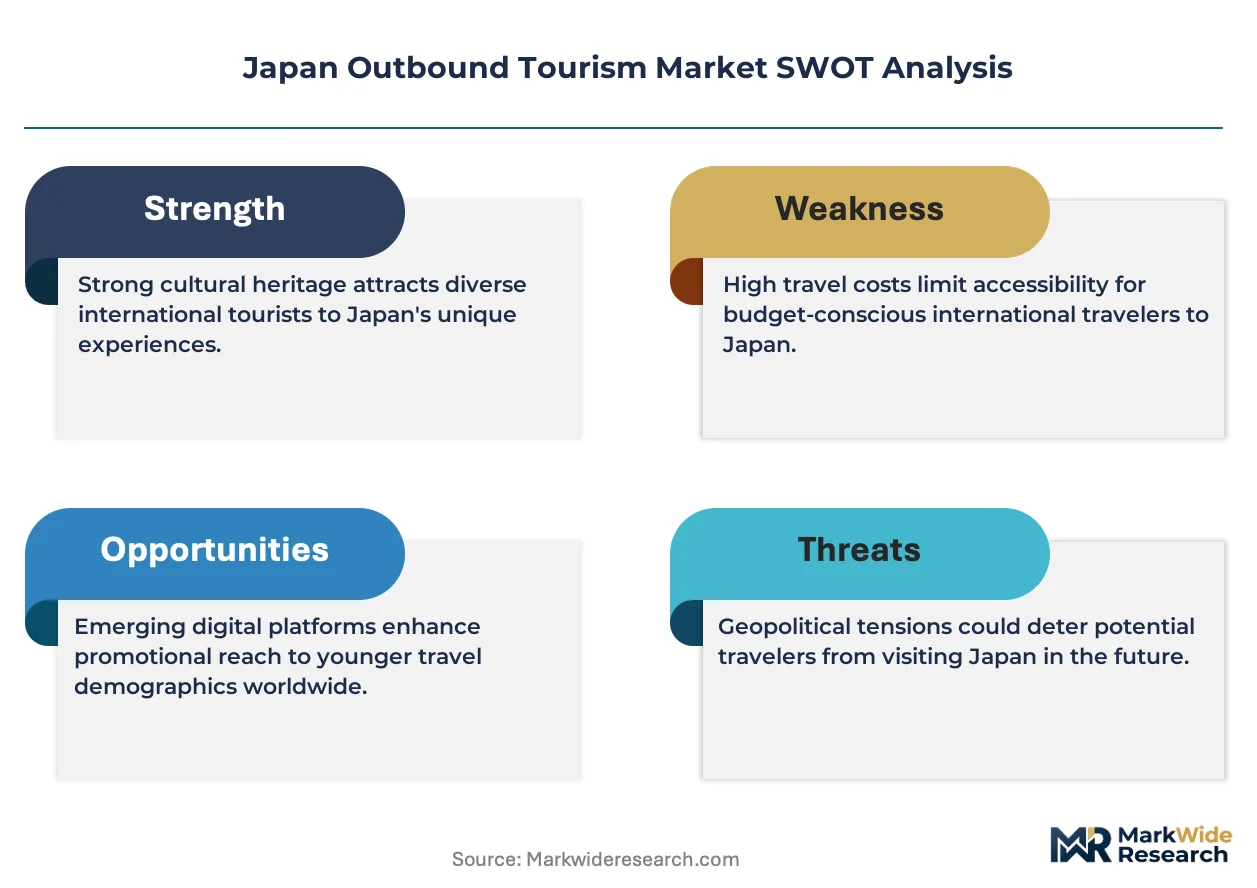
Digital platform standardization under METI is compressing the traditional storefront agency model while accelerating migration to super-app booking ecosystems. This structural force is redistributing margin capture from offline intermediaries to integrated inventory aggregators.
Growth Catalysts
- Yen depreciation dynamics:Competitive exchange rates against Southeast Asian currencies are expanding real purchasing power for Japanese leisure travelers in Thailand and Vietnam.
- METI Travel Agency Act enforcement:Escrow and disclosure mandates are elevating consumer trust in digital booking channels, accelerating online migration among risk-averse demographics.
- Charter flight infrastructure:In-house aircraft leasing by major tour operators is compressing per-seat costs on high-frequency routes to beach destinations.
Market Restraints
- Fuel surcharge volatility:Jet fuel price fluctuations represent an unhedged cost component that erodes package tour margins on long-haul European itineraries.
- Ground service supplier concentration:Destination management subsidiaries in Bangkok and Ho Chi Minh City create dependency on single-market labor availability.
- JIS certification timelines:Quality standard verification for overseas hotel partners extends supplier onboarding cycles by several quarters.
Strategic Opportunities
- Kyushu and Hokkaido feeder markets:Underpenetrated regional departure points beyond Tokyo and Osaka offer white-space expansion for direct charter routing.
- Health security documentation platforms:PMDA-aligned vaccination verification systems create service revenue streams for technology-integrated agencies.
- Super-app loyalty convergence:E-commerce point redemption bundling with outbound air inventory is capturing share from standalone travel portals.
Industry Challenges
- Bilingual itinerary design talent:Shortage of Japanese-English speaking product managers capable of structuring complex multi-city European offerings.
- Legacy reservation system integration:Mainframe-based inventory platforms at established agencies resist API connectivity with dynamic packaging engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Outbound Tourism Market |
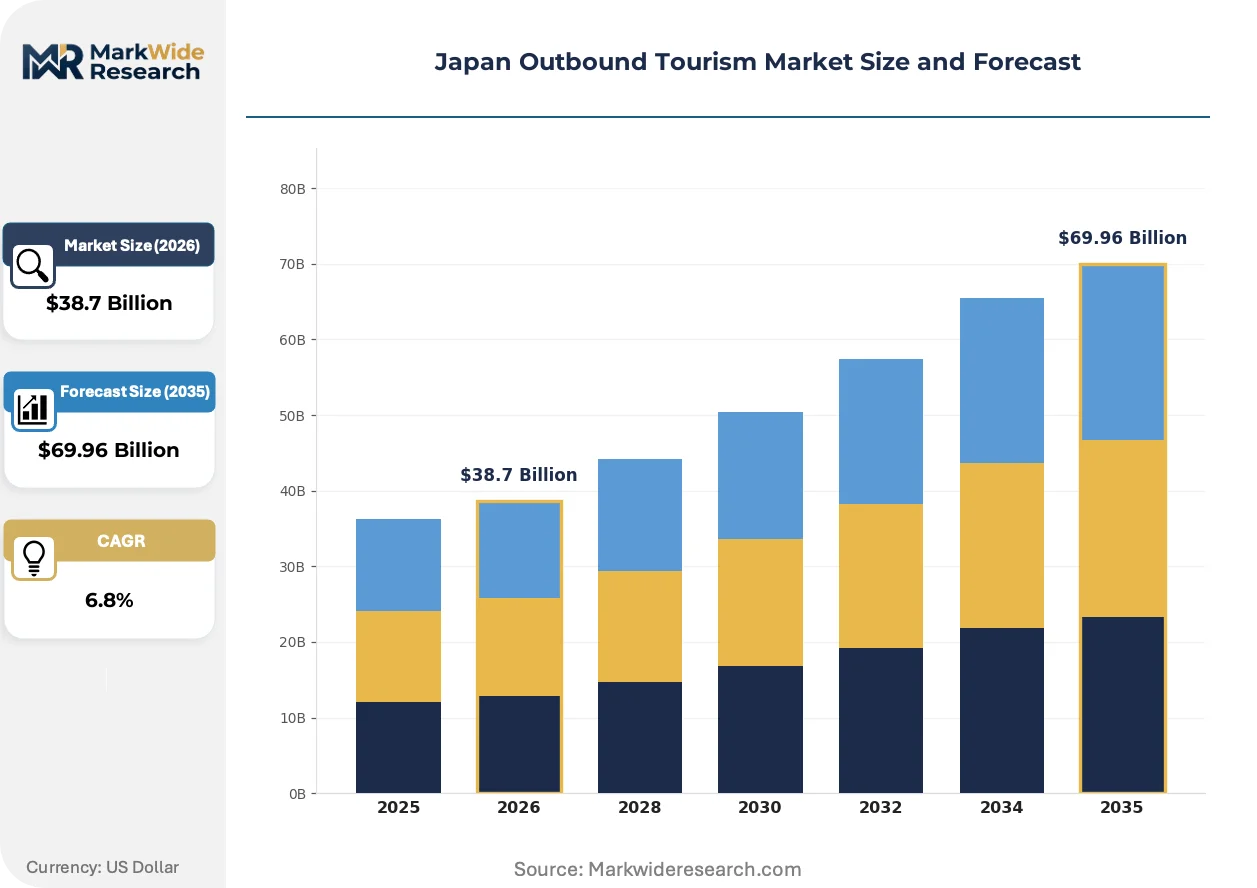
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Purpose: Leisure, Business, Education, Religious Travel Duration: Short-term, Long-term, Weekend, Extended Stay Travel Demographics: Families, Couples, Solo Travelers, Group Tours Booking Channel: Online Travel Agencies, Direct Booking, Travel Agents, Mobile Apps |
| Companies Covered | JTB Corporation, HIS Co., Ltd., Rakuten Travel, Expedia Japan, ANA X Inc., KNT-CT Holdings, JALPAK, Club Tourism International, VELTRA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Outbound Tourism Market Strategic Shifts
Real-time inventory connectivity is displacing static allotment contracts across Japanese tour distribution. Three convergent developments are restructuring how travelers discover, configure, and purchase international journeys.
Dynamic packaging engines are hybridizing flight, hotel, and ground components into algorithmically assembled itineraries. Mid-sized online agencies are adopting these tools fastest, compressing the traditional 48-hour quote cycle to instant confirmation. This hybridizing capability is eroding the price-discovery advantage historically held by storefront agents with manual supplier relationships.
METI's push for platform interoperability standards is mandating open API architectures across licensed travel distributors. The industrial consequence is forced unbundling of proprietary inventory systems, enabling third-party aggregators to access previously walled supplier networks. Short-haul beach package operators face the steepest compliance costs as they retrofit legacy infrastructure.
Solo traveler segments are abandoning group escort formats in favor of structured independent arrangements. Female professional demographics in their thirties and forties are driving this pivot, substituting flexible day-trip modules for fixed coach itineraries. This behavioral shift concentrates in Southeast Asian destinations where safety-perceived infrastructure supports unescorted exploration.
Japan Outbound Tourism Market Segmentation
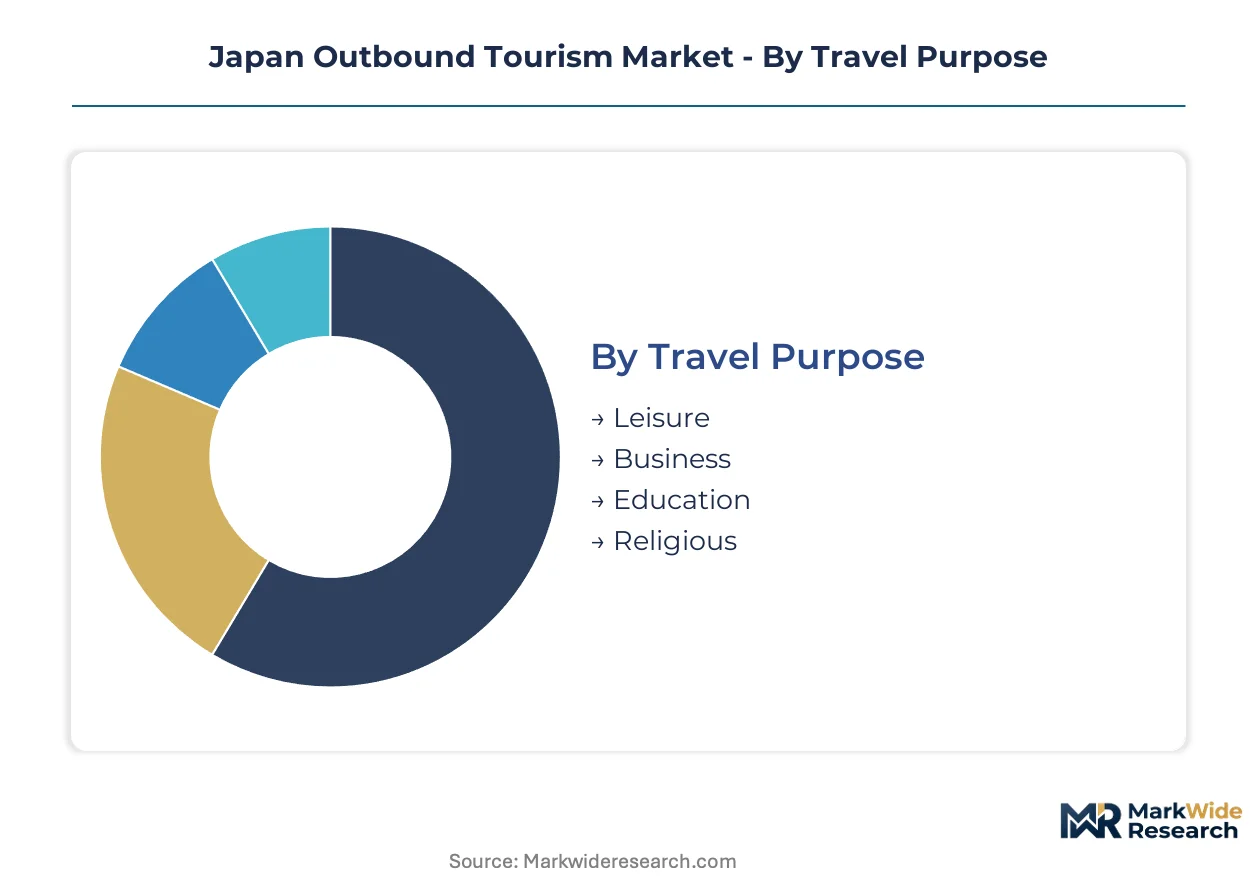
Japanese outbound travel demand fragments across four intersecting dimensions that determine pricing power, distribution strategy, and supplier selection. Tour operators calibrate inventory allocation and commission structures differently for each combination of purpose, duration, demographic, and booking channel.
Travel Purpose:
Leisure travelers span beach resort escapes, European cultural circuits, and food tourism itineraries with vastly different margin profiles and advance booking windows.
- Leisure:Multi-city European itineraries and Southeast Asian beach packages generate the dominant revenue pool. Retired baby boomers concentrate purchasing in Thailand and Vietnam as yen depreciation expands real purchasing power against local currencies.
- Business:Corporate travel procurement operates through contracted TMC relationships with negotiated airline corporate rates and centralized expense platforms. Post-pandemic hybrid work patterns have compressed traditional quarterly international meeting rotations.
- Education:Language immersion programs and university exchange semesters involve extended accommodation procurement and visa documentation services. Parent-funded bookings retain agent-mediated sales despite online migration elsewhere.
- Religious:Pilgrimage circuits to Buddhist sites in India and Christian heritage locations in Europe sustain specialized tour operators with clergy-guided group formats.
The dominant share belongs to Leisure, while Solo Travelers within that purpose bracket is closing the gap fastest.
Travel Duration:
Duration determines aircraft utilization economics and hotel contract structures, with short-haul beach routes optimized for high-frequency weekend departures.
- Short-term:Three-to-five-day itineraries concentrate in Southeast Asian beach destinations with charter flight compression. HIS Co. and JTB anchor competitive position through in-house aircraft leasing on Bangkok and Ho Chi Minh City routes.
- Long-term:European multi-city circuits spanning ten to fourteen days command premium pricing and complex ground logistics. Bilingual product managers capable of structuring these offerings remain scarce across Japanese agencies.
- Weekend:Two-night departures to Guam and Saipan sustained pre-pandemic volume but face competition from domestic alternatives as regional Japanese airports expand international connectivity.
- Extended Stay:Month-plus arrangements for snowbird retirees and remote workers require visa navigation and apartment-style accommodation sourcing beyond standard hotel inventory.
Short-term captures the volume base, though Extended Stay is expanding most quickly as remote work normalization enables location-independent living.
Travel Demographics:
Demographic targeting shapes marketing channel selection and itinerary design philosophy, with solo traveler growth forcing product architecture changes.
- Solo Travelers:Female professionals in their thirties and forties are abandoning group escort formats for structured independent arrangements with flexible day-trip modules. This pivot concentrates in safety-perceived Southeast Asian destinations.
- Families:Multi-generational bookings involving grandparents, parents, and children require room block coordination and age-diverse activity programming. School vacation calendars determine peak pricing windows.
- Couples:Honeymoon and anniversary segments sustain premium resort inventory in Maldives and Tahiti with commission structures favoring specialized romance tour operators.
- Group Tours:Fixed coach itineraries with escort guides retain share among senior demographics where JTB's century-old agency network sustains offline-to-online conversion.
Solo Travelers is gaining share fastest, while Families retains the largest absolute booking volume.
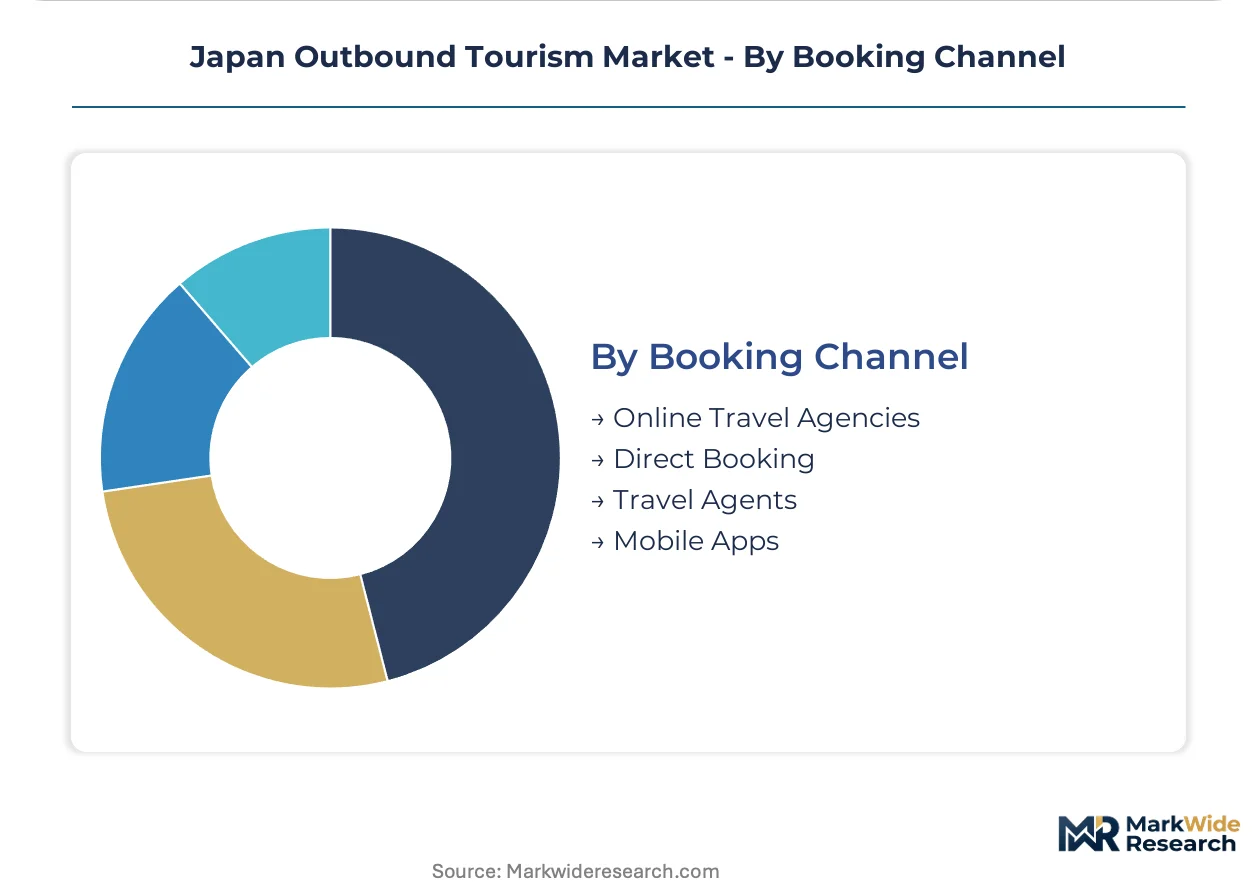
Booking Channel:
Channel migration is compressing storefront agency margins while redistributing margin capture to integrated inventory aggregators with super-app ecosystems.
- Online Travel Agencies:Dynamic packaging engines enable instant confirmation of hybridized flight-hotel-ground components. Mid-sized agencies adopting these tools fastest are eroding the price-discovery advantage historically held by storefront agents.
- Mobile Apps:Rakuten Travel differentiates via super-app integration bundling outbound flights with domestic e-commerce loyalty points. METI's platform interoperability mandates are forcing open API architectures that enable this convergence.
- Travel Agents:Complex long-haul European products retain agent-mediated sales where manual supplier relationships and itinerary customization justify commission premiums. Legacy reservation system integration remains a structural barrier.
- Direct Booking:Airline and hotel proprietary channels capture share through member-exclusive rates, though Japanese travelers show persistent preference for third-party price comparison.
Online Travel Agencies holds the dominant position, while Mobile Apps is climbing the fastest as super-app loyalty convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese leisure travelers deploy purchasing power differently across destination geographies, with Southeast Asian beach markets absorbing volume-sensitive packages while European corridors command premium-margin cultural itineraries. This consumption-mix differential shapes how tour operators allocate charter capacity and ground service investments.
Thailand
Bangkok and Phuket dominate Japanese short-haul beach demand, with yen depreciation expanding real purchasing power against the baht. Thailand's Tourism Authority runs joint marketing programs with METI-registered Japanese operators. HIS Co. maintains destination management subsidiaries in Bangkok handling ground logistics for volume charter routes.
Vietnam
Ho Chi Minh City and Da Nang capture growing share of Japanese solo travelers seeking safety-perceived unescorted exploration. Vietnam's Ministry of Culture, Sports and Tourism issues licensing frameworks for inbound Japanese tour operators. JTB Corporation sources extended-stay apartment inventory in Da Nang for remote-working snowbird demographics.
France
Paris and Lyon anchor multi-city European cultural circuits commanding ten-to-fourteen-day premium itineraries. French tourism regulators enforce package travel financial protection standards aligned with METI escrow requirements. Bilingual product managers capable of structuring complex French regional rail connections remain scarce across Japanese agencies.
Italy
Rome, Florence, and Venice concentrate food tourism and religious pilgrimage demand from Japanese travelers. Italy's national tourism board coordinates with METI on travel agency licensing reciprocity. Specialized operators in Osaka and Tokyo maintain clergy-guided group formats for Buddhist heritage circuits in India extending through Italian Christian sites.
Hawaii
Honolulu retains legacy position for weekend beach departures though facing competition from domestic Japanese alternatives. The Hawaii Tourism Authority manages destination marketing agreements with major Japanese charter operators. Guam and Saipan routes from regional Kyushu airports erode traditional Hawaii dominance for short-duration leisure.
Japan Outbound Tourism Market Competitive Environment
Capability concentration sits with established tour operators possessing in-house charter infrastructure; scale advantage sits with digital platforms integrating super-app loyalty ecosystems. The market structures around three tiers: legacy agency networks with century-old brand recognition, vertically integrated operators controlling aircraft and ground assets, and technology-driven aggregators bundling travel with e-commerce. Dominant competitive moves include charter flight capacity expansion on high-frequency Southeast Asian routes and dynamic packaging engine licensing for instant inventory confirmation.
Within the legacy network tier, JTB Corporation exemplifies offline-to-online conversion capabilities among senior demographics through its storefront presence. HIS Co., Ltd. occupies the vertically integrated position with in-house charter operations and Asia-Pacific destination management subsidiaries. Rakuten Travel anchors the super-app convergence archetype, bundling outbound air inventory with domestic e-commerce loyalty point redemption. These three represent distinct strategic postures rather than direct substitution competitors.
| Leading Market Players |
|---|
| JTB Corporation |
| HIS Co., Ltd. |
| Rakuten Travel |
| Expedia Japan |
| ANA X Inc. |
| KNT-CT Holdings |
| JALPAK |
| Club Tourism International |
| VELTRA |
| Others |
Value Chain & Pricing Dynamics
Fuel surcharge volatility represents an unhedged cost vector that compresses package tour margins on long-haul European itineraries while simultaneously forcing operators toward Southeast Asian charter concentration where per-seat economics prove more defensible. This risk asymmetry produces divergent pricing tier spreads between premium multi-city cultural products and volume beach packages, with supply chain shape following margin preservation logic.
Pricing Analysis
Contract structures in Japanese outbound tourism bifurcate between static allotment agreements for European hotel inventory and dynamic spot purchasing for Southeast Asian beach properties. Price differentiation rests on JIS certification tier and charter flight integration depth, with vertically integrated operators commanding premium positioning over third-party aggregators. Cost compression in the standard tier intensifies as HIS and JTB expand in-house aircraft leasing, eroding intermediary markups. Corporate travel management clients exhibit lowest price sensitivity due to negotiated corporate rate contracts, while solo leisure travelers demonstrate highest elasticity to dynamic packaging discounts.
Supply Chain Analysis
Upstream feedstock for Japanese tour products draws from Thailand, Vietnam, and France as dominant destination nodes, with ground service capacity concentrated in Bangkok, Ho Chi Minh City, and Paris metropolitan corridors. Aircraft leasing, hotel block contracting, and destination management subsidiary operations constitute the three critical input categories. Single-source vulnerability sits with Bangkok and Ho Chi Minh City labor pools for Japanese-speaking guide services. Distribution runs through METI-licensed platform aggregators that intermediate between charter operators and end travelers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's outbound tourism sector sits at a platform consolidation inflection where METI interoperability mandates are accelerating super-app convergence and compressing standalone agency viability.
For Market Incumbents: Entrench charter flight capacity on Thailand and Vietnam routes to defend margin position against dynamic packaging entrants. Deepen destination management subsidiary control in Da Nang and Phuket to secure ground service availability during peak booking windows. Prioritize API retrofit investment to satisfy METI open architecture compliance timelines. For New Entrants and Emerging Players: Regional departure points beyond Tokyo and Osaka represent the most penetrable entry corridor for direct charter routing to Southeast Asian beach markets. Health security documentation platforms aligned with PMDA vaccination verification standards offer technology-integrated service revenue streams. Pursue super-app loyalty point bundling partnerships with domestic e-commerce platforms as the primary go-to-market mechanism. For Investors and Strategic Acquirers: The market sits at a platform standardization phase that favors vertically integrated operators with captive aircraft and ground assets over pure digital intermediaries. Long-term viability concentrates in entities controlling charter infrastructure and Asia-Pacific destination management subsidiaries. Monitor METI enforcement intensity on escrow and disclosure mandates as the signal for digital entrant compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Charter Flight Capacity Expansion | In-house aircraft leasing by HIS and JTB compresses per-seat costs on high-frequency Bangkok and Ho Chi Minh City routes. |
| Dynamic Packaging Engine Licensing | Mid-sized online agencies adopting algorithmic itinerary assembly erode storefront agent price-discovery advantages. |
| Super-App Loyalty Convergence | Rakuten Travel's bundling of outbound flights with domestic e-commerce points captures share from standalone travel portals. |
| Destination Management Subsidiary Acquisition | Control over Bangkok and Ho Chi Minh City ground logistics secures operational capacity during peak Southeast Asian booking windows. |
| PMDA-Aligned Health Documentation Platform | Vaccination verification systems create service revenue streams for technology-integrated agencies serving risk-averse demographics. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with tour operator executives, charter fleet managers, destination management subsidiary directors, and METI regulatory affairs specialists; and secondary validation through Japan Tourism Agency departure statistics, METI Travel Agency Act enforcement records, JIS certification databases, and airline schedule filings. Bottom-up segment sizing across leisure, business, education, and religious purpose categories was triangulated against top-down market value reconstruction from operator revenue disclosures.
Forecast inputs considered travel purpose segmentation, booking channel migration patterns, demographic cohort expansion rates, and destination-specific capacity constraints across the projection horizon. CAGRs were derived from trend extrapolation of departure volume growth adjusted for yen purchasing power dynamics and charter fleet expansion schedules. The analytical framework incorporated METI platform interoperability compliance timelines and PMDA health security protocol evolution as structural demand modifiers.
Macroeconomic conditions sit as an overlay; deviation in yen exchange rate trajectories, jet fuel price volatility, or Southeast Asian destination political stability would shift the trajectory. Forecasts reflect documented assumptions regarding charter capacity deployment and super-app adoption curves. Cross-checking against Japan Tourism Agency official departure statistics and operator financial disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Sports Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Luxury Tourism Market
Travel and Tourism
Hong Kong Outbound Tourism Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
Asia-Pacific Tourism Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Asia-Pacific Travel Retail Market
Travel and Tourism
South Korea Tourism Market
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
Mexico Sustainable Tourism Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Global Ecotourism Market
Travel and Tourism
Malaysia Tourism Market
Travel and Tourism
Leisure Travel Market