
 Water Park Market | 2026-2036
Water Park Market Size, Share, and Industry Trends Forecast 2026-2036
Water Park Market Insights
ASTM F2377 qualification for water slide design and operation is rotating the competitive landscape toward engineering-capable incumbents. WhiteWater West leverages its integrated manufacturing and design capabilities across multiple continents. ProSlide Technology specializes in custom fiberglass slide systems with patented water flow management. Cedar Fair sustains a diversified portfolio balancing seasonal outdoor parks with year-round indoor water park expansions.
Water parks constitute engineered aquatic entertainment facilities utilizing fiberglass composite slides, pumped wave generation systems, and closed-loop water treatment infrastructure to deliver controlled recreational experiences. Primary commercial purpose centers on capturing extended visitor dwell time through multi-attraction environments that generate revenue across admission, hospitality, and retail touchpoints. Outdoor water parks anchor current revenue volumes across temperate climates, while indoor water parks are expanding fastest in regions seeking weather-independent operations. Resort water parks concentrate margin pools through bundled lodging and premium pricing structures.
FDA guidelines on recreational water quality, EPA effluent standards for water discharge, and ASTM International ride safety protocols collectively shape operator compliance costs and capital expenditure requirements. The EU Green Deal and REACH chemical regulations in Europe impose additional material and water treatment specifications on imported attractions and domestic installations. Stakeholders must monitor evolving municipal water rights allocations and energy efficiency mandates as these determine site feasibility and operating cost trajectories across new developments.
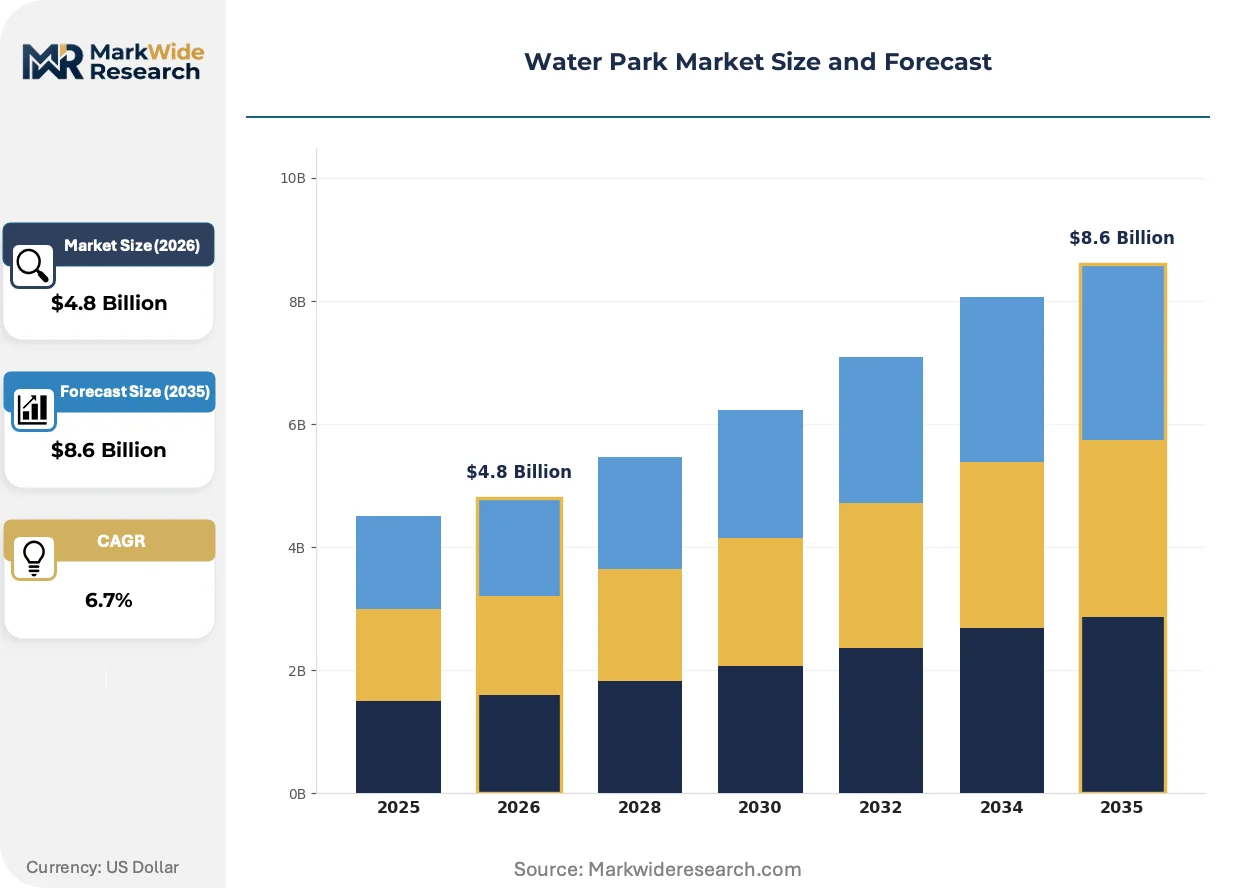
Market Dynamics
The EU Green Deal is forcing water park operators to restructure capital allocation toward closed-loop water recycling and photovoltaic-integrated infrastructure, compressing payback timelines and elevating engineering requirements for new entrants.
Growth Catalysts
- EU Green Deal implementation:Mandatory energy efficiency standards and water reuse targets are redirecting investment toward sustainable infrastructure, expanding the addressable market for treatment system integrators.
- Integrated resort bundling:Hospitality developers in China are embedding water parks within mixed-use leisure complexes, extending visitor dwell time and cross-selling hospitality revenue streams.
- Fiberglass composite advances:Improved resin formulations and modular slide manufacturing are reducing installation timelines and enabling seasonal expansion flexibility for operators.
Market Restraints
- Specialized fiberglass supply concentration:High-grade composite substrate production clusters in select Asian manufacturing hubs, exposing operators to input cost volatility and extended lead times.
- ASTM F2377 compliance burden:Third-party certification requirements for slide engineering and operational safety impose fixed upfront costs that disproportionately constrain smaller regional developers.
- Municipal water rights scarcity:Drought-prone jurisdictions in the western United States are tightening allocation permits, rendering greenfield site feasibility contingent on recycled water system investment.
Strategic Opportunities
- Indoor weather-independent expansion:Temperate-climate countries with short outdoor seasons present white space for year-round enclosed water park concepts anchored to retail or hospitality anchors.
- Dual carbon goals alignment:China's national decarbonization mandates are unlocking preferential financing and expedited permitting for low-energy attraction designs and solar-integrated facilities.
- Digital ticketing convergence:Mobile-first reservation platforms combined with dynamic capacity management are enabling yield optimization previously unavailable to seasonal outdoor operators.
Industry Challenges
- Certified aquatic engineer scarcity:Operators face recruitment friction for personnel qualified in both hydraulic system design and ASTM-compliant ride inspection protocols.
- Legacy water treatment retrofit complexity:Existing outdoor facilities must integrate closed-loop recycling without interrupting seasonal operations, compressing installation windows and elevating coordination risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Park Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Water Parks, Outdoor Water Parks, Amusement Parks with Water Attractions, Resort Water Parks Attraction Type: Water Slides, Wave Pools, Lazy Rivers, Splash Pads Visitor Demographics: Families, Young Adults, Children, Seniors Revenue Model: Entry Fees, Season Passes, Food & Beverage Sales, Merchandise Sales |
| Companies Covered | Chimelong Group, WhiteWater West, Six Flags Entertainment Corporation, Cedar Fair, Comcast Corporation, Europa-Park, ProSlide Technology, WM International, SeaWorld Parks & Entertainment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Park Market Trends and Innovations
Digital yield management platforms are supplanting static pricing calendars across the operator base, compressing revenue leakage and enabling real-time capacity optimization previously unavailable to seasonal facilities.
Variable-frequency drive pump systems are supplanting fixed-speed hydraulic infrastructure across new and retrofitted installations. Mid-scale operators in North America and Europe are adopting these systems at accelerating pace to reduce energy draw during off-peak hours. This technology is supplanting legacy mechanical flow control, compressing operating expenditure trajectories and extending equipment replacement cycles.
REACH chemical regulations in Europe are restricting certain biocide formulations previously standard in water treatment protocols. Industrial consequence includes accelerated reformulation of closed-loop sanitization chemistry and elevated compliance documentation burdens for imported attraction components. Indoor water park operators in Germany and France are most affected, responding through partnerships with certified chemical suppliers and enhanced effluent monitoring systems.
Family visitor segments are consolidating preference around multi-generational attraction portfolios that balance high-thrill slides with toddler-friendly zones and adult relaxation amenities. This behavioral pivot is displacing pure-adrenaline park concepts and elevating design requirements for spatial zoning and concurrent experience variety. The shift is most visible in China and the United Arab Emirates, where developers are expanding lazy river networks and cabana hospitality integration alongside traditional slide towers.
Water Park Market Segmentation
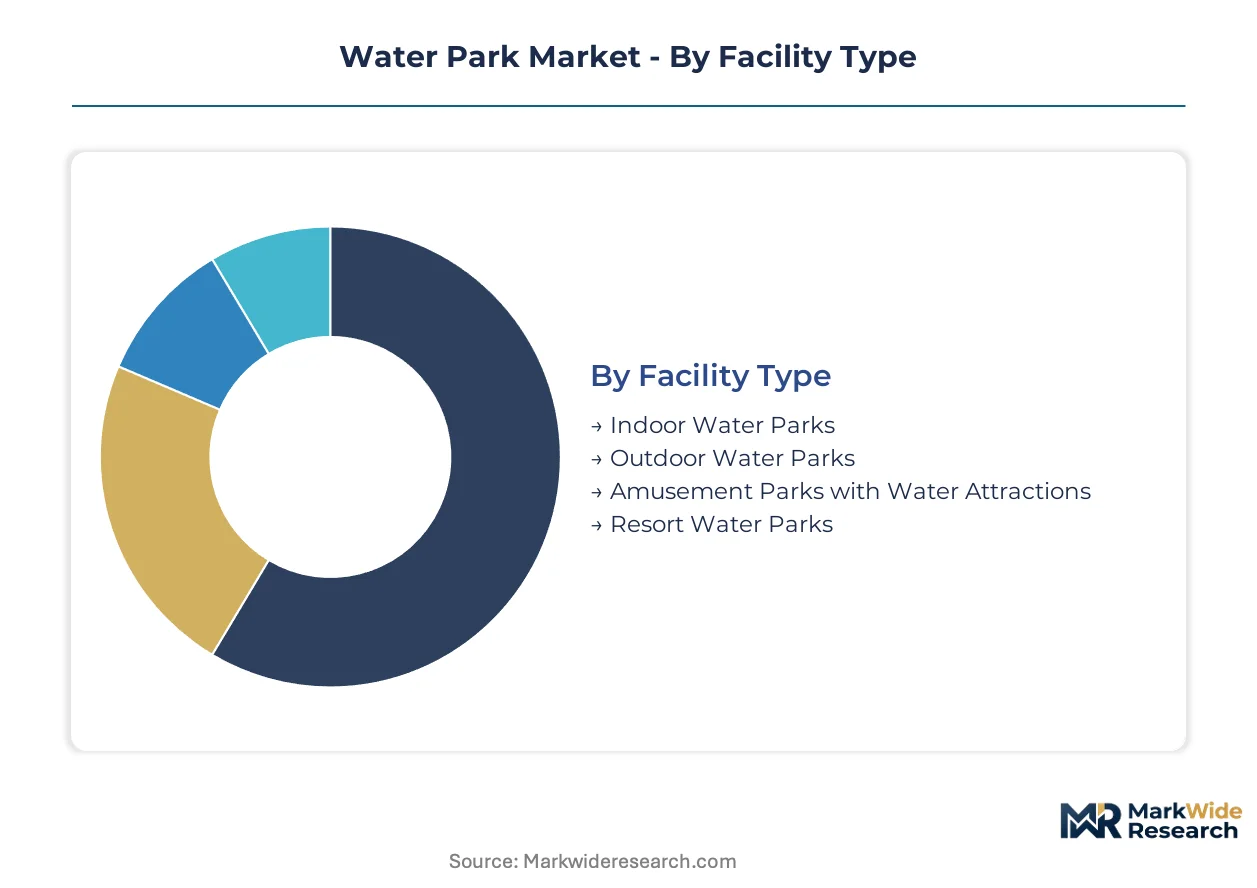
Water park segmentation reveals how facility economics and visitor behavior fragment across operational models. Understanding these divisions exposes where capital efficiency concentrates and which configurations face erosion from substitute leisure formats.
Facility Type:
Outdoor water parks face the most acute substitution pressure from home entertainment systems, staycation alternatives, and climate volatility that compresses reliable operating calendars.
- Indoor Water Parks:Enclosed climate-controlled environments utilizing HVAC-integrated humidity management and year-round operational capability. Demand concentrates in Germany, Poland, and the northeastern United States where short outdoor seasons limit competitive alternatives. Municipal zoning for large-footprint enclosed structures constrains greenfield development velocity.
- Outdoor Water Parks:Open-air facilities dependent on seasonal temperature windows and natural solar heating of water volumes. Florida, Texas, and Spain anchor attendance concentration due to extended warm-weather calendars. Drought-driven water rights restrictions in California and Arizona are forcing recycled system retrofits that elevate capital intensity.
- Amusement Parks with Water Attractions:Hybrid configurations embedding water rides within broader thrill-ride portfolios to extend dwell time without dedicated water park infrastructure.
- Resort Water Parks:Lodging-integrated facilities bundling accommodation, dining, and aquatic entertainment into single-package revenue streams.
Outdoor water parks retain volume leadership; indoor water parks hold the steepest expansion curve.
Attraction Type:
Water slides command the highest capital allocation per square meter, creating cost tier stratification that separates engineering-capable operators from asset-light competitors.
- Water Slides:Fiberglass-composite chute systems utilizing pumped water lubrication and engineered trajectory geometry. Custom tower configurations dominate in the United Arab Emirates and China where developers compete on record-breaking height and length specifications. ASTM F2377 certification requirements compress the supplier base to vertically integrated manufacturers.
- Wave Pools:Pneumatic or hydraulic wave generation systems creating artificial surf conditions in controlled basins. Australian and Brazilian operators are expanding these installations to capture surf-simulation demand in coastal-proximate markets.
- Lazy Rivers:Low-current closed-loop channels enabling passive flotation experiences across extended circuit distances.
- Splash Pads:Zero-depth interactive water features requiring minimal lifeguard staffing and reduced liability exposure.
Water slides capture premium pricing; splash pads are expanding most quickly in municipal and retail-anchored installations.
Visitor Demographics:
Family segments concentrate revenue across the widest operating calendar, while young adult demand fragments toward competitive substitute experiences.
- Families:Multi-generational visitor units requiring concurrent attraction variety spanning toddler zones, moderate-thrill slides, and adult relaxation amenities. Chinese developers at Chimelong and domestic resort chains are expanding dedicated family cabana networks and supervised children's areas to extend dwell time. This segment generates the highest per-capita hospitality revenue through bundled meal plans and retail purchases.
- Young Adults:Thrill-seeking visitors prioritizing high-speed slides, wave pool surfing, and social media-shareable experiences.
- Children:Age-restricted shallow-water zones with height-limited attractions and enhanced supervision protocols.
- Seniors:Thermal spa integration and low-impact aquatic wellness programming with reduced physical exertion requirements.
Families retain volume leadership; seniors hold the steepest expansion curve as longevity tourism and wellness integration accelerate.
Revenue Model:
Entry fee dependence creates margin vulnerability to weather and discretionary spending cycles, pushing diversification toward recurring revenue streams.
- Entry Fees:Single-day admission pricing structured across peak, off-peak, and dynamic yield-managed tiers. US operators in Texas and Florida are deploying mobile-first reservation platforms to compress revenue leakage from no-show capacity.
- Season Passes:Annual membership programs converting episodic visitors into recurring revenue with upfront cash collection.
- Food & Beverage Sales:Captive hospitality revenue streams within park perimeters with limited external competition.
- Merchandise Sales:Branded retail including apparel, photography, and souvenir items with high margin contribution.
Entry fees retain volume leadership; season passes hold the steepest expansion curve as operators prioritize recurring revenue stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's high-speed rail network funnels domestic tourists toward Shanghai and Hangzhou, anchoring China's position as the world's largest water park development frontier.
United States
Extended operating calendars in Florida and Texas sustain outdoor park volumes, while drought conditions in California tighten municipal water allocations. EPA effluent standards and state-level water rights permits now mandate recycled system retrofits for new developments. Orlando's hospitality corridor concentrates resort-integrated water park construction alongside theme park expansions.
Germany
Short outdoor seasons and robust winter demand accelerate indoor water park construction across Bavaria and North Rhine-Westphalia. REACH chemical regulations and EU Green Deal energy mandates reshape sanitization chemistry and HVAC specifications. Tropical Islands Resort near Berlin exemplifies the conversion of industrial infrastructure into climate-controlled aquatic entertainment complexes.
China
Dual carbon goals and domestic tourism stimulus programs unlock preferential financing for low-energy attraction designs in the Pearl River Delta. MIIT efficiency standards and MEE water quality protocols govern new installation approvals. Chimelong Group's integrated resort developments in Guangzhou and Zhuhai demonstrate scaled bundling of lodging, retail, and aquatic entertainment.
United Arab Emirates
Year-round warm temperatures and international visitor flows sustain premium outdoor water park operations in Dubai and Abu Dhabi. MOHAP recreational facility licensing and municipal sustainability codes govern water consumption limits and treatment system specifications. Yas Island's cluster of hospitality-anchored aquatic attractions competes on record-breaking slide specifications and luxury cabana integration.
Brazil
Seasonal temperature windows and emerging middle-class leisure spending expand addressable demand in São Paulo and Rio de Janeiro state corridors. ANVISA sanitary surveillance protocols and state environmental agency water discharge permits elevate compliance documentation for imported attraction components. Thermas dos Laranjais near Olímpia anchors the country's largest concentration of resort-integrated thermal and aquatic entertainment facilities.
Water Park Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and engineering capability dimensions, producing a tiered structure where scale advantages concentrate with integrated resort operators and specialized equipment fabricators. The vendor base separates into three strategic archetypes: hospitality conglomerates bundling water parks within mixed-use developments, vertically integrated slide manufacturers controlling composite production and installation, and regional park operators leveraging seasonal outdoor assets. Dominant competitive moves include portfolio diversification into year-round indoor concepts and backward integration into captive fiberglass manufacturing.
Among North American hospitality-anchored operators, Six Flags Entertainment Corporation and Cedar Fair exemplify the scale-driven archetype through diversified amusement and water park portfolios. ProSlide Technology occupies a position within the specialized manufacturing tier, representing engineering-capable incumbents with custom fiberglass system capabilities. WhiteWater West anchors the integrated design-build segment, spanning manufacturing and operational consulting across multiple continents.
| Leading Market Players |
|---|
| Chimelong Group |
| WhiteWater West |
| Six Flags Entertainment Corporation |
| Cedar Fair |
| Comcast Corporation |
| Europa-Park |
| ProSlide Technology |
| WM International |
| SeaWorld Parks & Entertainment |
| Others |
Pricing and Supply Chain Analysis
Nine-to-fourteen-month lead times for custom fiberglass slide systems concentrate pricing power with vertically integrated manufacturers while compressing margin flexibility for regional park developers dependent on spot-market composite sourcing. This inventory pressure elevates procurement costs for ASTM F2377-certified attractions and forces smaller operators toward standardized catalog configurations rather than bespoke tower designs.
Pricing Analysis
Volume-discount tiering structures separate master-planned resort developers purchasing multi-attraction packages from municipal operators acquiring single-slide installations. Pricing stratifies across premium custom-engineered systems, standard modular configurations, and economy catalog offerings, with differentiation driven by ASTM certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because Chinese domestic manufacturers are expanding resin-formulation capabilities. Municipal and retail-anchored buyers exhibit highest price sensitivity, while integrated resort developers prioritize engineering capability over unit cost.
Supply Chain Analysis
Inventory-to-delivery cycles stretching beyond three quarters for specialized composite substrates expose operators to input cost volatility and force advance capital commitment. High-grade fiberglass production clusters in China, South Korea, and select North American facilities, with engineered pump systems and pneumatic wave generators drawing from German and Italian component specialists. Single-source vulnerability concentrates in epoxy resin formulations subject to REACH chemical restrictions. Distribution runs through manufacturer-direct project sales for large installations and regional distributor networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water park economics are approaching a platform inflection where digital yield management systems and mobile-first reservation platforms create network effects previously unavailable to seasonal operators. Interoperability between attraction access control, hospitality bundling, and retail point-of-sale systems is consolidating competitive advantage around data-integrated operators.
For Market Incumbents: Shield market position through captive supply of fiberglass composite manufacturing and accelerated indoor facility expansion in temperate-climate corridors. ASTM F2377 certification investment creates regulatory moats against emerging Asian competitors. Channel control over hospitality-anchored distribution in Orlando and Shanghai reinforces pricing power. For New Entrants and Emerging Players: ASTM F2377 fast-track partnerships with established testing laboratories enable rapid market entry without multi-year engineering capability buildout. White space concentrates in indoor weather-independent concepts across Poland, the northeastern United States, and Bavaria where municipal zoning constraints limit incumbent expansion velocity. Go-to-market positioning should emphasize seasonal flexibility and modular installation timelines. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because season pass conversion and hospitality bundling generate predictable cash flows insulated from single-weather-season volatility. Acquisition targets should display vertical integration into composite manufacturing or captive digital platform development. The signal to watch is municipal water rights allocation tightening in drought-prone jurisdictions, which will accelerate recycled-system retrofit demand and consolidate viable site inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Water Recycling Retrofit | EPA effluent standards and EU Green Deal mandates elevate capital efficiency for compliant operators. |
| Digital Yield Management Platform Deployment | Mobile-first reservation systems enable real-time capacity optimization previously unavailable to seasonal facilities. |
| Indoor Climate-Controlled Expansion | HVAC-integrated humidity management extends operating calendars in Germany and the northeastern United States. |
| ASTM F2377 Certification Investment | Third-party engineering validation compresses the supplier base and creates regulatory barriers for new entrants. |
| Hospitality-Anchored Resort Bundling | Chimelong Group's integrated developments demonstrate scaled lodging-retail-aquatic revenue cross-selling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with water park general managers, fiberglass manufacturing procurement leads, municipal zoning officials, and hospitality development executives. Secondary validation drew from EPA effluent filing databases, EU ETS registry disclosures, ASTM International certification records, and trade customs data for composite substrate imports. Bottom-up installation counts triangulated against top-down hospitality revenue estimates across the analysis window.
Across the modeling period, projections incorporated facility type segmentation by operational model, attraction type by capital intensity tier, and visitor demographic by revenue contribution profile. CAGRs were derived from regression analysis of historical attendance patterns against macroeconomic indicators and regulatory implementation timelines. Forecast inputs included municipal water rights allocation trajectories and fiberglass composite price indices.
Decision-makers should treat outputs as directional under sustained EU Green Deal implementation and stable domestic tourism stimulus programs in China; material deviation in either would warrant model refresh. Specific risks include drought-driven operating calendar compression, REACH chemical reformulation delays, and certified aquatic engineer scarcity disrupting expansion timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Bleisure Tourism Market
Travel and Tourism
Pet Travel Services Market
Travel and Tourism
UAE Sustainable Tourism Market
Travel and Tourism
LAMEA Pet Travel Services Market
Travel and Tourism
India Travel Retail Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
Group Travel Market
Travel and Tourism
Travel and Tourism User Generated Content Market
Travel and Tourism
Ecotel Tourism Market
Travel and Tourism
Asia Pacific Wellness Tourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Asia-Pacific MICE Tourism Market
Travel and Tourism
Travel Intermediaries Business Market
Travel and Tourism
USA Sports Tourism Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
India Outbound Tourism Market