
 Global Golf Travel Market | 2026-2036
Global Golf Travel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Golf Travel Market Foresight
Luxury seekers is redrawing competitive positioning in golf travel as high-net-worth travelers prioritize exclusive tee-time access and bespoke caddie services over standardized packages. Pinehurst Resort leverages its historic championship pedigree to sustain premium rate integrity across multi-course estates. Golfbreaks competes through technology leadership in dynamic packaging, while Cabot Collection anchors demand in coastal destination development with integrated lodging-course design.
Golf travel encompasses structured itineraries centered on tee-time reservations, lodging coordination, and ground transportation logistics, typically bundled through specialized intermediaries or direct resort channels. The segment generates value by reducing search friction across geographically dispersed course inventories and securing preferred access windows at capacity-constrained venues. Independent travel captures margin concentration through customization premiums, while resort courses dominate destination type value pools due to integrated amenity capture. Corporate retreats represent the fastest-expanding travel type as firms substitute golf programming for conventional incentive structures.
The EU Green Deal's CSRD reporting obligations and the UK's Carbon Reduction Commitment shape operator disclosure requirements for golf destination emissions, particularly affecting Scottish and Irish links properties with coastal erosion exposure. FAA regulations govern domestic US air charter coordination for remote resort access, while Japan's METI tourism certification standards influence inbound golf travel quality benchmarks. Stakeholders must monitor how sustainability disclosure mandates alter destination marketing claims and traveler booking criteria.
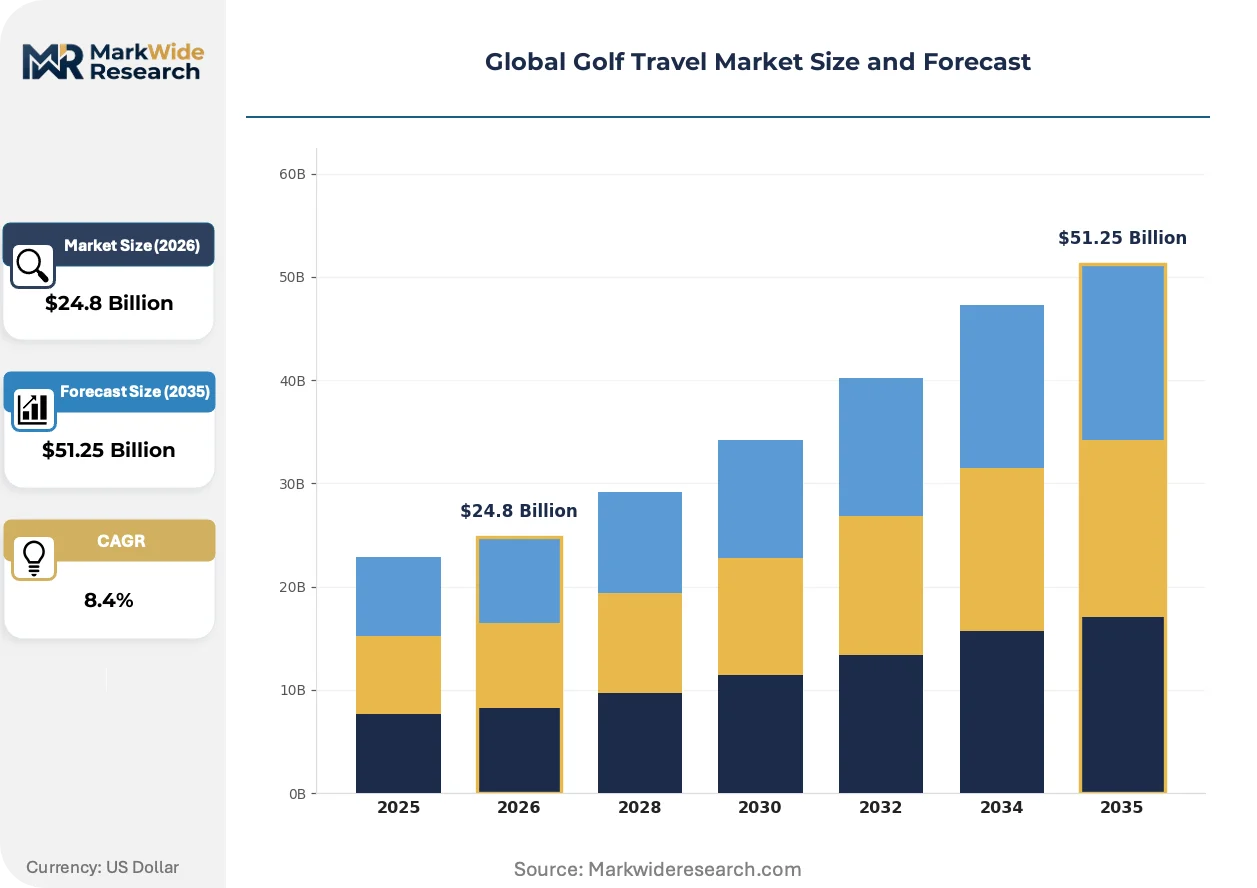
Market Dynamics
Experiential travel preferences are restructuring golf travel economics as luxury seekers abandon standardized packages for bespoke itinerary control, forcing intermediaries to rebuild value propositions around exclusive access rather than inventory aggregation.
Growth Catalysts
- EU Green Deal certification mandates:Carbon disclosure requirements for tourism operators are accelerating sustainable destination development across Scottish and Irish links corridors, creating premium pricing power for compliant properties.
- Corporate incentive restructuring:Firms are substituting conventional sales retreats with golf programming, expanding group booking volumes and extending shoulder-season demand into traditionally quiet months.
- Coastal destination clustering:Integrated lodging-course developments in Scotland's St Andrews-Turnberry corridor and Ireland's southwest links belt are concentrating high-yield traveler flows and infrastructure investment.
Market Restraints
- Aviation fuel cost volatility:Long-haul golf travel to remote resort destinations faces margin compression as jet fuel price swings directly transfer to packaged tour pricing.
- Coastal erosion exposure:Scottish and Irish links courses face accelerating physical asset risk from storm frequency, threatening century-old routing integrity and insurance coverage terms.
- Regulatory disclosure friction:The EU's CSRD reporting obligations impose compliance overhead on small- and mid-sized tour operators without dedicated sustainability teams.
Strategic Opportunities
- Japan inbound golf expansion:METI tourism certification standards are opening quality-assured market entry for premium operators targeting aging domestic golfers and inbound Asian travelers.
- Dynamic packaging technology:Real-time inventory aggregation across dispersed course networks enables personalized itinerary construction that bypasses traditional wholesale intermediaries.
- Carbon offset integration:Voluntary emissions compensation bundled into premium bookings is creating new revenue streams and traveler loyalty mechanisms for early-adopting destinations.
Industry Challenges
- Caddie workforce scarcity:Historic links properties face recruitment bottlenecks for experienced bag carriers, compressing tee-time throughput and degrading the bespoke service experience luxury travelers expect.
- Legacy reservation system integration:Small-course operators struggle to connect antiquated tee-time management software with modern distribution platforms, fragmenting inventory visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Golf Travel Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $51.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Travel Type: Golf Package, Independent Travel, Group Tours, Corporate Retreats Destination Type: Resort Courses, Private Clubs, Public Courses, Driving Ranges Customer Segment: Weekend Golfers, Professional Players, Leisure Travelers, Luxury Seekers Booking Channel: Online Travel Agencies, Direct Bookings, Travel Agents, Golf Associations |
| Companies Covered | Women's Golf & Travel, Pinehurst Resort, Golfbreaks, Luxe Golf Concierge, Global Golf Vacations, Your Golf Travel, Cabot Collection, Shandon Travel, Golf Escapes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Golf Travel Market Shifts & Advancements
Digital infrastructure is fragmenting traditional golf travel intermediation as travelers demand direct booking control, while sustainability disclosure mandates reshape destination marketing claims and operational transparency requirements.
Artificial intelligence-powered itinerary engines are decomposing the traditional package tour model by enabling real-time course-lodging-transport bundling across fragmented supplier networks. High-net-worth travelers are adopting these tools fastest, compressing search friction to minutes rather than days. The technology is decomposing wholesale intermediary margins by transferring pricing power to algorithmic comparison and direct supplier relationships.
The EU Green Deal's CSRD framework is mandating granular emissions disclosure from tourism operators serving golf destinations, with particular stringency for coastal properties in erosion-sensitive zones. Compliance costs are diverting marketing spend toward certification acquisition and third-party audit fees. Scottish links operators are responding fastest, embedding carbon accounting into guest-facing booking interfaces to preempt regulatory scrutiny.
Corporate procurement departments are unbundling golf retreat components—separating course fees, lodging, and ground transport into individually negotiated line items rather than accepting bundled packages. This behavior is disrupting traditional tour operator margins and transferring negotiation leverage to volume buyers. The shift is most visible in US-based financial services and technology sectors, where procurement teams apply travel-category management discipline to incentive programming.
Global Golf Travel Market Segmentation
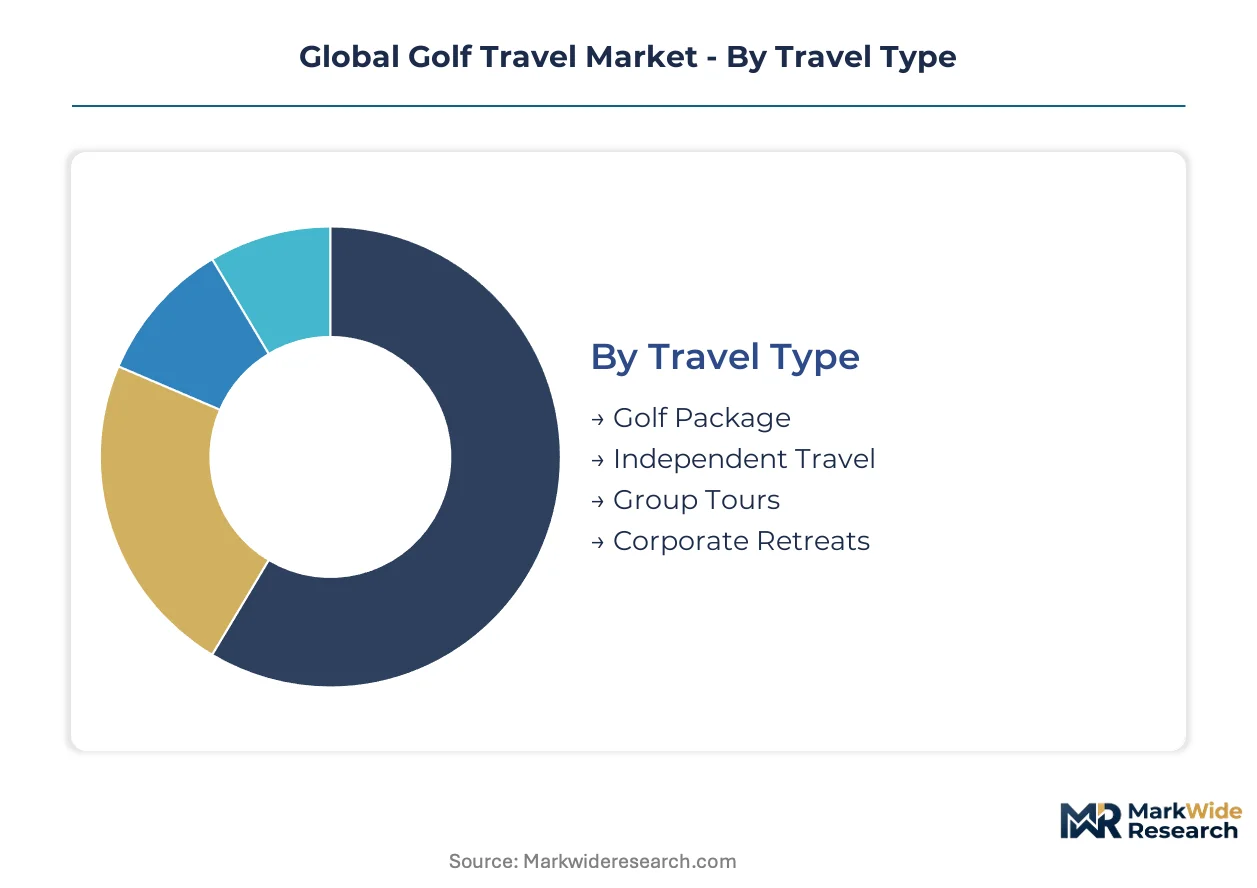
Golf travel segmentation reveals divergent margin structures across booking channels and customer archetypes. Package bundling versus independent customization creates distinct value capture mechanisms, while destination type determines amenity integration depth and pricing power.
Travel Type:
Channel mix varies sharply by travel type, with intermediaries dominating package sales while direct resort relationships capture independent traveler premiums.
- Independent Travel:Self-directed itinerary construction enables tee-time flexibility and lodging autonomy. Demand concentrates in Scotland's St Andrews corridor where golfers secure direct access to historic links without wholesale markups. This segment commands customization premiums but requires higher search effort from travelers.
- Corporate Retreats:Structured group programming substitutes for conventional sales incentives with integrated course access and team-building components. Volume buyers in US financial services and technology sectors negotiate unbundled line-item pricing, compressing traditional tour operator margins. This segment is expanding most quickly as firms redesign incentive structures.
- Golf Package:Pre-bundled course-lodging-transport combinations reduce coordination friction for time-constrained travelers.
- Group Tours:Organized multi-party itineraries with fixed schedules and shared transportation logistics.
Independent travel dominates installed base. Corporate retreats is where expansion concentrates.
Destination Type:
Margin tiering separates fully integrated resort estates from standalone course access, with coastal erosion exposure creating geographic risk concentration.
- Resort Courses:Lodging-course-amenity integration captures guest spending across multiple touchpoints. Properties in Ireland's southwest links belt and Scotland's Turnberry corridor concentrate investment due to yield premiums. CSRD disclosure requirements impose compliance overhead on these coastal assets.
- Private Clubs:Member-guest access protocols create scarcity value and exclusive tee-time windows. Demand clusters at historic UK and Irish properties where reciprocal arrangements enable visitor play. Caddie workforce scarcity limits throughput capacity at these venues.
- Public Courses:Municipal and daily-fee facilities with lower barrier to entry and standardized service levels.
- Driving Ranges:Practice-focused facilities typically serving local demand rather than destination travel.
Resort courses command highest revenue per traveler. Private clubs is where yield expansion concentrates.
Customer Segment:
Application context distinguishes recreational participation from performance-focused travel, with luxury seekers driving experiential premiumization.
- Luxury Seekers:High-net-worth travelers prioritizing exclusive access, bespoke caddie services, and itinerary control over standardized offerings. This segment adopts AI-powered booking tools fastest, compressing search friction and transferring pricing power to algorithmic comparison. METI certification standards in Japan target this demographic for inbound expansion.
- Professional Players:Tournament preparation and competitive practice drives destination selection toward championship-caliber conditioning. Concentrated demand at Pinehurst and St Andrews properties with historic championship pedigrees. Tournament schedules create seasonal volume spikes.
- Weekend Golfers:Recreational players with limited time budgets seeking accessible regional destinations.
- Leisure Travelers:General vacationers incorporating golf as one component of broader travel experiences.
Weekend golfers dominate transaction volume. Luxury seekers is where margin expansion concentrates.
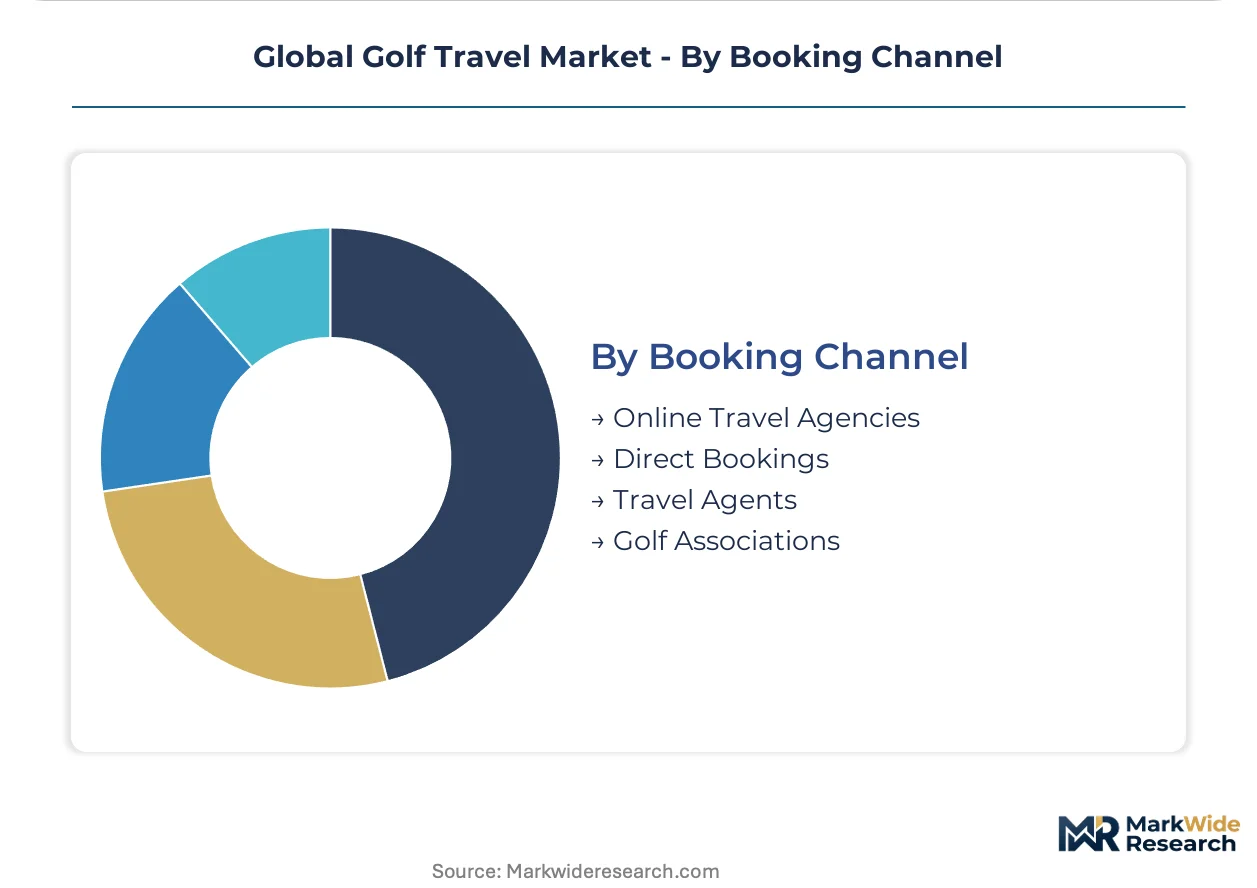
Booking Channel:
Technology adoption rates fragment channel performance, with legacy systems creating integration friction for small-course operators.
- Direct Bookings:Resort-to-traveler relationships eliminate intermediary commissions and enable personalized service customization. Golfbreaks and similar platforms compete by offering dynamic packaging technology that aggregates fragmented inventory. Properties with modern tee-time management systems capture disproportionate share.
- Online Travel Agencies:Digital platforms with real-time inventory visibility and algorithmic bundling capabilities. These intermediaries decompose wholesale margins by transferring pricing power to comparison engines. FAA regulations govern air charter coordination for remote resort access booked through these channels.
- Travel Agents:Human intermediaries providing advisory services for complex multi-destination itineraries.
- Golf Associations:Member-serving organizations with negotiated access arrangements at partner properties.
Direct bookings dominate premium segment capture. Online travel agencies is where technology-driven expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heathrow Airport's transatlantic connectivity underwrites the United Kingdom's centrality to premium golf travel flows, while Japan's Narita hub anchors inbound Asian golfer access. Scotland's St Andrews-Turnberry corridor and Ireland's southwest links belt concentrate infrastructure investment and yield premiums.
United States
Pinehurst Resort's championship pedigree drives demand concentration in North Carolina's Sandhills region. FAA regulations govern domestic air charter coordination for remote resort access, particularly affecting desert and coastal destinations. Corporate procurement teams in financial services and technology sectors negotiate unbundled retreat components, compressing traditional tour operator margins.
United Kingdom
St Andrews and Turnberry anchor historic links demand, with caddie workforce scarcity limiting tee-time throughput at premium properties. The UK's Carbon Reduction Commitment shapes operator disclosure requirements for destination emissions. Scotland's links corridor faces accelerating coastal erosion exposure, threatening century-old routing integrity and insurance coverage terms.
Ireland
The southwest links belt concentrates integrated lodging-course development investment from Ballybunion to Lahinch. EU Green Deal CSRD reporting obligations impose compliance overhead on coastal properties with erosion-sensitive zones. Dublin Airport's hub connectivity supports transatlantic golfer flows, particularly from US corporate retreat segments.
Japan
METI tourism certification standards are opening quality-assured market entry for premium operators targeting aging domestic golfers and inbound Asian travelers. Kansai and Chubu regions concentrate championship-caliber resort development. Osaka's international connectivity supports regional access for golf-centric experiential travel.
Global Golf Travel Market Competitive Landscape
Concentration sits with integrated resort estates and technology-enabled intermediaries rather than fragmented local operators. Historic championship properties capture premium rate integrity through scarcity value, while dynamic packaging platforms decompose wholesale margins by transferring pricing power to algorithmic comparison. Two strategic archetypes dominate: destination developers with captive lodging-course integration, and digital intermediaries with real-time inventory aggregation. Competitive moves center on exclusive access partnerships and sustainability certification acquisition.
Among resort-focused developers, Pinehurst Resort and Cabot Collection exemplify the integrated estate archetype through multi-course portfolios with lodging capture. Golfbreaks occupies a position within the technology-enabled intermediary tier, leveraging dynamic packaging capabilities to aggregate fragmented course inventories. These three entities represent distinct competitive vectors—historic pedigree, coastal destination development, and digital distribution technology—rather than direct substitutes.
| Leading Market Players |
|---|
| Women's Golf & Travel |
| Pinehurst Resort |
| Golfbreaks |
| Luxe Golf Concierge |
| Global Golf Vacations |
| Your Golf Travel |
| Cabot Collection |
| Shandon Travel |
| Golf Escapes |
| Others |
Supply & Pricing Matrix
EU Green Deal CSRD certification requirements gate both supplier qualification and price differentiation simultaneously, forcing Scottish and Irish links properties to embed carbon accounting costs into rate structures while compliant venues capture premium positioning over non-certified competitors.
Pricing Analysis
Volume-discount tiering structures dominate corporate retreat negotiations, with US financial services procurement teams extracting unbundled line-item pricing that compresses traditional tour operator margins. Price differentiation rests on caddie service tiers and exclusive tee-time windows at historic properties, with customization premiums widening as luxury seekers abandon standardized packages. Cost compression in mid-market package tiers is intensifying because aviation fuel volatility transfers directly to bundled tour pricing. Weekend golfers exhibit highest price sensitivity, while luxury seekers prioritize access scarcity over rate comparison.
Supply Chain Analysis
Inventory fragmentation across antiquated tee-time management systems creates lead-time unpredictability for small-course operators connecting to modern distribution platforms. Geographic supply concentrates in Scotland, Ireland, and the United States, with St Andrews-Turnberry and Pinehurst anchoring premium corridor development. Raw material dependencies include aviation fuel for long-haul charter coordination, coastal erosion mitigation infrastructure, and caddie workforce recruitment. Single-source vulnerability sits with legacy reservation software vendors serving historic links properties. Distribution runs through specialized golf intermediaries, direct resort channels, and emerging AI-powered booking platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Golf travel functions as a service-attach opportunity where carbon offset bundling and bespoke caddie programming expand faster than core tee-time transactions, creating recurring revenue layers that outperform standardized package economics.
For Market Incumbents: Consolidate exclusive access partnerships with historic links properties before dynamic packaging platforms erode wholesale intermediary positions. Acquire caddie workforce training capabilities to defend throughput capacity at premium venues against recruitment bottlenecks. Channel control through direct booking technology investment offsets margin compression from corporate procurement unbundling. For New Entrants and Emerging Players: Caddie workforce scarcity at Scottish links properties presents a service-layer gap where specialized staffing agencies can capture margin between operators and experienced bag carriers. Japan's METI-certified inbound segment offers the most penetrable geography for quality-assured market entry. A go-to-market angle targeting aging domestic Japanese golfers with English-speaking concierge coordination bypasses incumbent wholesale relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dynamic packaging technology providers as AI-powered itinerary engines achieve scale without proportional infrastructure expansion. Long-term viability favors technology-enabled intermediaries with real-time inventory aggregation over asset-heavy resort developers exposed to coastal erosion risk. Acquisition targets should demonstrate exclusive course partnerships and modern tee-time system integration. The signal to watch is corporate procurement adoption of unbundled retreat components as an inflection indicator for intermediary margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Offset Integration | Bundled emissions compensation creates loyalty mechanisms for EU Green Deal-compliant Scottish links properties. |
| Dynamic Packaging Technology | Real-time course-lodging aggregation transfers pricing power from wholesale intermediaries to algorithmic platforms. |
| Caddie Workforce Development | Specialized training programs address throughput bottlenecks at St Andrews and Turnberry premium venues. |
| METI Certification Acquisition | Quality-assured positioning opens Japan inbound expansion for operators targeting aging domestic golfers. |
| Direct Booking Channel Investment | Resort-to-traveler relationships eliminate intermediary commissions and enable personalized service customization. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with tour operator executives, resort revenue managers, caddie workforce coordinators, and corporate travel procurement officers; and secondary validation through FAA regulatory filings, EU CSRD disclosure databases, METI tourism certification records, and customs aviation fuel trade data. Bottom-up tee-time inventory aggregation triangulated against top-down destination spending estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including travel type, destination integration level, customer archetype, and booking channel technology adoption. CAGRs derived from historical growth trajectory analysis adjusted for regulatory inflection points and corporate incentive restructuring patterns. Forecast inputs incorporated coastal erosion exposure indices and aviation fuel price volatility assumptions.
Forecasts assume regulatory continuity in EU Green Deal CSRD frameworks and FAA charter coordination rules; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Travel and Tourism
Ethno Tourism Community Based Eco Tourism Market
Travel and Tourism
Latin America Inflight Services Market
Travel and Tourism
Yoga Tourism Market
Travel and Tourism
Tourism Security Market
Travel and Tourism
France Outbound Tourism Market
Travel and Tourism
Japan Tourism Market
Travel and Tourism
Germany Outbound Tourism Market
Travel and Tourism
Inflight Shopping Market
Travel and Tourism
China Travel Retail Market
Travel and Tourism
Agritourism Market
Travel and Tourism
Maldives Hospitality Market
Travel and Tourism
Global Home Exchange Service Market
Travel and Tourism
France Luxury Travel Market
Travel and Tourism
MICE Travel Service Market
Travel and Tourism
India Wellness Tourism Market
Travel and Tourism
Singapore Travel Retail Market