
 Europe Tumble Dryers Market | 2026-2036
Europe Tumble Dryers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Tumble Dryers Market Insights
The EU Green Deal is consolidating demand around low-energy appliances across European households. Miele & Cie. KG leverages its premium manufacturing base in Germany to dominate the high-efficiency segment. BSH Hausgeräte GmbH sustains broad portfolio coverage across multiple European markets through integrated production networks. Electrolux AB anchors its competitive stance with sensor-driven drying technologies that align with tightening EU efficiency mandates.
A tumble dryer is a forced-air laundry appliance that removes moisture from textiles through heated air circulation, with drum capacities typically spanning 7 to 10 kilograms for residential units and operating temperatures between 50°C and 70°C depending on the drying program selected. Heat pump variants now lead product type dynamics by recapturing and reusing thermal energy, while sensor drying technology commands expanding share as real-time moisture detection reduces cycle times and energy consumption. The commercial end user segment generates concentrated margin pools across hospitality and industrial laundries where throughput reliability determines procurement decisions.
The EU Ecodesign Directive and F-Gas Regulation shape mandatory efficiency thresholds and refrigerant specifications for heat pump dryers sold across member states. ECHA monitors chemical compliance in coatings and insulation materials used in drum assemblies and housing components. National energy labeling frameworks in France, Germany, and Italy directly influence consumer visibility of operating costs at the point of purchase. Stakeholders must track upcoming revisions to ecodesign requirements and refrigerant phase-down schedules to align R&D pipelines with compliance timelines.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant options for heat pump dryers, forcing manufacturers to accelerate R&D on natural refrigerants and low-GWP alternatives ahead of phasedown deadlines.
Growth Catalysts
- EU Green Deal efficiency mandates:The directive tightens energy performance standards for household appliances, compelling residential buyers to replace aging vented dryers with A+++ rated heat pump units.
- Heat pump technology maturation:Improved coefficient of performance ratios and reduced drying cycle times are eliminating the performance gap that previously deterred German and Italian consumers.
- France's national energy labeling visibility:Point-of-sale operating cost disclosures are redirecting purchase decisions toward higher-efficiency models in hypermarket and specialty retail channels.
Market Restraints
- Copper and aluminum price volatility:Heat pump compressors and heat exchangers depend on these base metals, exposing manufacturers to input cost swings that compress margin buffers on mid-tier products.
- Compressor supply concentration:European dryer OEMs rely heavily on Asian-sourced rotary and scroll compressors, creating vulnerability to logistics disruptions and tariff exposure.
- Vented dryer substitution drag:Lower upfront costs and faster cycle times continue to anchor demand in price-sensitive segments of Spain and Eastern Europe, slowing the efficiency transition.
Strategic Opportunities
- Poland and Romania residential penetration:Heat pump dryer ownership rates in these markets lag Western Europe by substantial margins, creating whitespace for entry-level efficiency products.
- Hospitality sector service contracts:Commercial laundries in France and Germany are migrating from capital purchase to managed service models that bundle equipment, maintenance, and energy optimization.
- Sensor-integrated predictive maintenance:IoT-enabled moisture detection and motor diagnostics are converging with remote monitoring platforms to unlock recurring revenue streams.
Industry Challenges
- Natural refrigerant certification timelines:The transition to propane and isobutane requires extensive safety testing under EU pressure equipment directives, stretching product development cycles.
- Heat pump technician scarcity:Installation and repair of complex refrigeration circuits demands specialized skills that vocational training programs in Italy and Spain have not scaled to match deployment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Tumble Dryers Market |
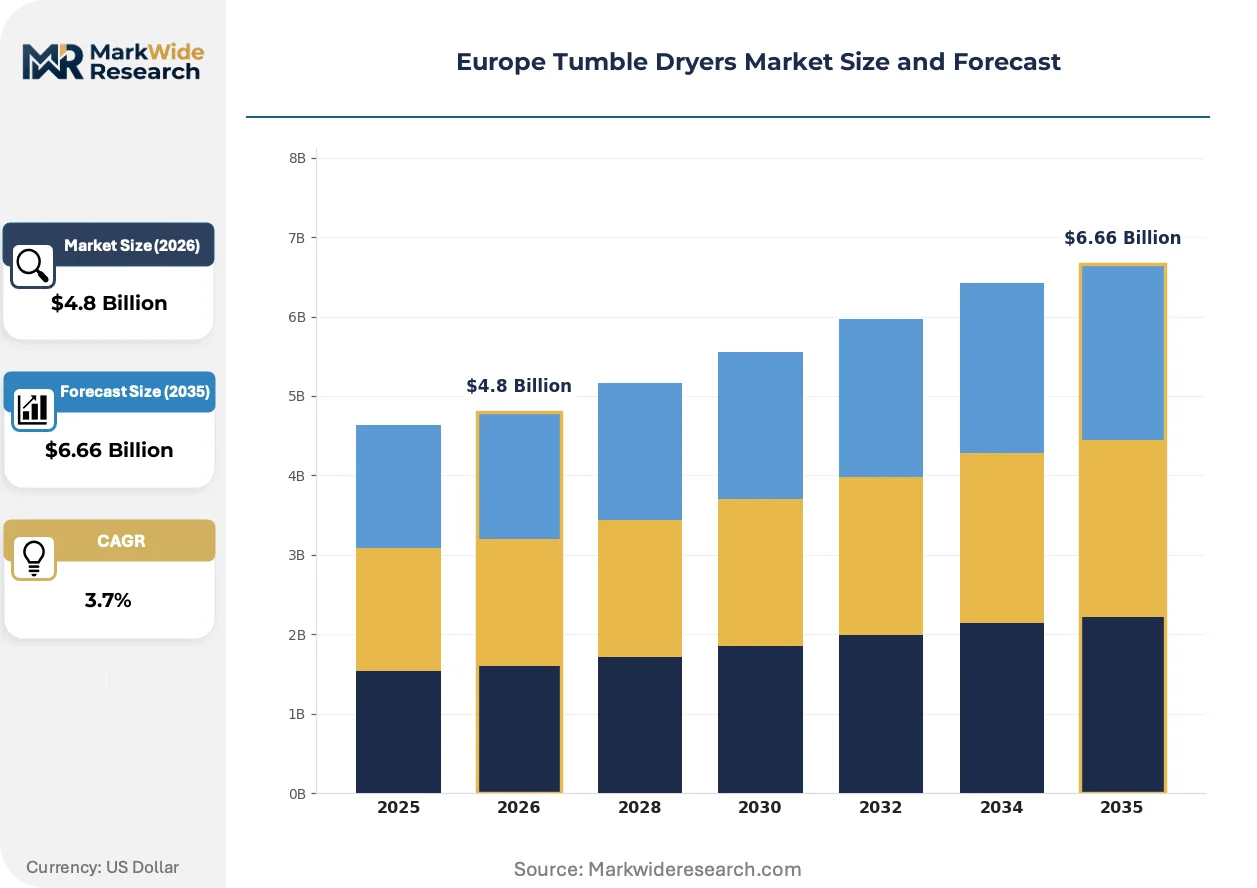
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vented, Condenser, Heat Pump, Compact End User: Residential, Commercial, Industrial, Hospitality Technology: Sensor Drying, Timed Drying, Energy Efficient, Smart Connect Distribution Channel: Online, Offline, Direct Sales, Retail |
| Companies Covered | Miele & Cie. KG, Samsung Electronics Co. Ltd., BSH Hausgeräte GmbH, Hisense Europe, Haier Europe, Whirlpool Corp., LG Electronics Inc., AEG, Electrolux AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Tumble Dryers Market Trends and Innovations
Connected appliance ecosystems and refrigerant chemistry advances are redefining product architecture and go-to-market economics across European laundry markets.
Heat pump drying circuits are unifying vapor compression and air-handling subsystems into compact, platform-shared modules. Premium residential buyers in Germany and the Netherlands are specifying these integrated systems at accelerating rates. This unification is compressing the cost gap between heat pump and conventional vented dryers, eroding the price barrier that historically segmented the market.
REACH chemical restrictions on coatings and insulation materials are forcing drum assembly redesigns across EU manufacturing footprints. The regulation's evolving SVHC candidate list is triggering supply chain audits for polymer components and surface treatments. Italian and Polish production facilities are responding by qualifying alternative powder coatings and bio-based insulation foams ahead of sunset dates.
Retail buyers are fragmenting across channel types, with French and German consumers splitting purchases between online marketplaces, manufacturer direct sites, and energy-efficiency subsidized municipal programs. Traditional electronics hypermarkets are losing traffic to specialized home appliance chains that offer installation bundling. This rotation is most visible in urban centers where same-day delivery logistics and white-glove service have become decisive selection criteria.
Europe Tumble Dryers Market Segmentation
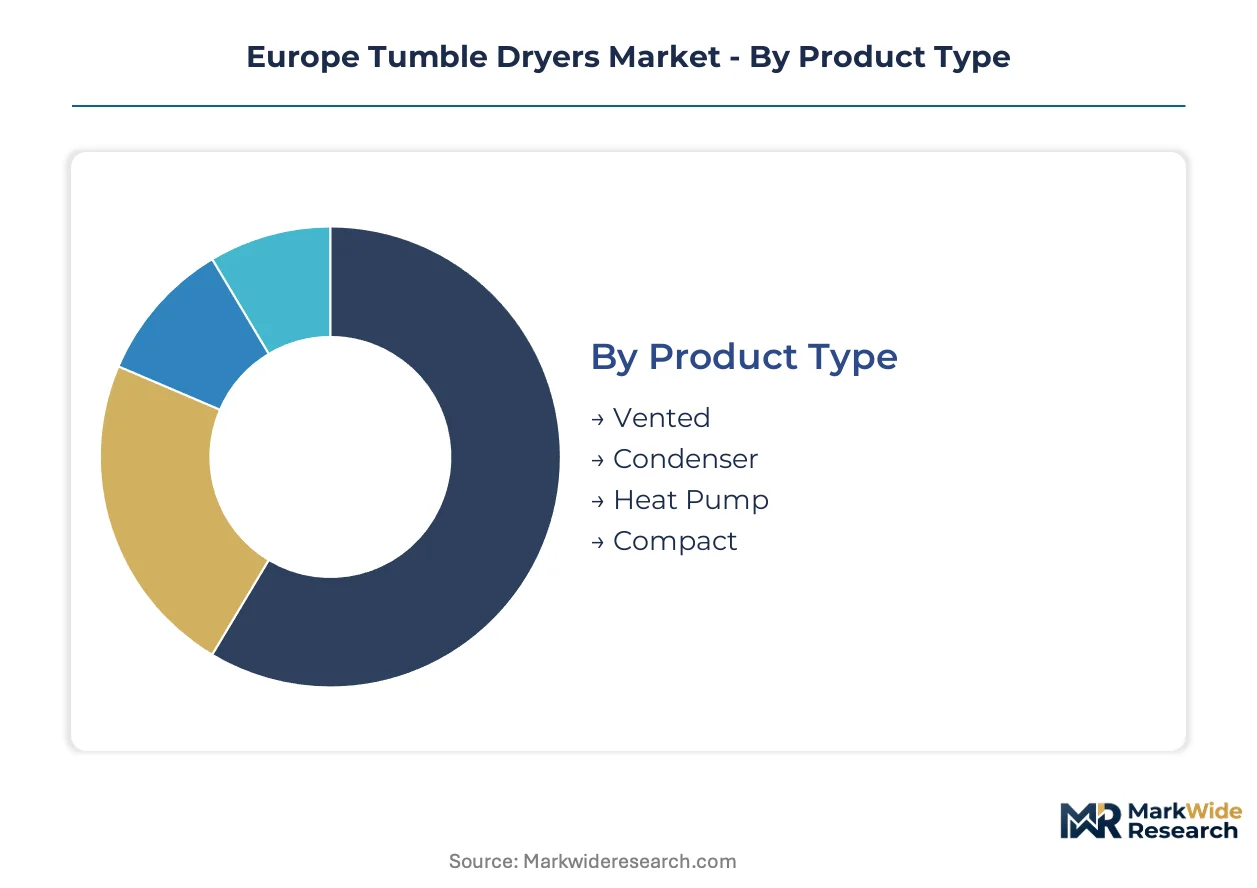
Segmentation in the Europe tumble dryers market reveals how efficiency mandates and purchasing channel shifts are fragmenting demand across technology tiers and end-use applications. Manufacturers must align product portfolios with distinct performance requirements and procurement behaviors.
Product Type:
The customization-vs-standardization spectrum spans from mass-market vented units to precision-engineered heat pump systems with proprietary refrigeration circuits.
- Heat Pump:Closed-loop refrigeration circuits recapture exhaust heat through vapor compression, achieving A+++ energy ratings under EU Ecodesign Directive thresholds. German and Dutch households are consolidating purchases around these units as operating cost visibility intensifies at point of sale.
- Vented:Direct exhaust systems expel moist air through external ducting, requiring minimal installation complexity but consuming substantially higher energy per cycle. Spain and Eastern European markets sustain demand here due to lower upfront price points and faster drying cycles.
- Condenser:Internal water collection eliminates external venting requirements, suiting apartment installations across urban France and Italy where building regulations restrict ductwork modifications.
- Compact:Reduced drum capacities below 6 kilograms target space-constrained urban dwellings and secondary vacation properties throughout Mediterranean coastal regions.
Leading the category by volume: Heat Pump. Expanding most quickly: Heat Pump.
End User:
Cost tier separation distinguishes capital-light residential replacement cycles from commercial procurement governed by total cost of ownership calculations.
- Residential:Individual households drive replacement demand through wear-out of aging vented units, with purchase decisions increasingly influenced by France's national energy labeling framework displaying ten-year operating costs. Sensor-equipped heat pump models are capturing disproportionate share in German suburban markets.
- Commercial:Independent laundromats and multi-family housing facilities prioritize throughput reliability and service response times over efficiency ratings, creating concentrated demand for robust condenser systems with extended warranty coverage.
- Industrial:Textile processors and institutional laundries operate continuous-batch equipment with drum capacities exceeding 15 kilograms, where heat recovery systems and automated loading interfaces determine vendor selection.
- Hospitality:Hotels and restaurant groups across France and Germany are migrating from equipment purchase to managed service contracts bundling maintenance, energy optimization, and linen supply logistics.
Dominant by revenue: Residential. Gaining share fastest: Hospitality.
Technology:
Application maturity separates established timed-drying platforms from emerging connectivity stacks requiring cloud infrastructure investment.
- Sensor Drying:Real-time moisture detection through conductivity or capacitive probes terminates cycles automatically, reducing energy consumption and fabric wear. Electrolux and BSH Hausgeräte are embedding these systems across premium portfolios to align with tightening EU efficiency mandates.
- Smart Connect:Wi-Fi enabled diagnostics and remote program selection integrate with home energy management systems, appealing to tech-forward households in Scandinavian markets and German smart city pilot zones.
- Timed Drying:Fixed-duration cycles without load sensing persist in rental property and budget-conscious segments where simplicity overrides efficiency optimization.
- Energy Efficient:Broad designation encompassing heat pump cores, inverter-driven motors, and optimized air handling geometries that collectively reduce kWh consumption per kilogram dried.
Widest installed base: Sensor Drying. Steepest adoption curve: Smart Connect.
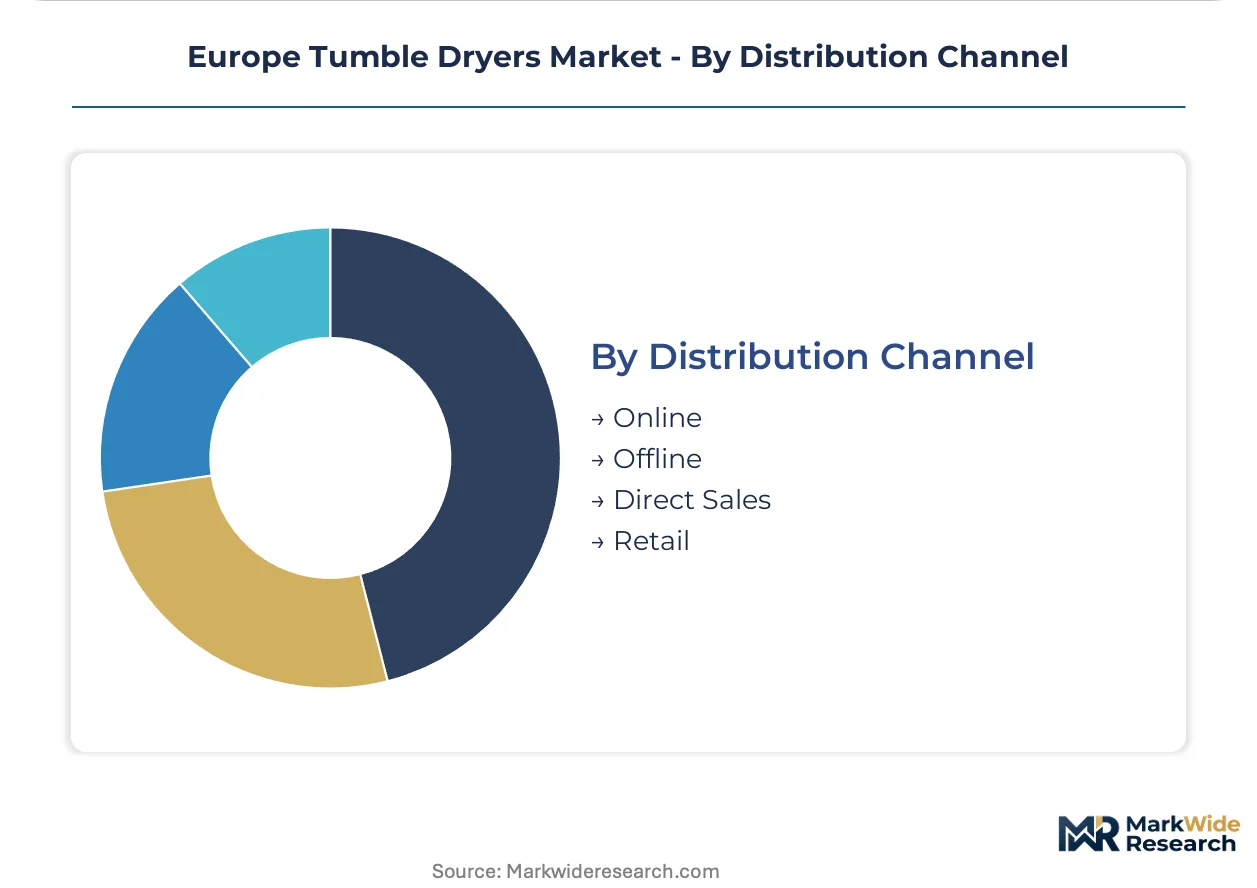
Distribution Channel:
Customer type fragmentation is redirecting volume from traditional electronics hypermarkets toward specialized retail and digital direct channels.
- Online:Manufacturer-direct storefronts and marketplace platforms capture growing share among replacement buyers conducting specification research independently, with same-day delivery logistics becoming decisive in urban German and French markets.
- Retail:Specialized home appliance chains with installation bundling and white-glove service are outperforming generalist electronics retailers, particularly for heat pump units requiring refrigeration-qualified technicians.
- Offline:Physical showrooms with live product demonstration retain importance for first-time heat pump buyers evaluating noise levels and interface ergonomics before commitment.
- Direct Sales:Municipal energy-efficiency subsidy programs and utility-sponsored retrofit initiatives route volume through contracted distributors with certified installation networks.
Highest transaction volume: Retail. Accelerating most rapidly: Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr industrial corridor anchors European tumble dryer manufacturing and R&D activity, with heat pump technology development clustering around Cologne-Düsseldorf engineering networks and supply chain integration extending through the Benelux ports.
Germany
Residential replacement cycles and municipal energy retrofit programs drive heat pump dryer demand across Baden-Württemberg and Bavaria. The Federal Office for Economic Affairs and Export Control (BAFA) administers point-of-sale subsidies for A+++ rated appliances under national efficiency frameworks. Stuttgart's industrial basin hosts compressor testing facilities and refrigeration circuit assembly operations serving Western European OEM networks.
France
Parisian apartment dwellers and hospitality operators generate concentrated demand for compact condenser and heat pump units with noise-optimized designs. The Agence de la Transition Écologique (ADEME) mandates ten-year operating cost disclosures at retail, redirecting purchases toward efficiency-optimized models. The Lyon-Grenoble corridor houses sensor technology suppliers and connected appliance software development clusters.
Italy
Multi-family housing in Milan and Rome sustains condenser dryer demand where building codes restrict external venting installations. The National Agency for New Technologies, Energy and Sustainable Economic Development (ENEA) coordinates regional efficiency incentive programs targeting appliance replacement. Veneto's manufacturing belt produces drum assemblies and control module subsystems for integrated European supply chains.
Netherlands
Amsterdam and Rotterdam households exhibit early adoption patterns for smart-connected heat pump systems integrated with residential energy management platforms. The Netherlands Enterprise Agency (RVO) funds pilot programs for grid-responsive appliance fleets in smart city districts. Eindhoven's high-tech campus anchors IoT development partnerships between appliance OEMs and semiconductor suppliers.
Poland
Warsaw and Kraków residential markets present whitespace for entry-level heat pump penetration as ownership rates trail Western European benchmarks. The National Fund for Environmental Protection and Water Management (NFOŚiGW) channels EU cohesion funds toward household appliance efficiency upgrades. Silesian industrial zones host expanding final assembly capacity serving Central European distribution networks.
Europe Tumble Dryers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and installation service bundling, with the market consolidating around three to four dominant manufacturing groups and a fragmented tier of regional assemblers. German and Korean capital anchors the upper tier through captive compressor supply and proprietary refrigeration circuit designs. Strategic archetypes include integrated appliance conglomerates with cross-category platform sharing, specialist laundry equipment manufacturers with service-network depth, and Asian electronics groups leveraging display panel and semiconductor synergies. Capacity expansion into Polish and Romanian assembly bases and technology licensing for natural refrigerant transitions represent the dominant competitive moves.
Among Germany-based fabricators, Miele & Cie. KG and BSH Hausgeräte GmbH exemplify the premium-tier archetype through manufacturing depth and distribution control, while Electrolux AB anchors Scandinavian-engineered positioning across sensor-integrated product lines. Samsung Electronics Co. Ltd. represents the scale-driven Korean electronics model with component integration advantages.
| Leading Market Players |
|---|
| Miele & Cie. KG |
| Samsung Electronics Co. Ltd. |
| BSH Hausgeräte GmbH |
| Hisense Europe |
| Haier Europe |
| Whirlpool Corp. |
| LG Electronics Inc. |
| AEG |
| Electrolux AB |
| Others |
Pricing and Supply Chain Analysis
Captive compressor production in Germany and South Korea anchors both supply security and premium pricing power for heat pump dryer OEMs serving Western European markets. This vertical integration choice insulates tier-one manufacturers from commodity metal volatility while enabling sustained margin capture on A+++ rated units.
Pricing Analysis
Value-based pricing anchored to ten-year operating cost savings dominates the residential segment, particularly where France's ADEME-mandated energy disclosures appear at retail. Pricing stratifies across premium heat pump systems with proprietary refrigeration circuits, standard sensor-equipped models, and economy condenser units for apartment installations. Cost compression in the mid-tier is intensifying because copper and aluminum input volatility erodes buffer margins on Asian-sourced compressor assemblies. Price-sensitive buyers concentrate in Poland and Romania, while German and Dutch households exhibit lowest sensitivity due to municipal subsidy programs.
Supply Chain Analysis
Direct-to-OEM channels handle compressor procurement for Miele and BSH Hausgeräte, while specialized appliance distributors manage aftermarket service parts across fragmented retail networks. Component sourcing concentrates in China, South Korea, and Germany, with rotary and scroll compressor assemblies drawing from Asian manufacturing bases. Heat exchanger aluminum, copper tubing, and refrigerant-grade steel represent critical input dependencies. Single-source vulnerability around Asian compressor supply creates exposure to logistics disruptions and tariff exposure. Distribution runs through Benelux port clusters into Rhine-Ruhr assembly facilities, with final-mile installation bundling increasingly handled by refrigeration-certified technician networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe tumble dryers market operates as a cost-of-compliance story where the EU F-Gas Regulation creates a barrier-to-entry moat for players with certified natural refrigerant platforms and captive safety testing capabilities.
For Market Incumbents: Lock in technician certification networks across Italy and Spain before vocational training bottlenecks constrain heat pump deployment rates. Deepen backward integration into refrigerant circuit assembly through Polish capacity expansion, defending against emerging Asian OEMs with display panel synergies. Prioritize sensor-integrated predictive maintenance platforms to capture recurring revenue streams as hospitality buyers migrate to managed service contracts. For New Entrants and Emerging Players: Launch via municipal energy-efficiency subsidy channels in Warsaw and Kraków, where heat pump ownership rates trail Western benchmarks and entry-tier whitespace remains unclaimed. Target compact condenser systems for Parisian apartment dwellings restricted by external venting regulations. Exploit the service-contract pivot among French and German hospitality operators by bundling equipment with remote monitoring diagnostics. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated appliance conglomerates seeking refrigeration circuit expertise and captive compressor supply. Long-term viability favors manufacturers with natural refrigerant certification timelines already cleared under EU pressure equipment directives. Watch for inflection signals in Poland's NFOŚiGW subsidy uptake rates as an indicator of Central European penetration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant Platform Migration | Propane and isobutane certification under EU pressure equipment directives secures F-Gas Regulation compliance ahead of phase-down deadlines. |
| Sensor-Integrated Predictive Maintenance | IoT-enabled moisture detection and motor diagnostics unlock recurring revenue from hospitality sector managed service contracts. |
| Poland and Romania Market Entry | NFOŚiGW-subsidized efficiency upgrades create whitespace for entry-level heat pump penetration below Western European ownership rates. |
| Technician Certification Network Buildout | Refrigeration-qualified installation capacity in Italy and Spain removes deployment bottlenecks constraining heat pump adoption velocity. |
| Compact Condenser System Development | Space-optimized designs address Parisian and Milanese apartment restrictions on external ducting modifications. |
Research Methodology
Multi-period observation of heat pump adoption rates, municipal subsidy program uptake, and refrigerant certification timelines anchored the trend analysis, supplemented by interviews with appliance OEM product managers, ECHA compliance officers, French retail category buyers, and Italian installation contractor networks. Secondary validation drew from EU Ecodesign Directive revision documents, F-Gas Regulation implementation schedules, national energy labeling frameworks, and customs data on compressor import flows. Bottom-up unit shipment modeling and top-down market value reconciliation ensured cross-verification of segment outputs.
Input-output matrices structured the projection framework across product type, end user, technology tier, and distribution channel dimensions throughout the forecast period. CAGRs were derived from fitted trend extrapolation against efficiency mandate phase-in schedules and replacement cycle dynamics. Industry-specific forecast inputs included BAFA and ADEME subsidy budget trajectories, REACH SVHC candidate list evolution, and smart city pilot program expansion rates in Dutch urban centers.
Refrigerant chemistry transitions, compressor supply disruptions, and subsidy program suspensions are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions on regulatory timeline adherence and metal price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Washing Appliances Market
Appliances
Asia-Pacific Microwave Oven Market
Appliances
Mexico Laundry Appliances Market
Appliances
Bathroom Heaters Market
Appliances
UAE Dishwasher Market
Appliances
Electric Rice Cooker Market
Appliances
Microwave Market
Appliances
Shared Shoe Washing Machine Market
Appliances
Portable Dishwasher Market
Appliances
Electric Fan Market
Appliances
Electric Hand Dryer Market
Appliances
Residential Space Heater Market
Appliances
Egypt Dishwashers Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Electric Iron Market