
 Laundry Kiosk Market | 2026-2036
Laundry Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Kiosk Market Insights
The gap between premium connected kiosks and basic coin-operated units is restructuring procurement patterns across the laundry kiosk landscape. Diebold Nixdorf leverages its financial self-service heritage to embed advanced payment architectures into laundry terminals. KioSoft anchors its position through software ecosystems that unify machine control, payment processing, and remote monitoring for multi-site operators. Alliance Laundry Holdings sustains manufacturing scale advantages that let it compete aggressively on equipment cost while maintaining service network density.
A laundry kiosk is an automated terminal integrating washing or drying machine control, payment processing, and user interface functions into a standalone or networked unit, typically supporting load capacities from 6 kg to 25 kg and operating on 208-240V three-phase power for commercial-grade throughput. Self-service kiosks dominate installed bases in North American apartment complexes and university housing, while mobile laundry units represent the fastest-expanding category as fleet-based operators target construction sites and seasonal hospitality venues. Full-service kiosks command premium positioning in hotel and resort settings where white-glass handling and garment tracking justify higher per-load pricing, and subscription models are capturing recurring revenue streams that offset upfront capital intensity for equipment deployers.
Electrical safety standards from IEC shape baseline product certification requirements for kiosk manufacturers exporting across multiple jurisdictions, while PCI DSS compliance governs payment module integration and directly influences vendor selection criteria for operators handling card transactions. In the United States, OSHA workplace safety guidelines affect commercial laundry facility layouts and kiosk placement protocols to protect attendants and service technicians. Stakeholders must weigh capital deployment timing against evolving contactless payment mandates and energy efficiency benchmarks that will determine which equipment vintages remain financeable over extended replacement cycles.
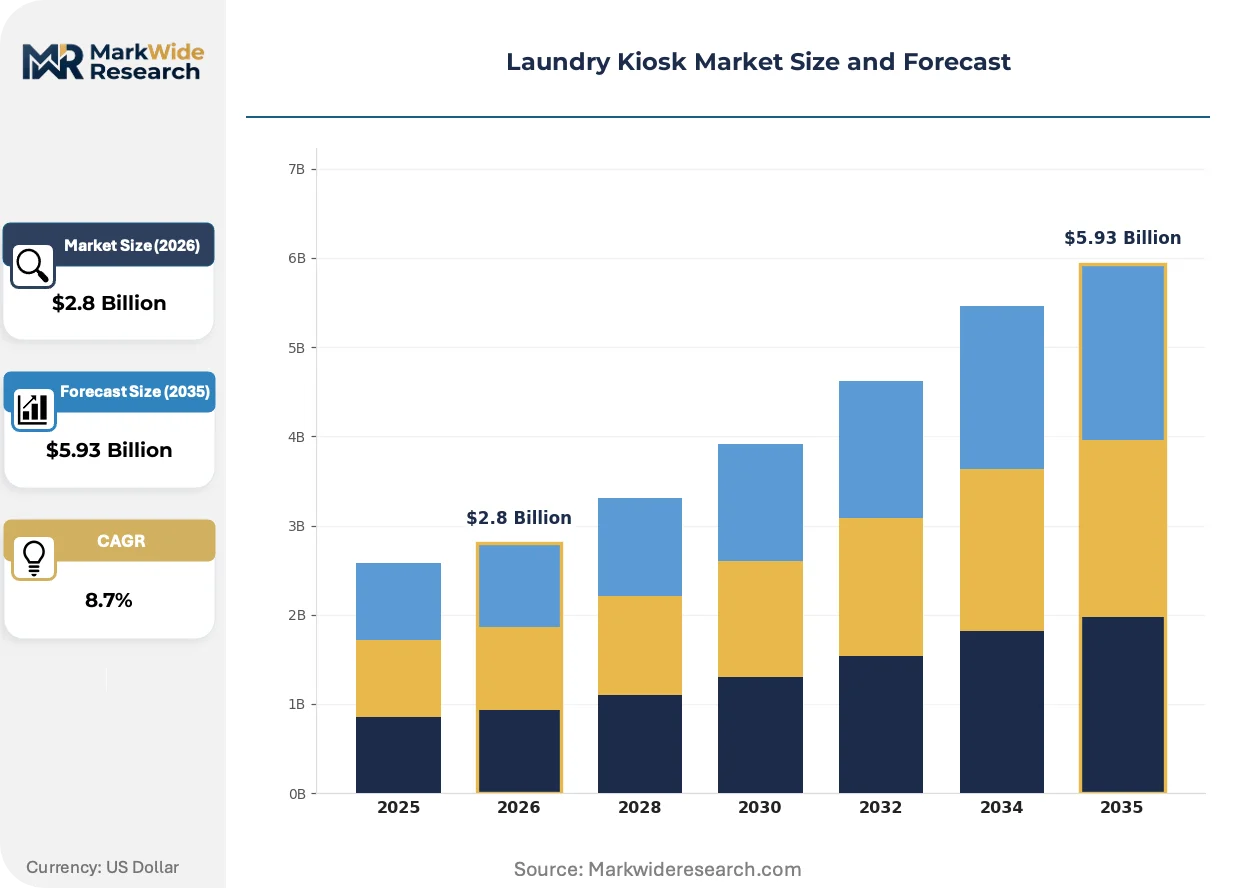
Market Dynamics
Contactless payment mandates from PCI DSS are forcing equipment replacement cycles to compress across commercial laundry operations, while university housing departments accelerate kiosk deployments to eliminate attendant labor costs.
Growth Catalysts
- PCI DSS contactless mandates:Operators in the United States face 2025 deadlines for EMV compliance, triggering wholesale terminal upgrades that favor integrated kiosk architectures over retrofitted coin boxes.
- University housing privatization:Campus facilities management outsourcing creates concentrated procurement pools seeking automated solutions to reduce resident service complaints and maintenance headcount.
- South Korean micro-housing density:Seoul's sub-30-square-meter apartment proliferation generates acute demand for compact, stackable kiosk configurations that maximize floor efficiency.
Market Restraints
- Stainless steel input volatility:Drum and chassis fabrication depends on 304-grade stainless pricing, with Korean and Chinese mill concentration exposing manufacturers to tariff and freight cost swings.
- Three-phase electrical infrastructure gaps:Older North American apartment buildings lack 208-240V commercial power, limiting kiosk penetration in pre-1990 housing stock without costly electrical retrofits.
- Coin mechanism residual dependency:Unbanked tenant populations in lower-income multifamily housing sustain demand for hybrid payment terminals, complicating pure contactless product roadmaps.
Strategic Opportunities
- Construction site mobile deployment:Fleet-based operators targeting oilfield and infrastructure projects in Texas and Alberta can capture premium pricing for temporary laundry services where permanent facilities do not exist.
- Hotel white-glass service integration:Full-service kiosks with garment tracking and pressing capabilities address unmet demand in boutique hospitality properties seeking to differentiate guest experience.
- Subscription revenue models:Unlimited wash plans for student housing and military bases convert volatile transaction revenue into predictable recurring cash flows that improve equipment financing terms.
Industry Challenges
- Field technician certification bottlenecks:Payment module and HVAC system repairs require dual-competency technicians, with training programs failing to keep pace with kiosk installation growth.
- Legacy building management system integration:Proprietary protocols from incumbent equipment vendors block seamless kiosk connectivity, forcing operators to maintain parallel maintenance contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Kiosk Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Full-Service Kiosks, Mobile Laundry Units, Drop-Off Kiosks Payment Method: Cash, Credit/Debit Cards, Mobile Payments, Contactless Payments End User: Residential Customers, Commercial Establishments, Hotels, Universities Service Model: Subscription Model, Pay-Per-Use, Membership-Based, On-Demand |
| Companies Covered | Diebold Nixdorf, NCR Voyix Corporation, Zebra Technologies, Advantech, Glory, KioSoft, CCI, Alliance Laundry Holdings, Dexter Laundry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Kiosk Market Trends and Innovations
Hardware-software convergence is compressing vendor margins while creating new service revenue layers. Equipment suppliers now compete on data platform capabilities rather than mechanical reliability alone.
Heat-pump drying technology is electrifying commercial kiosk efficiency. The technology recycles exhaust heat to reduce energy consumption by half compared to conventional gas or electric resistance dryers. University housing operators in California and New York are specifying heat-pump units to meet local building electrification ordinances. This shift is electrifying the competitive landscape by favoring vendors with thermal engineering expertise over traditional mechanical specialists.
OSHA's updated confined-space entry protocols for commercial laundry facilities are reshaping kiosk placement standards. The guidelines mandate minimum clearance zones around rear service panels, effectively prohibiting wall-mounted configurations in retrofitted utility closets. Equipment manufacturers are responding with front-access-only chassis designs that sacrifice load capacity for compliance flexibility. North American apartment complex operators face the steepest redesign costs as they reconfigure existing laundry rooms.
Usage-based financing is displacing traditional equipment lease structures. Laundry kiosk deployers now structure contracts where payments scale with transaction volume rather than fixed monthly rates. This model transfers demand risk from operators to financing parties, accelerating adoption among cash-constrained student housing authorities. The shift is most visible in South Korea, where KB Capital and other non-bank lenders have developed specialized underwriting for micro-housing kiosk portfolios.
Laundry Kiosk Market Segmentation
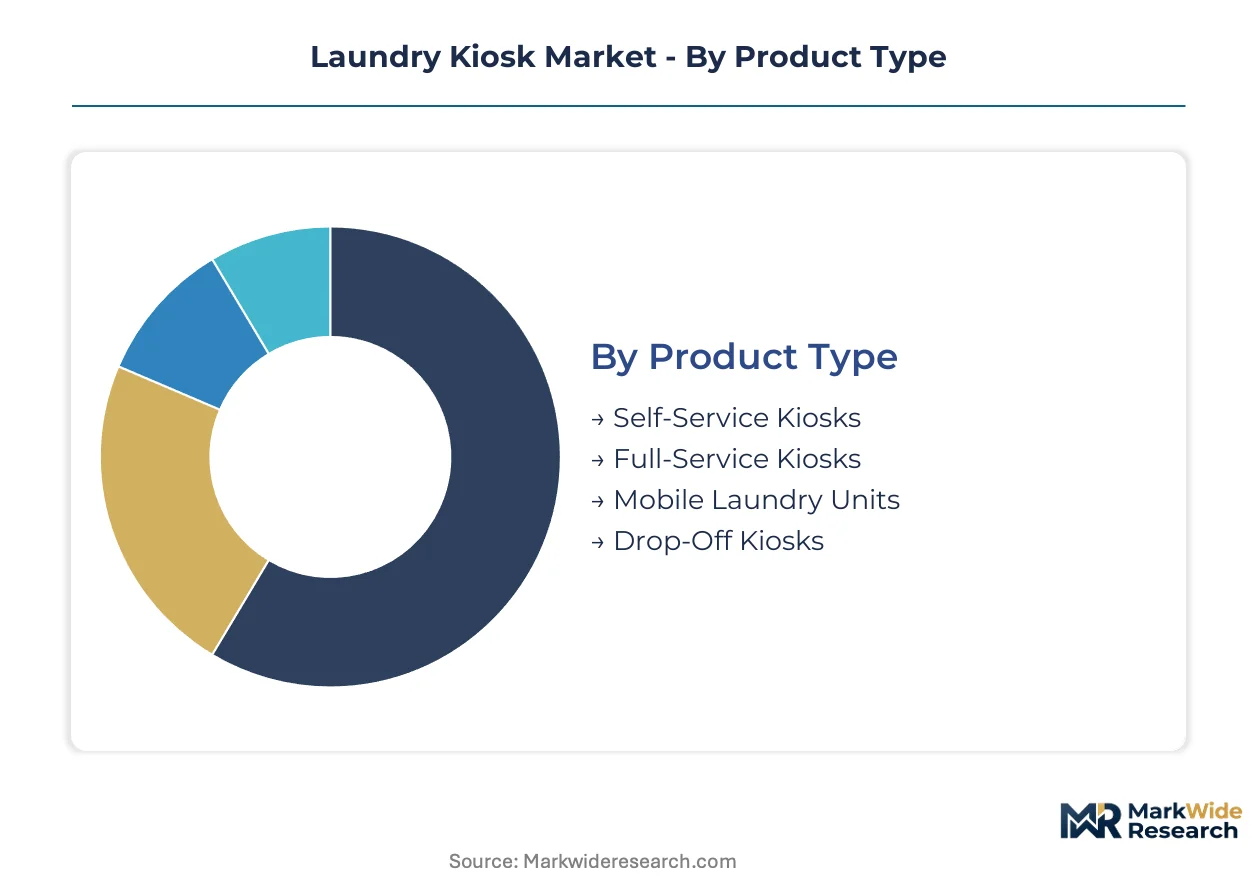
Laundry kiosk segmentation reveals how payment infrastructure, service intensity, and user context reshape procurement economics. Equipment specifications diverge sharply across these dimensions, forcing manufacturers to maintain modular platform architectures rather than unified product lines.
Product Type:
Capital deployment intensity and attendant labor requirements differentiate buyers most acutely across product categories.
- Self-Service Kiosks:Standalone terminals integrate washer/dryer control, payment processing, and user interface into unified chassis supporting 6-25 kg loads. University housing departments in the United States concentrate procurement here to eliminate resident service complaints and maintenance headcount.
- Mobile Laundry Units:Fleet-mounted equipment deploys to construction sites, oilfield camps, and seasonal hospitality venues without permanent infrastructure. Demand climbs fastest in Texas and Alberta where temporary workforce housing lacks utility connections.
- Full-Service Kiosks:White-glass handling and garment tracking capabilities command premium positioning in boutique hotels.
- Drop-Off Kiosks:Secure receptacle systems with digital tracking for unattended garment intake.
Volume sits with Self-Service Kiosks; growth tilts toward Mobile Laundry Units.
Payment Method:
PCI DSS compliance timelines and unbanked population density reshape terminal specifications and replacement cycles.
- Contactless Payments:NFC and tap-to-card architectures satisfy EMV mandates with minimal user friction. South Korean micro-housing operators specify these exclusively to match tenant smartphone dependency and accelerate throughput.
- Mobile Payments:QR-code and app-integrated wallets dominate student housing procurement where digital-native populations reject physical cards.
- Credit/Debit Cards:Magnetic stripe and chip-insert terminals persist in older multifamily stock.
- Cash:Coin and bill acceptors sustain relevance in lower-income housing serving unbanked tenant populations.
Deployment scale favors Contactless Payments; upgrade urgency centers on Mobile Payments.
End User:
Load predictability and service-level expectations determine equipment durability specifications and connectivity requirements.
- Universities:Concentrated procurement pools from privatized campus facilities management drive standardized kiosk rollouts. Peak-usage patterns around semester schedules demand high-throughput configurations with remote monitoring.
- Hotels:Garment-care quality requirements and guest experience differentiation justify premium full-service installations.
- Residential Customers:Apartment complex operators prioritize payment flexibility and vandal resistance.
- Commercial Establishments:Laundromat chains and retail hosts emphasize throughput maximization and labor reduction.
Installed base concentrates with Residential Customers; expansion rates peak at Universities.
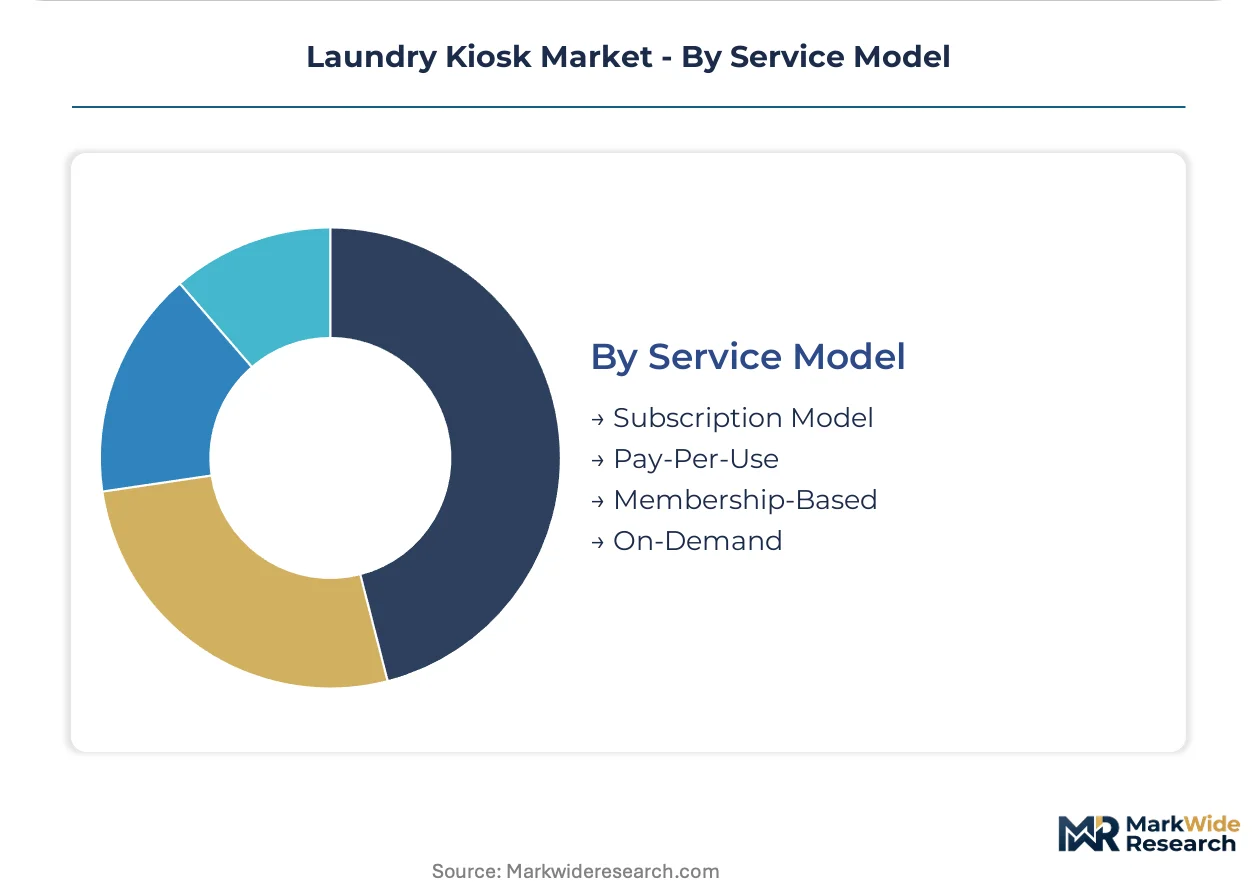
Service Model:
Revenue predictability and financing structure preferences separate stakeholders across service architectures.
- Subscription Model:Unlimited wash plans convert volatile transaction revenue into recurring cash flows. Military bases and student housing authorities in South Korea leverage these structures to improve equipment financing terms through KB Capital and non-bank lenders.
- Pay-Per-Use:Per-load pricing maintains flexibility for seasonal and transient populations.
- Membership-Based:Tiered access programs with loyalty integration target frequent users.
- On-Demand:App-triggered pickup and delivery coordination without fixed kiosk presence.
Transaction volume aggregates under Pay-Per-Use; margin expansion concentrates with Subscription Model.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul's sub-30-square-meter micro-apartment proliferation anchors the most concentrated kiosk deployment corridor worldwide, with the capital region housing density reshaping equipment specifications across the industry.
United States
University housing privatization and PCI DSS EMV compliance deadlines compress replacement cycles across campus facilities. OSHA confined-space protocols mandate front-access chassis redesigns for retrofitted utility closets. Texas and California lead deployment volume, with heat-pump specifications accelerating in electrification-mandated jurisdictions.
South Korea
Urban micro-housing density and smartphone-native tenant populations drive exclusive contactless payment specifications. KB Capital and non-bank lenders developed specialized underwriting for micro-housing kiosk portfolios. Seoul Capital Area operators stack compact configurations to maximize floor efficiency in sub-30-square-meter units.
Germany
Building electrification ordinances and REACH chemical safety standards reshape equipment import criteria. Industrial laundromat chains in North Rhine-Westphalia prioritize energy-label compliance for fleet standardization. Bavaria's hospitality corridor tests full-service kiosk integration for boutique hotel differentiation.
Japan
Space-constrained urban housing and METI energy efficiency benchmarks favor compact heat-pump configurations. Tokyo's coin-laundry market maturation pushes vendors toward subscription-model experimentation. Kansai region operators integrate mobile payment wallets to match digital-native demographics.
Canada
Alberta's oilfield camp infrastructure and seasonal workforce mobility sustain mobile laundry unit demand. Cold-climate operational requirements drive thermal engineering specifications for fleet-based deployments. Ontario's university housing authorities evaluate usage-based financing structures to transfer demand risk from operators.
Laundry Kiosk Market Competitive Landscape
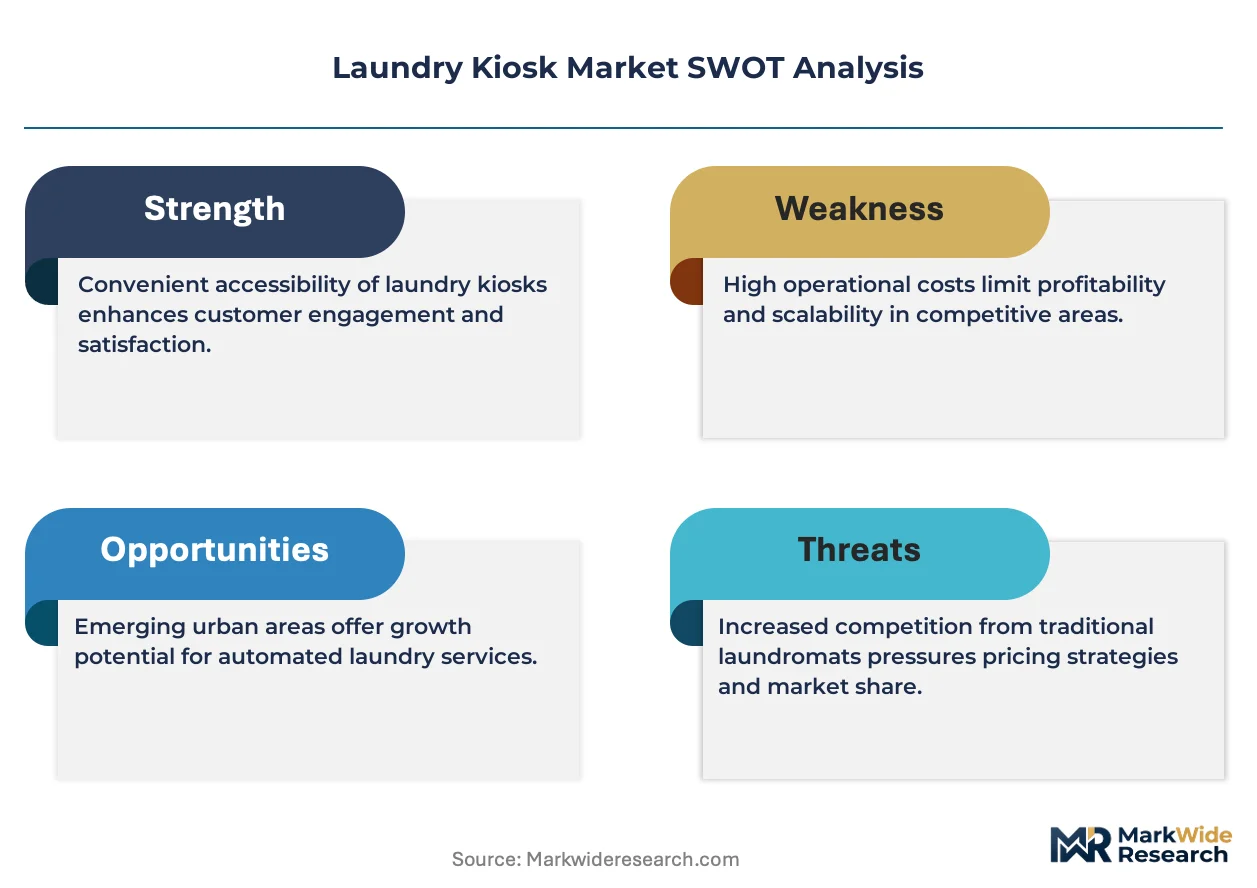
Capital-heavy producers compete with asset-light designers across a bifurcated structure where manufacturing scale advantages clash with software platform differentiation. Equipment fabricators with captive foundry capacity anchor supply security for stainless-steel drum fabrication, while payment module integrators license terminal architectures to avoid fixed asset intensity. Three archetypes dominate: diversified industrial conglomerates with financial self-service heritage, specialized kiosk software platforms unifying multi-site control, and pure-play laundry equipment manufacturers competing on service network density. Competitive moves concentrate on heat-pump thermal engineering acquisitions and usage-based financing partnership structures.
Within the financial self-service tier, Diebold Nixdorf and NCR Voyix Corporation represent heritage banking terminal players extending payment architectures into commercial laundry applications. KioSoft occupies a position exemplifying the software-platform archetype, with its ecosystem approach to machine control and remote monitoring. Alliance Laundry Holdings anchors the manufacturing-scale tier, competing through equipment cost positioning and service network density.
| Leading Market Players |
|---|
| Diebold Nixdorf |
| NCR Voyix Corporation |
| Zebra Technologies |
| Advantech |
| Glory |
| KioSoft |
| CCI |
| Alliance Laundry Holdings |
| Dexter Laundry |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap equipment fabricators with captive foundry capacity anchor supply security for stainless-steel drum production while exerting pricing discipline through backward integration into metal forming. Their ownership structure insulates procurement from short-term commodity swings, compressing margin volatility for downstream kiosk deployers.
Pricing Analysis
Value-based pricing anchored to machine throughput and uptime guarantees dominates procurement contracts for university housing operators. Three-tier pricing structure across premium connected kiosks, standard EMV-compliant terminals, and economy coin-hybrid units reflects payment module certification grade and remote monitoring capability. Cost compression in the economy tier is intensifying because unbanked tenant populations sustain residual coin demand, forcing manufacturers to maintain hybrid architectures. Student housing authorities exhibit the lowest price sensitivity, prioritizing subscription-model predictability over per-load economics.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Korean 304-grade stainless steel mills concentrated in Jiangsu and Gyeongsang provinces. Drum and chassis fabrication draws from these concentrated metallurgical suppliers while payment module assembly rests on Taiwanese semiconductor foundries and Malaysian contract manufacturers. Tariff exposure on steel imports into the United States creates margin pressure for domestic equipment assemblers. Distribution runs through authorized service networks rather than direct OEM-to-operator channels, embedding maintenance contract economics into upfront equipment pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as kiosk manufacturers pursue captive control over heat-pump thermal engineering and payment module firmware to escape commoditization.
For Market Incumbents: Anticipate margin compression from software-platform entrants by deepening in-house production of IoT control systems and securing exclusive heat-pump component supply agreements. Counter the threat of usage-based financing disruptors by embedding subscription-management capabilities directly into equipment firmware, reducing operator dependence on third-party lenders. For New Entrants and Emerging Players: Enter via mobile laundry fleet deployment targeting Alberta oilfield camps and Texas infrastructure corridors where permanent utility infrastructure is absent. The construction site segment offers the most penetrable entry point with minimal incumbent service network density. Pursue a go-to-market angle anchored to thermal engineering differentiation for cold-climate operational requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized kiosk software platforms with multi-site control capabilities in South Korea's micro-housing corridor. Long-term viability hinges on recurring revenue attachment rates rather than equipment shipment volumes. Watch for inflection when usage-based financing penetration crosses critical mass among student housing authorities, signaling platform economics maturation.| Strategic Initiative | Industry Significance |
|---|---|
| Heat-Pump Technology Acquisition | Captures California and New York building electrification mandates while differentiating from gas-heated competitors. |
| Usage-Based Financing Partnership | Transfers demand risk from operators to KB Capital and non-bank lenders, accelerating cash-constrained adoption. |
| PCI DSS Certification Investment | Secures EMV compliance positioning ahead of United States operator upgrade deadlines. |
| Front-Access Chassis Redesign | Satisfies OSHA confined-space protocols for retrofitted North American apartment utility closets. |
| Subscription Platform Integration | Converts volatile transaction revenue into predictable recurring cash flows for military base and university deployments. |
Research Methodology
Trade association filings, customs records, and SEC equipment manufacturer disclosures formed the secondary backbone for shipment volume and pricing calibration. Primary interviews with campus facilities directors, commercial laundry operators, payment module integrators, and thermal engineering specialists validated assumptions on replacement cycle timing and specification preferences. Bottom-up and top-down triangulation reconciled machine-level deployment data against aggregate market value estimates.
Bottom-up modeling aggregated unit economics across product type, payment method, and end-user segments over the projection horizon. Segmentation dimensions included load capacity tier, connectivity architecture, service intensity level, and regional regulatory cluster. CAGRs were derived from installed base growth net of replacement demand and average selling price trajectory assumptions. Heat-pump adoption curves and contactless payment mandate compliance schedules served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under stainless steel tariff escalation or accelerated building electrification ordinance adoption. Forecasts reflect documented assumptions on university housing privatization pace and PCI DSS enforcement rigor. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Minibar Refrigerators Market
Appliances
Smart Refrigerator Market
Appliances
Global Vended Laundry Equipment Market
Appliances
Global Electric Water Heaters Market
Appliances
Lightwave Microwave Oven Market
Appliances
Colombia Appliances and Electronics Market
Appliances
Hairdryer Market
Appliances
China Washing Machine Market
Appliances
Mini Refrigerator Market
Appliances
Saudi Arabia Water Heater Market
Appliances
Egypt Dishwashers Market
Appliances
Washing Appliances Market
Appliances
Asia Pacific Water Heater Market
Appliances
Electric Iron Market
Appliances
Smart Connected Washing Machine Market
Appliances
Turkey Washing Machine Market