
 Laundry Detergent Sheets Market | 2026-2036
Laundry Detergent Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Detergent Sheets Market Analytics
Premium biodegradable certification is bifurcating the competitive landscape into performance-grade and value-grade tiers. Tru Earth leverages its direct-to-consumer platform to sustain subscription-driven retention in North America. Henkel AG and Co. KGaA anchors European shelf presence through established retail partnerships with major supermarket chains. Earth Breeze differentiates through plastic-free packaging and carbon-neutral shipping claims.
Laundry detergent sheets are thin, water-soluble films composed of concentrated surfactants, builders, and enzymes that dissolve completely in wash cycles without residue. These pre-measured strips typically weigh under 3 grams each and eliminate liquid measuring errors while reducing packaging volume by over 90 percent versus conventional bottles. The eco-friendly segment leads volume growth as consumers prioritize phosphate-free and plastic-reduced alternatives, while concentrated formulations capture margin pools through higher per-unit pricing and lower logistics costs. Commercial laundries represent the fastest-expanding end-user category as hotels and institutional facilities seek operational simplification and reduced storage footprints.
The EPA Safer Choice program and EU REACH framework govern chemical disclosure and biodegradability standards for detergent sheets sold in the United States and Europe, while the FDA regulates labeling claims for antimicrobial variants. Compliance with these overlapping standards shapes product development timelines and determines market access for new entrants. Stakeholders must monitor evolving state-level packaging mandates and retailer-specific sustainability scorecards that increasingly dictate shelf placement decisions.
Market Dynamics
Urban apartment dwellers in North America and Europe are compressing demand toward space-efficient laundry formats, while EPA Safer Choice and EU REACH phosphates restrictions force rapid biodegradable formulation transitions.
Growth Catalysts
- EPA Safer Choice certification:Hotels and institutional laundries in the United States now require phosphate-free sheets to meet procurement mandates, accelerating commercial segment adoption.
- Enzyme stabilization technology:Cold-water soluble films incorporating protease and lipase enzymes expand wash-temperature flexibility, capturing energy-conscious residential users.
- South Korea:Dense urban housing and government-backed green consumption incentives position Seoul apartment complexes as early mass adopters of subscription-based sheet delivery.
Market Restraints
- Palm-derived surfactant cost volatility:Malaysia and Indonesia supply concentration exposes manufacturers to input price swings that compress margin pools at value-grade tiers.
- EU REACH compliance friction:Divergent biodegradability testing protocols between member states extend product registration timelines and deter smaller entrants from European shelf placement.
- Liquid pod substitution threat:Established PVA-encapsulated detergent pods retain consumer familiarity and retail distribution density, slowing sheet penetration in mass-market channels.
Strategic Opportunities
- Germany:The EU Green Deal's packaging waste reduction targets and supermarket sustainability scorecards create first-mover advantage for plastic-free sheet entrants in Berlin and Munich retail networks.
- Antimicrobial sheet variants:Healthcare linen services and nursing home operators seek FDA-registered formulations, opening premium pricing tiers beyond residential applications.
- Direct-to-locker distribution:South Korean convenience store chains and apartment complex smart lockers enable subscription bypass of traditional retail slotting fees.
Industry Challenges
- Formulation chemist scarcity:Expertise in water-soluble film engineering and enzyme stability at commercial scale concentrates among a narrow pool of specialty chemical professionals.
- ISO 17025 laboratory certification delays:Independent biodegradability verification required for EPA and EU claims faces 6-12 month backlog at accredited testing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Detergent Sheets Market |
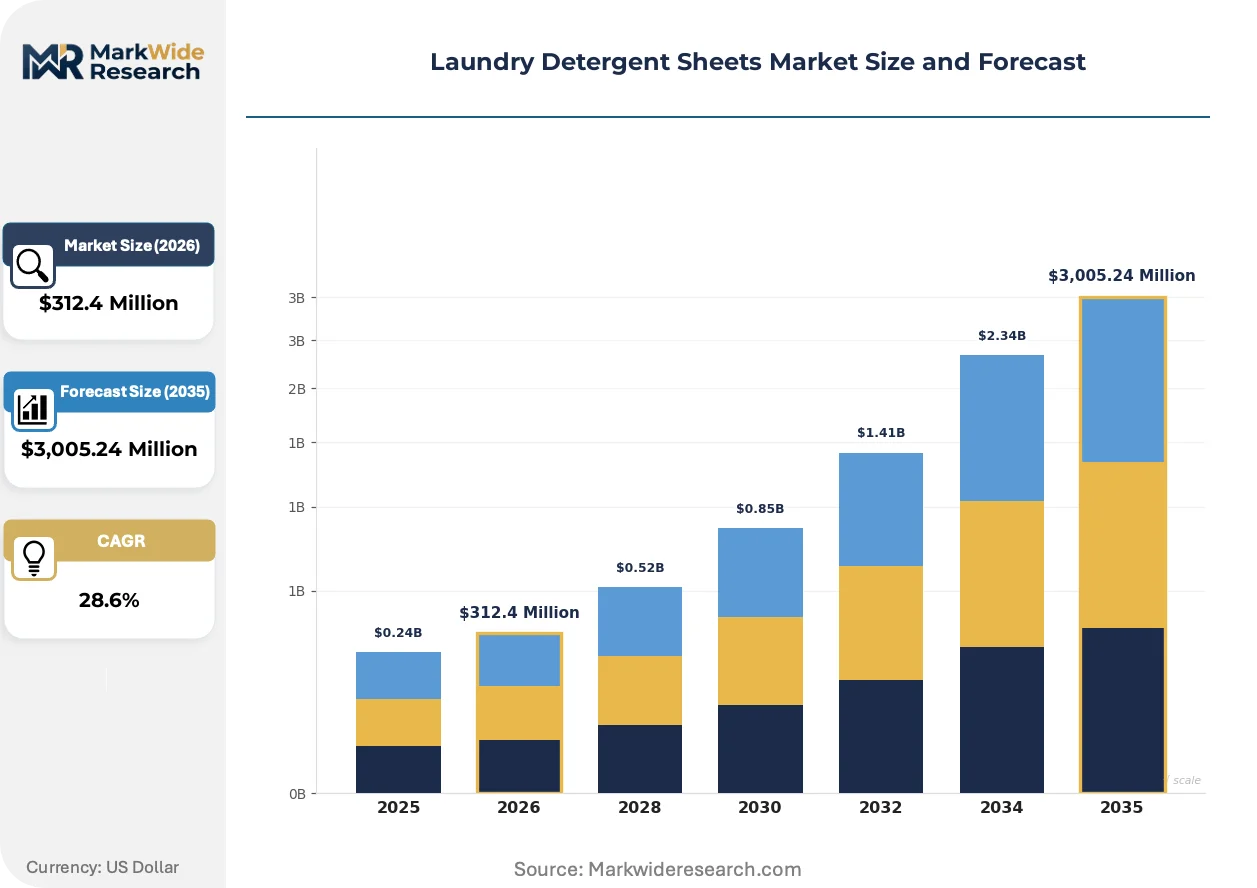
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $3,005.24 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Eco-Friendly, Concentrated, Standard, Scented End User: Households, Commercial Laundries, Hotels, Institutional Facilities Sales Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Formulation: Liquid, Powder, Gel, Biodegradable |
| Companies Covered | Kind Laundry, LG Household and Health Care Ltd., Earth Breeze, Church and Dwight Co. Inc., Unilever PLC, Tru Earth, Henkel AG and Co. KGaA, ECOS, Dizolve Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Detergent Sheets Market Evolving Landscape
Concentrated surfactant films are displacing legacy liquid formats through pre-measured dosing precision and logistics compression, while regulatory disclosure mandates and subscription commerce reshape competitive entry points.
Cold-water enzyme activation technology is bifurcating product development paths. Advanced lipase and cellulase formulations enable effective cleaning at 20°C wash cycles, cutting residential energy consumption. Hotels in the United States and Germany adopt these variants to meet corporate sustainability targets and reduce utility expenditures. The performance-grade tier is separating from value-grade alternatives based on enzyme concentration and temperature flexibility, compressing mid-market positioning.
REACH Annex XVII restrictions on phosphates and microplastics are tightening chemical disclosure requirements for detergent sheets sold across European Union member states. Manufacturers must submit full surfactant biodegradability data to ECHA, extending product development cycles by 8-14 months. German and French retailers now require third-party sustainability scorecard compliance for shelf placement, favoring established players with dedicated regulatory affairs capacity.
Subscription-based replenishment models are displacing episodic retail purchasing among urban apartment dwellers. Direct-to-consumer platforms in the United States and South Korea offer automated delivery cycles synchronized with wash frequency data, capturing lifetime value through reduced churn. This shift concentrates customer acquisition spend toward digital channels and away from retail slotting fees, with Seoul and San Francisco metropolitan areas showing highest conversion rates for annual commitment plans.
Laundry Detergent Sheets Market Segmentation
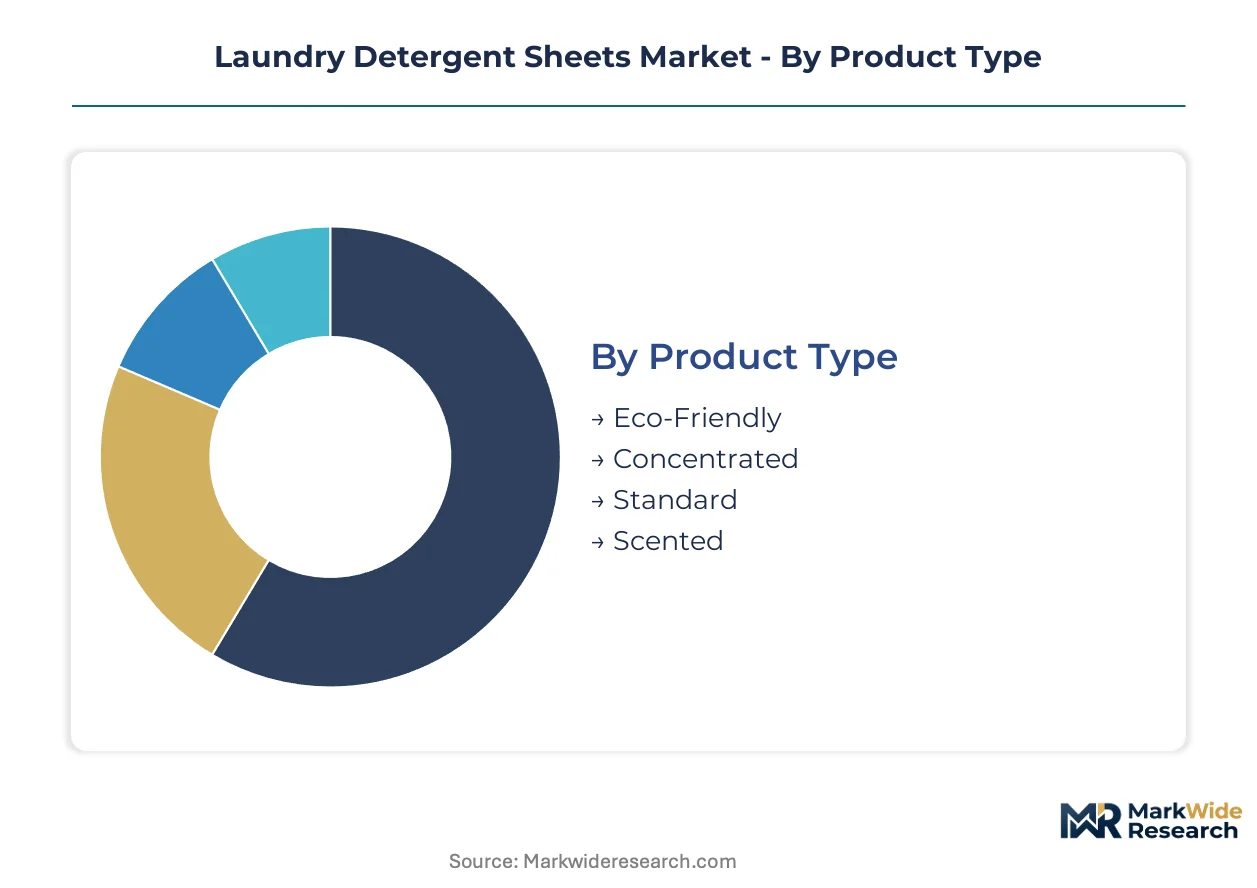
Segmentation in laundry detergent sheets reveals how formulation chemistry, distribution economics, and end-use requirements split margin capture across discrete customer pools. Manufacturers align R&D spend and channel investments against these fractures to defend pricing power.
Product Type:
Margin pools concentrate in certified biodegradable tiers where EPA Safer Choice and EU REACH compliance create scarcity premiums.
- Eco-Friendly:Phosphate-free surfactant systems with third-party biodegradability certification command shelf placement premiums in German and French supermarket networks. Hotel procurement teams in the United States now mandate these variants for corporate sustainability scorecards.
- Concentrated:High-surfactant films under 3 grams per sheet reduce logistics costs by over 90 percent versus liquid bottles. Dense urban households in Seoul and San Francisco metropolitan areas drive subscription adoption for space-constrained storage.
- Standard:Baseline formulations without certification premiums serve price-sensitive mass-market channels.
- Scented:Fragrance-encapsulated variants target residential preference differentiation with limited commercial uptake.
The dominant share belongs to Eco-Friendly, while Concentrated is closing the gap fastest.
End User:
Volume concentration splits between high-frequency institutional buyers and dispersed residential households with divergent procurement patterns.
- Households:Urban apartment dwellers in North America and Europe compress demand toward space-efficient formats with subscription replenishment models capturing lifetime value.
- Commercial Laundries:Hotels and linen services seek operational simplification and reduced storage footprints. Cold-water enzyme variants cut utility expenditures while meeting corporate sustainability targets in the United States and Germany.
- Hotels:Procurement mandates from major hospitality chains now require phosphate-free formulations, accelerating certified product adoption.
- Institutional Facilities:Nursing homes and healthcare linen services seek FDA-registered antimicrobial variants, opening premium pricing tiers beyond residential applications.
Commercial Laundries now outpace Households in volume growth velocity as procurement centralization accelerates.
Sales Channel:
Customer acquisition economics favor direct digital routes over retail slotting fees in high-density urban markets.
- Online Retail:Subscription platforms bypass traditional distribution costs with automated delivery cycles synchronized to wash frequency data. Seoul and San Francisco show highest conversion rates for annual commitment plans.
- Supermarkets:Established retail partnerships anchor European shelf presence where sustainability scorecards determine placement.
- Convenience Stores:South Korean chains integrate smart locker distribution for apartment complex penetration.
- Wholesale:Bulk procurement serves commercial laundries with centralized inventory management.
Online Retail holds the largest volume share, though Convenience Stores are expanding most quickly in Asian metropolitan clusters.
Formulation:
Water-soluble film engineering separates performance-grade tiers from commodity alternatives based on enzyme stability and temperature flexibility.
- Biodegradable:Full surfactant biodegradability data submission to ECHA extends development cycles but secures EU market access. German and French retailers require third-party verification for shelf placement.
- Liquid:Legacy format retains consumer familiarity though packaging volume disadvantages constrain growth.
- Powder:Pre-measured compression formats compete on cost but lack the logistics compression of film-based alternatives.
- Gel:Encapsulated surfactant systems occupy niche positioning with limited scale economics.
Biodegradable formulations dominate value capture, while Powder alternatives retain residual share in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized surfactant film manufacturing clusters in Germany, the United States, and South Korea supply formulation expertise and water-soluble polymer engineering to detergent sheet producers worldwide. These three countries anchor regional demand patterns through distinct regulatory environments and urban housing structures.
United States
EPA Safer Choice certification requirements from the Environmental Protection Agency now govern procurement decisions at major hotel chains and institutional laundries. Dense urban corridors in New York and San Francisco compress residential storage space, driving subscription adoption for pre-measured sheet formats. The Pacific Northwest cluster around Seattle shows highest conversion rates for annual commitment plans tied to carbon-neutral shipping claims.
Germany
EU REACH Annex XVII restrictions on phosphates and microplastics force full surfactant biodegradability disclosure to the European Chemicals Agency. The EU Green Deal's packaging waste reduction targets reshape retailer scorecards in Berlin and Munich supermarket networks. Baden-Württemberg's chemical engineering base supplies enzyme stabilization technology for cold-water soluble films.
South Korea
Seoul Capital Area apartment complexes concentrate demand for space-efficient laundry formats through government-backed green consumption incentives. The Ministry of Food and Drug Safety regulates antimicrobial variant labeling for healthcare applications. Convenience store chains integrate smart locker distribution networks for subscription bypass of traditional retail slotting fees.
United Kingdom
London metropolitan renters prioritize logistics-compressed formats with reduced packaging volume for small-footprint housing. The UK Environment Agency enforces biodegradable claims verification under overlapping EU-legacy and post-Brexit chemical disclosure frameworks. Manchester and Birmingham distribution hubs serve direct-to-consumer platforms targeting annual subscription commitments.
France
Île-de-France hospitality procurement teams mandate phosphate-free formulations for corporate sustainability scorecards. ANSM and CNIL oversight extends to antimicrobial healthcare variants and consumer data handling in subscription commerce. Lyon and Marseille retail networks apply sustainability scorecards that favor established players with dedicated regulatory affairs capacity.
Laundry Detergent Sheets Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the detergent sheet market. Concentrated surfactant film engineering and enzyme stabilization expertise concentrates among specialty chemical divisions of diversified conglomerates, while pure-play direct-to-consumer brands capture subscription economics through digital-native customer acquisition. Three archetypes dominate: multinational FMCG giants with retail shelf anchoring, subscription-first digital natives with sustainability positioning, and private-label contract manufacturers serving supermarket chains. Competitive moves center on portfolio diversification into antimicrobial healthcare variants and geographic expansion through regulatory compliance capacity.
Within the FMCG conglomerate tier, Henkel AG and Co. KGaA and Unilever PLC exemplify players leveraging established retail partnerships and dedicated regulatory affairs teams to secure European shelf placement. Among direct-to-consumer specialists, Tru Earth and Earth Breeze occupy positions defined by subscription retention mechanics and plastic-free packaging claims. LG Household and Health Care Ltd. represents the Asia-Pacific integrated player archetype with domestic market anchoring and export formulation supply.
| Leading Market Players |
|---|
| Kind Laundry |
| LG Household and Health Care Ltd. |
| Earth Breeze |
| Church and Dwight Co. Inc. |
| Unilever PLC |
| Tru Earth |
| Henkel AG and Co. KGaA |
| ECOS |
| Dizolve Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements with Malaysian and Indonesian palm-derived surfactant suppliers lock in both raw material access and price visibility for detergent sheet manufacturers navigating EPA Safer Choice compliance costs. These contracts insulate performance-grade tier producers from input volatility while compressing margins for value-grade competitors exposed to spot market swings.
Pricing Analysis
EPA Safer Choice certification dictates the pricing tier structure across the detergent sheet market, separating premium biodegradable formulations from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and enzyme concentration intensity. Cost compression in the value-grade tier is intensifying because palm-derived surfactant price volatility feeds directly into formulation costs. Commercial laundries and hotel procurement teams show lowest price sensitivity due to mandated sustainability compliance, while mass-market residential consumers in emerging channels exhibit highest elasticity.
Supply Chain Analysis
Inventory cycles stretching six to twelve months for water-soluble film substrates create working capital intensity that favors scaled producers. Manufacturing concentration centers on Germany, the United States, and South Korea for specialized surfactant film engineering and enzyme stabilization technology. Raw material dependencies include palm-derived surfactants from Southeast Asia, polyvinyl alcohol films from Japanese chemical suppliers, and protease enzymes from Danish biotechnology sources. Single-source vulnerability in PVA film supply creates structural risk for producers lacking qualified secondary vendors. Distribution runs through direct-to-consumer platforms and supermarket retail networks with divergent slotting fee economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement centralization among major hospitality chains and institutional laundry operators is shifting buyer power toward volume consolidators capable of mandating certified formulations. This fragmentation of purchasing authority across fewer large-scale decision-makers compresses supplier negotiation leverage.
For Market Incumbents: Shield market position by securing exclusive enzyme stabilization technology licensing from Baden-Württemberg chemical engineering clusters before patent cliffs expire. Backward integration into water-soluble film production reduces PVA supply vulnerability while capturing margin pools currently diverted to Japanese substrate suppliers. Prioritize EPA Safer Choice certification maintenance against emerging state-level packaging mandates that threaten shelf access. For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in European markets outside Germany create white-space opportunity for automated replenishment platforms targeting French and UK metropolitan renters. Direct-to-locker distribution partnerships with South Korean convenience chains offer the most penetrable geographic entry point. Antimicrobial healthcare variants for nursing home operators provide premium pricing tiers with limited incumbent competition. For Investors and Strategic Acquirers: Specialty chemical divisions with dedicated regulatory affairs capacity and ECHA submission track records represent the most defensible acquisition targets across the analysis window. Formulation chemist scarcity concentrates expertise among narrow talent pools in Germany and South Korea. Watch for FDA registration momentum in antimicrobial sheet variants as inflection indicator for healthcare segment viability.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Water Enzyme Formulation Development | Captures energy-conscious residential users and hotel sustainability targets in Germany and the United States. |
| Direct-to-Consumer Platform Launch | Bypasses supermarket slotting fees while capturing lifetime value through subscription retention mechanics. |
| Antimicrobial Variant FDA Registration | Opens premium pricing tiers for healthcare linen services and nursing home procurement channels. |
| Backward Integration into Film Manufacturing | Reduces PVA substrate supply vulnerability and captures margin pools from Japanese chemical suppliers. |
| EU REACH Compliance Capacity Expansion | Secures shelf placement in Berlin and Munich retail networks applying sustainability scorecards. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with detergent sheet brand managers, supermarket category buyers, hotel procurement directors, and formulation chemists; and secondary validation through EPA Safer Choice certified product databases, EU ECHA registration filings, customs trade records for water-soluble film imports, and SEC disclosures from listed household care conglomerates. Bottom-up demand modeling triangulated against top-down market sizing from production capacity assessments.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type tier, end-user segment, sales channel economics, and formulation chemistry complexity. CAGRs derived from segment-level growth rate assumptions weighted by regional regulatory enforcement intensity and urban housing density patterns. Forecast inputs incorporated cold-water enzyme adoption curves in residential segments and procurement mandate rollout timelines for commercial laundries.
Material uncertainties — regulatory timeline shifts for EU REACH Annex XVII amendments, palm oil price volatility from Southeast Asian supply disruptions, and liquid pod technology improvements — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification penetration rates and subscription commerce conversion benchmarks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Toilet Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Flatware Market
Household Items
Dosage Spoon Market
Household Items
Tablet Tissue Paper Market
Household Items
Electric Mop Market
Household Items
North America Robotic Pool Cleaner Market
Household Items
Washing Capsules Market
Household Items
US Air Purifier Market
Household Items
Commercial Lawnmower Market
Household Items
Turkey Cookware Market
Household Items
Global Buddhist Supplies Market
Household Items
North America Liquid Hand Soap Market
Household Items
Snow Blower Market
Household Items
Portable Car Vacuum Market
Household Items
Ceramic Travel Mug Market