
 Tablet Tissue Paper Market | 2026-2036
Tablet Tissue Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Tablet Tissue Paper Market Analytics
FSC chain-of-custody certification is unwinding the competitive landscape for tablet tissue paper, as major retail and hospitality procurement teams now mandate verified sustainable sourcing. Purcotton, LLC leverages its medical-grade cotton supply chain to dominate healthcare channel positioning. AoGrand anchors volume production through integrated nonwoven substrate operations in eastern China. Ningbo Riway Daily Necessities Co. Ltd competes on OEM flexibility, supplying private-label tablet formats to European distributors.
Tablet tissue paper denotes compact, dehydrated cellulose or cotton-based sheets that expand upon contact with water to yield usable wet wipes or facial tissues, typically compressed to diameters under three centimeters for portability. Manufacturers employ spunlace or airlaid bonding followed by mechanical compression to achieve dissolution-ready densities without compromising tensile strength upon rehydration. The biodegradable product type commands premium placement in hospitality amenity kits and airline passenger sets, while recycled grades occupy price-sensitive wholesale channels. Three-ply variants sustain higher per-unit margins in commercial end-user segments requiring durability during saturated use.
The EU Ecolabel and FDA cosmetic good manufacturing practice standards jointly govern product claims and substrate safety for tablet tissues sold into personal care applications. China's GB standards for disposable hygiene products, administered by SAMR, dictate microbial limits and labeling requirements for domestic manufacture and export certification. REACH compliance in Europe and state-level plastic reduction mandates in California and New York are converging to favor water-dispersible formats over conventional wet wipes. Stakeholders must monitor evolving compostability certification schemes and regional single-use material bans to align R&D pipelines with shifting procurement criteria.
Market Dynamics
Plastic packaging bans across the EU, California, and New York are compressing demand for conventional wet wipes and redirecting procurement budgets toward water-dispersible tablet formats that eliminate single-use plastic entirely.
Growth Catalysts
- EU Single-Use Plastics Directive:Hospitality chains across France, Germany, and Italy now mandate biodegradable amenity formats, eliminating plastic wipe sachets from guest rooms and airline passenger kits.
- Spunlace nonwoven advances:Mechanical compression bonding now achieves dissolution-ready densities without tensile strength loss upon rehydration, opening medical and cosmetic applications.
- Zhejiang manufacturing cluster:Contract manufacturers concentrated around Ningbo and Hangzhou capture economies of scale for both domestic Chinese consumption and export fulfillment to European distributors.
Market Restraints
- Cotton pulp input volatility:Medical-grade cotton supply chains face price pressure from pharmaceutical sector competition, squeezing margins for premium tablet tissue grades.
- REACH compliance friction:European chemical registration requirements create 12-18 month certification timelines for new substrate formulations, delaying product launches.
- Conventional wet wipe substitution:Lower-cost plastic-packaged alternatives retain shelf space in price-sensitive mass retail channels, particularly in Southeast Asian convenience stores.
Strategic Opportunities
- Underpenetrated US hospitality:Domestic hotel chains lag European counterparts in amenity kit conversion, creating first-mover positioning for FSC-certified tablet suppliers.
- Airline sustainability mandates:IATA carbon reduction commitments pressure carriers to eliminate plastic from passenger sets, favoring compact tablet formats that reduce weight and waste volume.
- Healthcare channel expansion:FDA cosmetic GMP standards enable tablet tissues to displace sterile gauze in pre-operative skin preparation protocols.
Industry Challenges
- FSC chain-of-custody certification timelines:Verified sustainable sourcing documentation requires 8-14 months to complete, blocking access to premium retail and hospitality procurement channels.
- Spunlace equipment capex intensity:Production lines capable of medical-grade substrate bonding require capital deployment that mid-tier manufacturers struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tablet Tissue Paper Market |
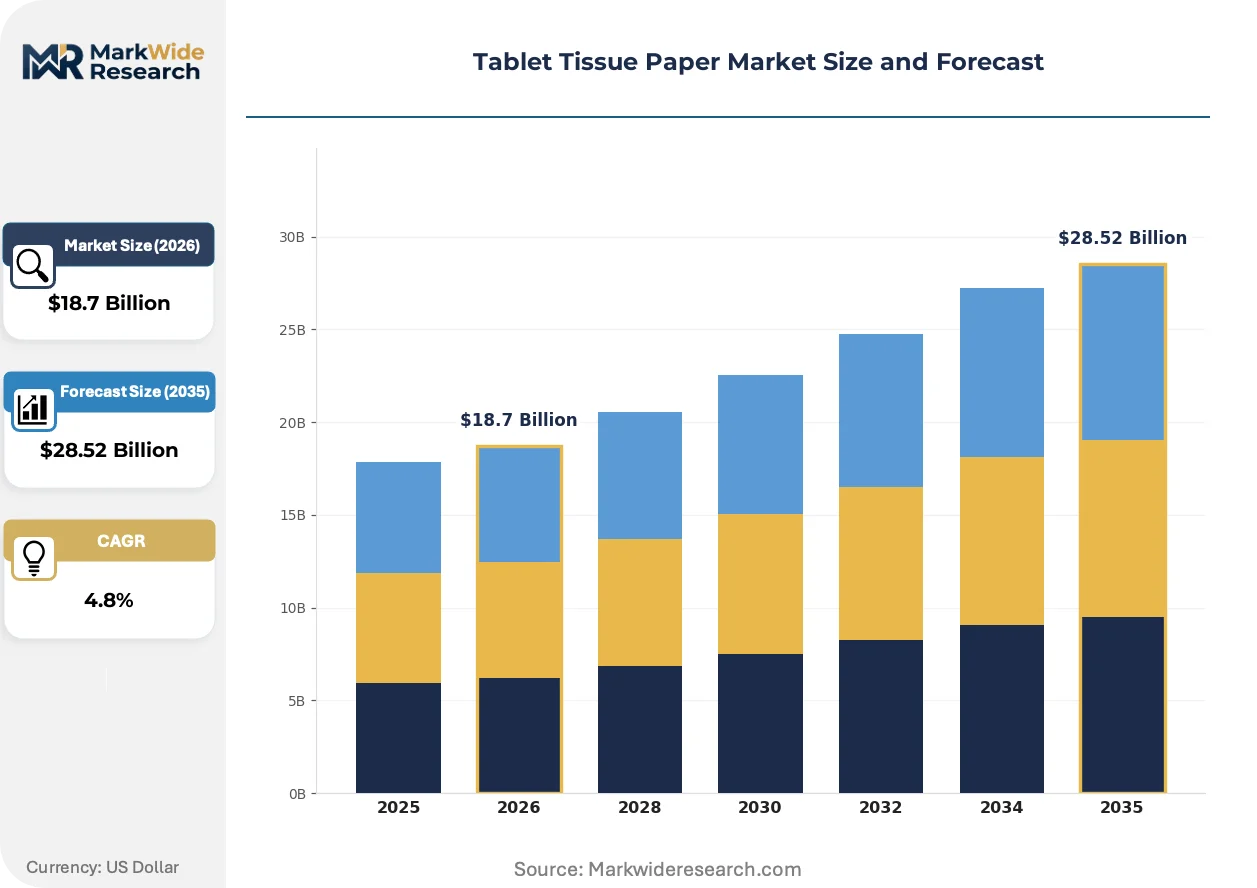
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Ply, Three-Ply, Biodegradable, Recycled End User: Household, Commercial, Healthcare, Hospitality Distribution Channel: Online, Supermarkets, Convenience Stores, Wholesale Packaging Type: Bulk, Retail Packs, Eco-Friendly, Single-Use |
| Companies Covered | Portawipes, Onrush Paper And Print (OPC) Pvt. Ltd., Purcotton, LLC, Adventure Wipe Company, AoGrand, Ningbo Riway Daily Necessities Co. Ltd, Hangzhou Lin'an Huasheng daily necessities Co. Ltd, Swaroop Industry, Smile Way Textile Manufacture Co. LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tablet Tissue Paper Market Evolving Landscape
Substrate engineering and regulatory compliance are converging to split the market between premium certified grades and commodity alternatives, with procurement teams rewriting vendor qualification criteria around verified sustainability credentials.
Mechanical compression technology is bifurcating tablet tissue production into two distinct quality tiers. High-pressure bonding systems now achieve densities exceeding 0.4 g/cm³ for medical applications requiring rapid dissolution without fiber residue. Hospitality procurement teams in the EU and UK are specifying these premium grades for guest amenities, while price-sensitive wholesale channels in Southeast Asia absorb lower-density variants that sacrifice rehydration speed for unit cost reduction.
REACH registration requirements for cellulose derivatives are tightening substrate safety documentation obligations for European personal care applications. The regulation now mandates full chemical characterization for compressed nonwovens marketed as cosmetic wipes, forcing reformulation of legacy binders and wetting agents. Manufacturers serving the German and French markets are accelerating substitution of synthetic additives with plant-derived alternatives to preempt compliance failures.
Airline procurement departments are consolidating supplier relationships around single-source tablet tissue contracts that bundle amenity kit assembly with waste reduction reporting. Carriers including those based in Singapore and the UAE now require vendors to document plastic elimination metrics as a contractual performance clause. This specification compression favors integrated manufacturers with in-house compression bonding and kit assembly capabilities over pure-play substrate suppliers.
Tablet Tissue Paper Market Segmentation
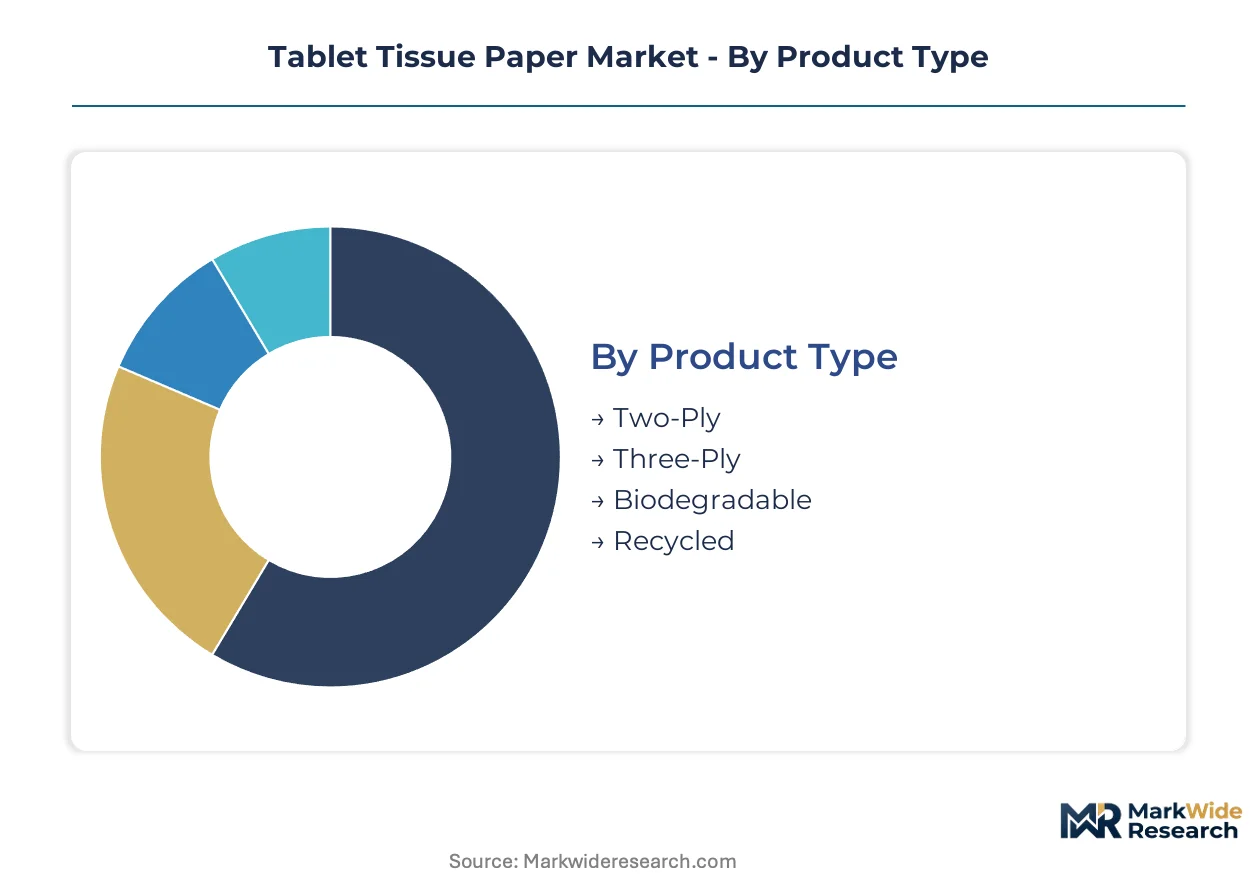
Tablet tissue paper segmentation reveals how procurement criteria diverge across price-sensitive wholesale channels and premium-certified hospitality programs. Compression density, substrate certification, and packaging format together determine vendor qualification and margin capture.
Product Type:
Margin pools concentrate in certified biodegradable grades where EU Ecolabel and FSC chain-of-custody documentation command procurement premiums.
- Biodegradable:Cellulose substrates bonded without synthetic wetting agents dissolve completely upon rehydration. EU hospitality chains in France, Germany, and Italy now mandate this grade for guest amenities, displacing conventional wet wipes under Single-Use Plastics Directive compliance deadlines.
- Three-Ply:Multi-layer compression achieves tensile strength above 15 N/cm² for saturated use in medical and cosmetic applications. Healthcare facilities in China's Zhejiang province specify this grade for pre-operative skin preparation protocols.
- Two-Ply:Lower-density compression suits price-sensitive household and travel retail segments across Southeast Asian convenience stores.
- Recycled:Post-consumer fiber content meets wholesale channel cost targets in North American mass retail, though rehydration speed trails virgin cellulose grades.
Biodegradable holds installed capacity. Three-Ply is rotating up the share rankings.
End User:
Volume concentrates in commercial procurement programs where sustainability reporting requirements compress supplier shortlists.
- Hospitality:Hotel chains and airlines specify compact tablet formats to eliminate plastic packaging from guest amenities and passenger kits. Singapore and UAE carriers now bundle waste reduction metrics into supplier contracts.
- Healthcare:FDA cosmetic GMP compliance enables displacement of sterile gauze in pre-operative protocols, with Purcotton leveraging medical-grade cotton supply chains for channel positioning.
- Commercial:Office and institutional buyers absorb mid-tier recycled grades through wholesale distributors.
- Household:Direct-to-consumer online channels drive trial of novelty formats, though repeat purchase rates lag commercial segments.
Hospitality holds installed capacity. Healthcare is rotating up the share rankings.
Distribution Channel:
Customer access patterns split between procurement team mandates in institutional segments and impulse purchase dynamics in retail.
- Wholesale:European distributors consolidate private-label tablet sourcing around Ningbo and Hangzhou manufacturers, capturing economies of scale for hospitality and airline fulfillment.
- Online:Direct-to-consumer platforms enable subscription models for household trial and replenishment, particularly in underpenetrated US markets.
- Supermarkets:Mass retail shelf space favors established wet wipe brands, limiting tablet tissue visibility outside certified organic product sets.
- Convenience Stores:Southeast Asian chains retain price-focused conventional wet wipes, with tablet formats confined to airport and transit hub locations.
Wholesale holds installed capacity. Online is rotating up the share rankings.
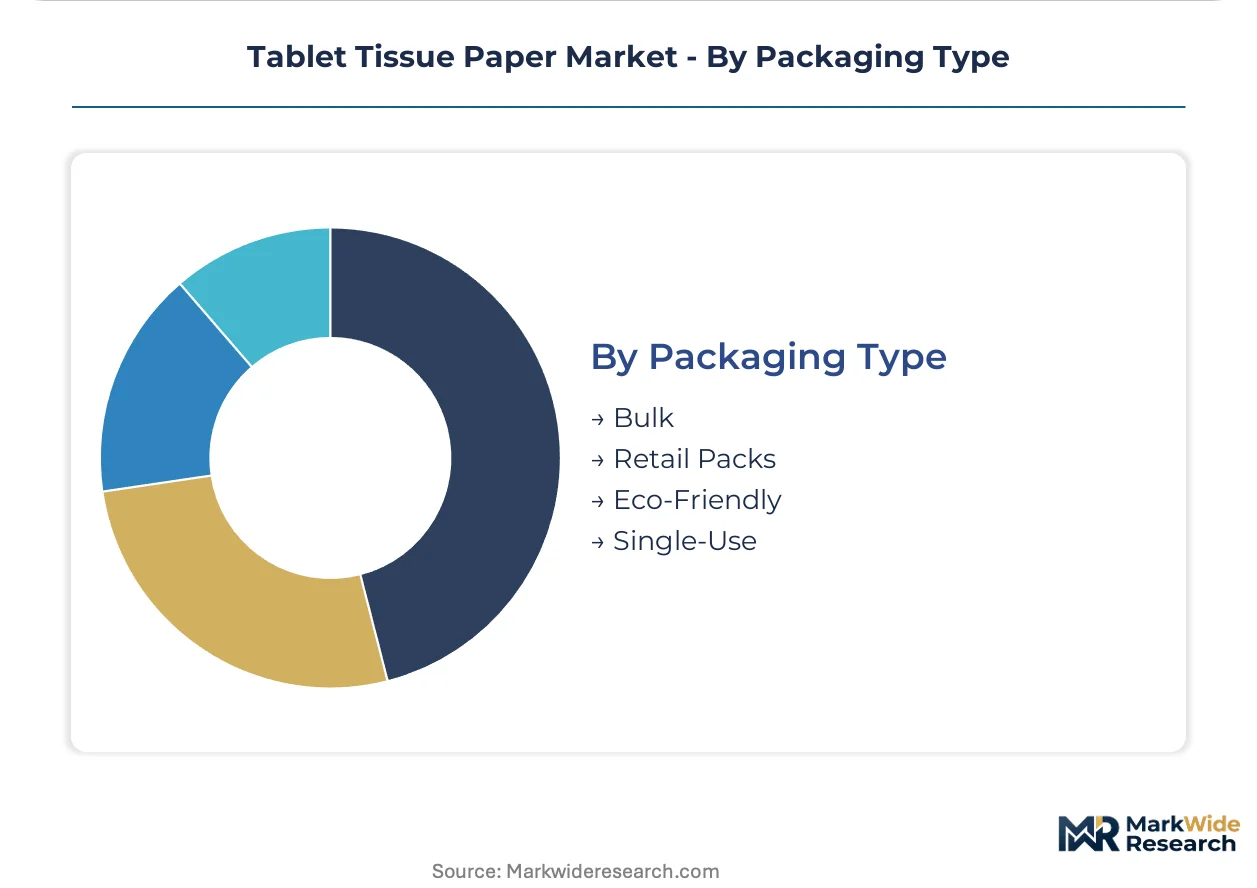
Packaging Type:
Format economics track the tension between logistics efficiency and single-use elimination mandates.
- Eco-Friendly:Compostable wrappers and bulk dispensers satisfy EU Ecolabel and corporate sustainability procurement criteria, commanding placement in premium hospitality amenity kits.
- Bulk:Refill formats reduce per-unit packaging cost for high-volume healthcare and commercial installations.
- Retail Packs:Branded multi-count configurations target household trial through supermarket and online channels.
- Single-Use:Individual tablet sachets persist in airline passenger sets and travel retail, though substrate innovation now enables plastic-free film alternatives.
Eco-Friendly holds installed capacity. Bulk is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Ningbo-Zhoushan anchors Asia-Pacific tablet tissue paper logistics, processing raw cellulose imports and finished exports for Zhejiang manufacturing clusters serving European and North American hospitality procurement teams.
China
Zhejiang province manufacturers cluster around Hangzhou and Ningbo to capture spunlace nonwoven economies of scale for both domestic airline amenity programs and export fulfillment. SAMR administers GB standards for disposable hygiene products, dictating microbial limits and labeling requirements for domestic manufacture and export certification. Ningbo contract fabricators now supply private-label tablet formats to European distributors under compressed lead times.
United States
Domestic hotel chains lag European counterparts in amenity kit conversion, creating positioning opportunities for FSC-certified tablet suppliers targeting sustainability procurement mandates. FDA cosmetic good manufacturing practice standards govern substrate safety claims for personal care applications. California and New York state-level plastic reduction mandates are converging to favor water-dispersible formats over conventional wet wipes in hospitality and travel retail channels.
Germany
REACH registration requirements for cellulose derivatives tighten substrate safety documentation obligations for European personal care applications, mandating full chemical characterization for compressed nonwovens marketed as cosmetic wipes. ECHA enforcement timelines create 12-18 month certification delays for new substrate formulations. Frankfurt and Munich-based hospitality procurement teams now specify biodegradable tablet grades under corporate sustainability frameworks.
France
EU Single-Use Plastics Directive compliance deadlines are eliminating plastic wipe sachets from Paris-based hotel chain guest rooms and Air France passenger kits. ANSM oversees cosmetic product safety claims for tablet tissues marketed with medical-adjacent positioning. Lyon and Marseille hospitality clusters are consolidating supplier relationships around single-source contracts bundling amenity kit assembly with waste reduction reporting.
Singapore
Changi Airport transit retail and Singapore Airlines procurement departments specify compact tablet formats to reduce weight and waste volume in passenger amenity programs. IATA carbon reduction commitments pressure carriers to eliminate plastic from passenger sets. Local distributors are consolidating private-label sourcing around Zhejiang manufacturers capable of FSC-certified production at scale.
Tablet Tissue Paper Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and channel access, producing a bifurcated structure where scale-driven fabricators serve mass hospitality contracts while boutique operators capture premium sustainability mandates. The vendor base fragments across three strategic archetypes: integrated nonwoven substrate producers, OEM-flexible contract manufacturers, and medical-grade cotton specialists. Dominant competitive moves include backward integration into spunlace equipment ownership and strategic partnerships with FSC-certified pulp suppliers to preempt procurement qualification delays.
Within the medical-grade cotton specialist tier, Purcotton, LLC exemplifies supply chain positioning that bridges pharmaceutical and personal care applications. Among Zhejiang-based fabricators, Ningbo Riway Daily Necessities Co. Ltd and Hangzhou Lin'an Huasheng daily necessities Co. Ltd occupy positions defined by OEM flexibility and proximity to export logistics infrastructure. AoGrand anchors volume production through integrated operations, representing the scale-driven archetype that captures economies of density in both domestic Chinese consumption and European distributor fulfillment.
| Leading Market Players |
|---|
| Portawipes |
| Onrush Paper And Print (OPC) Pvt. Ltd. |
| Purcotton, LLC |
| Adventure Wipe Company |
| AoGrand |
| Ningbo Riway Daily Necessities Co. Ltd |
| Hangzhou Lin'an Huasheng daily necessities Co. Ltd |
| Swaroop Industry |
| Smile Way Textile Manufacture Co. LTD |
| Others |
Value Network & Pricing Analysis
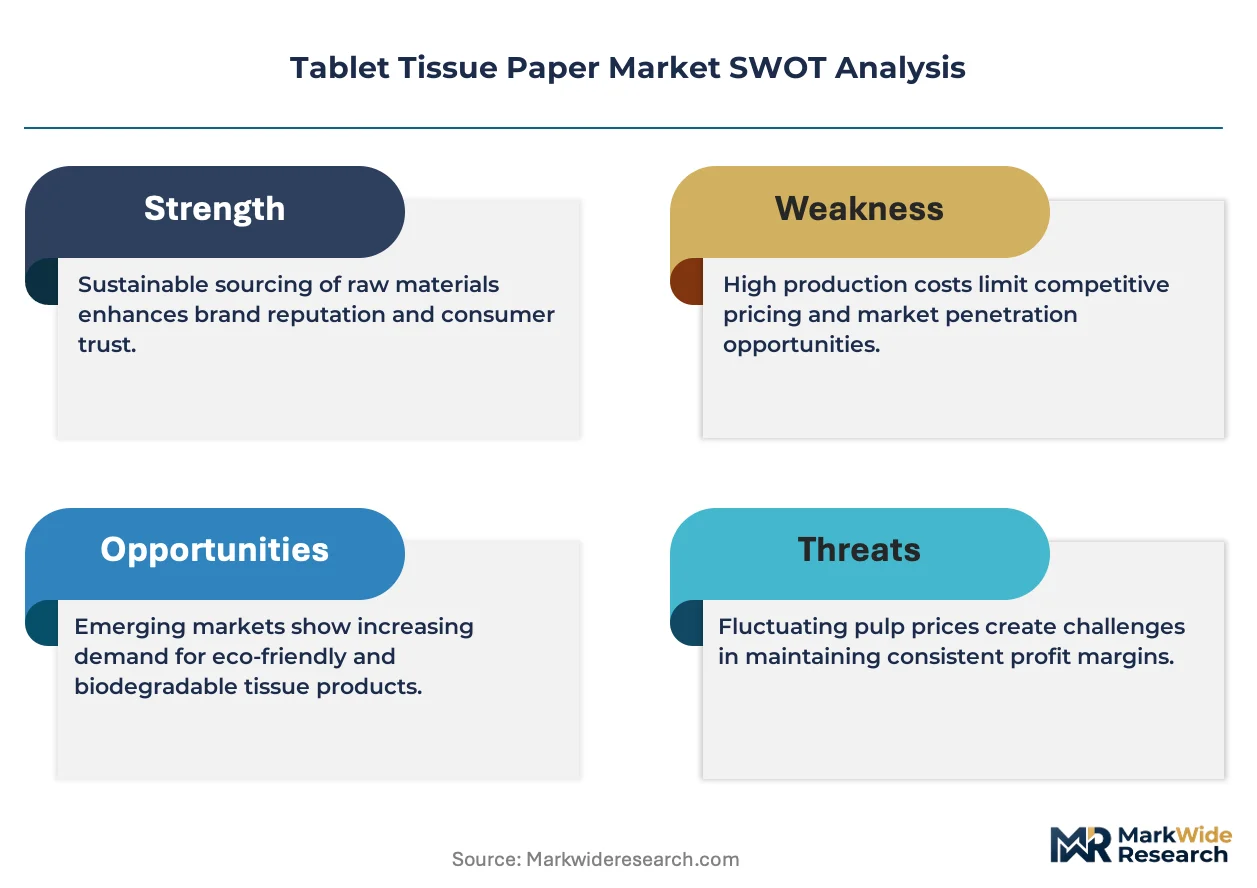
Spunlace equipment utilization rates above 85 percent in Zhejiang province compress unit economics for medical-grade tablet tissue, concentrating pricing power among fabricators with captive bonding lines while forcing toll-manufacturing competitors toward thinner margin recycled grades.
Pricing Analysis
Volume-discount tiering structures stratify across FSC-certified premium, standard biodegradable, and economy recycled cellulose levels. Certification grade and compression density together determine price positioning, with EU Ecolabel documentation commanding procurement premiums from hospitality chains. Cost compression in economy tiers intensifies because cotton pulp input competition from pharmaceutical buyers squeezes converter margins. Mass retail distributors in Southeast Asia exhibit highest price sensitivity, while airline procurement teams absorbing sustainability mandates show lowest.
Supply Chain Analysis
Ningbo-Zhoushan port congestion periodically chokes tablet tissue export flows to European distributors, amplifying lead time volatility during peak hospitality amenity procurement cycles. Manufacturing concentrates in China, with secondary fabricators in South Korea and Japan serving specialized medical-grade segments. Raw material inputs draw from dissolving pulp mills in Canada, bleached cotton linters from Central Asian suppliers, and plant-derived wetting agents from Malaysian oleochemical producers. Single-source vulnerability runs through Zhejiang compression bonding capacity. Distribution runs through wholesale distributors consolidating private-label sourcing for hospitality and airline fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tablet tissue procurement is hardening into a service-attach play as waste reduction reporting and kit assembly bundling expand faster than substrate commodity sales, rewarding vendors with integrated amenity program management capabilities.
For Market Incumbents: Fortify FSC chain-of-custody certification pipelines to preempt 8-14 month qualification delays blocking premium hospitality channel access. Backward integration into spunlace equipment ownership defends margin position against toll-manufacturing competitors facing cotton pulp cost volatility. Prioritize captive supply of medical-grade cotton to secure healthcare channel positioning against Purcotton's pharmaceutical supply chain leverage. For New Entrants and Emerging Players: Aftermarket replenishment subscription models for household direct-to-consumer segments represent an under-served service layer where incumbents lack digital-native fulfillment infrastructure. Target US hospitality chains lagging European sustainability conversion timelines with FSC-certified pilot programs bundled with plastic elimination metrics reporting. Pursue white-label airline amenity kit assembly partnerships as the most penetrable entry vector, leveraging Zhejiang contract manufacturing relationships for rapid scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated manufacturers combining compression bonding with kit assembly and waste reporting services, generating multi-year contractual visibility beyond commodity substrate sales. Long-term viability favors acquisition targets with established airline and hospitality procurement relationships, in-house spunlace capacity, and FSC-certified pulp supply agreements. Monitor IATA carbon reduction commitment enforcement timelines as the critical inflection signal for tablet tissue displacement of conventional wet wipes in passenger sets.| Strategic Initiative | Industry Significance |
|---|---|
| FSC Chain-of-Custody Certification | Verified sustainable sourcing documentation unlocks premium hospitality procurement channels under EU Single-Use Plastics Directive compliance. |
| Backward Integration into Spunlace Bonding | In-house compression equipment ownership captures medical-grade density capabilities and defends margin against toll-manufacturing competitors. |
| Airline Amenity Kit Assembly Partnerships | Bundled waste reduction reporting services convert commodity substrate sales into multi-year contractual relationships with IATA-committed carriers. |
| Healthcare Channel FDA Compliance Investment | Cosmetic GMP certification enables displacement of sterile gauze in pre-operative protocols with higher-margin three-ply tablet formats. |
| Direct-to-Consumer Subscription Launch | Digital-native replenishment models penetrate under-served US household segments with novelty trial and repeat purchase automation. |
Research Methodology
Operator-level perspectives from hospitality procurement directors, airline sustainability officers, Zhejiang contract manufacturing executives, and spunlace equipment suppliers anchored the qualitative base for this analysis. Primary interview findings triangulated against secondary validation from SAMR GB standard filings, EU Ecolabel certification databases, REACH registration disclosures via ECHA, and IATA sustainability commitment tracking. Customs records through Ningbo-Zhoushan port and hospitality distributor procurement databases provided trade flow corroboration. Bottom-up capacity utilization estimates and top-down demand segmentation were cross-checked for consistency.
Sensitivity analysis across compression density adoption curves, cotton pulp price volatility bands, and regulatory enforcement timelines shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type tier, end-use procurement channel, distribution format, and packaging sustainability grade. CAGRs were derived from installed capacity expansion schedules, airline fleet amenity conversion rates, and hospitality chain sustainability mandate penetration curves. Forecast inputs incorporated spunlace equipment deployment pipelines, FSC-certified pulp supply growth, and REACH registration backlog clearance rates.
Underlying assumptions cover EU Single-Use Plastics Directive enforcement consistency, Zhejiang manufacturing cluster capacity stability, and airline passenger traffic recovery trajectories, with deviation risk concentrated in cotton pulp pharmaceutical demand competition and REACH certification timeline extensions. Practitioners should keep alternative scenarios live as IATA carbon commitment enforcement intensity and US state-level plastic reduction mandate adoption patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Global Sports Bottle Market
Household Items
Smart Bathroom Products Market
Household Items
US Handheld Vacuum Cleaners Market
Household Items
Towel Warmers Market
Household Items
Laundry Detergent Sheets Market
Household Items
Infrared Sauna Heaters Market
Household Items
Washing Capsules Market
Household Items
Bladeless Neck Fan Market
Household Items
United Kingdom Air Purifier Market
Household Items
Global on-Premise-Laundry (OPL) Market
Household Items
India Air Purifier Market
Household Items
Pet Fur Remover Market
Household Items
Copper Water Bottle Market
Household Items
Smart Memory Foam Market
Household Items
Europe & UK Nonstick Cookware Market
Household Items
US Soap Dispenser Market