
 United Kingdom Homeware Market | 2026-2036
United Kingdom Homeware Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Homeware Market Analytics
Multi-sourced procurement from Asian manufacturing hubs is recalibrating how UK retailers manage inventory and margin structures. Dunelm Group leverages its vertically integrated textile mills to control quality and speed-to-market for curtains and bedding. IKEA sustains competitive pressure through its flat-pack logistics network and captive design studios. John Lewis differentiates via its employee-owned governance model and premium service reputation in homeware.
United Kingdom homeware encompasses durable and semi-durable goods for residential interior environments, including furniture constructed from engineered wood, solid timber, metal frames, and upholstered composites with specified foam densities and fabric abrasion ratings. These products serve functional, aesthetic, and comfort purposes across living, sleeping, dining, and storage applications. Kitchenware and textiles occupy mature volume positions with stable replacement cycles, while furniture commands disproportionate margin pools due to higher price elasticity and brand attachment. The online distribution channel captures the fastest growth trajectory as digital-native shoppers expect augmented reality visualization and next-day delivery.
The UK's Furniture and Furnishings (Fire Safety) Regulations, enforced by local trading standards authorities, mandate specific ignition resistance standards for domestic upholstered products. BSI kitemark certification and EU-originated REACH chemical compliance protocols further constrain material sourcing and finishing processes for manufacturers selling into Britain. Stakeholders must monitor evolving post-EU product safety divergence, carbon border adjustment mechanisms, and consumer duty regulations from the Financial Conduct Authority that increasingly govern retail payment practices. The decisive variable ahead lies in whether domestic retailers accelerate backward integration into European manufacturing or deepen reliance on Far Eastern supply chains with extended inventory risk.
Market Dynamics
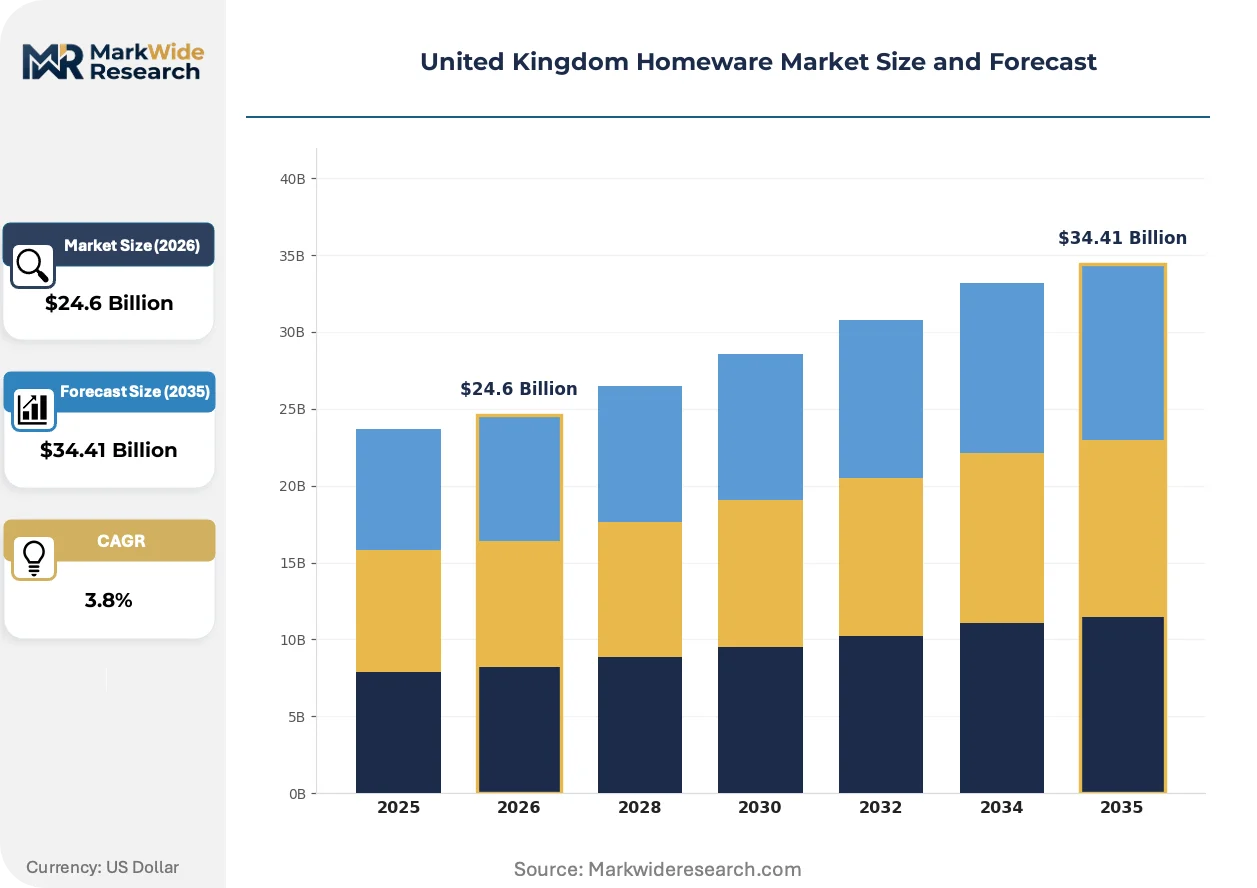
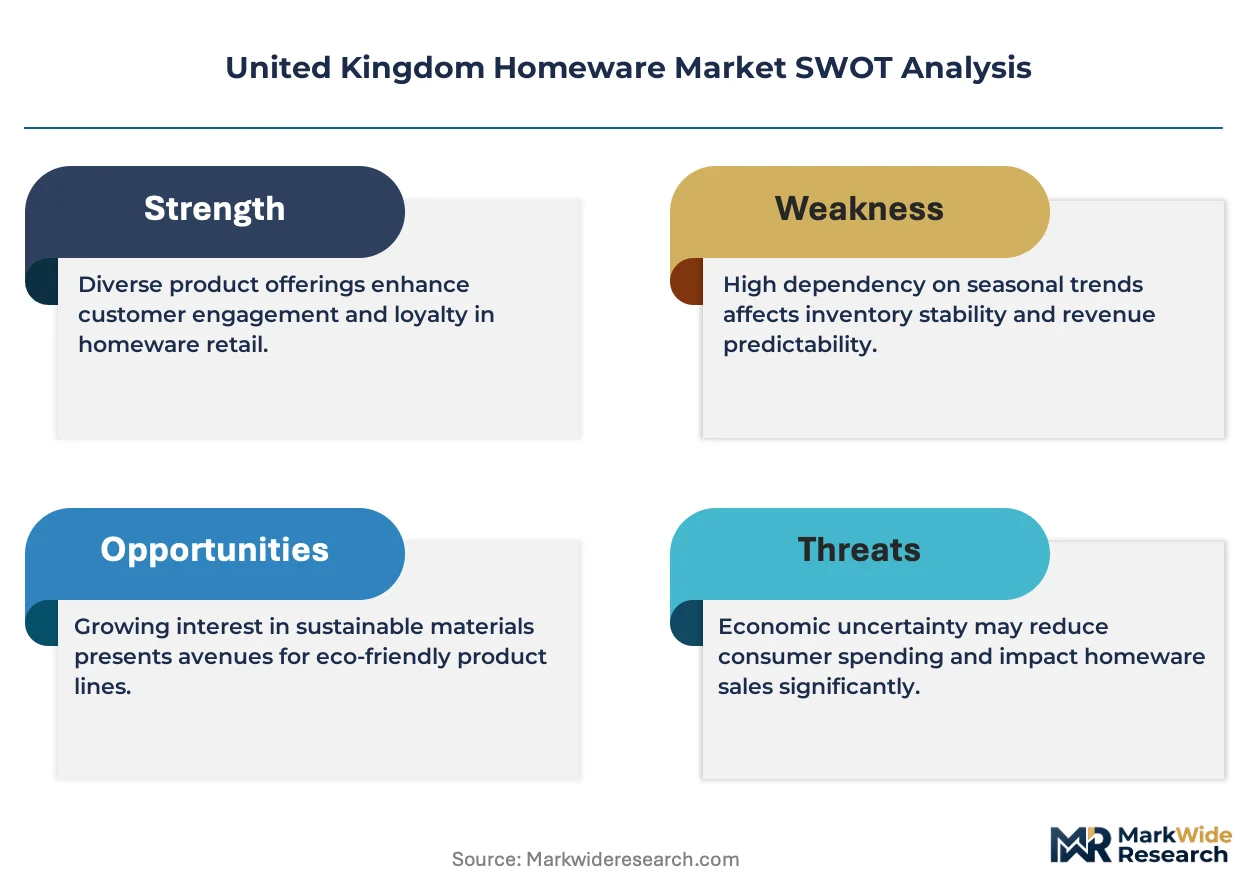
The UK's Furniture and Furnishings (Fire Safety) Regulations are compressing product development timelines while Asian supply chain concentration forces inventory risk onto domestic retailers. These dual pressures are restructuring margin allocation across the value chain.
Growth Catalysts
- Regulatory harmonization pressure:Post-EU divergence creates demand for UK-specific compliance consulting services. Trading standards authorities enforce stricter ignition resistance testing for upholstered goods.
- Digital-native buyer expansion:Augmented reality visualization tools reduce return rates for furniture purchases. Younger households in Greater London adopt these technologies fastest.
- Carbon border adjustment anticipation:Importers accelerate near-shoring discussions with European manufacturers. This reshapes procurement geography before formal mechanisms activate.
Market Restraints
- Container shipping rate volatility:Far Eastern supply dependence exposes margins to freight cost swings. Inventory carrying costs spike during port congestion events.
- REACH chemical compliance burden:EU-originated substance restrictions limit finishing process options. UK manufacturers face dual registration requirements post-Brexit.
- Engineered wood substitution threat:Solid timber commands premium positioning but faces price competition from particleboard alternatives. Sustainability claims partially offset this pressure.
Strategic Opportunities
- South East underpenetration:High disposable income households in Surrey and Kent show below-average Dunelm penetration relative to London. Specialty retailers capture this gap.
- Circular economy incentives:Extended producer responsibility frameworks for furniture waste create refurbishment service openings. Trading standards authorities pilot take-back scheme recognition.
- AI-driven demand forecasting:Machine learning tools converge with supplier API integration. This compresses replenishment cycles for seasonal textile collections.
Industry Challenges
- Fire safety certification bottlenecks:BSI kitemark testing capacity constrains new product launches. Laboratories report twelve-week backlogs for upholstered furniture assessments.
- Legacy ERP integration friction:Wholesale buyers demand EDI connectivity that smaller textile mills lack. Middleware investments strain mid-tier supplier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Homeware Market |
| Market Size in 2026 | $24.6 Billion |
| Market Size in 2035 | $34.41 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Kitchenware, Textiles, Decor End User: Households, Hospitality, Retailers, Online Shoppers Distribution Channel: Online, Brick-and-Mortar, Wholesale, Direct Sales Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Dunelm Group, IKEA, Argos, DFS Furniture, Wayfair, The Range, B&M, John Lewis, TK Maxx, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Homeware Market Evolving Landscape
Technology convergence and regulatory recalibration are compressing traditional competitive advantages in UK homeware. Retailers must rebuild capabilities around speed and compliance rather than scale alone.
Augmented reality visualization software is unifying the online and physical shopping experience for furniture buyers. Digital-native consumers in Greater London now expect room-placement simulation before purchase commitment. This capability is compressing the advantage of showroom-based retailers and forcing investment in 3D asset libraries.
The UK's post-EU product safety divergence is creating parallel compliance tracks for upholstered goods. Trading standards authorities enforce Furniture and Furnishings (Fire Safety) Regulations with stricter local interpretation than EU equivalents. Manufacturers serving both markets face duplicated testing costs, with smaller exporters most exposed to margin compression.
Subscription-based textile refresh models are displacing traditional ownership patterns among urban renters. Young professionals in Manchester and Bristol trade upfront purchase for seasonal linen and curtain rotations. This behavior concentrates in furnished rental markets where customization desire meets temporary residency constraints.
United Kingdom Homeware Market Segmentation
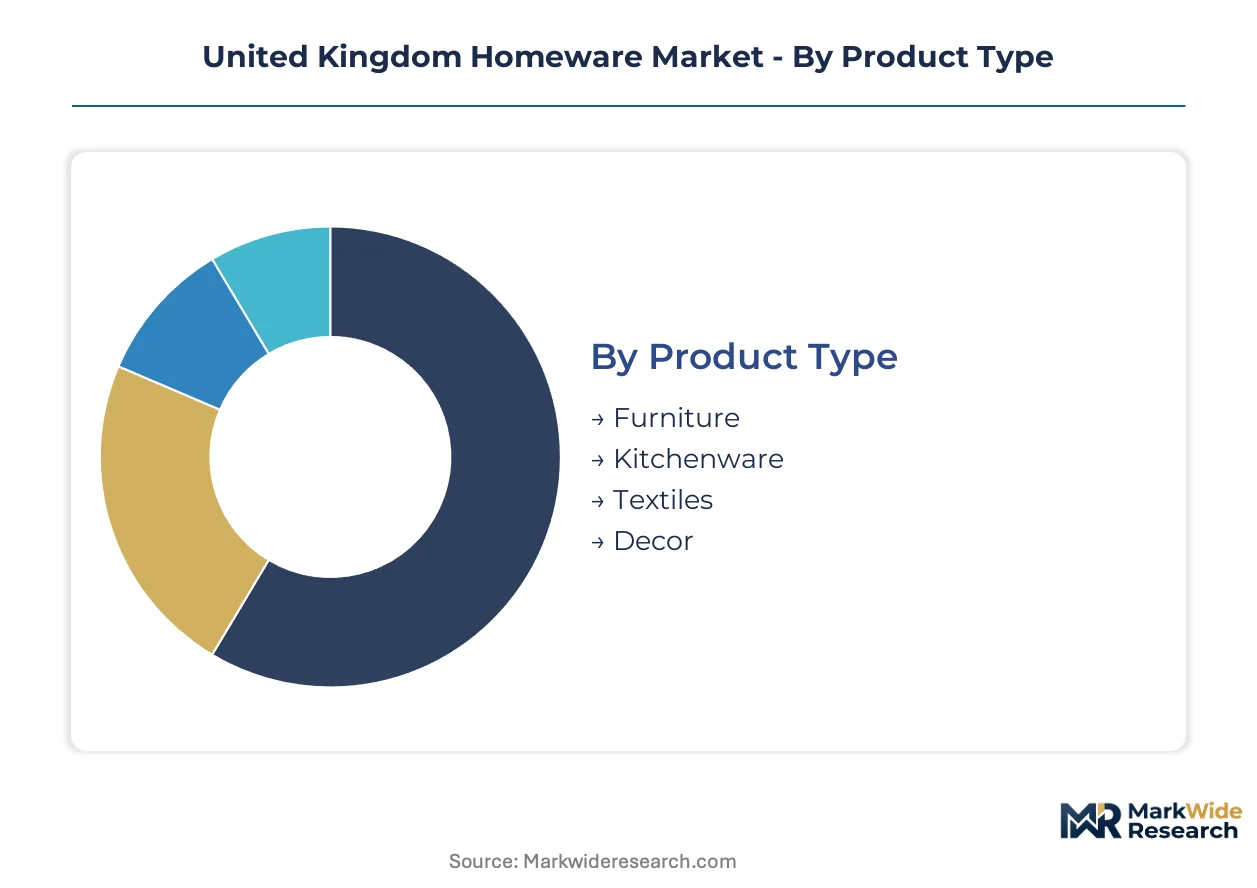
Segmentation in UK homeware reveals how regulatory burden and channel economics reshape competitive boundaries. Different product categories carry divergent compliance costs, while distribution mode determines margin capture and inventory risk allocation.
Product Type:
Furniture and Furnishings (Fire Safety) Regulations impose tiered certification requirements across this category, with upholstered goods facing stricter ignition resistance testing than hard surfaces.
- Furniture:Constructed from engineered wood, solid timber, metal frames, and upholstered composites with specified foam densities. Demand concentrates in Greater London and the South East, where housing density and disposable income support higher spending on statement pieces. Trading standards authorities enforce twelve-week BSI kitemark backlogs that constrain new product launches.
- Textiles:Comprises curtains, bedding, and soft furnishings with specified fabric abrasion ratings. Dunelm Group leverages vertically integrated textile mills to control quality and speed-to-market for these products. REACH chemical compliance protocols limit finishing process options for UK manufacturers.
- Kitchenware:Mature volume position with stable replacement cycles driven by wear-and-tear obsolescence.
- Decor:Lower regulatory burden enables faster design refresh cycles and seasonal collection turnover.
Leading the category by volume: Kitchenware. Growing fastest: Furniture.
End User:
Customer type determines purchasing frequency, basket composition, and sensitivity to delivery speed versus tactile evaluation.
- Households:Primary demand driver with replacement cycles tied to housing transactions and life-stage transitions. Augmented reality visualization tools reduce return rates for furniture purchases among digital-native segments.
- Online Shoppers:Expect room-placement simulation and next-day delivery. Younger households in Greater London adopt these technologies fastest, compressing the advantage of showroom-based retailers.
- Hospitality:Bulk procurement with durability specifications and fire safety certification requirements.
- Retailers:Wholesale buyers demand EDI connectivity that smaller textile mills lack, creating middleware investment burdens.
Households dominate absolute spend. Online Shoppers are expanding most quickly.
Distribution Channel:
Channel selection dictates working capital intensity and exposure to container shipping rate volatility from Far Eastern supply dependence.
- Online:Captures the steepest expansion trajectory as digital-native shoppers expect augmented reality visualization and next-day delivery. This capability compresses replenishment cycles for seasonal textile collections.
- Brick-and-Mortar:Sustains advantage in tactile categories where fabric texture and furniture scale resist digital substitution. IKEA's flat-pack logistics network and captive design studios sustain competitive pressure here.
- Wholesale:Concentrates procurement volume for hospitality and retail trade buyers.
- Direct Sales:John Lewis differentiates via its employee-owned governance model and premium service reputation in this channel.
Brick-and-Mortar retains the largest transaction share. Online is gaining share fastest.
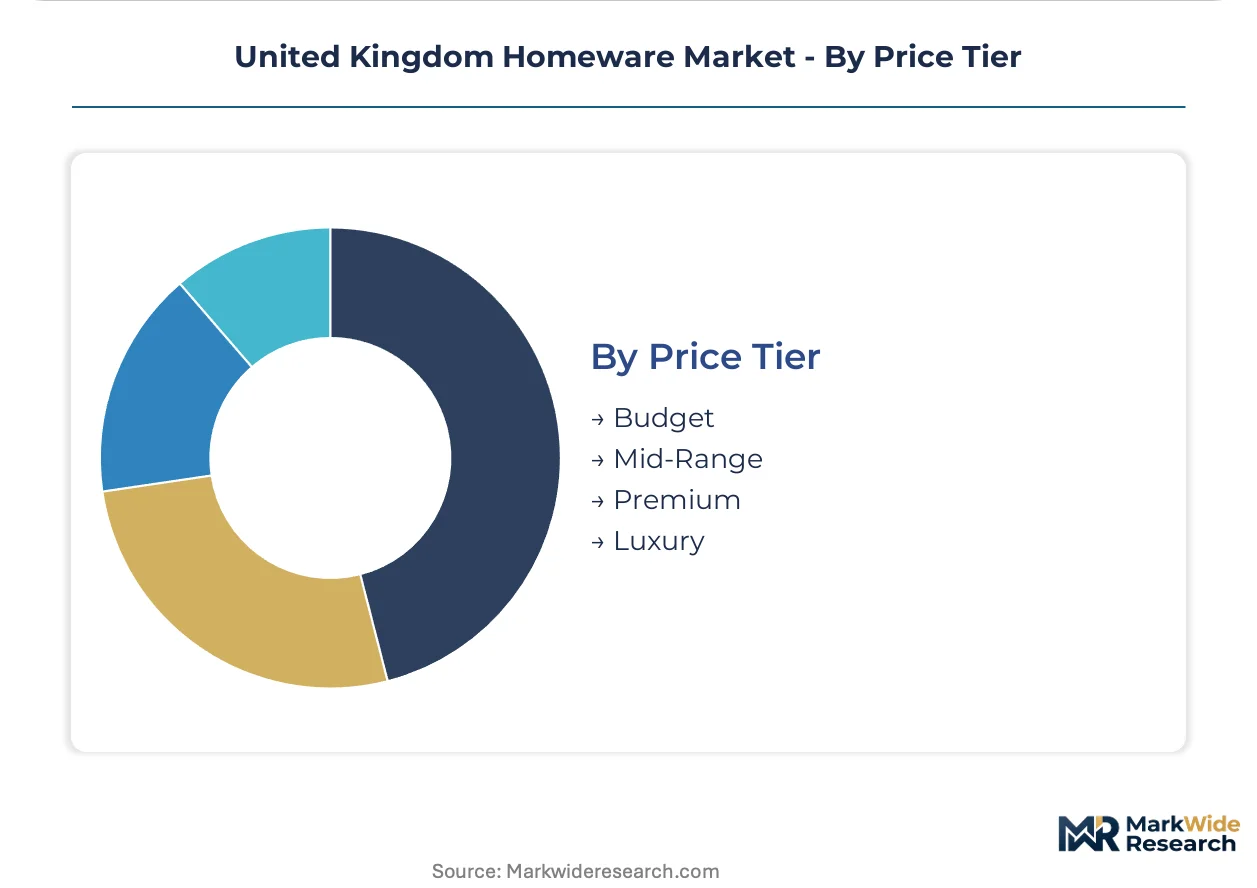
Price Tier:
Margin structure varies sharply across tiers, with premium positioning dependent on sustainability claims and solid timber substitution resistance.
- Premium:Commands disproportionate margin pools due to higher price elasticity and brand attachment. Sustainability claims partially offset engineered wood substitution pressure.
- Mid-Range:Balances quality perception with accessibility for urban renters in furnished markets.
- Budget:Faces particleboard alternative competition and compressed margins from freight cost swings.
- Luxury:Small volume base with heritage positioning and bespoke service requirements.
Mid-Range leads by unit volume. Premium shows the strongest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for homeware in the United Kingdom concentrates in Greater London and the South East, where housing density and disposable income support higher spending on interior goods. Regional disparities in compliance infrastructure and logistics access shape competitive positioning across England, Scotland, Wales, and Northern Ireland. Trading standards authorities in each jurisdiction enforce the Furniture and Furnishings (Fire Safety) Regulations with varying local interpretation.
Greater London and South East
Digital-native households in London adopt augmented reality visualization tools fastest, compressing showroom-based retail advantages. Trading standards authorities here maintain the strictest ignition resistance enforcement for upholstered goods. Croydon and Watford distribution clusters handle next-day delivery fulfillment for online shoppers across the capital.
Midlands
Engineered wood furniture manufacturing concentrates around Nottingham and Leicester with legacy textile mill infrastructure. Local trading standards offices face BSI kitemark testing backlogs that constrain new product launches. Birmingham retail corridors serve as logistics interchange points between northern production and southern consumption.
North England
Manchester and Leeds furnished rental markets drive subscription-based textile refresh demand among young professionals. REACH chemical compliance costs fall heavier here where smaller finishing operations lack dual-registration scale. Sheffield metal-frame furniture heritage supports specialty manufacturing for hospitality procurement.
Scotland
Edinburgh and Glasgow housing transaction volumes trigger replacement cycle peaks for furniture demand. Scottish trading standards operate distinct notification requirements for fire safety compliance that diverge from England-Wales practice. Aberdeen's energy sector salary base sustains premium homeware positioning despite national average gaps.
Wales and Northern Ireland
Cardiff and Belfast retail catchments show below-average Dunelm penetration relative to comparable English cities, creating specialty retailer openings. Post-EU product safety divergence forces dual-track compliance for manufacturers serving both UK and Republic of Ireland markets. Holyhead and Belfast ports face container shipping volatility from Far Eastern supply dependence.
United Kingdom Homeware Market Competitive Landscape
Backward integration into captive textile production dominates the current landscape as margin pressure from Asian supply chain concentration forces capability building. The vendor base organizes around three tiers: vertically integrated specialists with in-house mills, flat-pack logistics operators with design studio networks, and employee-governed premium service retailers. Two competitive moves define current positioning: M&A activity targeting regional specialty chains and API-based supplier integration for demand forecasting compression.
Among UK-based retailers, Dunelm Group and John Lewis exemplify divergent governance and supply chain archetypes. Dunelm occupies the vertically integrated position through captive textile mill control. John Lewis anchors the employee-owned tier with premium service reputation. IKEA, the Swedish flat-pack operator, sustains competitive pressure through logistics network density and captive design capabilities.
| Leading Market Players |
|---|
| Dunelm Group |
| IKEA |
| Argos |
| DFS Furniture |
| Wayfair |
| The Range |
| B&M |
| John Lewis |
| TK Maxx |
| Others |
Value Network & Pricing Analysis
Textile mill operatives in the East Midlands and West Yorkshire concentrate specialized finishing skills that compress labor-cost spreads between premium and budget tiers. REACH chemical compliance protocols and the UK's Furniture and Furnishings (Fire Safety) Regulations force dual registration burdens that widen pricing differentials based on certification investment rather than material quality alone.
Pricing Analysis
Extended warranty bundling separates John Lewis premium positioning from unbundled after-sales service at budget retailers. Three-tier pricing structure across premium, standard, and economy levels anchors on BSI kitemark certification status and solid timber versus engineered wood substitution. Price differentiation hinges on augmented reality visualization inclusion and next-day delivery guarantees. Cost compression in the budget tier intensifies because container shipping rate volatility from Far Eastern supply dependence erodes already-thin margins. Hospitality procurement teams show least price sensitivity due to durability specifications and bulk volume, while urban renters in furnished markets exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing qualification requirements from major UK retailers mandate approved supplier lists spanning China, Vietnam, and India for textiles, with Malaysia and Indonesia gaining share in engineered wood components. Raw material dependencies center on cotton fiber, foam densities for upholstery, and metal frame alloys. Single-source vulnerability concentrates in BSI kitemark testing laboratories where twelve-week backlogs constrain new product launches. Distribution runs through Croydon and Watford fulfillment clusters for Greater London next-day coverage, with Birmingham serving as northern interchange.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom Homeware Market functions as a cost-of-compliance story where the Furniture and Furnishings (Fire Safety) Regulations erect barrier-to-entry moats favoring incumbents with established testing relationships and captive laboratory access.
For Market Incumbents: Extend BSI kitemark testing capacity through laboratory partnerships or captive certification investment to compress twelve-week backlogs into competitive advantage. Deepen backward integration into European textile finishing to reduce REACH dual-registration exposure. Engineer wood substitution pressure from particleboard alternatives threatens solid timber premium positioning; sustainability claims and chain-of-custody certification defend margin pools. For New Entrants and Emerging Players: Begin with subscription-based textile refresh models targeting Manchester and Bristol furnished rental markets where temporary residency constraints meet customization desire. South East counties including Surrey and Kent show below-average penetration from established vertically integrated retailers, creating white-space for specialty positioning. Direct-to-consumer augmented reality visualization capability bypasses showroom infrastructure requirements and compresses capital barriers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive textile mill control and established trading standards relationships over asset-light digital pure-plays. Long-term viability rests on compliance infrastructure ownership rather than channel presence alone. Watch BSI testing capacity expansion announcements as inflection signal for new product launch velocity and market share redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into European Manufacturing | Reduces REACH dual-registration burden and carbon border adjustment exposure for UK retailers. |
| Captive BSI Kitemark Testing Investment | Compresses twelve-week laboratory backlogs into speed-to-market advantage for upholstered goods. |
| API-Based Supplier Integration | Machine learning demand forecasting converges with textile mill systems to shorten replenishment cycles. |
| Subscription Textile Refresh Launch | Urban renters in Manchester and Bristol trade ownership for seasonal rotation in furnished markets. |
| Augmented Reality Visualization Deployment | Digital-native Greater London households expect room-placement simulation before purchase commitment. |
Research Methodology
Independent corroboration across trading standards authority enforcement data, customs import records, and retailer procurement disclosures underwrites the qualitative findings. Primary interviews with textile mill operations directors, furniture category buyers at major retailers, trading standards enforcement officers, and logistics fulfillment managers combined with secondary validation from Companies House filings, British Retail Consortium reports, and BSI certification registry data. Bottom-up SKU-level demand modeling and top-down category expenditure triangulation anchored volume estimates.
Comparable historical reference periods spanning housing transaction cycles, regulatory enforcement intensity variations, and freight cost volatility episodes anchored the projection horizon. Segmentation dimensions modeled include product type, distribution channel, price tier, and regional housing density cluster. CAGRs derived from regression against disposable income growth, online penetration curves, and replacement cycle compression. Industry-specific inputs incorporated fire safety certification lag times and textile mill capacity utilization rates.
Underlying measurement precision varies by segment; online channel metrics carry tighter precision than hospitality procurement estimates due to data availability. Forecasts reflect assumptions regarding regulatory divergence trajectory, container shipping rate normalization, and carbon border adjustment implementation timing. Deviation in BSI testing capacity expansion or REACH-UKCA regulatory alignment would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Home & Garden
Electric Lawn Mower Market
Home & Garden
Flowerpots and Planters Market
Home & Garden
United States Lawn Care Market
Home & Garden
Flexible Garden Hoses Market
Home & Garden
North America Floral Gifting Market
Home & Garden
Garage Organization and Storage Market
Home & Garden
Japan Flower Pots Market
Home & Garden
Lawn and Gardening Consumables Market
Home & Garden
North America Flower Pots and Planters Market
Home & Garden
Outdoor Cooking Table Market
Home & Garden
Hedge Trimmer Market
Home & Garden
Asia-Pacific Bonsai Market
Home & Garden
Artificial Plants and Flowers Market
Home & Garden
US Garden Planter Market
Home & Garden
Global Hot Tub Market
Home & Garden
Landscaping Services Market