
 Digital Label Printers Market | 2026-2036
Digital Label Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Label Printers Market Outlook
China's expanding electronics manufacturing belt is reshaping regional demand for digital label printers. Zebra Technologies leverages its industrial printer portfolio to anchor North American logistics automation. Seiko Epson competes through precision micro-piezo inkjet heads that dominate high-resolution color label segments. HP Inc. extends its PageWide technology leadership into narrow-web converter installations across European packaging hubs.
Digital label printers are electrophotographic or inkjet-based systems that deposit pigmented inks or toners onto pressure-sensitive substrates at resolutions typically exceeding 600 dpi, enabling variable-data printing without plate changes. Their primary commercial purpose is to produce short-run, customized labels for products requiring frequent design changes, batch-specific coding, or regulatory traceability. Industrial printer configurations command the dominant installed base due to continuous-duty requirements in food processing and pharmaceutical packaging lines. Inkjet technology represents the fastest-expanding segment as single-pass aqueous and UV-curable systems displace thermal transfer in color applications. Direct thermal technology occupies a mature, cost-optimized niche within shipping and logistics end users where image permanence requirements remain limited.
FDA track-and-trace regulations and the EU Falsified Medicines Directive mandate unit-level serialization, forcing pharmaceutical manufacturers to replace legacy coding equipment with digital systems capable of integrating with enterprise verification databases. REACH compliance on substrate chemistries and evolving GB standards in China further constrain material choices, directing R&D investment toward compliant adhesive and ink formulations. Stakeholders must monitor how sustainability disclosure rules under the EU Green Deal and emerging state-level packaging laws in California reshape substrate specifications and end-of-life handling requirements for printed label waste streams.
Market Dynamics
Pharmaceutical serialization mandates are compressing replacement cycles across converter operations, forcing capital redeployment from analog flexographic assets toward digital systems capable of unit-level traceability integration.
Growth Catalysts
- EU Falsified Medicines Directive:Mandated unit-level serialization drives pharmaceutical manufacturers to retrofit packaging lines with digital printing systems capable of real-time verification database connectivity.
- Short-run flexible production:Brand owners in food and beverage sectors demand batch-specific customization without plate-change downtime, accelerating inkjet adoption among contract converters.
- Germany's industrial packaging corridor:Dense clustering of converter investments in the Rhine-Ruhr and Baden-Württemberg regions concentrates demand for narrow-web digital presses with sub-24-hour turnaround capabilities.
Market Restraints
- UV-curable ink cost volatility:Photoinitiator supply concentration in Chinese chemical manufacturing exposes European and North American printer operators to input price swings exceeding fifteen percent annually.
- Substrate compliance friction:REACH restrictions on adhesive chemistries limit compatible labelstock availability, forcing reformulation cycles that extend qualification timelines by six to nine months.
- Thermal transfer substitution:Mature direct thermal technology retains cost advantage in monochrome logistics applications, capping color digital penetration in shipping label segments.
Strategic Opportunities
- India's electronics manufacturing expansion:PLI scheme incentives for smartphone and component assembly are creating unmet demand for serialized component labels in Karnataka and Tamil Nadu industrial zones.
- EU Green Deal packaging rules:Emerging sustainability disclosure mandates and extended producer responsibility frameworks favor digital systems enabling on-demand production that minimizes label waste from obsolescence.
- Cloud-based print management convergence:Integration of ERP-connected workflow software with single-pass inkjet hardware creates service-revenue streams beyond equipment sales for system vendors.
Industry Challenges
- Color management specialist scarcity:Converter operations face recruitment gaps for technicians capable of calibrating ICC profiles across aqueous, UV, and toner-based digital systems.
- Legacy MES integration complexity:Pharmaceutical packaging lines require seamless data handoff between digital printers and existing manufacturing execution systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Label Printers Market |
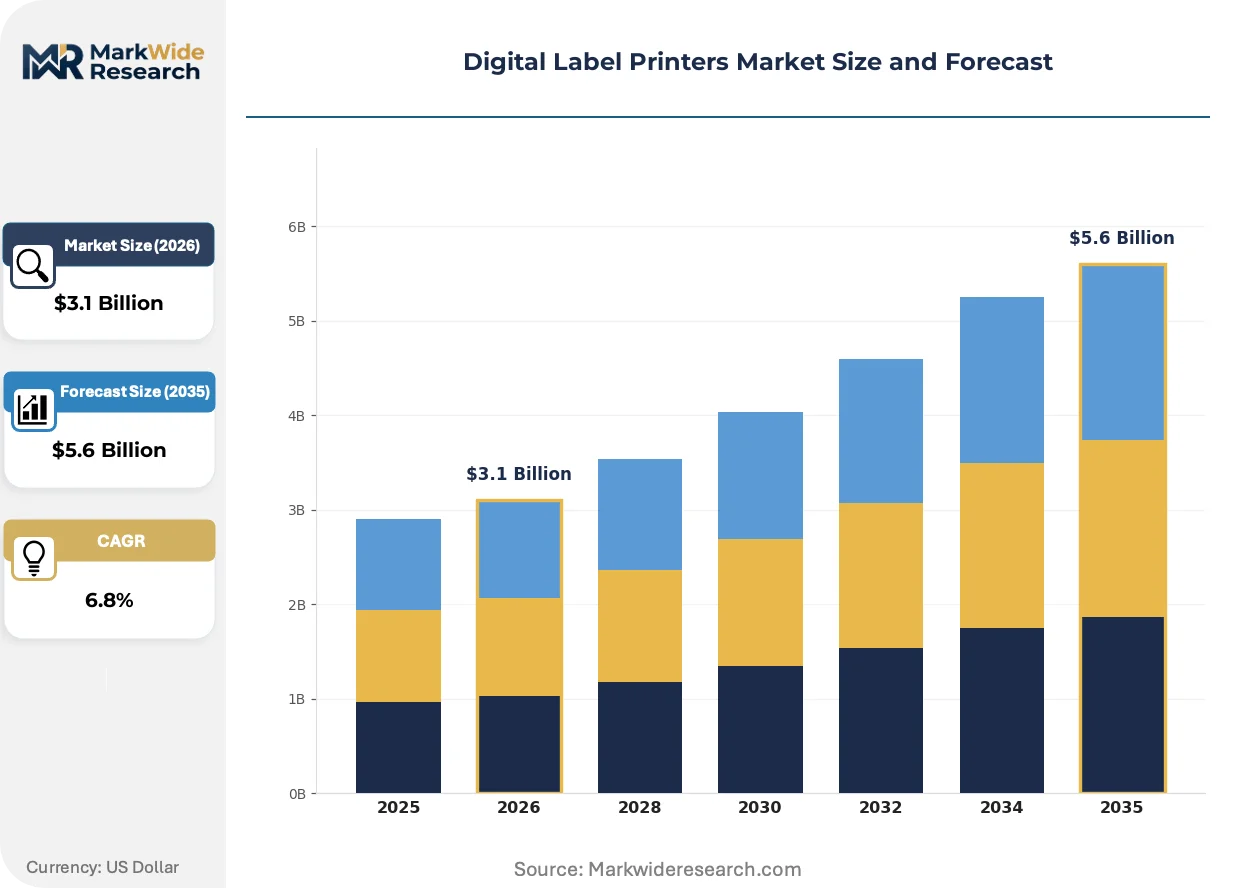
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.6 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desktop Printers, Industrial Printers, Portable Printers, High-Speed Printers Technology: Inkjet, Laser, Thermal Transfer, Direct Thermal Application: Food & Beverage, Pharmaceuticals, Retail, Electronics End User: Manufacturers, Distributors, Retailers, Logistics |
| Companies Covered | Zebra Technologies, Brother Industries, Seiko Epson, Avery Dennison, SATO Holdings, TSC Auto ID Technology, HP Inc., Primera Technology, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Label Printers Market Strategic Shifts
Single-pass aqueous inkjet architectures are compressing total cost of ownership calculations for mid-volume converters, while regulatory serialization requirements and sustainability disclosure rules simultaneously reshape equipment specifications and buyer evaluation criteria.
Single-pass UV inkjet systems with fixed-array piezo printheads are rendering obsolete multi-pass scanning architectures in narrow-web label production. Pharmaceutical contract packagers in Switzerland and Germany are adopting these configurations to meet EU Falsified Medicines Directive throughput requirements. The technology is eliminating mechanical complexity and maintenance intervals that previously constrained uptime guarantees in 24-hour packaging operations.
REACH authorization procedures for photoinitiator and monomer chemistries are tightening substrate compatibility windows for UV-curable digital inks. Converter operations must now validate alternative adhesive formulations that maintain tack performance under modified curing energy profiles. German and French packaging hubs are experiencing the most acute qualification delays as ECHA substance evaluation timelines extend beyond original equipment depreciation schedules.
Brand owners are consolidating label procurement across fewer converter relationships while demanding variable-data capabilities that previously required multiple supplier contracts. This concentration is compressing converter margins and accelerating capital equipment refresh cycles in Italy and Spain where fragmented supplier bases persist. Food and cosmetics verticals exhibit the most pronounced consolidation, with multinational manufacturers reducing approved vendor lists by forty to sixty percent over three-year horizons.
Digital Label Printers Market Segmentation
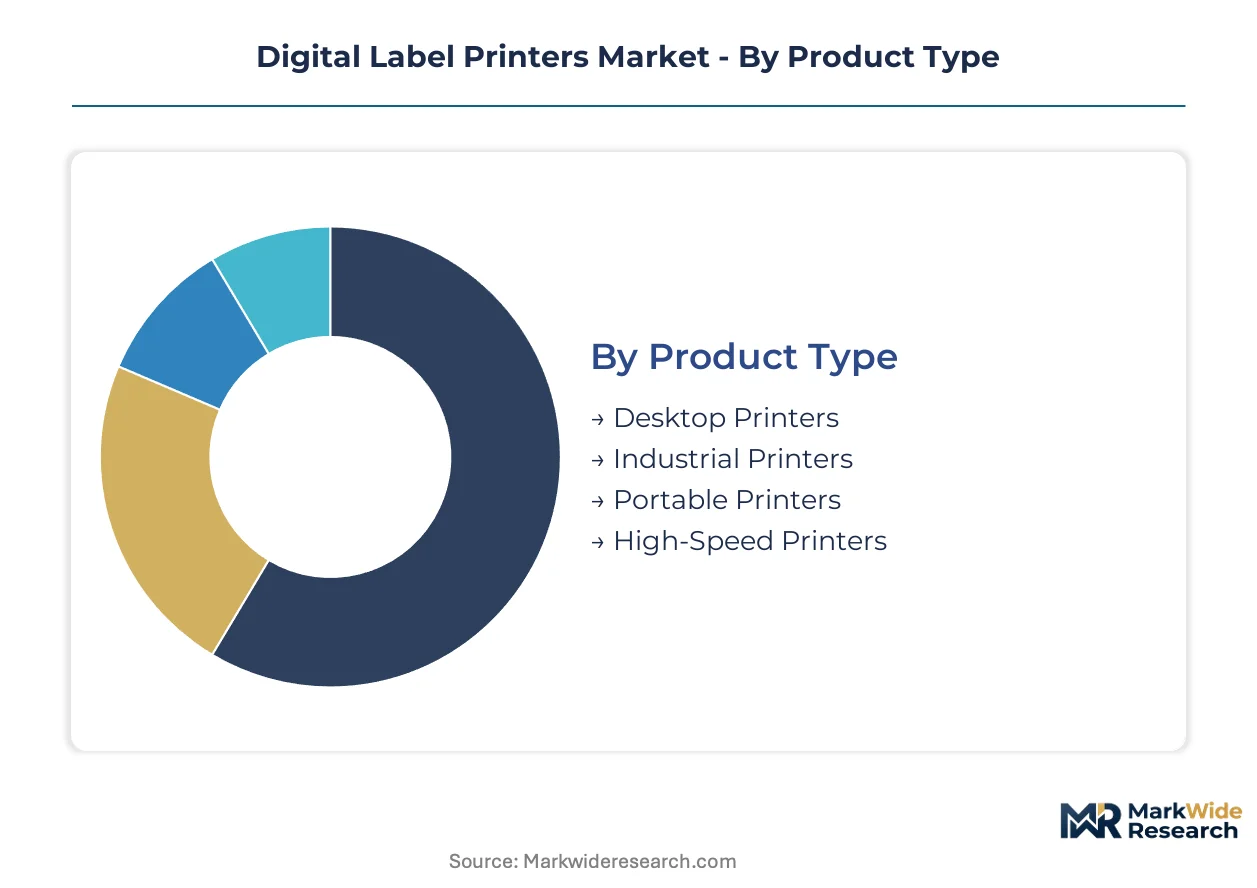
Segmentation reveals how pharmaceutical serialization mandates and short-run production economics concentrate demand across equipment tiers and technology platforms. Understanding these splits exposes where converter capital deployment and regulatory compliance intersect most intensely.
Product Type:
End-use requirements span from low-volume office environments to continuous-duty packaging lines, creating distinct equipment tiers with divergent margin profiles and replacement cycles.
- Industrial Printers:Continuous-duty electrophotographic and inkjet systems engineered for 24-hour pharmaceutical and food processing operations. Demand concentrates in Germany's Rhine-Ruhr packaging corridor where EU Falsified Medicines Directive compliance mandates real-time serialization throughput.
- Desktop Printers:Compact thermal transfer and direct thermal units serving prototype labs and small-batch cosmetics operations. Procurement is accelerating among Italian and Spanish contract converters seeking sub-500-unit production flexibility without plate-change overhead.
- Portable Printers:Battery-powered mobile units for field service and warehouse floor applications.
- High-Speed Printers:Single-pass inkjet architectures exceeding 150 meters per minute for beverage bottling lines.
The dominant share belongs to Industrial Printers, while Desktop Printers are closing the gap fastest.
Technology:
Print engine selection determines substrate compatibility, color capability, and total cost of ownership across regulatory and commercial use cases.
- Inkjet:Piezoelectric drop-on-demand and continuous inkjet systems deposit aqueous or UV-curable inks at resolutions exceeding 600 dpi. Swiss and German pharmaceutical packagers are adopting single-pass fixed-array architectures to meet EU Falsified Medicines Directive throughput mandates.
- Thermal Transfer:Resin and wax-resin ribbon systems dominate monochrome logistics labeling where image permanence requirements remain limited.
- Laser:Electrophotographic toner fusion enabling metallic and security substrates for high-value cosmetics.
- Direct Thermal:Chemically treated substrates activated by thermal printheads, retaining cost advantage in shipping applications.
Inkjet commands the largest installed base expansion, with Thermal Transfer defending its position in logistics most tenaciously.
Application:
Vertical-specific compliance burdens and design refresh frequencies create divergent equipment specifications across end-use sectors.
- Pharmaceuticals:Unit-level serialization requirements under FDA track-and-trace regulations and the EU Falsified Medicines Directive mandate digital systems with ERP-connected verification database integration. German and Swiss packaging hubs concentrate deployment.
- Food & Beverage:Batch-specific allergen labeling and seasonal design rotations demand short-run flexibility without plate-change downtime.
- Retail:Price markdown and promotional label variability driving mid-volume converter investments.
- Electronics:Component serialization for traceability in China's expanding manufacturing belt.
Pharmaceuticals absorbs the dominant equipment investment, though Food & Beverage is expanding most quickly as brand owners consolidate supplier relationships.
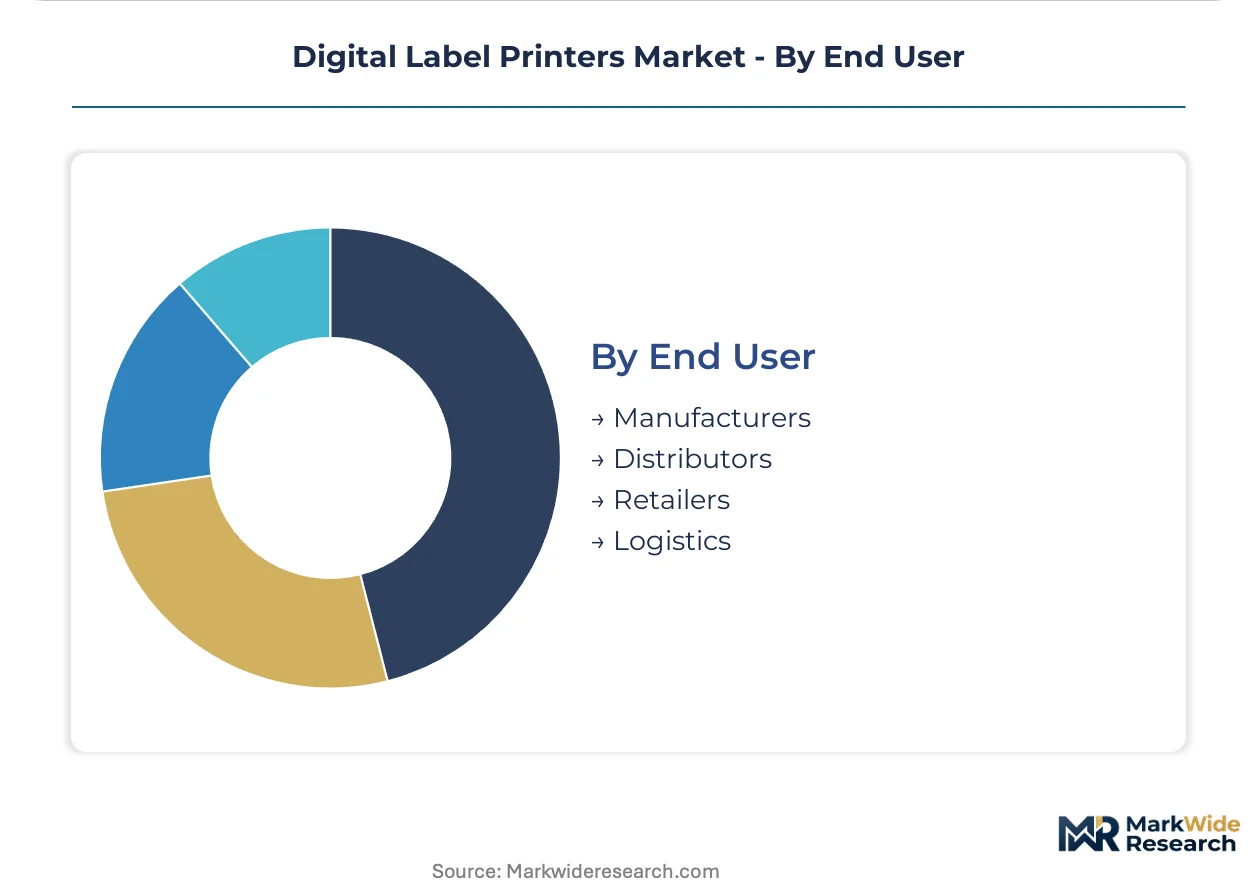
End User:
Procurement authority and integration complexity vary sharply across the value chain, shaping vendor sales motion and service attach rates.
- Manufacturers:In-house packaging lines at pharmaceutical and food processing facilities where MES integration complexity extends deployment timelines.
- Distributors:Third-party logistics providers managing variable-data compliance labeling for multiple brand owners.
- Retailers:Private-label operations and in-store promotional production with localized design authority.
- Logistics:Shipping and warehousing operations where direct thermal cost optimization prevails.
Manufacturers retain the dominant procurement volume, while Distributors are gaining share fastest as brand owners outsource serialization compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter equipment procurement clusters in Germany's industrial packaging corridor, with pharmaceutical serialization mandates and short-run flexible production economics driving parallel investments across Switzerland, the United States, China, and India.
Germany
Rhine-Ruhr and Baden-Württemberg packaging hubs concentrate narrow-web digital press deployments for EU Falsified Medicines Directive compliance. EMA serialization requirements force converter capital redeployment from analog flexographic assets. Stuttgart-based system integrators anchor pharmaceutical contract packaging automation.
Switzerland
Swissmedic mandates compress replacement cycles for unit-level traceability equipment in Basel and Zurich pharmaceutical clusters. REACH restrictions on photoinitiator chemistries extend substrate qualification timelines. Geneva-area converters prioritize single-pass UV inkjet architectures for continuous-duty operations.
United States
FDA track-and-trace regulations drive pharmaceutical packaging line retrofits in New Jersey and Pennsylvania manufacturing corridors. HP Inc. leverages PageWide technology installations across Midwest converter operations. California's emerging state-level packaging sustainability laws reshape substrate specifications for West Coast brand owners.
China
GB standards evolution and expanding electronics manufacturing in Guangdong and Jiangsu provinces create demand for serialized component labels. NMPA pharmaceutical traceability requirements align with international serialization protocols. Zebra Technologies anchors logistics automation deployments in Yangtze River Delta distribution hubs.
India
PLI scheme incentives for smartphone assembly generate unmet demand for electronics component labeling in Karnataka and Tamil Nadu industrial zones. CDSCO serialization mandates for pharmaceutical exports drive digital system adoption. Mumbai and Ahmedabad converters invest in desktop thermal transfer units for sub-500-unit cosmetics production flexibility.
Digital Label Printers Market Competitive Environment
Industrial printing system specialists and precision imaging component suppliers split the market into technology-led and application-led competitive spheres. The vendor base organizes around three strategic archetypes: diversified electronics conglomerates with industrial printer portfolios, dedicated narrow-web press manufacturers, and inkjet component technology licensors. Consolidation pressures favor M&A activity among mid-cap converter equipment suppliers, while technology licensing agreements accelerate single-pass architecture adoption.
Within the diversified electronics tier, Zebra Technologies and Brother Industries exemplify scale-driven positioning across North American logistics automation and Asian manufacturing supply chains respectively. Seiko Epson occupies a precision component archetype through micro-piezo inkjet head licensing to narrow-web press OEMs. These three entities represent distinct strategic postures: hardware volume leadership, vertical integration into consumables, and core technology IP monetization.
| Leading Market Players |
|---|
| Zebra Technologies |
| Brother Industries |
| Seiko Epson |
| Avery Dennison |
| SATO Holdings |
| TSC Auto ID Technology |
| HP Inc. |
| Primera Technology |
| Konica Minolta |
| Others |
Value Chain & Pricing Dynamics
Photoinitiator supply concentration in Chinese chemical manufacturing anchors downstream margin distribution, forcing European and North American printer operators to absorb input price swings exceeding fifteen percent annually while converter investments in Germany's industrial packaging corridor capture premium pricing for EU Falsified Medicines Directive-compliant serialization throughput.
Pricing Analysis
REACH authorization procedures dictate the pricing tier structure across UV-curable digital ink formulations, with compliant adhesive systems commanding premium positioning against restricted chemistries. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade serialization bundles from food-and-beverage batch customization and monochrome logistics configurations. Cost compression in mid-volume converter segments is intensifying because single-pass aqueous inkjet architectures compress total cost of ownership calculations. Logistics end users exhibit the highest price sensitivity, while pharmaceutical contract packagers demonstrate the lowest due to regulatory non-negotiability.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculations for photoinitiator and monomer chemistries essential to UV-curable ink formulations. Manufacturing concentration in China, Japan, and Germany feeds specialized piezoelectric printhead fabrication, precision substrate coating, and industrial automation integration. Raw material dependencies on rare earth elements for permanent magnet actuators, specialty photoinitiators, and pressure-sensitive adhesive polymers create single-source vulnerability in qualified pharmaceutical-grade supply tiers. Distribution runs through authorized converter equipment dealers with attached service contracts, supplemented by direct OEM relationships for high-volume pharmaceutical packaging line retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital label printer incumbents face substitution defense imperatives as analog flexographic assets retain cost advantage in ultra-long-run applications and direct thermal technology defends monochrome logistics segments.
For Market Incumbents: Pre-empt analog retention in food-and-beverage long-run contracts by accelerating single-pass inkjet throughput demonstrations that eliminate plate-change economics. Secure backward integration into compliant adhesive formulations to circumvent REACH qualification delays that extend six to nine months. Channel control through Stuttgart-based system integrators anchors pharmaceutical automation retrofit capture against emerging Asian entrants. For New Entrants and Emerging Players: Desktop thermal transfer configurations for Italian and Spanish contract converters represent the most penetrable entry point, with sub-500-unit cosmetics production flexibility underserved by industrial-tier vendors. India's PLI scheme electronics manufacturing zones in Karnataka and Tamil Nadu offer second-mover serialization demand with less entrenched supplier relationships. Cloud-based print management software bundling creates service-revenue differentiation against hardware-centric incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed narrow-web press manufacturers seeking exit liquidity amid consolidation pressures favoring M&A activity among mid-cap converter equipment suppliers. Five-to-ten-year viability hinges on single-pass architecture adoption velocity and ERP-connected workflow software integration depth. The signal to watch is pharmaceutical contract packager consolidation rates in Switzerland and Germany, where vendor list reductions of forty to sixty percent concentrate procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Pass Inkjet Architecture Adoption | Swiss and German pharmaceutical packagers adopt fixed-array configurations to meet EU Falsified Medicines Directive throughput mandates. |
| Backward Integration into Compliant Adhesives | REACH restrictions on photoinitiator chemistries force reformulation cycles that extend qualification timelines beyond equipment depreciation schedules. |
| Cloud-Based Print Management Convergence | ERP-connected workflow software integration with single-pass hardware creates recurring service revenue beyond equipment sales. |
| Pharmaceutical Serialization Line Retrofit | FDA track-and-trace regulations and EU Falsified Medicines Directive force replacement of legacy coding equipment with digital verification-capable systems. |
| India Electronics Manufacturing Zone Entry | PLI scheme incentives for smartphone assembly in Karnataka and Tamil Nadu generate unmet demand for serialized component labels. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across converter operations, pharmaceutical contract packaging facilities, and industrial automation integrators. Primary interviews with narrow-web press operators, color management specialists, MES integration engineers, and procurement leads at food-and-beverage brand owners were validated against secondary sources including ECHA substance evaluation databases, FDA track-and-trace guidance documents, EU Falsified Medicines Directive implementation reports, and customs trade data on photoinitiator imports. Bottom-up equipment deployment counts triangulated with top-down market sizing across technology platforms.
Calibration against historical replacement cycle data and regulatory compliance deadline phasing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment tier, print engine technology, end-use vertical, and geographic regulatory cluster. CAGRs were derived from installed base expansion rates and average selling price trajectories. Forecast inputs incorporated pharmaceutical serialization mandate compliance timelines, substrate chemistry authorization status under REACH, and electronics manufacturing incentive scheme uptake in India.
Stress conditions across photoinitiator supply disruption, REACH authorization timeline extension, and analog flexographic retention in long-run food applications were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory enforcement consistency and converter capital redeployment velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pre-Printed Liners Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Mexico Print Label Market
Packaging Printing
Flex Banner Market
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Global Electrophotographic Printing in Packaging Market
Packaging Printing
Label Printers Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Heat Transfer Press Printing Machine Market
Packaging Printing
Qatar Printing and Packaging Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Digital Printing Packaging Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market