
 Global Printing for Packaging Market | 2026-2036
Global Printing for Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Printing for Packaging Market Outlook
The gap between premium security-printed pharmaceutical packaging and commodity food-grade flexographic output is broadening as brand owners split procurement budgets by performance tier. Amcor plc leverages its pharmaceutical certification network across multiple continents to sustain high-margin contracts for serialized blister foils. HP Inc. competes in the digital tier with inkjet web presses that enable variable-data printing for regional compliance labeling.
Printing for packaging encompasses the application of graphics, text, barcodes, and security features onto substrates such as paperboard, flexible films, and metal foils using processes that achieve resolutions from 80 lines per centimeter in flexography to over 1200 dpi in single-pass inkjet systems. Its primary commercial purpose is to convey brand identity, regulatory information, and supply-chain traceability while protecting product integrity through tamper-evident and authentication features. Flexographic printing dominates volume in corrugated and flexible food packaging where long runs amortize plate costs, while digital printing captures margin pools in pharmaceutical and personalized consumer segments where lot sizes shrink and versioning multiplies. Offset printing retains structural importance in premium cosmetics and electronics boxes where color fidelity and substrate versatility justify slower make-ready times.
EU REACH restrictions on solvent-based inks and FDA food-contact notification requirements for printing substrates are redirecting formulation investment toward water-based and UV-curable chemistries. ECHA substance evaluations and EPA TSCA Section 5 premanufacture notices are lengthening approval timelines for new pigment and photoinitiator chemistries, tightening supplier qualification criteria. Stakeholders must monitor how evolving extended producer responsibility frameworks in Germany, France, and California reshape substrate-recyclability specifications and ink-to-paper deinkability standards.
Market Dynamics
Pharmaceutical serialization mandates and EU Falsified Medicines Directive enforcement are compressing lot sizes while multiplying SKU variants, forcing converters to absorb setup cost penalties or migrate to digital platforms that eliminate plate economics.
Growth Catalysts
- EU Falsified Medicines Directive:Serialization requirements for prescription medicines are mandating two-dimensional data matrix codes on every saleable unit, expanding demand for high-resolution digital print heads capable of variable-data imprinting at pharmaceutical-grade line speeds.
- India's PLI scheme for packaging:Production-linked incentives for specialized packaging clusters in Gujarat and Maharashtra are attracting foreign inkjet press manufacturers to establish local assembly operations, reducing import duty burdens for domestic converters.
- Single-pass inkjet web technology:Print-bar advances achieving 1200 dpi at 150 meters per minute are closing the productivity gap with flexography for mid-run folding cartons, enabling pharmaceutical contract packagers to version batches without plate changeover delays.
Market Restraints
- Photoinitiator supply concentration:German and Chinese suppliers control 70% of global UV-curable photoinitiator output, exposing ink formulators to input volatility when environmental inspections interrupt Chinese specialty chemical production.
- ECHA substance evaluation timelines:Extended REACH compliance assessments for novel pigment chemistries are stretching new product qualification cycles to 24-36 months, freezing formulation pipelines for converters serving EU pharmaceutical exporters.
- Substrate-ink adhesion limitations:Water-based flexographic inks on high-density polyethylene flexible films continue to exhibit rub resistance failures below pharmaceutical specification thresholds, blocking migration from solvent systems despite regulatory pressure.
Strategic Opportunities
- Brazil's ANVISA track-and-trace mandate:Pending pharmaceutical serialization regulations will replicate EU compliance infrastructure requirements across Latin America's largest drug market, creating first-mover advantage for digital press operators establishing São Paulo service bureaus.
- Smart packaging convergence:Integration of printed NFC antennas with conventional folding carton graphics is enabling authentication-plus-engagement dual functionality, commanding 40-60% price premiums over standard security print in cosmetics and spirits applications.
- Extended producer responsibility frameworks:Germany's VerpackG and France's AGEC law are mandating recyclability-by-design specifications that favor mono-material carton constructions, displacing multi-layer flexible laminates and expanding addressable volume for recyclable ink systems.
Industry Challenges
- Color management specialist scarcity:Converters report 18-month recruitment cycles for operators capable of calibrating expanded gamut (CMYK+OGV) ink sets across hybrid flexo-digital production lines, constraining capacity expansion timelines.
- FDA food-contact notification complexity:New photoinitiator and pigment submissions require toxicological dossiers costing $200,000-$400,000 per substance, forcing mid-tier ink suppliers to abandon niche food-packaging segments rather than absorb compliance overhead.
- Legacy MIS integration friction:Digital press workflow software lacks native interoperability with established flexographic job ticketing systems, requiring custom middleware development that extends digital transformation projects by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Printing for Packaging Market |
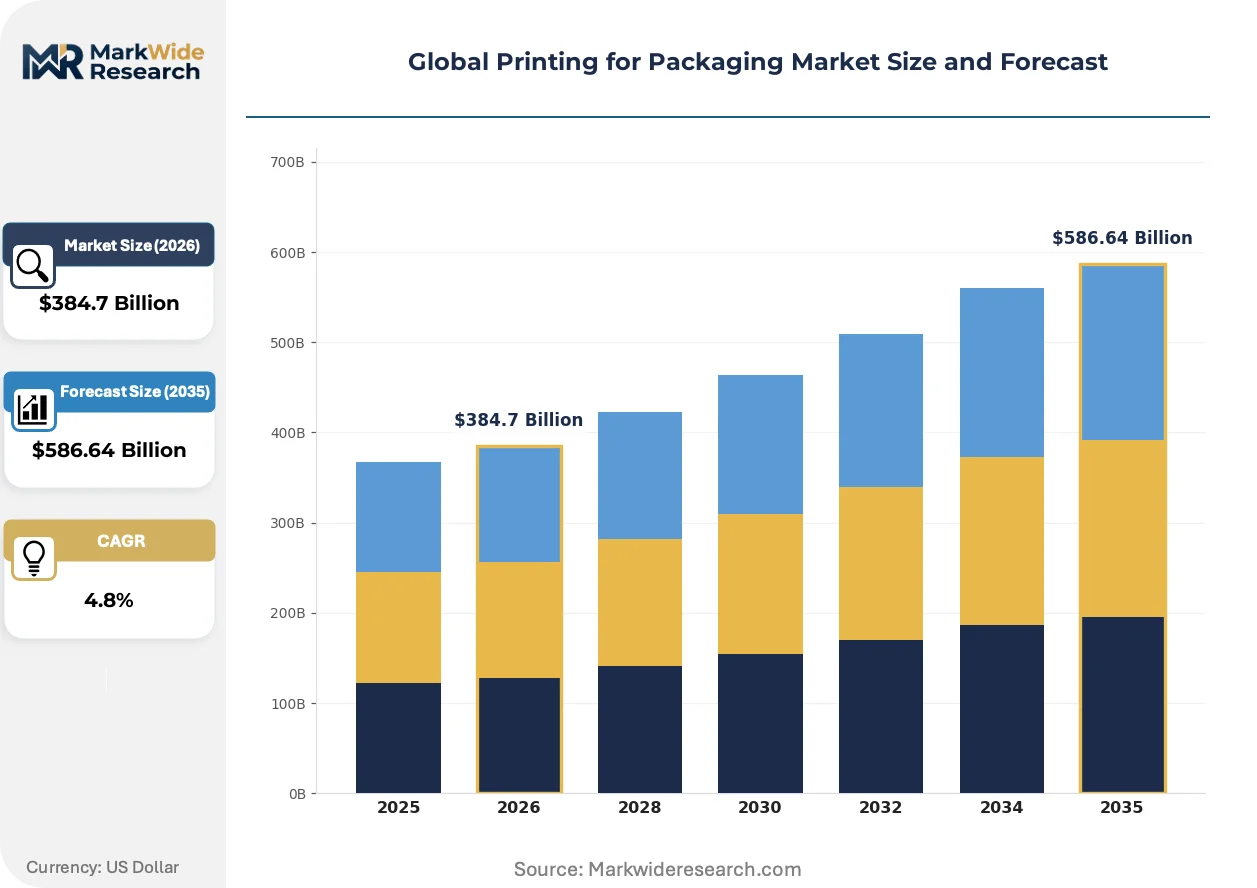
| Market Size in 2026 | $384.7 Billion |
| Market Size in 2035 | $586.64 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexographic, Gravure, Digital, Offset Material: Paper, Plastic, Metal, Wood Application: Food & Beverage, Consumer Goods, Pharmaceuticals, Electronics End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Amcor plc, Avery Dennison Corporation, CCL Industries Inc., International Paper Company, WestRock Company, DS Smith plc, HP Inc., Smurfit Kappa Group, Mondi Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Printing for Packaging Market Strategic Shifts
Electrification of print imaging is collapsing traditional process boundaries, as electron beam and UV-LED curing systems displace thermal drying infrastructure while artificial intelligence compresses color matching protocols from hours to minutes.
Single-pass inkjet array technology is electrifying short-run pharmaceutical and personalized consumer packaging economics by eliminating plate costs and enabling lot-size-one production. Brand owners in Germany and India are deploying these systems for regionalized medicine campaigns and geographically targeted FMCG promotions. The technology is compressing minimum efficient scale thresholds for folding carton converters, fragmenting volume concentration among regional specialists.
EU REACH Annex XVII restrictions on bisphenol A and phthalate plasticizers are redirecting thermal transfer ribbon and laminating adhesive formulations toward bio-based polyester alternatives. Ink manufacturers serving EU pharmaceutical exporters must reformulate entire product lines to maintain market access. German converters report 12-18 month reformulation cycles to achieve equivalent scuff resistance with compliant chemistries.
Brand owner procurement teams are consolidating print specifications around certified circularity metrics rather than unit cost minimization. Major retailers in France and California are requiring deinkability scores and recycled content verification as mandatory bid criteria, displacing lowest-bid-wins sourcing protocols. This behavioral shift is most visible in premium cosmetics and organic food segments where packaging sustainability credentials directly influence shelf placement negotiations.
Global Printing for Packaging Market Segmentation
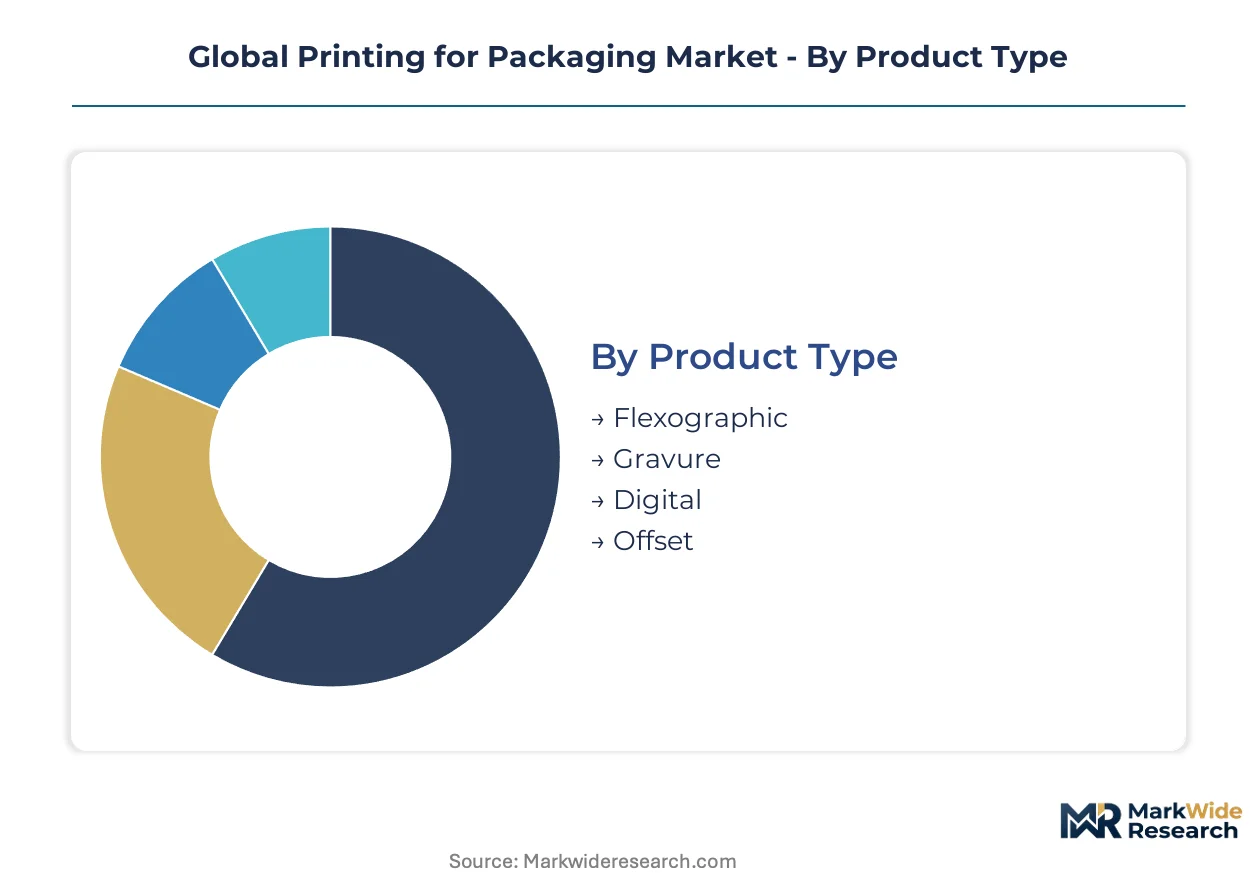
Converters allocate capital across printing platforms based on run-length economics and regulatory compliance requirements. Material selection and end-use specifications determine ink chemistry investments and curing infrastructure. Understanding how procurement splits across these dimensions reveals where margin pools concentrate versus where volume commoditizes.
Product Type:
Buyers choose between analog and digital platforms based on lot-size thresholds and versioning frequency.
- Flexographic:Rotary relief printing using photopolymer plates delivers 80-120 lines per centimeter resolution on corrugated and flexible films. Long-run food packaging contracts in India and Brazil amortize plate costs across millions of impressions, sustaining volume concentration despite setup penalties.
- Digital:Single-pass inkjet arrays achieve 1200 dpi with variable-data capability at 150 meters per minute. Pharmaceutical serialization mandates in Germany and the United States are compressing lot sizes and multiplying SKU variants, forcing migration from analog plates to toner and inkjet systems.
- Gravure:Engraved cylinder intaglio process excels in high-volume decorative laminates and publication gravure. Cylinder engraving costs restrict economic viability to runs exceeding 500,000 impressions, concentrating demand in tobacco and premium spirits export packaging.
- Offset:Lithographic planographic method transfers ink via intermediate blanket cylinders. Premium cosmetics and electronics boxes in Japan and Switzerland demand the color fidelity and substrate versatility that offset provides despite slower make-ready times.
Volume sits with Flexographic; growth tilts toward Digital.
Material:
Substrate selection constrains ink adhesion chemistry and determines recyclability certification pathways.
- Paper:Cellulosic substrates including folding carton board and corrugated linerboard dominate pharmaceutical and food primary packaging. EU EPR frameworks in Germany and France mandate mono-material recyclability, expanding addressable volume for deinkable ink systems on paperboard.
- Plastic:Polyethylene, polypropylene, and polyester films serve barrier-sensitive food and medical applications. Water-based flexographic inks on high-density polyethylene continue exhibiting rub resistance failures below pharmaceutical thresholds, blocking solvent system displacement despite REACH pressure.
- Metal:Aluminum and tinplate substrates enable retort pouches and aerosol cans requiring sterilization compatibility. India's PLI scheme for specialized packaging clusters is attracting foreign investment in metal decorating press capacity for regional beverage can production.
- Wood:Plywood and solid wood cases provide structural protection for heavy machinery and export goods. Industrial logistics applications in Brazil and China sustain niche demand for screen-printed branding on crating and pallets.
Paper commands the installed press base; plastic faces the steepest regulatory reformulation pressure.
Application:
End-use specifications determine security-feature investment and compliance documentation intensity.
- Food & Beverage:Flexible films and folding cartons for perishable and shelf-stable goods. FDA food-contact notification requirements for new photoinitiator chemistries force mid-tier ink suppliers to abandon niche segments rather than absorb $200,000-$400,000 toxicological dossier costs per substance.
- Pharmaceuticals:Serialized blister foils, labels, and cartons requiring tamper-evident and authentication features. EU Falsified Medicines Directive and FDA DSCSA mandates are accelerating demand for track-and-trace capable printed packaging with two-dimensional data matrix codes.
- Consumer Goods:Personalized folding cartons and labels for cosmetics, spirits, and regional FMCG campaigns. Brand owners in Germany and India concentrate procurement on digitally printed short-run production for geographically targeted promotions.
- Electronics:Premium rigid boxes and anti-static flexible pouches for smartphones, semiconductors, and components. Offset printing retains structural importance here where color fidelity justifies slower throughput.
Food and Beverage anchors volume throughput; Pharmaceuticals generates the steepest expansion trajectory.
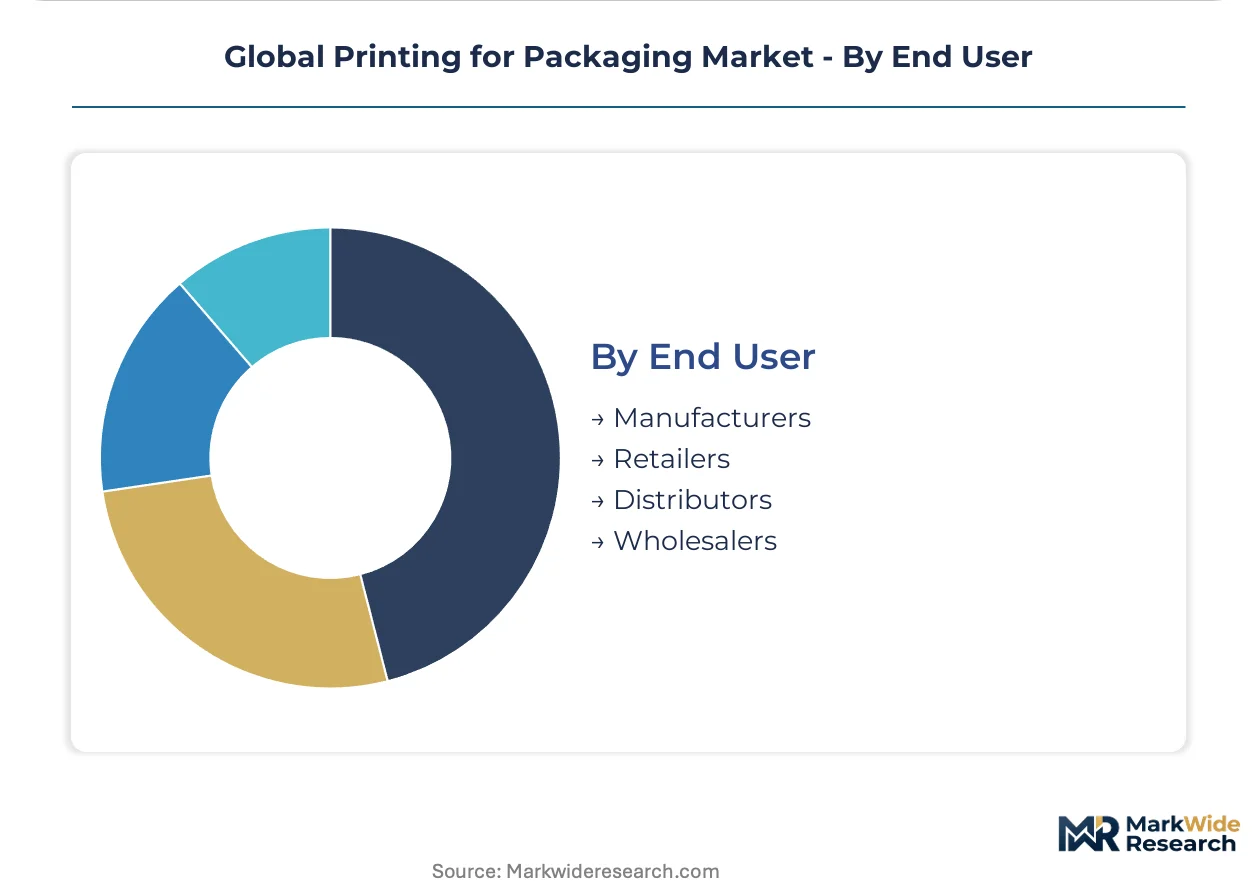
End User:
Channel position determines inventory risk tolerance and print versioning requirements.
- Manufacturers:Brand-owning producers including pharmaceutical companies, food processors, and electronics OEMs. Direct procurement of serialized packaging by drug manufacturers in the United States and European Union compresses converter margins while demanding quality system certifications.
- Retailers:Private-label controllers and supermarket chains specifying packaging for store brands. French and California retailers mandate deinkability scores and recycled content verification as mandatory bid criteria, displacing lowest-bid-wins sourcing protocols.
- Distributors:Third-party logistics providers managing regional warehousing and repackaging operations. Brazilian pharmaceutical distributors anticipate ANVISA track-and-trace mandates, creating service bureau opportunities for digital press operators establishing São Paulo capacity.
- Wholesalers:Bulk intermediaries aggregating volume for institutional and export channels. Price-sensitive procurement in emerging markets sustains gravure and flexographic volume for standardized export cartons.
Manufacturers concentrate value-added demand; Retailers are reshaping specification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European demand for pharmaceutical-grade folding cartons, while Mumbai and São Paulo emerge as competing hubs for digital conversion services serving regionalized medicine campaigns.
United States
Pharmaceutical contract packagers in New Jersey and North Carolina absorb FDA DSCSA serialization mandates through digital press investments. The FDA food-contact notification process for new photoinitiator chemistries stretches qualification timelines, freezing mid-tier ink suppliers out of niche segments. Chicago-area converters integrate single-pass inkjet arrays to version batches without plate economics penalties.
Germany
Brand-owning drug manufacturers in Bavaria and Baden-Württemberg compress converter margins while demanding quality system certifications for serialized blister foils. ECHA REACH Annex XVII restrictions on bisphenol A redirect thermal transfer ribbon formulations toward bio-based polyester alternatives. The Stuttgart industrial corridor hosts HP Inc. inkjet press demonstration centers targeting pharmaceutical versioning demand.
India
CDSCO pharmaceutical serialization requirements replicate EU compliance infrastructure, accelerating demand for track-and-trace capable printed packaging. The PLI scheme for specialized packaging clusters in Gujarat and Maharashtra attracts foreign inkjet press manufacturers to establish local assembly operations. Mumbai-based converters concentrate procurement on digitally printed short-run folding cartons for personalized medicine campaigns.
Brazil
ANVISA track-and-trace mandates pending for pharmaceutical distribution create first-mover advantage opportunities for digital press operators. São Paulo service bureaus anticipate compliance infrastructure requirements across Latin America's largest drug market. Local converters serving regional beverage can production benefit from metal decorating press capacity investments under industrial stimulus programs.
China
NMPA pharmaceutical serialization standards and dual carbon goals redirect formulation investment toward water-based and UV-curable ink chemistries. Environmental inspections interrupt specialty chemical production in coastal manufacturing zones, exposing ink formulators to photoinitiator input volatility. The Yangtze River Delta retains volume concentration in long-run flexible food packaging despite regulatory pressure on solvent systems.
Global Printing for Packaging Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification-grade and technology-platform dimensions. The market structures around three tiers: multinational integrated packaging conglomerates with pharmaceutical certification networks, specialized digital press technology licensors, and regional flexographic converters serving long-run food contracts. Consolidation pressures concentrate among mid-tier analog specialists facing digital migration costs. Dominant competitive moves include strategic partnerships between inkjet press manufacturers and pharmaceutical contract packagers, plus backward integration into substrate production by folding carton converters.
Within the integrated packaging tier, Amcor plc and Mondi Group exemplify multinational conglomerates sustaining high-margin contracts through pharmaceutical certification networks across multiple continents. HP Inc. occupies a position among digital technology licensors competing with inkjet web presses for variable-data printing applications. These three companies represent the archetype spectrum from substrate-integrated packaging to pure-play digital equipment supply.
| Leading Market Players |
|---|
| Amcor plc |
| Avery Dennison Corporation |
| CCL Industries Inc. |
| International Paper Company |
| WestRock Company |
| DS Smith plc |
| HP Inc. |
| Smurfit Kappa Group |
| Mondi Group |
| Others |
Value Chain & Pricing Dynamics
EU EPR recyclability mandates gate qualified supply and premium-tier pricing access for converters serving pharmaceutical and cosmetics brand owners in Germany and France. Compliance-certified ink systems and mono-material substrate constructions command 15-25% price premiums over commodity flexographic output, while non-compliant suppliers face exclusion from retailer procurement shortlists.
Pricing Analysis
Yield-guaranteed throughput contracts anchor value-based pricing for single-pass inkjet installations serving pharmaceutical serialization demand. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified serialization work from regional food-grade flexographic volume and commodity corrugated output. Cost compression in mid-tier offset folding cartons is intensifying because brand owners consolidate specifications around circularity metrics rather than unit cost. Generic flexographic converters serving Indian and Brazilian food contracts exhibit highest price sensitivity; certified pharmaceutical contract packagers in New Jersey and Stuttgart show lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Freight cost volatility from German and Chinese photoinitiator hubs exposes ink formulators to margin erosion when environmental inspections interrupt specialty chemical production. Supply concentrates in China for UV-curable resin feedstocks, Germany for photoinitiator innovation, and India for water-based flexographic pigment dispersion. Raw material dependencies span petrochemical-derived acrylates, titanium dioxide pigments, and bisphenol A-free thermal transfer substrates. Single-source vulnerability concentrates in Chinese coastal manufacturing zones subject to unscheduled environmental compliance shutdowns. Distribution runs through converter-direct relationships for pharmaceutical serialization contracts and regional distributor networks for commodity food packaging inputs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive control over certified substrate supply to defend margin pools against digital platform commoditization.
For Market Incumbents: Deploy pharmaceutical certification network expansion to lock out regional digital specialists bidding for EU and US serialization contracts. Acquire water-based ink formulation capabilities in India to preempt PLI scheme localization requirements. Consolidate folding carton substrate production in Germany to secure mono-material recyclability certification ahead of France's AGEC law enforcement. For New Entrants and Emerging Players: Pharmaceutical distributors in São Paulo represent the most penetrable channel partner type for digital press service bureaus anticipating ANVISA track-and-trace mandates. Target Brazil's pending compliance infrastructure gap before incumbent converters establish local capacity. Pursue white-label smart packaging integration partnerships with cosmetics brand owners seeking NFC-enabled authentication-plus-engagement functionality. For Investors and Strategic Acquirers: HP Inc. demonstration center expansion in Stuttgart is the leading indicator that pharmaceutical versioning demand is accelerating faster than analog converter digital migration capacity. Position for 5-10 year viability around mid-cap digital press operators with installed pharmaceutical certification bases. Monitor ECHA substance evaluation timeline extensions as the signal for formulation supplier distress acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Substrate Production | Captive folding carton board supply secures mono-material recyclability certification for EU EPR compliance. |
| Single-Pass Inkjet Press Deployment | 1200 dpi pharmaceutical-grade resolution eliminates plate economics penalties for lot-size-one serialization. |
| Photoinitiator Supply Agreement | Long-term offtake from German suppliers mitigates Chinese environmental inspection volatility. |
| Smart Packaging Platform Integration | Printed NFC antenna convergence commands 40-60% price premiums in cosmetics and spirits applications. |
| Regional Service Bureau Establishment | São Paulo capacity positioning captures first-mover advantage from Brazil's pending ANVISA mandates. |
Study Parameters
Multi-period observation of inkjet press installation rates, ECHA substance evaluation timelines, and pharmaceutical serialization compliance deadlines anchored the trend analysis, supplemented by interviews with folding carton converters, ink formulation technical directors, pharmaceutical contract packaging procurement leads, and brand owner sustainability specification managers. Secondary validation drew from FDA food-contact notification databases, EU REACH Annex XVII restriction updates, CDSCO pharmaceutical packaging advisories, and customs trade data for photoinitiator and UV resin imports. Bottom-up press capacity modeling and top-down pharmaceutical packaging demand projections were triangulated against converter revenue disclosures.
Segment-weighting across product type, material substrate, end-use application, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from installed base evolution curves and replacement demand elasticity by platform technology. Industry-specific forecast inputs included EPR framework implementation schedules, serialization mandate phase-in deadlines, and single-pass inkjet productivity improvement trajectories.
Caveats apply where ECHA substance evaluation timeline extensions, Chinese environmental inspection intensity, or FDA food-contact notification processing delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Global Pre Print Flexo Press Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Stack Flexo Printing Press Market
Packaging Printing
Czech Republic Printing Label Market
Packaging Printing
Laser Coders Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Europe Printed Packaging Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Asia-Pacific Digital Printing Packaging Market
Packaging Printing
Rotogravure Printing Cylinder Market
Packaging Printing
North America Thermal Transfer Overprinter Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Digital Label Printers Market