
 Kids Toothbrush Market | 2026-2036
Kids Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Kids Toothbrush Market Analytics
Supermarket shelf space for children's oral care is narrowing as pharmacy chains and direct-to-consumer platforms capture larger transaction volumes. Colgate-Palmolive leverages its pediatric dentist endorsement networks to sustain brand trust among first-time parents. Philips Sonicare anchors the premium electric segment through rechargeable handles with pressure sensors designed for juvenile grip strength. Pigeon Corporation specializes in silicone-bristle designs for infant gum massage, occupying a distinct niche below standard toothbrush age thresholds.
A kids toothbrush is a scaled dental cleaning instrument engineered with reduced head dimensions, extra-soft filament diameters typically below 0.15 millimeters, and ergonomic handles sized for developing palmar grasp. Its commercial purpose centers on plaque removal without enamel abrasion during deciduous and mixed dentition phases. Manual toothbrushes still lead volume shipments across mass retail, though smart variants with Bluetooth-connected brushing timers represent the fastest-expanding margin pool as parents seek compliance verification. Biodegradable materials remain a nascent category constrained by cost premiums and limited industrial composting infrastructure for cornstarch-based handles.
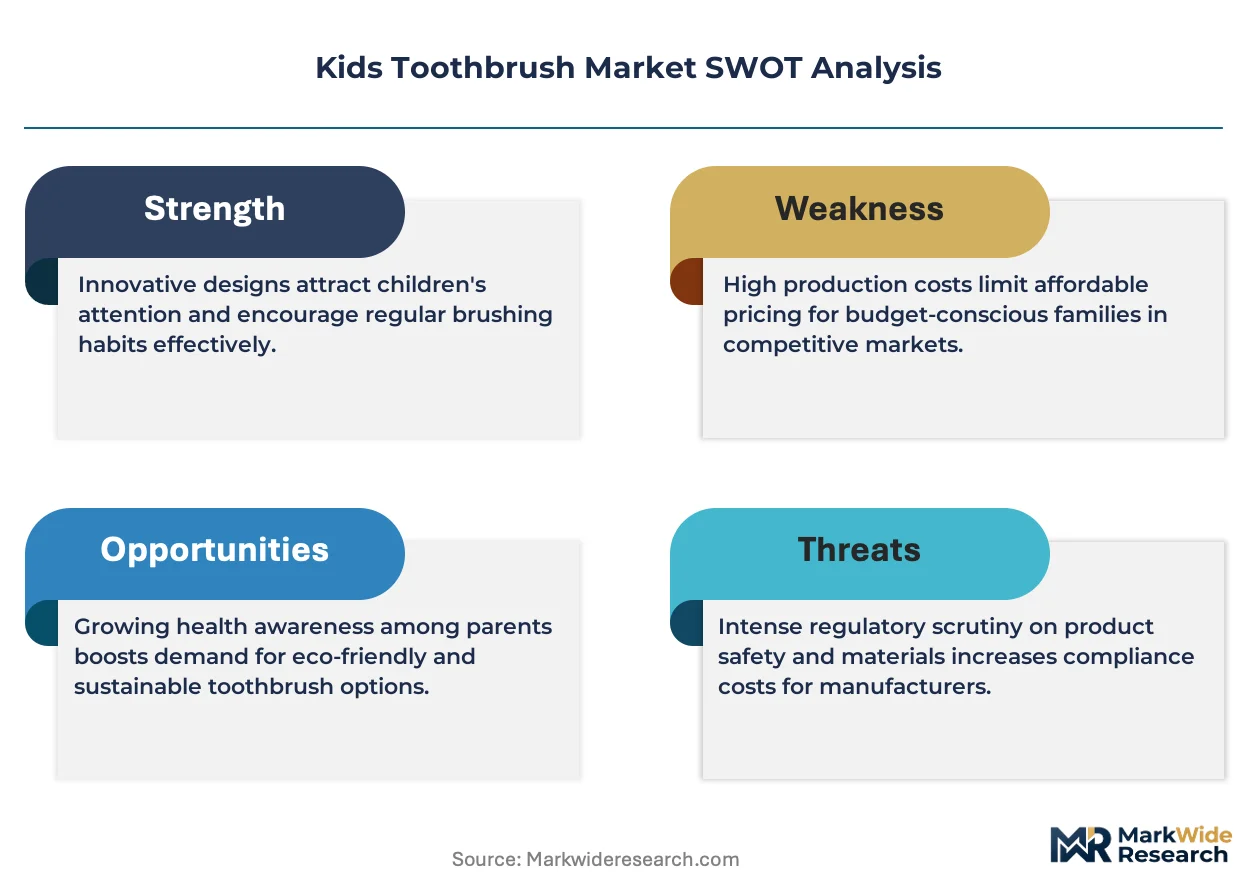
FDA Center for Devices and Radiological Health oversees electric toothbrush safety classifications, while BIS mandates mechanical testing for children's products sold in India, and the EU Green Deal's packaging waste directives are pressuring single-use plastic reduction across European imports. These frameworks elevate compliance costs for new entrants but simultaneously reinforce incumbent advantages through pre-certified supply chains. Stakeholders must monitor evolving battery transportation regulations and regional extended producer responsibility schemes as product electrification accelerates.
Market Dynamics
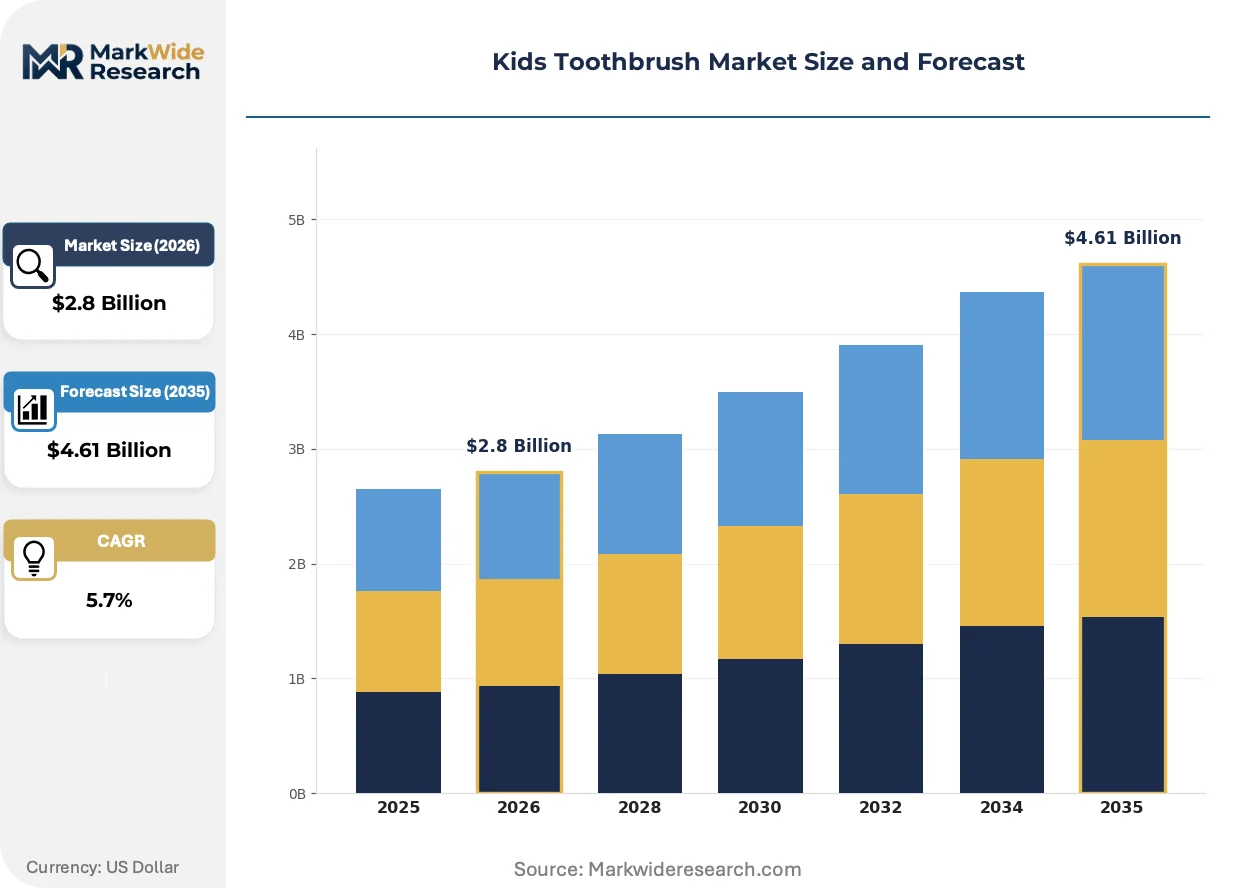
Parental demand for compliance verification is compressing manual toothbrush margins while accelerating electrification and connectivity investments across juvenile oral care portfolios.
Growth Catalysts
- EU Green Deal packaging directives:Single-use plastic reduction mandates are creating certified sustainable product lines that command shelf space in European pharmacy chains and premium positioning.
- Silicone-bristle infant massage:Pre-tooth gum care protocols endorsed by pediatric dentistry associations are extending addressable age thresholds below standard toothbrush entry points.
- Urban China:Middle-class household upgrading from manual to electric formats is concentrating volume expansion in tier-one and tier-two cities with higher disposable income elasticity.
Market Restraints
- Lithium-ion battery cost volatility:Electric handle production faces input price instability from concentrated cathode material processing in East Asian supply chains.
- BIS mechanical testing requirements:India's certification timeline for children's products creates 4-6 month entry delays for non-incumbent suppliers lacking pre-certified manufacturing partners.
- Cornstarch handle biodegradation:Limited industrial composting infrastructure in most markets constrains end-of-life claims and limits premium pricing justification.
Strategic Opportunities
- Bluetooth-connected brushing timers:Gamified compliance tracking for parents represents unoccupied white space between basic electric handles and premium smart devices.
- Direct-to-consumer subscription models:Recurring brush head replenishment bypasses retail slotting fees and captures lifetime value from first-time parent cohorts.
- FDA pediatric device pathway:Streamlined 510(k) clearance for juvenile-specific pressure sensors and grip ergonomics offers regulatory tailwind for specialized form factors.
Industry Challenges
- ISO 20126 filament durability testing:Extended certification cycles for extra-soft bristle formulations delay product launches and compress innovation-to-shelf timelines.
- Cross-border battery transportation regulations:UN 38.3 lithium cell compliance adds documentation complexity and freight cost premiums for direct-ship e-commerce fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kids Toothbrush Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Battery-operated, Smart Material: Plastic, Silicone, Biodegradable, Rubber Age Group: Toddlers, Preschoolers, Early Elementary, Preteens Features: Soft Bristles, Cartoon Characters, Light-up, Travel Case |
| Companies Covered | Oral-B, Philips Sonicare, Colgate-Palmolive, Procter & Gamble, Johnson & Johnson, Pigeon Corporation, Unilever, Church & Dwight, Fairywill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kids Toothbrush Market Evolving Landscape
Connectivity and material science are converging to transform juvenile oral care from commodity hardware into data-generating wellness platforms with recurring revenue architecture.
Smart toothbrush technology is migrating from simple quadrant timers to full-session data capture with parental dashboard integration. First-time parents in North American and Chinese metropolitan markets are adopting these devices at accelerating rates. This migration is compressing margins on non-connected electric handles while creating software-subscription revenue pools previously unavailable to hardware manufacturers.
REACH substance restrictions on microplastics in rinse-off cosmetics are extending scrutiny to toothbrush filament coatings and handle additives. EU-based importers must now document full material composition chains for juvenile products. The directive most affects mass-market suppliers dependent on petroleum-based colorants and antimicrobial surface treatments, forcing reformulation investments or geographic market exclusion.
Pharmacy chains are consolidating children's oral care assortments around clinically endorsed SKUs with dentist co-branding. Independent retailers and supermarket channels are losing shelf space to Walgreens, CVS, and Boots locations with in-house pediatric health positioning. This channel rotation is most visible in the United Kingdom and United States, where pharmacy foot traffic recovery post-pandemic has outpaced general merchandise retail.
Kids Toothbrush Market Segmentation
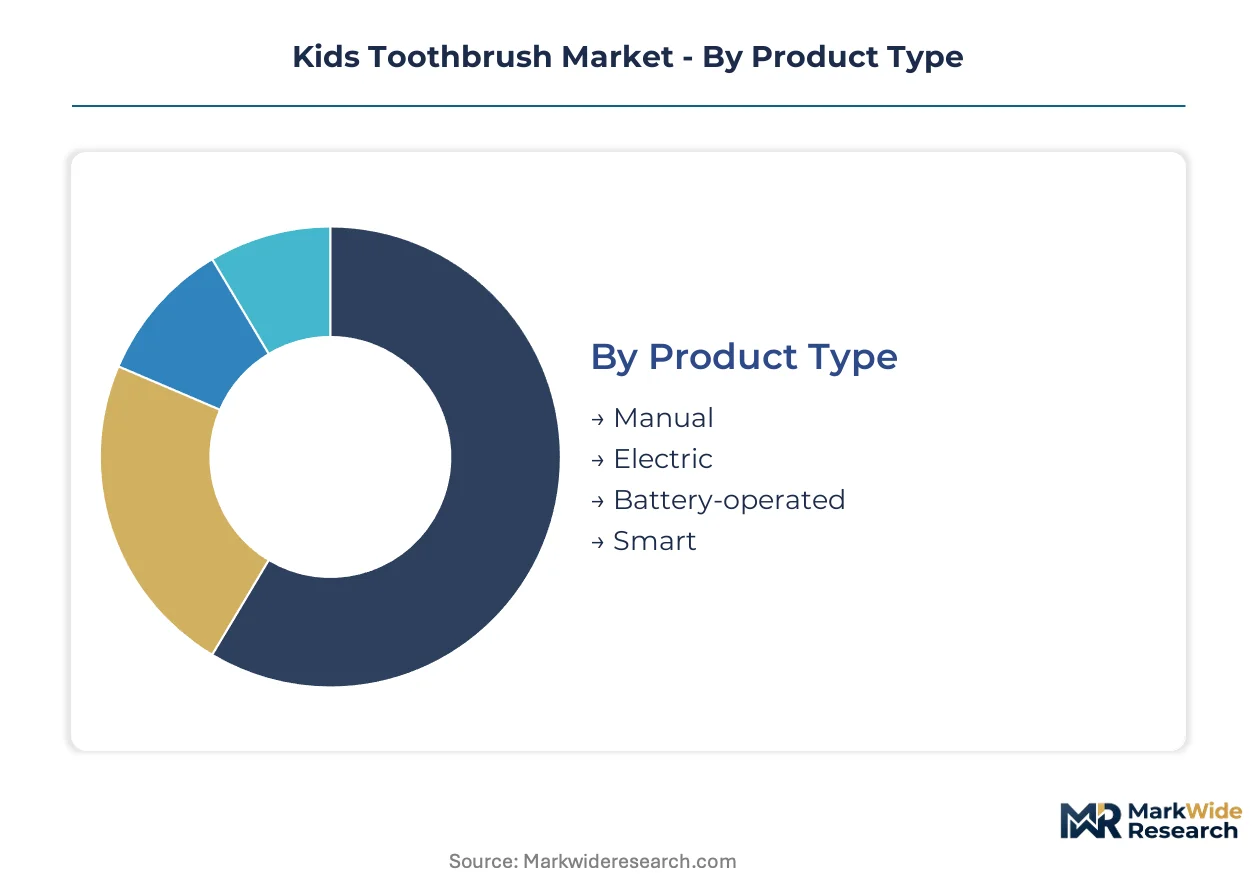
Segmentation in juvenile oral care reveals distinct replacement cycles and margin profiles across product formats. Understanding these patterns helps stakeholders allocate R&D resources between high-frequency consumables and durable platform investments.
Product Type:
Replacement frequency varies dramatically across this category, with manual handles turning over fastest while smart devices lock in multi-year ecosystem relationships.
- Manual:Polypropylene handles with nylon filament tufts dominate pharmacy and supermarket volume. Parents in tier-one Chinese cities are upgrading away from this segment fastest as electric alternatives penetrate middle-class households.
- Electric:Rechargeable handles with oscillating or sonic mechanisms command premium shelf positioning. Demand concentrates among North American parents seeking pressure-sensor protection for developing enamel.
- Battery-operated:Single-use alkaline cell designs occupy the mid-price tier with limited durability. Indian households favor this format where BIS certification complexity deters full rechargeable adoption.
- Smart:Bluetooth-enabled session tracking with parental dashboard integration represents the steepest expansion trajectory. FDA 510(k) pathway clarity for juvenile-specific sensors is accelerating specialized form factor development.
Manual brushes anchor the volume base while smart devices gain share at the steepest rate.
Material:
Cost tier alignment shapes procurement patterns, with petroleum-derived inputs at the economy end and certified biopolymers commanding pharmacy chain placement premiums.
- Plastic:ABS and polypropylene formulations remain the default for mass retail SKUs. REACH documentation requirements for EU importers are forcing supply chain transparency investments.
- Silicone:Medical-grade elastomer bristles enable pre-tooth gum massage protocols. Pigeon Corporation's infant-focused designs have established this material's credibility below standard toothbrush age thresholds.
- Biodegradable:Cornstarch-based handles and castor oil-derived filaments target sustainability-positioned parents. Limited industrial composting infrastructure in most markets constrains end-of-life claim verification.
- Rubber:Thermoplastic elastomer overmolds improve grip security for juvenile palmar grasp development. This material sees concentrated use in toddler-focused ergonomic designs.
Plastic handles maintain the installed base while silicone applications expand most quickly into younger age brackets.
Age Group:
Parental involvement intensity varies across developmental stages, from direct brushing assistance for toddlers to compliance monitoring for preteens.
- Toddlers:Products targeting 6-24 month users require caregiver-controlled application. Pediatric dentistry association endorsements drive purchase decisions for this highest-attention segment.
- Preschoolers:Three-to-five year olds represent the fastest-expanding buyer cohort as early dental hygiene habits gain priority among first-time parents.
- Early Elementary:Six-to-eight year olds transition toward independent brushing with gamified compliance tools. Smart toothbrush connectivity sees concentrated adoption at this threshold.
- Preteens:Nine-to-twelve year old users demand aesthetic personalization and social signaling features. Cartoon character licensing and color customization dominate this segment's differentiation.
Preschoolers anchor volume expansion while smart format adoption climbs fastest among early elementary users.
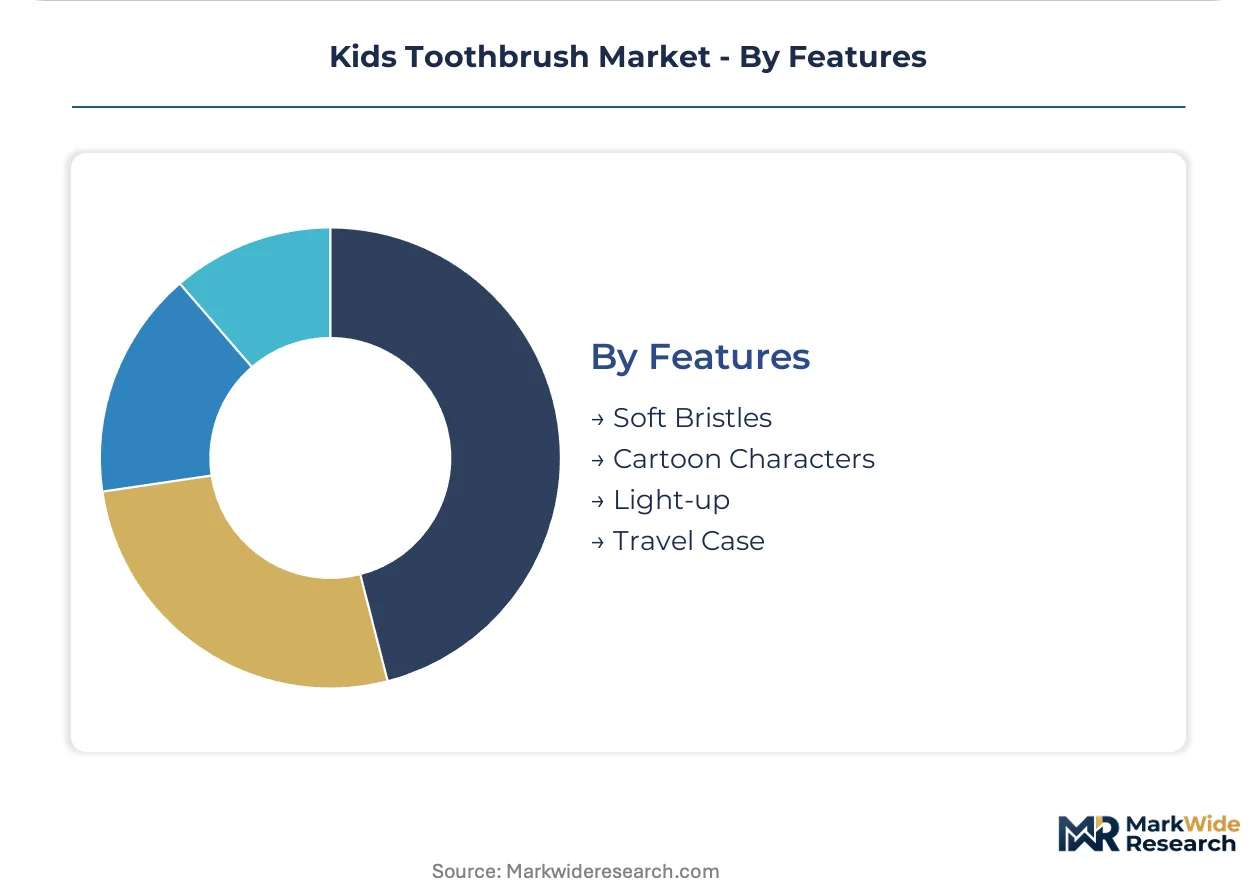
Features:
Margin stratification follows functional complexity, from commodity bristle softness claims to integrated electronics with recurring revenue architecture.
- Soft Bristles:Filament diameters below 0.15 millimeters are mandatory for deciduous dentition safety. ISO 20126 durability testing for extra-soft formulations extends certification timelines.
- Cartoon Characters:Licensed IP drives impulse purchase conversion in retail environments. Preteen demand concentrates heavily on entertainment property collaborations.
- Light-up:LED timers and quadrant indicators improve brushing duration compliance. This feature bridges manual and smart segments at intermediate price points.
- Travel Case:Protective enclosures extend product lifespan and support premium positioning. Direct-to-consumer subscription bundles frequently include case accessories.
Soft bristle claims maintain universal penetration while light-up features are climbing fastest as electrification spreads.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Shanghai and Shenzhen exceeds that of Mumbai and Delhi by substantial margins, reflecting divergent household upgrade trajectories for juvenile oral care. This asymmetry shapes manufacturer portfolio allocation between premium electrification and mass-market manual penetration.
United States
FDA Center for Devices and Radiological Health classifications for juvenile-specific pressure sensors accelerate specialized form factor development. The 510(k) clearance pathway offers regulatory tailwind for smart toothbrush entrants with connected compliance features. Greater Boston anchors pediatric dentist endorsement networks that sustain brand trust among first-time parents in metropolitan Northeast corridors.
China
Urban middle-class households in tier-one and tier-two cities upgrade from manual to electric formats at accelerating velocity. SAMR oversight of connected device data handling intersects with GB standards for children's product safety. Yangtze River Delta manufacturing clusters concentrate rechargeable handle assembly for domestic consumption and regional export.
India
BIS mechanical testing mandates for children's products create 4-6 month certification delays for non-incumbent suppliers lacking pre-certified partners. CDSCO alignment with pediatric device safety protocols is tightening for battery-enclosed formats. Maharashtra's pharmaceutical distribution networks are repurposing last-mile infrastructure for oral care product penetration into tier-two and tier-three cities.
Germany
REACH substance restrictions on microplastics extend scrutiny to toothbrush filament coatings and petroleum-based colorants. EU Green Deal packaging waste directives pressure single-use plastic reduction across juvenile product imports. Bavaria's precision engineering clusters supply pressure-sensor components for premium electric handle manufacturers serving European pharmacy chains.
United Kingdom
Boots and pharmacy chain consolidation around clinically endorsed SKUs with dentist co-branding is compressing supermarket shelf space for independent retailers. MHRA pediatric device guidance aligns with MDR transitional provisions for connected oral care hardware. London-Southeast demand concentrates among sustainability-positioned parents seeking biodegradable handle alternatives despite limited industrial composting verification.
Kids Toothbrush Market Competitive Landscape
Consumer health conglomerates and specialized juvenile care specialists split the market between scale-driven brand equity and niche ergonomic innovation. Incumbent advantages consolidate around pre-certified supply chains and pediatric dentistry endorsement networks that new entrants cannot rapidly replicate. Three archetypes dominate: diversified FMCG portfolios with dentist co-branding, dedicated infant-care specialists with silicone-bristle expertise, and connected-device hardware platforms with subscription revenue architecture. Competitive moves concentrate on direct-to-consumer channel bypass of retail slotting fees and regulatory pre-certification investments that extend manufacturing partnerships.
Among diversified consumer health portfolios, Colgate-Palmolive and Procter & Gamble exemplify archetypes leveraging established distribution density and professional endorsement networks. Pigeon Corporation occupies a distinct specialist position below standard toothbrush age thresholds with medical-grade elastomer designs. Philips Sonicare anchors the premium connected-device tier through rechargeable platforms with juvenile-specific sensor integration. These three represent the strategic spectrum from mass-market brand equity to niche material science to hardware-software ecosystem architecture.
| Leading Market Players |
|---|
| Oral-B |
| Philips Sonicare |
| Colgate-Palmolive |
| Procter & Gamble |
| Johnson & Johnson |
| Pigeon Corporation |
| Unilever |
| Church & Dwight |
| Fairywill |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta port congestion and trans-Pacific container rate volatility compress margins on imported electric handles while amplifying price spreads between certified premium tiers and unbranded economy alternatives. This freight corridor cost dynamic concentrates pricing power with domestic Chinese manufacturers serving pharmacy chains and direct-to-consumer platforms.
Pricing Analysis
The customization-premium spread between configured-to-order smart handles and standard manual brushes reaches its widest point in North American and European pharmacy channels. Three-tier pricing structure across premium, standard, and economy levels anchors on certification grade and connectivity features. Cost compression in the battery-operated tier intensifies because lithium-ion cathode material processing concentrates in East Asian supply chains. First-time parents in tier-one Chinese cities demonstrate the lowest price sensitivity, while mass-market manual buyers in India exhibit the highest.
Supply Chain Analysis
Supplier-financing facilities extended by Yangtze River Delta assembly clusters enable smaller brands to compete on payment terms against Colgate-Palmolive and Procter & Gamble procurement leverage. Manufacturing concentrates in China, India, and Germany for distinct tier specializations. Cornstarch biopolymer formulations and medical-grade silicone elastomers constitute critical raw material dependencies. Single-source vulnerability in lithium cell supply creates structural risk for electric format entrants. Distribution runs through pharmacy chain consolidation in the United Kingdom and United States, with direct-to-consumer subscription models gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kids toothbrush market fragmentation creates multiple entry points as parental demand splits between compliance-verification technology and sustainability-positioned materials. The preschooler segment's rapid expansion generates niche opportunities for specialized form factors.
For Market Incumbents: Insulate pediatric dentist endorsement networks through exclusive co-branding agreements with regional dentistry associations. Secure pre-certified manufacturing partnerships in India to neutralize BIS mechanical testing timeline disadvantages against emerging competitors. Backward integration into silicone elastomer compounding protects margin position from medical-grade material cost volatility. For New Entrants and Emerging Players: Bluetooth-connected brushing timers with gamified parental dashboards represent the most penetrable entry point between basic electric handles and premium smart ecosystems. Direct-to-consumer subscription models for brush head replenishment bypass pharmacy chain slotting fees and capture lifetime value from first-time parent cohorts. FDA 510(k) pathway clarity for juvenile-specific pressure sensors offers regulatory tailwind for specialized hardware development. For Investors and Strategic Acquirers: Connected-device hardware platforms with established subscription revenue architecture offer the strongest long-term viability framing across the analysis window. Acquisition targets should demonstrate software-companion development capabilities and pediatric regulatory pre-certification. The signal to monitor is SAMR data-handling enforcement tightening for connected juvenile devices in China, which would accelerate consolidation around compliant platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Regulatory Pre-Certification | BIS and FDA pathway investments compress entry timelines for compliant suppliers against non-certified competitors. |
| Direct-to-Consumer Subscription Launch | Recurring brush head replenishment captures lifetime value while bypassing pharmacy slotting fees. |
| Silicone Elastomer Backward Integration | In-house compounding of medical-grade materials protects margins from supply concentration in East Asian chemical clusters. |
| Bluetooth Connectivity Platform Integration | Gamified compliance tracking with parental dashboard differentiation commands premium positioning in early elementary segment. |
| Sustainability Repositioning | EU Green Deal packaging compliance enables certified product lines with pharmacy chain placement premiums. |
Research Methodology
A spread of perspectives from pediatric dentistry association executives, pharmacy chain category buyers, connected-device hardware engineers, and biopolymer procurement specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation from FDA 510(k) filings, BIS certification registries, EU REACH substance databases, and customs trade records. Bottom-up demand modeling across age segments and product formats triangulated against top-down market sizing from retail audit data.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, material composition, age group, and connectivity feature tier. CAGRs derived from replacement cycle frequency analysis and household penetration elasticity modeling. Industry-specific forecast inputs incorporated BIS certification timeline distributions and lithium-ion battery cost trajectory assumptions.
Practitioners should monitor regulatory enforcement tightening for connected device data handling and extended producer responsibility scheme implementation for early signals of competitive structure shift. Forecasts reflect assumptions about parental compliance verification demand persistence and electrification penetration rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Goods
Bounce House Market
Consumer Goods
South Africa Cosmetics and Personal Care Products Market
Consumer Goods
Wax Melts Market
Consumer Goods
Swimwear and Beachwear Market
Consumer Goods
North America Microwave Oven Market
Consumer Goods
Leather Jewellery Box Market
Consumer Goods
Janitorial Service Market
Consumer Goods
Over-Night Hair Treatment Products Market
Consumer Goods
Japan Camping Equipment Market
Consumer Goods
Smart Washing Machine Market
Consumer Goods
Smart Audio System Market
Consumer Goods
Baby Bottle Holder Market
Consumer Goods
Sneaker Deodorant Market
Consumer Goods
Europe Household Refrigerator Market
Consumer Goods
Egypt Dishwashers Market
Consumer Goods
Lightwave Microwave Oven Market