
 Global Luggage Market | 2026-2036
Global Luggage Market Size, Share, and Industry Trends Forecast 2026-2036
Global Luggage Market Outlook
Direct-to-consumer e-commerce is rewriting how luggage brands reach end buyers, collapsing traditional wholesale markups and accelerating feedback loops between design teams and purchasers. Samsonite International S.A. anchors its position through controlled retail networks across Asia and Europe, while Away leverages digital-native marketing to sustain rapid customer acquisition without physical store overhead. Tumi differentiates through business-traveler specialization, occupying the premium cabin-luggage tier with leather-accented polycarbonate constructions that command higher unit economics than mass-market alternatives.
Luggage comprises wheeled and hand-carried containers engineered from polymers, textiles, or metal alloys to protect apparel and personal effects during transit, with polycarbonate shells typically specified at 1.5–2.5 mm wall thickness to balance impact resistance against weight constraints. Hard-shell polycarbonate luggage leads volume shipments due to airline liability trends favoring rigid protection, while backpack configurations represent the fastest-expanding structural category as hybrid work-travel patterns blur traditional segmentation boundaries. Specialty stores retain margin concentration for premium leather and aluminum offerings despite online retail capturing the bulk of polyester and nylon volume.
FAA carry-on dimensional enforcement and EU REACH substance restrictions jointly constrain material choices and exterior sizing across North American and European supply chains, compelling manufacturers to certify zipper compounds and surface coatings against migrating chemical thresholds. Japan's METI product safety standards and China's GB/T national luggage quality specifications add further compliance layers for brands sourcing assembly from East Asian contract manufacturers. Stakeholders must monitor evolving airline baggage fee structures and polymer feedstock volatility as these forces determine whether hard-shell or soft-shell platforms deliver superior returns through the forecast horizon.
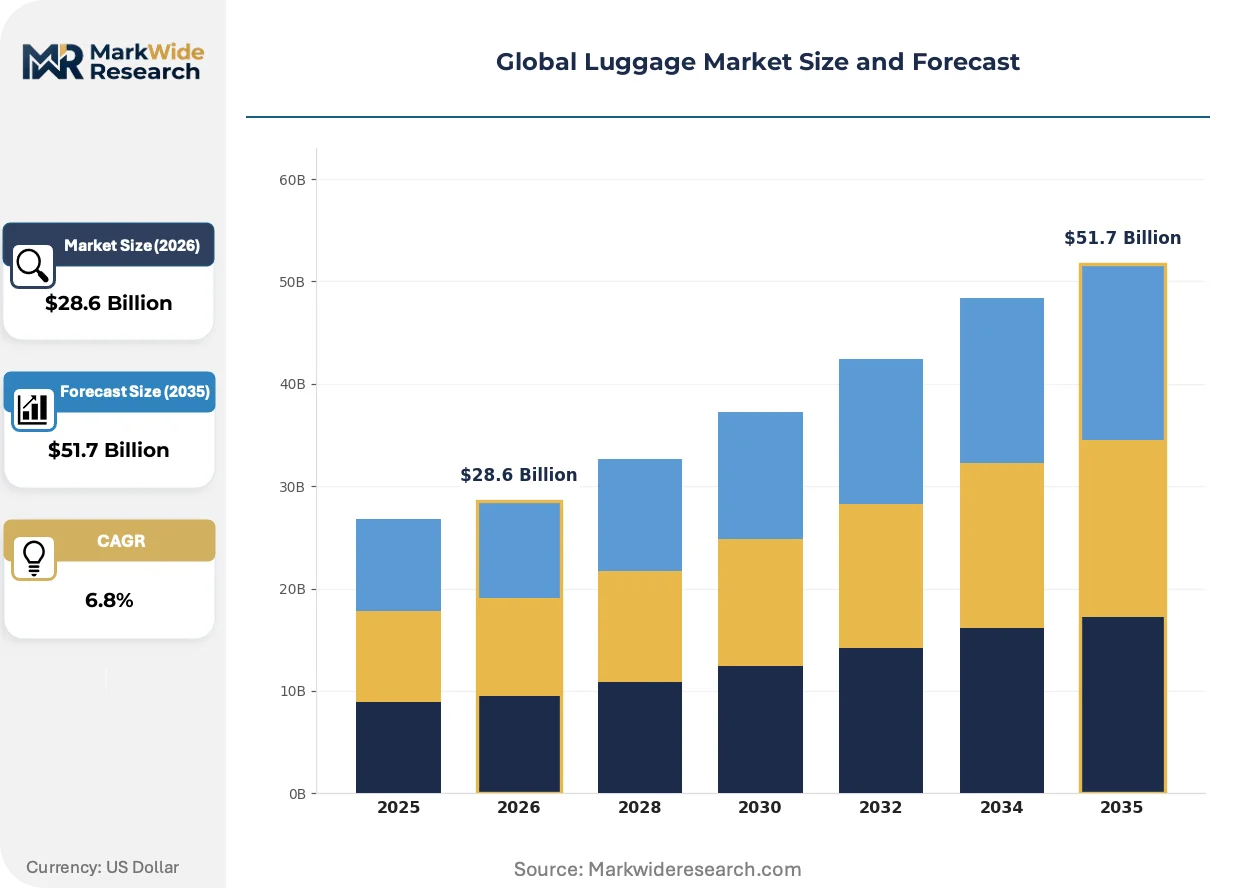
Market Dynamics
Polycarbonate hard-shell designs are compressing replacement cycles across leisure travel segments while FAA dimensional enforcement and EU REACH compliance simultaneously constrain material specifications and exterior sizing.
Growth Catalysts
- Domestic Outbound Tourism:China's expanding middle class is elevating premium luggage purchases through e-commerce channels, with domestic travel recovery outpacing international route restoration.
- REACH Compliance:ECHA substance restrictions are accelerating R&D investment in compliant zipper compounds and surface coatings, creating first-mover advantages for certified suppliers.
- Hybrid Work-Travel Patterns:Backpack configurations are capturing share from traditional upright luggage as business-leisure trip blending demands versatile carrying solutions.
Market Restraints
- Polymer Feedstock Volatility:Polycarbonate resin prices fluctuate with benzene and bisphenol-A supply disruptions, compressing margin stability for hard-shell manufacturers.
- East Asian Contract Concentration:Assembly dependence on Guangdong and Zhejiang province facilities creates single-source vulnerability for brands lacking geographic diversification.
- Airline Liability Limitations:Carrier damage claim caps reduce consumer willingness to invest in premium protection, favoring lower-price-tier purchases.
Strategic Opportunities
- India E-Commerce Penetration:Flipkart and Amazon India logistics expansion is opening direct-to-consumer pathways for mid-premium brands previously locked out of physical retail.
- Smart Luggage Convergence:GPS tracking modules paired with biometric locks are creating subscription-enabled revenue streams beyond unit sales.
- FAA Carry-On Harmonization:Standardized dimensional rules across US carriers reduce SKU complexity for brands optimizing single-model production runs.
Industry Challenges
- Multi-Jurisdiction Certification:Simultaneous compliance with Japan METI safety standards, China GB/T specifications, and EU REACH creates timeline bottlenecks for new product launches.
- Legacy Soft-Shell Inventory:Wholesale channel overhang from displaced nylon and polyester constructions is forcing discount-driven clearance activity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Luggage Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hard Shell, Soft Shell, Backpack, Duffel Bag Material: Polyester, Nylon, Leather, Polycarbonate End User: Travelers, Business Professionals, Adventurers, Students Distribution Channel: Online Retail, Specialty Stores, Department Stores, Airports |
| Companies Covered | Safari Industries India Ltd., Tumi, Samsonite International S.A., Victorinox, Rimowa, LVMH Moet Hennessy Louis Vuitton SE, IT Luggage Limited, Away, VIP Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Luggage Market Strategic Shifts
Embedded connectivity and biometric security are transforming luggage from passive containers into active travel infrastructure, while regulatory fragmentation across major economies is fragmenting product development roadmaps.
Integrated GPS tracking and Bluetooth proximity sensors are digitizing how travelers monitor baggage location and receive tamper alerts. Business travelers operating on tight connection windows are adopting these modules fastest, with airline app integration now standard. Real-time visibility is digitizing the traditional lost-baggage claim process and compressing resolution timelines from days to hours.
EU REACH substance restrictions are eliminating legacy phthalate plasticizers and certain flame retardants from interior lining materials. Manufacturers must reformulate polymer compounds or source certified alternatives, raising R&D expenditure thresholds. Premium leather-accented lines face the steepest reformulation costs due to tanning chemical scrutiny.
Direct-to-consumer channels are collapsing traditional wholesale markups and accelerating design feedback loops. Specialty retailers retain margin concentration for aluminum and full-grain leather offerings, while online platforms capture polyester and nylon volume. This bifurcation is most visible in China's Tmall and JD.com ecosystems, where live-stream commerce drives impulse purchases of mid-tier hard-shell sets.
Global Luggage Market Segmentation
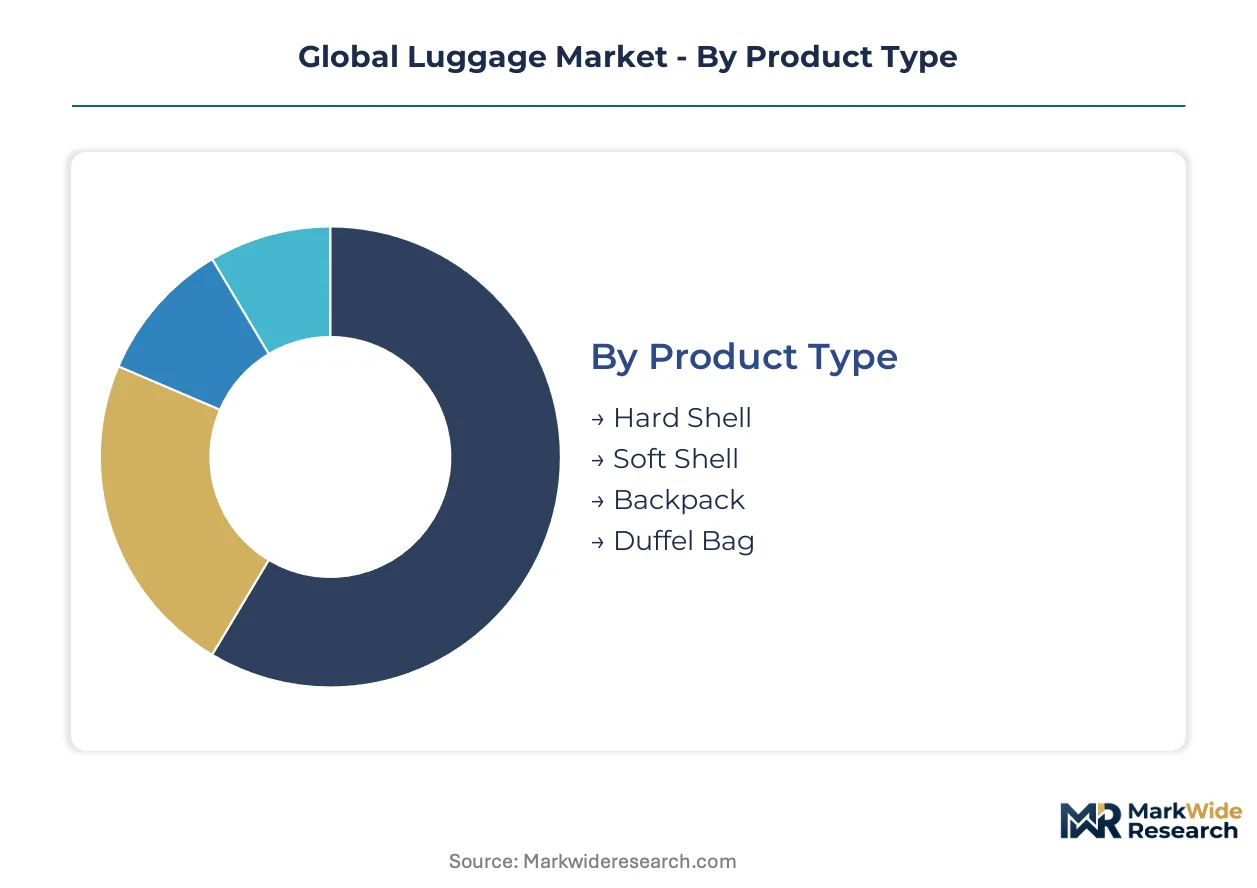
Luggage segmentation reveals how polycarbonate shells, hybrid work-travel formats, and direct-to-consumer channels are fragmenting traditional category boundaries. Manufacturers must align material specifications and distribution investments against diverging durability expectations and purchasing behaviors.
Product Type:
Traveler use-cases span airport check-in durability, cabin compliance, and multi-modal portability requirements.
- Hard Shell:Polycarbonate or ABS constructions with 1.5–2.5 mm wall thickness deliver impact resistance against airline handling. Demand concentrates in China through Tmall and JD.com live-stream commerce, where domestic outbound tourism elevates premium hard-shell set purchases.
- Backpack:Ergonomic frame systems with laptop compartments and weather-resistant fabrics address hybrid work-travel patterns. Business-leisure trip blending in the United States and Germany is accelerating backpack adoption over traditional upright luggage for sub-72-hour journeys.
- Soft Shell:Woven polyester or nylon exteriors with expandable gussets retain flexibility for overstuffed loads. Budget-conscious leisure travelers in India favor soft-shell value positioning.
- Duffel Bag:Cylindrical or rectangular unframed designs with shoulder straps suit gym-to-gate transitions. Weekend travelers in the United Kingdom select duffels for short-haul European routes.
The dominant share belongs to Hard Shell, while Backpack is closing the gap fastest.
Material:
Cost tiers separate mass-market synthetics from premium natural and engineered polymers.
- Polycarbonate:Thermoplastic resin with high impact strength and low density enables lightweight rigid shells. FAA carry-on dimensional enforcement across United States carriers favors polycarbonate's strength-to-weight ratio for size-optimized designs.
- Leather:Full-grain or top-grain hides with vegetable or chrome tanning deliver executive aesthetics. EU REACH substance restrictions on tanning chemicals are raising reformulation costs for European-sourced leather-accented lines.
- Polyester:PET-based woven fabrics with PU coatings provide water resistance at entry price points. Volume manufacturing concentrates in Guangdong province contract facilities.
- Nylon:Polyamide 6 or 6,6 constructions with ripstop weaves resist abrasion for soft-shell durability. Japanese METI product safety standards govern nylon import specifications.
Polycarbonate holds the largest volume position, though leather commands the steepest unit economics.
End User:
Customer type determines feature prioritization across connectivity, weight minimization, and aesthetic signaling.
- Travelers:Leisure and vacation purchasers prioritize TSA-compatible locks and expandable capacity. China's expanding middle class drives this segment through e-commerce penetration.
- Business Professionals:Frequent flyers demand integrated USB charging, garment sleeves, and cabin-compliant dimensions. This group adopts GPS tracking modules fastest in the United States.
- Adventurers:Outdoor and expedition users require waterproof sealing and reinforced corner guards. Technical specifications align with New Zealand and Australian trekking tourism.
- Students:Price-sensitive academic buyers favor wheeled backpacks and convertible duffels. India's Flipkart logistics expansion captures this cohort through direct-to-consumer pathways.
Travelers constitute the broadest base, while Business Professionals generate the highest per-unit margins.
Distribution Channel:
Supply concentration varies between digital-native fulfillment and tactile premium retail experiences.
- Online Retail:Direct-to-consumer platforms collapse wholesale markups and accelerate design feedback loops. Amazon India and Tmall dominate volume for polyester and polycarbonate luggage in their respective markets.
- Specialty Stores:Curated showrooms with trained staff and repair services retain margin concentration for aluminum and full-grain leather offerings. Japan's department store culture sustains this channel for premium cabin luggage.
- Department Stores:Multi-brand floor space with seasonal promotions captures mid-tier gift purchases. Macy's in the United States and John Lewis in the United Kingdom anchor this segment.
- Airports:Last-minute convenience retail and duty-free positioning target impulse upgrades and replacement scenarios. Dubai International Airport and Singapore Changi drive highest per-square-foot luggage revenue globally.
Online Retail captures volume leadership, while Specialty Stores defend profitability for premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium luggage commands 40% higher unit prices in Japan than in India, yet volume growth concentrates in emerging Asian markets where e-commerce penetration is rewriting distribution economics. This pricing-power asymmetry shapes how manufacturers allocate capacity between margin defense and volume capture.
China
Domestic outbound tourism and live-stream commerce on Tmall and JD.com are elevating polycarbonate hard-shell purchases among the expanding middle class. GB/T national luggage quality specifications govern product safety certification for domestic sales. Manufacturing clusters in Guangdong and Zhejiang provinces supply assembly capacity for both domestic brands and export orders.
United States
FAA carry-on dimensional enforcement across major carriers favors size-optimized polycarbonate designs with strength-to-weight ratios that maximize packing volume. Business-leisure trip blending accelerates backpack adoption for sub-72-hour journeys. California and New York Metro area consumers drive premium smart-luggage adoption with integrated GPS tracking modules.
Germany
EU REACH substance restrictions on phthalate plasticizers and flame retardants are raising reformulation costs for interior lining materials. ECHA compliance timelines create first-mover advantages for certified suppliers of zipper compounds and surface coatings. Bavaria-based specialty retailers sustain margin concentration for aluminum and full-grain leather cabin luggage.
Japan
METI product safety standards govern import specifications for nylon and polycarbonate constructions, adding compliance layers for foreign brands. Department store culture in Tokyo and Osaka sustains premium retail channels with trained staff and repair services. Japanese travelers prioritize TSA-compatible locks and expandable capacity for leisure vacation purchases.
India
Flipkart and Amazon India logistics expansion is opening direct-to-consumer pathways for mid-premium brands previously locked out of physical retail. Price-sensitive academic buyers in Maharashtra and Karnataka favor wheeled backpacks and convertible duffels. BIS certification requirements for imported luggage are tightening quality thresholds for entry-level polyester offerings.
Global Luggage Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying certified polymers and hardware assemblies. The vendor base organizes around three archetypes: heritage luxury houses with leather-accented polycarbonate lines, digital-native direct-to-consumer brands collapsing wholesale markups, and mass-market manufacturers optimizing Guangdong contract capacity. Dominant competitive moves include strategic partnerships with airline loyalty programs and portfolio diversification into smart-luggage modules with subscription-enabled revenue streams.
Within the heritage platform tier, Samsonite International S.A. and LVMH Moet Hennessy Louis Vuitton SE exemplify controlled retail network strategies across Asia and Europe. Among digital-native challengers, Away occupies a position leveraging social-media acquisition without physical store overhead. These three anchors illustrate how scale, brand equity, and channel innovation separate margin capture from volume commoditization.
| Leading Market Players |
|---|
| Safari Industries India Ltd. |
| Tumi |
| Samsonite International S.A. |
| Victorinox |
| Rimowa |
| LVMH Moet Hennessy Louis Vuitton SE |
| IT Luggage Limited |
| Away |
| VIP Industries Ltd. |
| Others |
Value Chain & Pricing Dynamics
Guangdong and Zhejiang province manufacturing clusters anchor global polycarbonate luggage assembly, concentrating margin capture with brands that control certified polymer sourcing and direct-to-consumer channel access rather than wholesale-dependent competitors.
Pricing Analysis
Configured-to-order leather-accented polycarbonate lines command substantial premiums over standard hard-shell sets. Three-tier pricing structure across premium, standard, and economy levels separates Tumi-grade business-traveler specialization from mass-market ABS alternatives. Cost compression in entry-level polyester tiers is intensifying because Flipkart and Amazon India logistics expansion exposes budget manufacturers to direct price comparison. Students and price-sensitive leisure travelers in India exhibit highest price sensitivity, while Japanese department store shoppers purchasing aluminum cabin luggage show lowest elasticity.
Supply Chain Analysis
Extended payment terms from East Asian contract manufacturers to European and North American brand headquarters have become standard working-capital instruments. Assembly draws from China, Vietnam, and Bangladesh, with polycarbonate resin, aluminum extrusions, and full-grain hides as critical inputs. Single-source vulnerability concentrates in Guangdong zipper and wheel hardware suppliers. Distribution runs through direct-to-consumer platforms for volume, specialty retail for premium margin defense.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Luggage is transitioning toward platform-economics dynamics where smart-luggage ecosystems with subscription-enabled GPS tracking create recurring revenue attachment to hardware sales.
For Market Incumbents: Entrench control over certified polymer supply chains and captive retail networks across Asia to defend against digital-native challengers collapsing wholesale markups. Backward integration into REACH-compliant zipper compound manufacturing protects margin pools as ECHA enforcement tightens. Prioritize smart-luggage module R&D to capture subscription revenue streams before connectivity commoditizes. For New Entrants and Emerging Players: Mid-premium hard-shell sets for India's Flipkart and Amazon India ecosystems represent the most penetrable entry point, given logistics expansion and previously locked-out physical retail access. Hybrid work-travel backpack configurations for sub-72-hour business-leisure trips in Germany and the United States offer second white-space targeting. Launch through live-stream commerce partnerships on Tmall and JD.com to bypass legacy wholesale channel barriers. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native brands with proven customer acquisition economics and smart-luggage technology stacks rather than legacy soft-shell manufacturers carrying wholesale inventory overhang. Long-term viability favors platform-integrated players with recurring revenue potential over pure hardware vendors. Monitor FAA carry-on dimensional harmonization progress as signal for SKU complexity reduction enabling scaled production efficiency.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Luggage Module Integration | GPS tracking and biometric lock subscriptions create recurring revenue beyond unit sales for business travelers. |
| Direct-to-Consumer Channel Expansion | Live-stream commerce on Tmall and JD.com collapses wholesale markups and accelerates design feedback loops. |
| REACH Compliance Certification | ECHA-certified zipper compounds and surface coatings create first-mover advantages in European market access. |
| Backpack Configuration Development | Ergonomic frame systems with laptop compartments capture hybrid work-travel demand in United States and Germany. |
| Airport Retail Partnership | Dubai International Airport and Singapore Changi positioning targets impulse upgrades with highest per-square-foot revenue. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with luggage brand procurement directors, Guangdong contract manufacturing facility managers, Tmall and JD.com category buyers, airline baggage operations executives, and EU regulatory compliance officers. Secondary validation drew from customs and trade data, SEC 10-K filings for publicly traded luggage manufacturers, ECHA substance restriction databases, and FAA regulatory filings. Bottom-up shipment volume estimates triangulated against top-down consumer spending models.
Calibration against historical polycarbonate resin price volatility and airline baggage fee structure changes anchored projections across the analysis window. Segmentation dimensions modeled include product type (hard shell, backpack, soft shell, duffel), material specification (polycarbonate, leather, polyester, nylon), end-user archetype (travelers, business professionals, adventurers, students), and distribution channel (online retail, specialty stores, department stores, airports). CAGRs derived from weighted average of demand elasticity coefficients and supply capacity expansion timelines, with e-commerce penetration curves and domestic outbound tourism recovery as luggage-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in benzene and bisphenol-A feedstock prices, airline liability limitation policies, or China-originated logistics disruption would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timelines and consumer channel migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luggage
Global Smart Luggage and Tracking Technologies Market
Luggage
Second Hand Bag Market
Luggage
Camera Bag Market
Luggage
Travel Bag Market
Luggage
Global Outdoor Sports Luggage Market
Luggage
Trolley Bags Market
Luggage
Trunks Market
Luggage
Global Premium Luggage Market
Luggage
Kids Backpack Market
Luggage
Sewing Bags Market
Luggage
Travel and Business Bags Market
Luggage
Laptop Messenger Bags Market
Luggage
Laptop Carry Case Market
Luggage
Sports Luggage Market
Luggage
School Bags Market
Luggage
Backpack Market