
 Asia-Pacific Wireless Audio Market | 2026-2036
Asia-Pacific Wireless Audio Market Size, Share, and Industry Trends Forecast 2026-2036
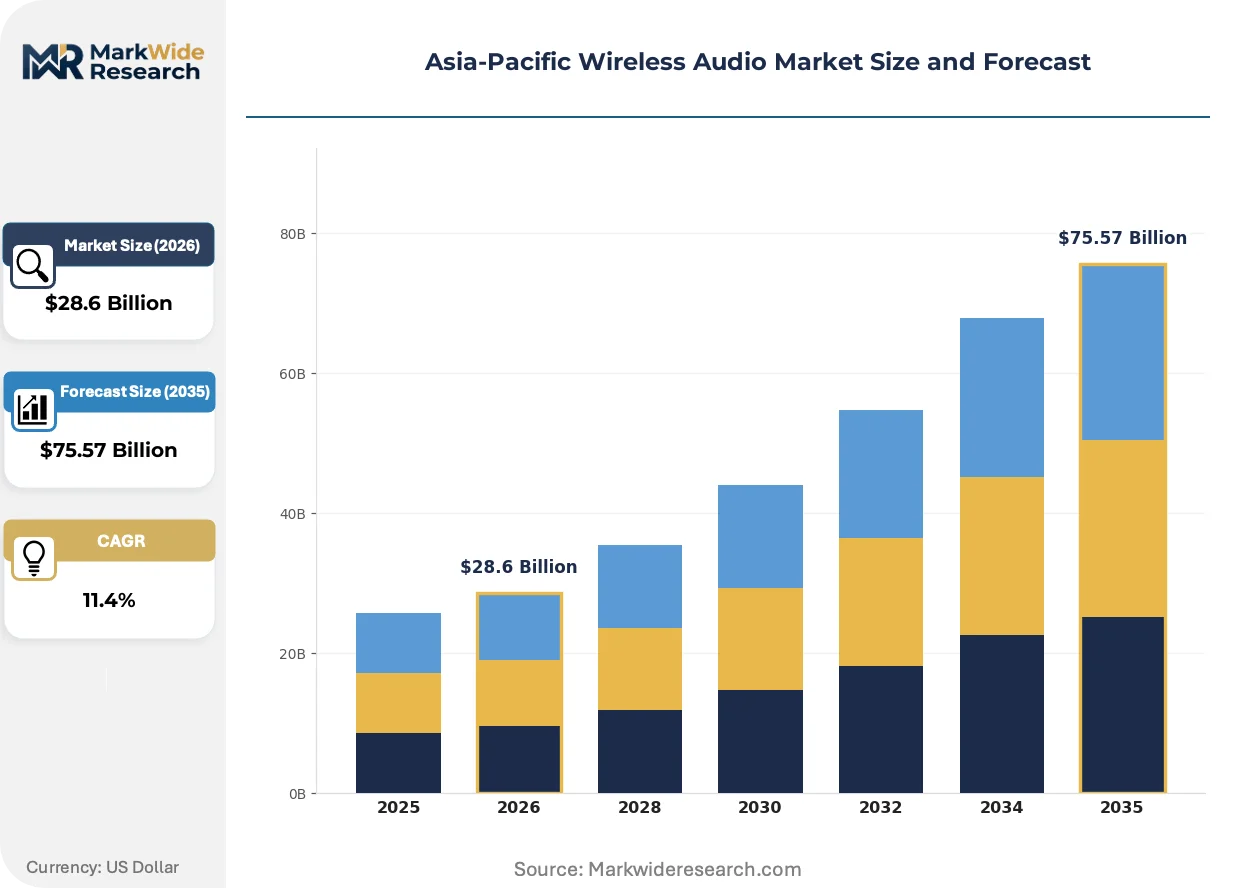
Asia-Pacific Wireless Audio Market Outlook
Gaming and fitness applications are consolidating as the fastest-expanding end-use verticals across the Asia-Pacific Wireless Audio Market. Samsung Electronics leverages its Galaxy ecosystem integration to anchor premium TWS share in South Korea and Southeast Asia. Xiaomi Corporation competes aggressively on cost-engineered earbuds, while Sony Group Corporation differentiates through proprietary LDAC codec licensing and studio-grade tuning.
Asia-Pacific wireless audio encompasses earphones, headphones, speakers, and soundbars that transmit audio signals via Bluetooth, Wi-Fi, or proprietary RF protocols without physical cabling, typically operating in the 2.4 GHz ISM band with codec support for AAC, SBC, and aptX. These devices serve consumer entertainment, commercial conferencing, and educational multimedia delivery. Earbuds command the largest volume pool due to smartphone bundling and gym-centric lifestyles, while soundbars capture disproportionate margin from home-theater upgrades in Japan and Australia. Bluetooth retains dominance in connectivity, though Wi-Fi-enabled multi-room systems are gaining traction in premium residential installations across Singapore and Hong Kong.
China's MIIT enforces SRRC certification for radio transmission equipment, while South Korea's Radio Waves Act mandates KC mark compliance for electromagnetic compatibility. Japan's TELEC certification adds another layer for ultra-low latency gaming peripherals entering Tokyo and Osaka retail channels. Stakeholders must monitor evolving codec royalty structures and regional RF spectrum reallocations that could render existing chipset architectures non-compliant.
Market Dynamics
China's MIIT spectrum reallocation and South Korea's tightened Radio Waves Act emission ceilings are compressing chipset design cycles across the Asia-Pacific Wireless Audio Market. Shenzhen-based OEMs now face simultaneous compliance deadlines across three certification regimes while scaling low-latency gaming SKUs for Bengaluru and Seoul.
Growth Catalysts
- Low-latency codec proliferation:aptX Adaptive and LC3plus adoption in gaming headsets is pulling replacement cycles forward in South Korea and Japan. Professional esports leagues mandate sub-40ms latency thresholds.
- India's PLI scheme for electronics manufacturing:The Production Linked Incentive scheme is attracting TWS assembly capacity to Tamil Nadu and Karnataka, reducing import dependency for domestic brands.
- Fitness-integrated wearables:Heart-rate monitoring earbuds are capturing gym subscription bundling deals across Australia's metropolitan fitness chains.
Market Restraints
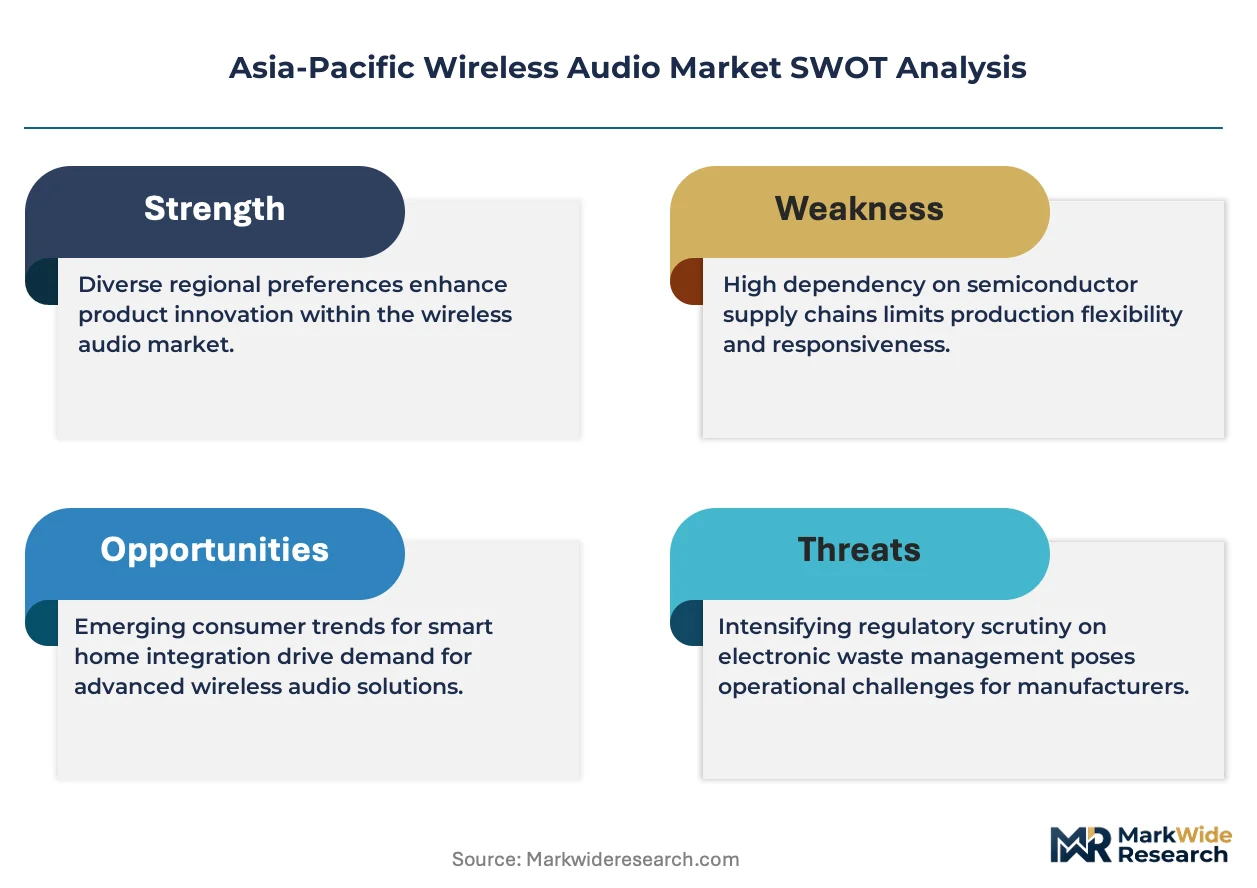
- Silicon supply concentration:Advanced Bluetooth 5.3 SoC fabrication depends on TSMC's 22nm capacity in Taiwan, creating allocation risk during smartphone chipset priority ramps.
- Codec royalty stacking:LDAC, aptX, and AAC licensing layers add cumulative per-unit costs that compress margin on sub-$50 retail SKUs.
- RF interference densification:2.4 GHz ISM band saturation in Shenzhen-Guangzhou and Seoul metropolitan zones degrades connection stability for unlicensed spectrum devices.
Strategic Opportunities
- Vietnam manufacturing corridor:Labor cost arbitrage and emerging electronics zones near Hanoi offer TWS assembly alternatives to Pearl River Delta concentration.
- Enterprise conferencing retrofit:Wi-Fi 6E-enabled speakerphone systems are displacing legacy PSTN hardware in Singapore and Hong Kong financial services offices.
- Japan's TELEC fast-track pathway:Streamlined certification for ultra-low latency gaming peripherals accelerates Tokyo retail placement versus standard 90-day review cycles.
Industry Challenges
- Multi-regional certification parallelism:Simultaneous SRRC, KC mark, and TELEC testing requires dedicated regulatory affairs teams that smaller Shenzhen OEMs cannot staff.
- Acoustic tuning talent scarcity:Studio-grade DSP calibration expertise concentrates in Tokyo, Seoul, and Taipei, forcing brands to outsource or poach at premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wireless Audio Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headphones, Earbuds, Speakers, Soundbars Connectivity: Bluetooth, Wi-Fi, NFC, AirPlay End User: Consumers, Commercial, Educational, Corporate Application: Streaming, Gaming, Fitness, Multimedia |
| Companies Covered | Apple Inc., Samsung Electronics, Sony Group Corporation, Harman International Industries, Xiaomi Corporation, Oppo, Realme, LG Electronics, Audio-Technica Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wireless Audio Market Strategic Shifts
Spatial audio rendering and head-tracking sensors are migrating from premium cinema installations into mass-market TWS form factors across Asia-Pacific. Codec efficiency wars and RF spectrum management are reshaping competitive differentiation.
LC3plus codec implementation is expanding into mid-tier TWS and gaming headset segments previously served by SBC and baseline AAC. Indian smartphone bundling programs and Southeast Asian e-commerce flash sales are accelerating adoption at sub-$30 price points. This compression of premium audio features into economy hardware is expanding into margin structures that legacy Bluetooth Classic vendors cannot defend.
South Korea's Radio Waves Act amendments now mandate stricter electromagnetic compatibility testing for 2.4 GHz devices with transmit power exceeding 10 mW. Gaming peripheral manufacturers must redesign antenna architectures to meet revised KC mark thresholds before Seoul retail distribution. Japanese importers are leveraging TELEC's mutual recognition agreements to streamline parallel compliance, while Chinese brands absorb retesting costs to maintain cross-border shipment velocity.
Direct-to-consumer subscription bundling is displacing traditional electronics retail for wireless audio in Australia and Singapore. Fitness chains and telecom operators now white-label TWS as membership perks, compressing standalone retail traffic. This channel migration is most visible in Sydney and Melbourne, where gym-centric lifestyle brands capture younger demographics ahead of established consumer electronics chains.
Asia-Pacific Wireless Audio Market Segmentation
Segmentation in Asia-Pacific wireless audio reveals how codec licensing costs, RF compliance regimes, and end-use latency requirements split demand across hardware tiers. Buyers in Seoul and Shenzhen prioritize different connectivity stacks than those in Bengaluru or Tokyo.
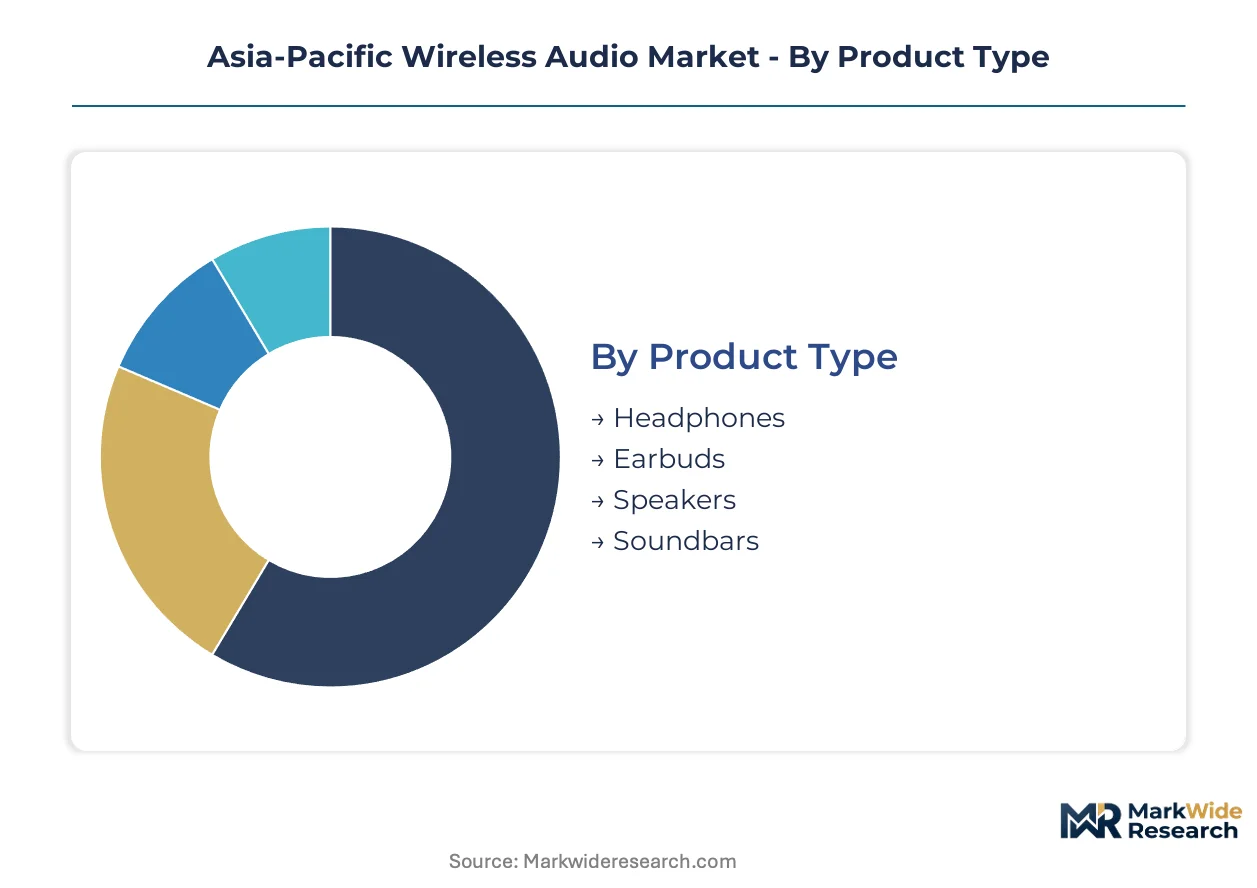
Product Type:
Buyers select form factors based on portability needs, acoustic isolation requirements, and smartphone ecosystem bundling incentives.
- Earbuds:True wireless stereo devices with MEMS microphones and touch controls dominate smartphone accessory sales. Demand concentrates in China's Shenzhen-Guangzhou manufacturing corridor for export to Southeast Asian e-commerce channels, driven by gym-centric lifestyle adoption and telecom operator bundling programs.
- Headphones:Over-ear and on-ear designs with active noise cancellation target commuters and esports participants. Professional gaming leagues in South Korea and Japan mandate sub-40ms latency thresholds that pull replacement cycles forward for premium circumaural units.
- Speakers:Portable and stationary units with Bluetooth or Wi-Fi connectivity serve residential and outdoor use cases. India's Bengaluru-Hyderabad IT clusters generate commercial procurement for conference room installations.
- Soundbars:Slim audio systems designed for television audio enhancement capture disproportionate margin from home-theater upgrades in Japan and Australia.
Volume sits with Earbuds; growth tilts toward Soundbars.
Connectivity:
Protocol selection determines RF certification burden, royalty stacking exposure, and interoperability with installed device bases.
- Bluetooth:Dominant protocol operating in the 2.4 GHz ISM band with codec support for AAC, SBC, aptX, and LDAC. China's MIIT enforces SRRC certification for all radio transmission equipment, compressing design cycles for Shenzhen-based OEMs.
- Wi-Fi:Enables multi-room synchronization and higher bandwidth for lossless audio streaming. Premium residential installations across Singapore and Hong Kong favor Wi-Fi 6E-enabled speakerphone systems for enterprise conferencing retrofits.
- NFC:Near-field pairing simplifies device handshake for non-technical users. Japan's retail channels leverage NFC for tap-to-connect demonstrations in Tokyo and Osaka electronics districts.
- AirPlay:Apple's proprietary streaming protocol locks in iOS ecosystem users. Australia's direct-to-consumer subscription bundling channels favor AirPlay-compatible white-label TWS for fitness chain partnerships.
Bluetooth commands installed base; Wi-Fi claims steepest expansion trajectory.
End User:
Procurement authority and budget cycles differentiate consumer impulse purchases from institutional tender processes.
- Consumers:Individual purchasers responding to retail promotion, smartphone bundling, and lifestyle brand marketing. Flash sales on Southeast Asian e-commerce platforms accelerate adoption at sub-$30 price points.
- Commercial:Hospitality, retail, and fitness operators sourcing durable audio hardware with centralized fleet management. Australia's metropolitan fitness chains white-label heart-rate monitoring earbuds as membership perks.
- Educational:Schools and universities procuring multimedia delivery systems for hybrid learning infrastructure. India's PLI scheme for electronics manufacturing attracts TWS assembly capacity to Tamil Nadu for domestic brand supply.
- Corporate:Enterprise IT departments standardizing on unified communications peripherals. Singapore and Hong Kong financial services offices displace legacy PSTN hardware with Wi-Fi 6E-enabled conferencing systems.
Consumers drive unit volume; Corporate delivers margin expansion.
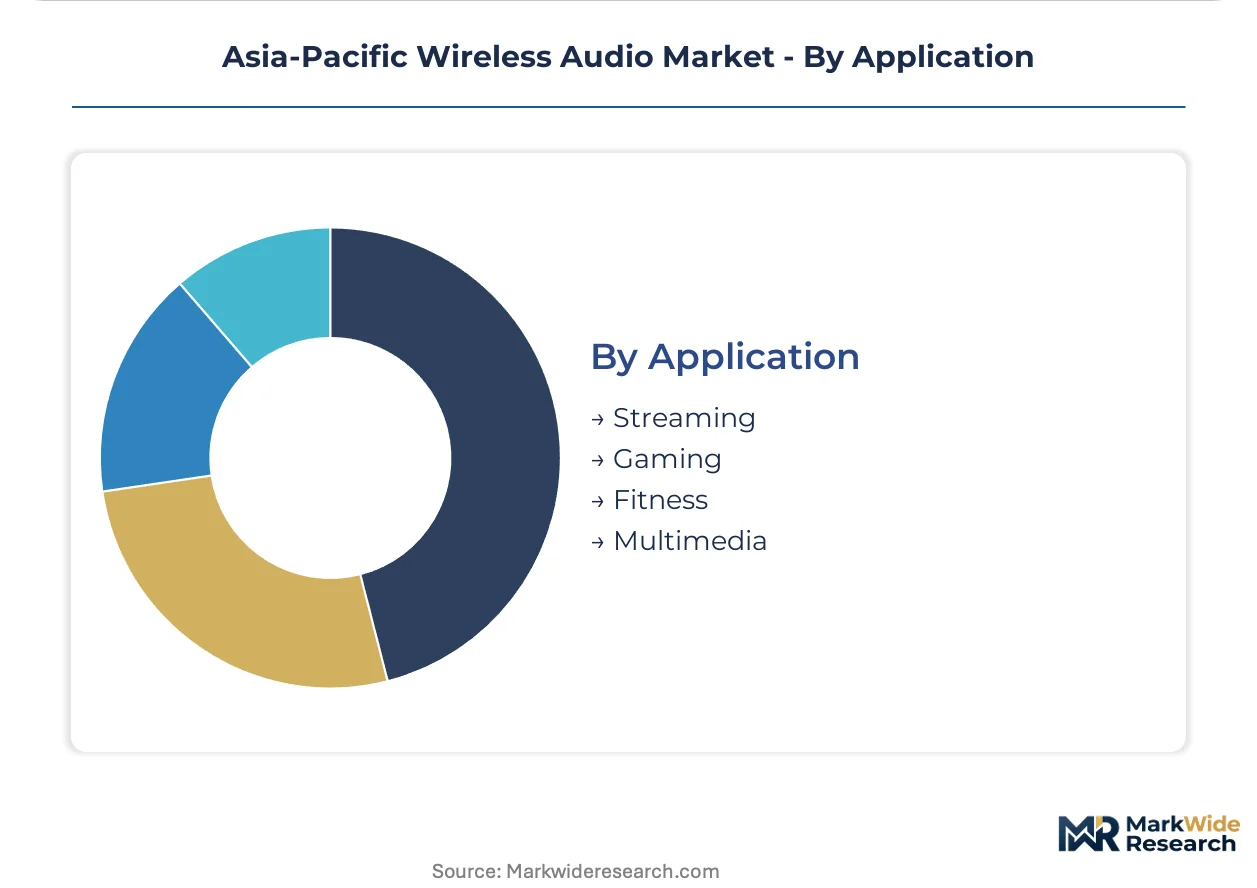
Application:
Use-case latency requirements and content format preferences segment hardware performance tiers.
- Streaming:Music and video consumption prioritizing codec efficiency and battery longevity. LC3plus implementation expands into mid-tier TWS segments previously served by SBC and baseline AAC.
- Gaming:Competitive and casual play demanding sub-40ms audio latency for positional awareness. South Korea's Radio Waves Act mandates stricter electromagnetic compatibility testing for 2.4 GHz devices exceeding 10 mW transmit power.
- Fitness:Activity-integrated audio with biometric sensors and sweat resistance. Heart-rate monitoring earbuds capture gym subscription bundling deals across Australia's metropolitan fitness chains.
- Multimedia:General-purpose audio for video conferencing, content creation, and casual consumption. Spatial audio rendering and head-tracking sensors migrate from premium cinema installations into mass-market TWS form factors.
Streaming anchors baseline volume; Gaming and Fitness together expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone anchors contract manufacturing concentration, while South Korea's Songdo Free Economic Zone pulls R&D investment for low-latency codec development.
China
MIIT's SRRC certification mandates compress design cycles for radio transmission equipment. Shenzhen-Guangzhou corridor dominates TWS export manufacturing for Southeast Asian e-commerce channels. Guangdong province absorbs retesting costs to maintain cross-border shipment velocity under tightened spectrum rules.
South Korea
Radio Waves Act amendments enforce stricter electromagnetic compatibility thresholds for 2.4 GHz devices exceeding 10 mW transmit power. Seoul's Gangnam district retail channels prioritize sub-40ms latency gaming peripherals for esports league compliance. Incheon Free Economic Zone concentrates antenna architecture redesign facilities.
Japan
TELEC certification adds compliance layers for ultra-low latency gaming peripherals entering Tokyo-Osaka retail channels. METI streamlines mutual recognition agreements to accelerate parallel compliance with regional regimes. Akihabara electronics district serves as demonstration hub for NFC tap-to-connect retail experiences.
India
PLI scheme for electronics manufacturing attracts TWS assembly capacity to Tamil Nadu and Karnataka. TRAI spectrum management frameworks shape RF device import protocols. Bengaluru-Hyderabad IT clusters generate commercial procurement for enterprise conferencing installations.
Australia
Direct-to-consumer subscription bundling displaces traditional electronics retail across Sydney and Melbourne metropolitan zones. TGA-equivalent electromagnetic standards govern device safety for fitness-integrated wearables. Fitness chain white-label partnerships capture younger demographics ahead of established consumer electronics channels.
Asia-Pacific Wireless Audio Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with ecosystem-integrated electronics conglomerates commanding premium TWS positioning while Shenzhen-based OEMs capture volume through cost-engineered SKUs. The vendor base organizes around three strategic archetypes: vertically integrated semiconductor-to-retail conglomerates, audio-focused heritage brands with studio-grade tuning expertise, and contract manufacturers serving telecom operator bundling programs. M&A activity concentrates on codec licensing portfolios and acoustic tuning talent acquisition, while capacity expansion targets Vietnam's emerging electronics zones as Pearl River Delta labor costs escalate.
Among ecosystem-integrated conglomerates, Apple Inc. and Samsung Electronics exemplify platform-lock-in strategies that monetize through hardware-software-service bundles. Sony Group Corporation occupies a position within the heritage audio specialist tier, leveraging proprietary codec licensing to differentiate studio-grade positioning. Xiaomi Corporation represents the cost-engineering archetype, anchoring volume share through aggressive price positioning in telecom operator and e-commerce flash sale channels.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics |
| Sony Group Corporation |
| Harman International Industries |
| Xiaomi Corporation |
| Oppo |
| Realme |
| LG Electronics |
| Audio-Technica Corporation |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between SRRC-compliant export SKUs and domestic-only hardware splits both margin structures and component sourcing across the Asia-Pacific Wireless Audio Market. Premium TELEC-certified gaming peripherals command 40-60% assembly cost premiums over baseline Bluetooth SKUs, while Shenzhen OEMs absorb retesting cycles to maintain cross-border velocity under MIIT's tightened spectrum rules.
Pricing Analysis
Short lead-time premiums for KC mark-compliant gaming headsets pull pricing 15-25% above spot inventory from non-certified parallel imports. Three-tier pricing structure across premium, standard, and economy levels reflects codec licensing stacks—LDAC and aptX Adaptive tiers separate from baseline SBC configurations. Pricing pressure stems from royalty stacking on sub-$50 retail SKUs where cumulative per-unit licensing erodes margin. Enterprise procurement in Singapore and Hong Kong shows lowest price sensitivity due to Wi-Fi 6E conferencing retrofit mandates.
Supply Chain Analysis
Certification gating through SRRC, KC mark, and TELEC regimes concentrates qualified assembly capacity in China's Guangdong province, Vietnam's Bac Ninh corridor, and Taiwan's Hsinchu Science Park. Advanced Bluetooth 5.3 SoC fabrication draws from TSMC's 22nm node, while MEMS microphone and antenna module sourcing rests on Murata and AAC Technologies. Single-source vulnerability sits with TSMC capacity allocation during smartphone chipset priority ramps. Distribution runs through telecom operator bundling programs and Southeast Asian e-commerce flash sale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical-integration momentum is accelerating as ecosystem players pursue captive codec licensing portfolios to escape royalty stacking and compress BOM costs. Control over LDAC, aptX, or proprietary low-latency protocol stacks represents the decisive upstream lever.
For Market Incumbents: Acquire acoustic tuning talent pools concentrated in Tokyo, Seoul, and Taipei before compensation inflation locks out mid-tier brands. Defend premium positioning by embedding heart-rate biometric sensors into fitness-integrated SKUs ahead of white-label gym chain entrants. Lock TSMC 22nm allocation through multi-year foundry service agreements before smartphone SoC ramps crowd out Bluetooth controller capacity. For New Entrants and Emerging Players: Telecom operator bundling programs in India and Southeast Asia offer the most penetrable channel for sub-$30 TWS volume entry. Target Tamil Nadu PLI-subsidized assembly capacity to match landed cost structures of Shenzhen exporters. Lead with LC3plus codec implementation at economy price points where legacy SBC vendors cannot defend feature parity. For Investors and Strategic Acquirers: Re-rating potential sits with heritage audio specialists holding proprietary codec licensing and studio-grade DSP calibration expertise given spatial audio migration into mass-market form factors. Long-term viability favors acquirers of TELEC fast-track certification capabilities and antenna architecture IP. Watch India's PLI scheme disbursement velocity as inflection signal for assembly capacity relocation from Pearl River Delta.| Strategic Initiative | Industry Significance |
|---|---|
| Codec Licensing Acquisition | Proprietary LDAC or aptX portfolios eliminate per-unit royalty stacking and defend margin in sub-$50 tiers. |
| TELEC Fast-Track Certification Investment | Streamlined 60-day Tokyo retail placement accelerates gaming peripheral distribution versus standard 90-day KC mark cycles. |
| Vietnam Manufacturing Footprint Expansion | Bac Ninh and Hai Phong electronics zones offer labor cost arbitrage as Shenzhen wages escalate. |
| Biometric Sensor Integration | Heart-rate monitoring earbuds capture Australia's gym subscription bundling deals ahead of pure-play audio brands. |
| Wi-Fi 6E Enterprise Conferencing Systems | Singapore and Hong Kong financial services displacement of PSTN hardware opens speakerphone margin pools. |
Study Parameters
Document review covered MIIT SRRC certification databases, South Korea Radio Waves Act amendment filings, and TELEC mutual recognition agreements, complemented by interviews with RF compliance consultants, Shenzhen OEM procurement directors, and Bengaluru enterprise IT managers. Secondary validation drew from customs export records, semiconductor foundry capacity disclosures, and telecom operator bundling contract terms. Bottom-up SKU-level build-up and top-down regional demand aggregation were cross-referenced for triangulation.
Historical shipment data was cross-referenced against panel input from codec licensors and acoustic engineering firms. The analytical framework modeled product type, connectivity protocol, end-user procurement authority, and application latency requirements across the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic indicators and regulatory implementation timelines. RF spectrum reallocation schedules and PLI scheme capacity absorption curves served as industry-specific forecast inputs.
Caveats apply where MIIT spectrum reallocation, TSMC node allocation priority shifts, or India's PLI disbursement delays could materially shift the outlook. Forecasts reflect assumptions on certification timeline standardization and codec royalty rate stability. Stakeholders should weight assumptions against their own operating context and regulatory compliance capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Audio Equipment
Electronic Drums Market
Audio Equipment
Canada Gaming Headsets Market
Audio Equipment
Global Audio Devices and Components Market
Audio Equipment
Gaming Earbuds Market
Audio Equipment
Home Audio Equipment Market
Audio Equipment
Motorcycle Audio Systems Market
Audio Equipment
Europe Audio Products Market
Audio Equipment
United States Gaming Headsets Market
Audio Equipment
Germany Radio Headset Market
Audio Equipment
Wireless Audio Devices Market
Audio Equipment
Speaker Driver Market
Audio Equipment
Studio Headphones Market
Audio Equipment
Hi-Fi Cartridges Market
Audio Equipment
Consumer Audio Market
Audio Equipment
India Wireless Audio Market
Audio Equipment
Monitoring Sound Box for Playing Market