
 Toothbrush Market | 2026-2036
Toothbrush Market Size, Share, and Industry Trends Forecast 2026-2036
Toothbrush Market Intelligence
Chinese nylon-bristle producers are rebalancing capacity toward bio-based filaments as resin costs fluctuate. Colgate-Palmolive Company leverages its pharmacy channel density across Latin America to sustain recurring manual brush volumes. Procter & Gamble Company anchors premium positioning through its oscillating-rotating electric platforms. Koninklijke Philips N.V. dominates the sonic segment with brush heads that command higher replacement pull-through.
A toothbrush is a handheld oral hygiene instrument comprising a head with tufted filaments and an ergonomically shaped handle, typically injection-molded from polypropylene or biodegradable polymers with filaments of nylon-612 or PBT ranging 0.15–0.25 mm in diameter, designed to mechanically disrupt dental plaque and stimulate gingival tissue. Its primary commercial purpose spans daily consumer self-care and professional prophylactic support in dental practice settings. Electric toothbrush platforms capture the fastest-expanding margin pool as consumers trade up from manual equivalents, while orthodontic care applications within the application dimension attract specialized brush geometries with premium pricing. Sonic toothbrush variants lead technology-driven replacement cycles due to their fluid-dynamic cleaning action.
FDA regulates toothbrush claims and material safety for products entering the United States, while REACH and the EU Green Deal restrict certain plastic additives and mandate recyclability disclosures in Europe. China's SAMR enforces GB standards for imported oral care devices, shaping market access for foreign manufacturers. Stakeholders must monitor evolving biopolymer certification schemes and regional extended-producer-responsibility rules to secure supply continuity and shelf placement.
Market Dynamics
Electric toothbrush platforms are compressing replacement cycles and capturing margin from manual equivalents as consumers prioritize gum health outcomes over basic plaque removal.
Growth Catalysts
- REACH compliance requirements:European mandates for recyclability disclosures and restricted plastic additives are accelerating bio-based filament R&D among nylon-612 producers seeking premium positioning.
- Orthodontic patient volumes:Specialized brush geometries for bracket and aligner care command price premiums and create recurring attachment sales in dental practice channels.
- Sonic fluid-dynamic cleaning:The technology's demonstrable efficacy in interdental plaque disruption is driving trade-up from oscillating-rotating platforms among adult gum-care seekers.
Market Restraints
- Petrochemical input volatility:Polypropylene and PBT resin prices fluctuate with crude oil markets, compressing margin stability for injection-molded handle producers.
- Single-source filament concentration:Nylon-612 supply clusters among Chinese petrochemical complexes, exposing brush manufacturers to geographic concentration risk.
- Biodegradable polymer performance gaps:Current PLA and starch-based handles lack the moisture resistance and structural integrity of conventional polypropylene in humid bathroom environments.
Strategic Opportunities
- Germany's pharmacy channel density:Professional recommendation networks in urban households remain underexploited for premium electric platform penetration.
- Subscription replacement models:Direct-to-consumer brush head auto-replenishment bypasses retail slotting fees and locks in lifetime value.
- China's dual carbon goals:National targets for carbon neutrality are creating procurement preference for manufacturers with certified biopolymer supply chains.
Industry Challenges
- Biopolymer certification timelines:Obtaining TÜV or BPI compostability credentials for novel handle materials extends new product introduction cycles by 12-18 months.
- Cross-border GB standard navigation:SAMR enforcement of imported oral care device standards creates compliance complexity for foreign manufacturers entering China.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toothbrush Market |
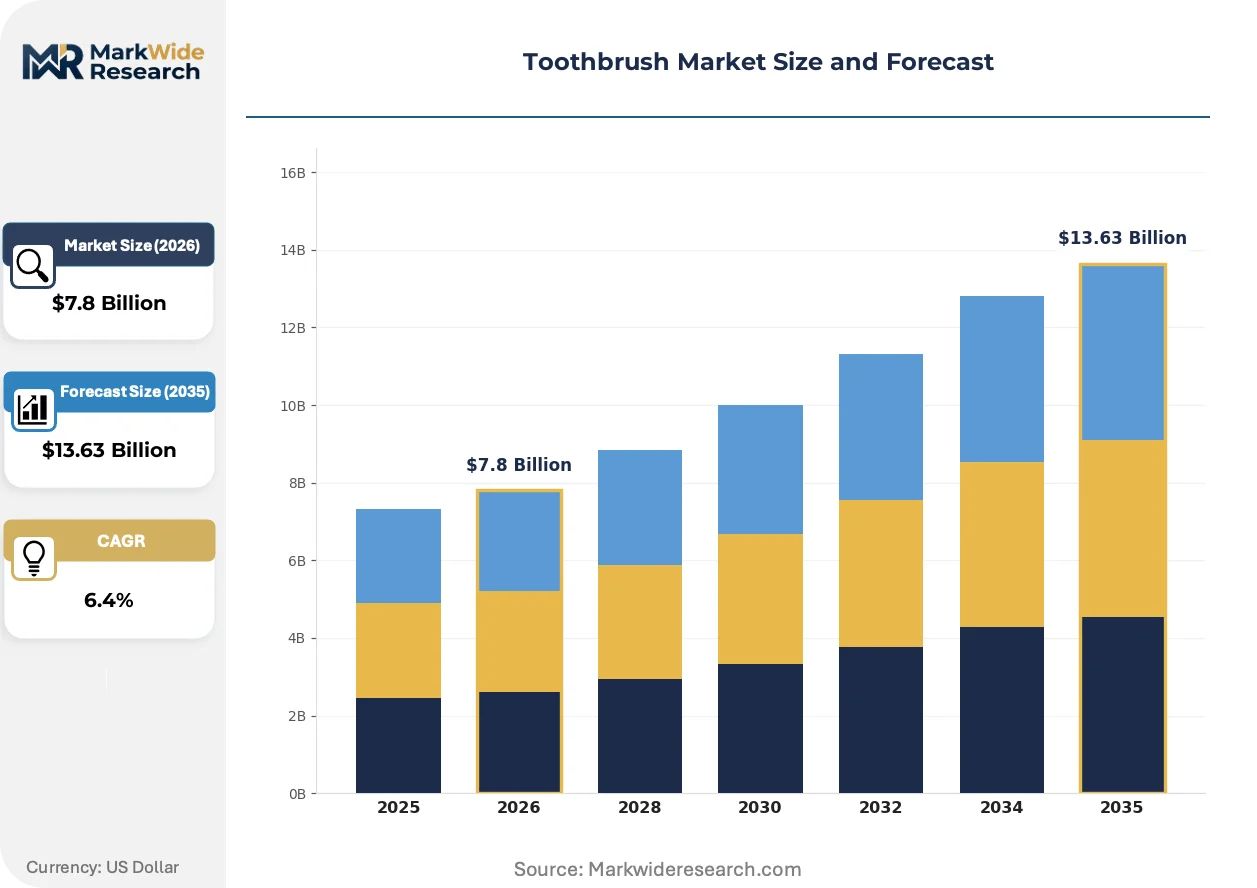
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Toothbrush, Electric Toothbrush, Battery-Powered Toothbrush, Sonic Toothbrush, Interdental Brushes Application: Plaque Removal, Gum Care, Whitening, Orthodontic Care, Sensitive Teeth, Breath Freshening End User: Adults, Children, Elderly, Dental Clinics, Orthodontists Distribution Channel: Supermarkets, Pharmacies, Online Retailers, Specialty Stores, Dental Offices |
| Companies Covered | Colgate-Palmolive Company, Procter & Gamble Company, Koninklijke Philips N.V., Church & Dwight Co., Inc., Unilever PLC, Panasonic Corporation, FOREO, Lion Corporation, Haleon plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toothbrush Market Strategic Shifts & Innovations
Sensor-integrated brushing systems and sustainable material transitions are restructuring competitive advantage around data-driven compliance and circular design credentials rather than mechanical efficacy alone.
Artificial intelligence-enabled pressure sensors and real-time brushing guidance is rewriting how consumers engage with daily oral care routines. Adult users in the United States and Germany are adopting these connected platforms at rates that outpace basic electric segment growth. The technology is rewriting margin structures by converting one-time hardware sales into ongoing subscription and data-service revenue streams.
REACH restrictions on microplastic additives and the EU Green Deal's recyclability mandates are forcing reformulation of conventional bristle polymers and handle colorants. European manufacturers must now disclose full material composition and end-of-life pathways to maintain shelf placement. Sonic toothbrush variants face particular scrutiny due to their complex multi-material construction and battery integration.
Dental practitioners in China and Germany are increasingly specifying brush head types and replacement intervals during routine prophylaxis appointments. This professional channel recommendation is displacing unaided retail selection and compressing price sensitivity among insured patient populations. The shift is most visible in urban Chinese households where dental clinic density has expanded rapidly.
Toothbrush Market Segmentation
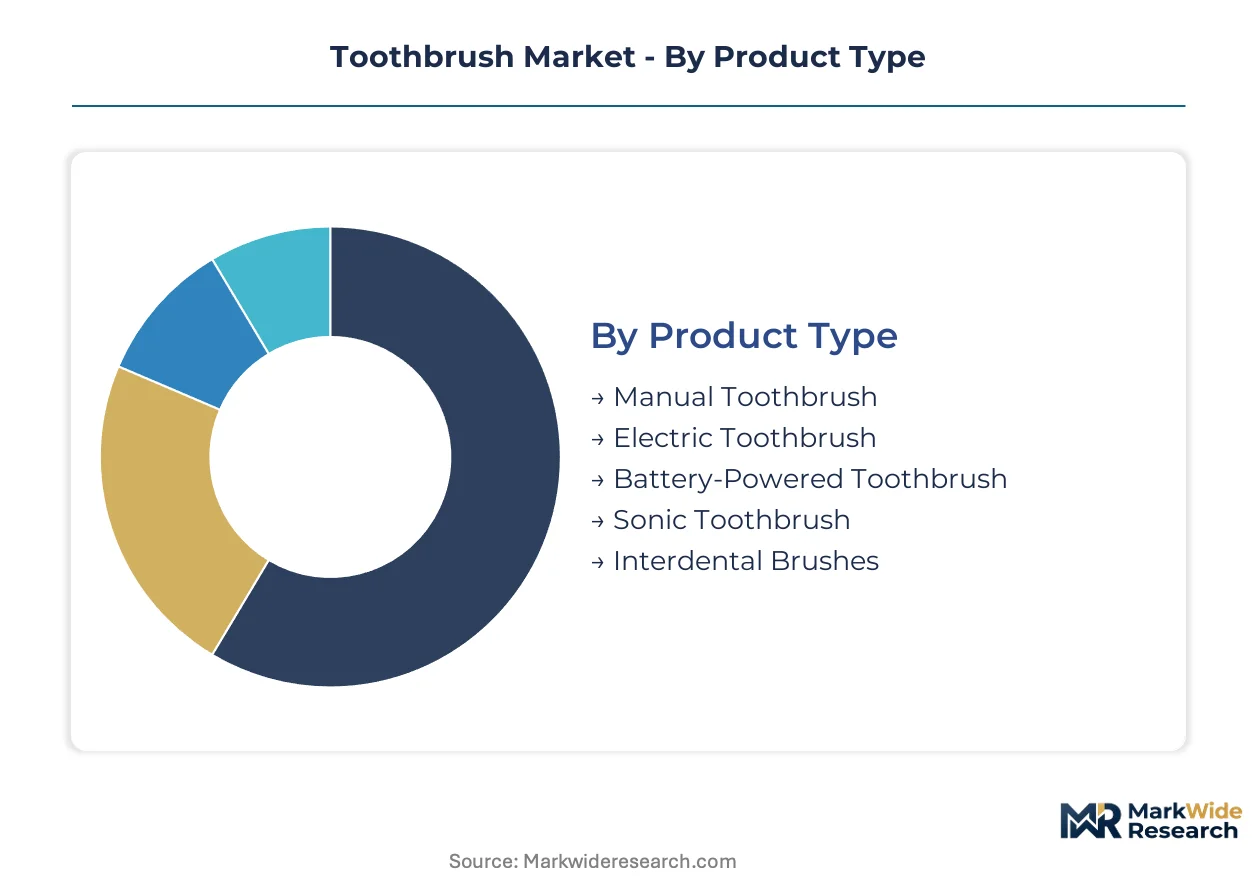
Toothbrush purchasing decisions split across functional need, clinical endorsement, and channel accessibility. Manufacturers align R&D spend and distribution contracts to these fracture lines, recognizing that gum-care seekers, orthodontic patients, and subscription-driven households rarely overlap in buying behavior.
Product Type:
Technology sophistication separates replacement-cycle economics and margin capture across this dimension.
- Manual Toothbrush:Injection-molded polypropylene handles with nylon-612 or PBT filaments dominate unit volume in emerging economies and price-sensitive demographics. Demand concentrates in Latin American pharmacy chains where Colgate-Palmolive leverages existing shelf density to sustain recurring purchases despite electric encroachment.
- Electric Toothbrush:Oscillating-rotating and sonic motor platforms command premium positioning through demonstrable plaque reduction efficacy. Procter & Gamble anchors this segment in US and German urban households where gum health outcomes drive trade-up from manual equivalents.
- Battery-Powered Toothbrush:Lower-cost motorization without recharge infrastructure suits travel and secondary household use cases. Penetration remains strongest in mid-tier Chinese cities where consumers experiment with powered cleaning before committing to full electric systems.
- Sonic Toothbrush:Fluid-dynamic cleaning action generates higher interdental efficacy scores in clinical validation studies. Koninklijke Philips N.V. dominates replacement brush head pull-through with proprietary snap-fit geometries that lock in lifetime value.
- Interdental Brushes:Cylindrical or tapered filament configurations target periodontal maintenance and implant care. Dental clinic recommendation drives adoption among elderly populations in Germany and Japan where professional prophylaxis frequency exceeds global averages.
Volume sits with Manual Toothbrush; growth tilts toward Sonic Toothbrush.
Application:
Clinical outcome specificity determines brush geometry, filament stiffness, and pricing tier.
- Plaque Removal:Standard tuft configurations with medium-durometer filaments address baseline oral hygiene needs. This application captures broadest demographic coverage but faces margin compression as consumers migrate to outcome-specific alternatives.
- Gum Care:Soft filament arrays and pressure-sensitive electric platforms target gingival health maintenance. Sonic variants with real-time feedback sensors are expanding fastest among insured US adults receiving periodontal risk assessments during routine dental visits.
- Whitening:Abrasive filament coatings and specialized polishing heads address extrinsic stain removal. Demand clusters in urban Chinese households where aesthetic dentistry penetration drives accessory brush head purchases.
- Orthodontic Care:V-shaped tuft patterns and proxy brush configurations navigate bracket and wire geometries. Dental practitioners in Germany increasingly specify replacement intervals during adjustment appointments, compressing price sensitivity.
- Sensitive Teeth:Ultra-soft filaments and desensitizing filament coatings reduce dentin hypersensitivity triggers. Pharmacy channel placement in France and Switzerland supports professional recommendation networks.
- Breath Freshening:Tongue-cleaning ridges and antimicrobial filament treatments target volatile sulfur compound reduction. This application trails other segments in dedicated SKU development, typically bundling with whitening or gum-care positioning.
Orthodontic Care commands steepest expansion trajectory as bracket patient volumes rise; Plaque Removal retains largest installed base.
End User:
Age-linked oral health conditions and professional procurement authority segment buying criteria.
- Adults:Primary revenue pool spanning preventive maintenance through therapeutic intervention. Electric platform adoption concentrates among 35-55 age cohorts in the United States and Germany prioritizing gum health outcomes.
- Children:Smaller handle scales, character licensing, and parental safety concerns shape product development. Chinese one-child policy legacy households show elevated willingness-to-pay for premium pediatric electric systems.
- Elderly:Arthritis-adapted grips, enlarged handles, and interdental specialization address dexterity limitations. Japan's aging demographic sustains dedicated SKU development from domestic manufacturers.
- Dental Clinics:Bulk procurement of disposables and patient giveaway brushes for prophylaxis compliance. Clinic density expansion in urban China is displacing retail selection for insured patient populations.
- Orthodontists:Specialized brush prescriptions bundled with treatment contracts. This channel commands highest per-patient attachment revenue through recurring replacement head scheduling.
Adults generate current revenue concentration; Orthodontists drive fastest lifetime value expansion.
Distribution Channel:
Channel selection determines price transparency, professional endorsement leverage, and subscription convertibility.
- Supermarkets:Mass-market manual brush volume with high SKU proliferation and promotional intensity. Margin pressure from private-label alternatives limits manufacturer investment in this channel.
- Pharmacies:Professional recommendation networks and insurance reimbursement integration support premium positioning. Germany's pharmacy density enables electric platform penetration through dentist-pharmacist referral loops.
- Online Retailers:Direct-to-consumer subscription models bypass slotting fees and capture replacement-cycle economics. US and Chinese e-commerce penetration enables brush head auto-replenishment with highest lifetime value realization.
- Specialty Stores:Curated premium and sustainable material offerings for environmentally conscious segments. Limited footprint concentrates in Nordic urban centers with strong circular economy consumer sentiment.
- Dental Offices:Point-of-care specification and immediate fulfillment during prophylaxis appointments. This channel shows fastest growth in China where clinic construction outpaces retail infrastructure expansion.
Supermarkets retain unit volume leadership; Dental Offices gain share fastest through professional channel displacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nylon-612 filament production clusters in Chinese petrochemical complexes supply brush manufacturers worldwide, while polypropylene resin pricing ties handle economics to crude oil markets in the United States and Germany.
United States
Insured adults receiving periodontal risk assessments drive electric platform trade-up from manual equivalents. FDA regulates material safety and therapeutic claims for devices entering the market. Greater Boston hosts sensor-integrated brushing system development for real-time pressure feedback applications.
China
Urban dental clinic density expansion displaces retail selection among insured patient populations. SAMR enforces GB standards for imported oral care devices, shaping foreign manufacturer market access. Yangtze River Delta biopolymer producers rebalancing capacity toward certified filament supply chains.
Germany
Pharmacy channel density enables professional recommendation networks for premium electric penetration. REACH mandates recyclability disclosures and restricted plastic additives for shelf placement maintenance. Bavaria concentrates orthodontic brush specification through dental practitioner networks during adjustment appointments.
Japan
Aging demographic sustains dedicated SKU development for arthritis-adapted grips and interdental specialization. METI oversees industrial standards for oral care device materials and performance claims. Kansai region domestic manufacturers lead elderly-specific handle ergonomics and filament softness calibration.
Brazil
Pharmacy chain shelf density sustains recurring manual brush volumes despite electric encroachment. ANVISA regulates product registration and material safety for oral hygiene devices. São Paulo serves as Latin American distribution hub for injection-molded handle supply to regional markets.
Toothbrush Market Key Industry Players
Global majors compete with regional champions across technology sophistication and channel access dimensions. The vendor base stratifies into three tiers: multinational consumer goods conglomerates with oscillating-rotating and sonic platforms, specialized electric device manufacturers with proprietary brush head geometries, and regional manual brush producers leveraging pharmacy density. Strategic moves concentrate on subscription replacement model deployment and biopolymer certification acquisition for European shelf placement.
Among diversified consumer goods conglomerates, Colgate-Palmolive Company and Procter & Gamble Company exemplify the pharmacy-channel and premium-electric archetypes respectively, while Koninklijke Philips N.V. occupies a position within the specialized technology tier through sonic platform dominance. These three anchors represent distinct competitive vectors: manual volume sustainability through professional channel leverage, oscillating-rotating efficacy positioning in insured adult segments, and fluid-dynamic cleaning technology with proprietary replacement economics.
| Leading Market Players |
|---|
| Colgate-Palmolive Company |
| Procter & Gamble Company |
| Koninklijke Philips N.V. |
| Church & Dwight Co., Inc. |
| Unilever PLC |
| Panasonic Corporation |
| FOREO |
| Lion Corporation |
| Haleon plc |
| Others |
Cost & Logistics Intelligence
Insured urban households in the United States and Germany anchor premium electric toothbrush demand, locking in subscription-based pricing models that bundle hardware with recurring brush head replenishment. This buyer concentration enables manufacturers to extract lifetime value through locked-in replacement cycles while manual brush segments compete on pharmacy shelf price alone.
Pricing Analysis
Warranty and service bundling separates premium electric platforms from unbundled manual equivalents, with sonic variants commanding highest attachment economics through proprietary snap-fit geometries. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service inclusion. Cost compression in manual segments is intensifying because private-label alternatives erode brand premiums at mass retail. Price-sensitive emerging-market households in Latin America and mid-tier Chinese cities drive volume in unpowered categories, while insured periodontal patients in Germany and the United States show lowest price sensitivity for gum-care-specific electric systems.
Supply Chain Analysis
TÜV and BPI compostability certifications gate European shelf placement, extending new product introduction timelines and favoring incumbents with established biopolymer credentialing. Nylon-612 filament production clusters in Chinese petrochemical complexes, while polypropylene resin supply draws from United States and German petrochemical infrastructure. Single-source concentration in Yangtze River Delta filament production creates geographic vulnerability for brush manufacturers. Distribution runs through pharmacy chains in Germany, direct-to-consumer subscriptions in the United States, and expanding dental clinic networks in urban China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where REACH recyclability mandates and FDA material safety requirements create regulatory moats that disadvantage unqualified entrants. The capital burden of biopolymer certification and extended-producer-responsibility compliance favors scaled players with existing credentialing infrastructure.
For Market Incumbents: Deepen backward integration into certified biopolymer supply chains to secure European shelf placement against REACH enforcement tightening. Lock in dental clinic channel control through exclusive brush head specification contracts before clinic density expansion in China saturates professional recommendation networks. Sensor-integrated platform proliferation from specialized electric device manufacturers threatens oscillating-rotating incumbents in the United States and Germany. For New Entrants and Emerging Players: AI-enabled pressure sensor technology offers a technology-first wedge into the premium adult gum-care segment where real-time brushing guidance commands subscription convertibility. Target underpenetrated orthodontic patient management software integrations as a go-to-market angle, bundling brush head auto-replenishment with aligner treatment tracking. Germany's pharmacy-dentist referral loops and China's clinic construction boom represent the most penetrable white-space geographies for professional channel entry. For Investors and Strategic Acquirers: The window for entry favors specialized electric device manufacturers with proprietary brush head geometries and locked-in replacement economics over diversified consumer goods conglomerates with stagnant manual volumes. Long-term viability hinges on subscription model maturity and biopolymer certification scalability across the next decade. Watch for SAMR enforcement shifts on imported oral care device standards as the signal for China market access inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Certification Acquisition | TÜV and BPI credentials secure European pharmacy shelf placement under REACH mandates. |
| Subscription Replacement Model Deployment | Direct-to-consumer auto-replenishment bypasses retail slotting fees and captures lifetime value in US urban households. |
| Dental Clinic Channel Expansion | Professional specification during prophylaxis appointments displaces unaided retail selection in China's insured urban populations. |
| Sensor-Integrated Platform Development | Real-time pressure feedback converts one-time hardware sales into ongoing data-service revenue streams. |
| Orthodontic Brush Geometry Specialization | V-shaped tuft configurations command premium pricing through practitioner-specified replacement intervals in Germany. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across toothbrush brand managers, dental clinic procurement leads, pharmacy category buyers, biopolymer R&D directors, and SAMR compliance consultants. FDA 510(k) submissions, REACH registration databases, ECHA substance dossiers, and Chinese customs import records provided material flow validation. Bottom-up unit volume modeling and top-down value triangulation reconciled manufacturer shipment data with retail audit tracking.
Data-stream reconciliation across the analysis window applied growth rate derivation from historical trajectory analysis and segment-specific driver elasticity. Segmentation dimensions spanned product type, application, end user, and distribution channel, with additional modeling of regional regulatory cluster effects. CAGRs were computed from normalized baseline values through iterative convergence testing against primary interview guidance. Electric platform replacement cycle compression and biopolymer certification timeline delays served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to EU Green Deal implementation timelines and sudden petrochemical input price shocks beyond historical volatility bands. Forecasts reflect documented assumptions regarding clinic channel expansion rates and subscription model adoption elasticities. A model refresh is warranted upon material change in SAMR enforcement posture on imported oral care device standards or REACH microplastic additive restriction expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Grooming Products
North America Hair Styling Tools Market
Personal Grooming Products
Global Consumer Use IPL Hair Removal Devices Market
Personal Grooming Products
Antibacterial Soap Market
Personal Grooming Products
Personal Lubricants Market
Personal Grooming Products
Floss Picks Market
Personal Grooming Products
Smart Electric Toothbrush Market
Personal Grooming Products
North America Mosquito Repellent Market
Personal Grooming Products
Back Massager Market
Personal Grooming Products
Underarm Sweat Pads Market
Personal Grooming Products
Global Canes and Walking Sticks Market
Personal Grooming Products
Shoe Deodorizer Market
Personal Grooming Products
Disposable Razor Market
Personal Grooming Products
Latin America Professional Liquid Soap Market
Personal Grooming Products
Massage Fascia Gun Market
Personal Grooming Products
Global Sex Toys Market
Personal Grooming Products
Gel Socks Market