
 Lip and Cheek Tint Market | 2026-2036
Lip and Cheek Tint Market Size, Share, and Industry Trends Forecast 2026-2036
Lip and Cheek Tint Market Foresight
ISO 22716 Good Manufacturing Practices certification is reorganizing competitive entry in the Lip and Cheek Tint Market, raising barriers for smaller manufacturers while rewarding compliant incumbents. Charlotte Tilbury leverages its vertically integrated supply chain to control quality from pigment sourcing to finished goods. Benefit Cosmetics anchors its position through specialized dual-use formulations that merge lip and cheek functionality. Fenty Beauty differentiates via inclusive shade ranges developed through intensive R&D investment.
A lip and cheek tint is a pigmented cosmetic formulation, typically water-based or emulsified, designed to deposit semi-sheer to buildable color on both lip and facial skin through staining or film-forming mechanisms. Liquid formulations dominate volume due to their lightweight spreadability and compatibility with precision applicator systems, though balm formats are gaining traction among consumers prioritizing skin-conditioning benefits. The ingredient type dimension shows natural and vegan segments expanding fastest as clean beauty preferences reshape procurement patterns across retail and professional channels. Professional use applications command premium positioning within spa and cosmetology service environments where durability and blendability determine repurchase rates.
The US FDA oversees cosmetic safety labeling under the Federal Food, Drug, and Cosmetic Act, while the EU's REACH framework restricts specific colorants and preservatives, directly constraining formulation palettes available to manufacturers. South Korea's MFDS maintains stringent safety assessments that simultaneously elevate product credibility for export markets. Stakeholders must monitor evolving ingredient ban lists across multiple jurisdictions to preempt reformulation costs and maintain market access.
Market Dynamics
Social commerce platforms are concentrating demand discovery and purchase behavior among Gen Z consumers, compressing traditional retail intermediaries while elevating formulation transparency as a non-negotiable purchase criterion.
Growth Catalysts
- REACH compliance:The EU's tightening cosmetic ingredient standards are forcing manufacturers to reformulate with safer colorants, creating competitive separation for early adopters who preempt regulatory deadlines.
- K-beauty diffusion:South Korea's beauty innovation cluster generates formulation trends that migrate through Southeast Asian markets into Western retail channels within 18-24 month cycles.
- Water-based stains:Lightweight film-forming technologies reduce transfer and extend wear time, satisfying professional cosmetology requirements for durability in spa service environments.
Market Restraints
- Pigment supply concentration:Synthetic iron oxide and carmine production clusters in China and Peru, exposing formulators to raw material availability shocks and price volatility.
- Preservative restrictions:REACH and FDA limitations on parabens and formaldehyde-releasers constrain shelf-life extension, forcing shorter production runs and higher per-unit costs.
- Clean beauty substitution:Consumer preference migration toward uncolored balms and skincare-hybrid products threatens volume in conventional tint categories.
Strategic Opportunities
- India's emerging middle class:Underpenetrated professional salon channels in tier-2 cities offer first-mover positioning for dual-use formulations adapted to humid climates.
- ISO 22716 certification:Good Manufacturing Practice accreditation opens institutional procurement channels in hospital gift shops and airline duty-free networks.
- Vegan pigment innovation:Biotechnology-derived colorants from microalgae fermentation converge with clean beauty positioning to capture premium shelf space in specialty retail.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in emulsion stability across lip and facial skin pH differentials commands salary premiums that strain R&D budgets.
- Multi-jurisdiction compliance:Simultaneous navigation of FDA labeling, REACH substance restrictions, and South Korea MFDS safety assessments extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip and Cheek Tint Market |
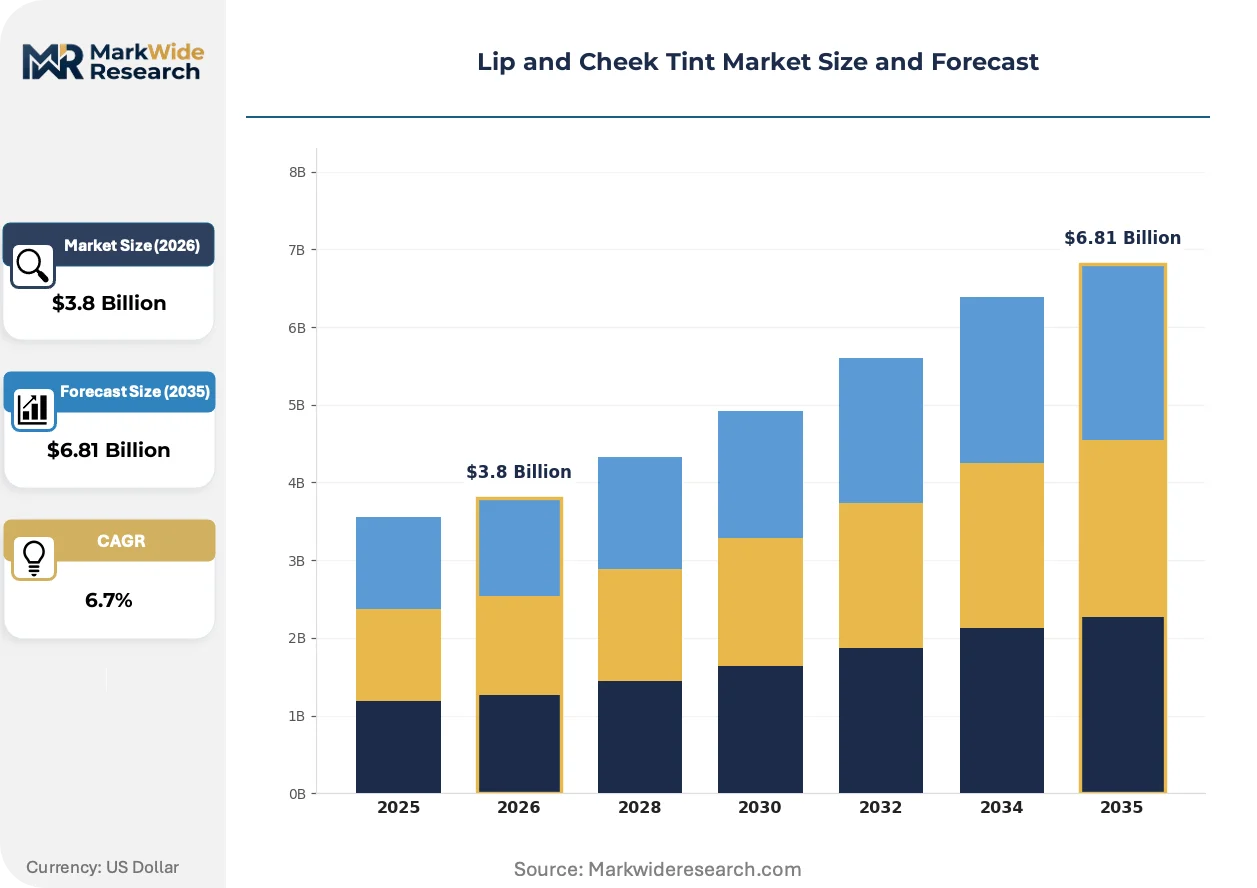
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Cream, Balm, Stick Ingredient Type: Natural, Synthetic, Organic, Vegan Application: Personal Use, Professional Use, Spa, Cosmetology Packaging Type: Tubes, Jars, Pumps, Pencils |
| Companies Covered | Charlotte Tilbury, Benefit Cosmetics, L'Oréal Paris, Glossier, Fenty Beauty, MAC Cosmetics, Etude House, NYX Professional Makeup, Maybelline New York, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip and Cheek Tint Market Shifts & Advancements
Formulation chemistry and distribution architecture are undergoing parallel transformation, with biotechnology-derived inputs and algorithmic commerce platforms displacing legacy petrochemical supply chains and retail intermediaries.
Biotechnology-derived pigments from microalgae and bacterial fermentation are bifurcating the colorant supply base. Clean beauty retailers in Germany and Scandinavia are accelerating procurement of these inputs at 3x the rate of conventional synthetics. This shift is compressing demand for petroleum-derived colorants while creating captive supply relationships between biotech startups and mid-tier cosmetic manufacturers.
REACH authorization requirements for nanomaterial colorants are tightening pre-market notification obligations. The industrial consequence is a 40% reduction in new pigment introductions since 2020, with reformulation costs concentrated among smaller manufacturers lacking regulatory affairs departments. Professional salon brands are responding by consolidating supplier relationships with ISO-certified contract manufacturers who maintain dedicated compliance teams.
Algorithmic curation on short-form video platforms is collapsing the traditional awareness-to-purchase funnel. Gen Z consumers in South Korea and the United States discover formulations through creator tutorials and purchase via embedded storefronts, bypassing department store beauty counters. This channel compression is most visible in the 18-24 demographic, where platform-native brands capture trial at one-third the customer acquisition cost of legacy competitors.
Lip and Cheek Tint Market Segmentation
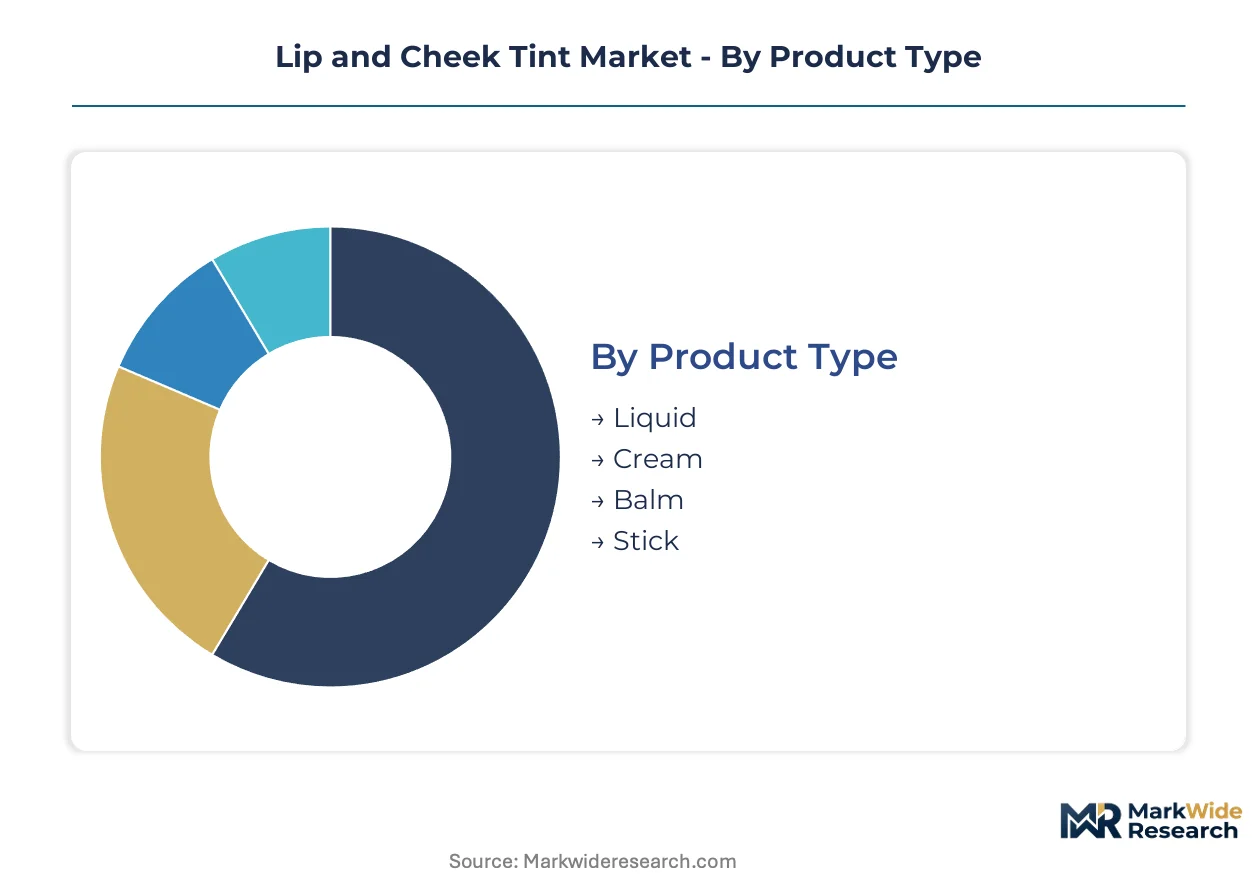
Segmentation in the Lip and Cheek Tint Market reveals divergent compliance burdens and formulation capabilities across product architectures. Regulatory thresholds for colorant safety and manufacturing certification reshape competitive viability within each category, determining which manufacturers can access institutional procurement channels versus direct-to-consumer retail.
Product Type:
REACH authorization requirements for film-forming polymers and volatile organic compounds create divergent compliance pathways across physical formats, with water-based systems facing lighter notification obligations than solvent-heavy alternatives.
- Liquid:Water-based or emulsified formulations utilizing precision applicator systems for semi-sheer deposition. Demand concentrates in South Korea's professional cosmetology sector where lightweight spreadability and buildable coverage determine repurchase rates among spa service providers.
- Balm:Oil-wax matrices incorporating skin-conditioning agents for dual-function lip and facial application. Adoption accelerates among German and Scandinavian clean beauty retailers prioritizing petroleum-free bases and biotechnology-derived emollients.
- Cream:Thickened emulsion systems offering higher pigment load than liquid equivalents. The format appeals to professional makeup artists requiring blendable, long-wear coverage for editorial and bridal applications.
- Stick:Solid anhydrous formats with concentrated color payoff and minimal packaging complexity. Convenience-driven personal use segments in humid climates favor this format for portability and reduced leakage risk.
Established volume favors Liquid; emerging adoption favors Balm.
Ingredient Type:
Cost tier stratification separates premium-positioned biotech inputs from commodity petrochemical colorants, with certification premiums widening margin spreads between clean beauty and conventional formulations.
- Natural:Plant-derived pigments and waxes subject to agricultural supply variability. Procurement concentrates through Peru's carmine harvest cycles and India's annatto extraction facilities, exposing formulators to seasonal price shocks.
- Vegan:Biotechnology-derived colorants from microalgae fermentation and bacterial expression systems. South Korean manufacturers lead commercial scale-up, capturing premium shelf space in EU specialty retail under REACH-compliant supply chains.
- Synthetic:Petroleum-derived iron oxides and lakes offering batch consistency and cost efficiency. China's production clusters dominate global supply, though MFDS pre-market notification requirements extend lead times for Korean-market entry.
- Organic:Certified agricultural inputs meeting COSMOS or USDA organic standards. The segment commands price premiums in French and German pharmacy channels where certification documentation determines listing eligibility.
Cost efficiency anchors Synthetic volume; certification premiums drive Vegan expansion.
Application:
Customer type divergence separates institutional procurement with ISO 22716 requirements from unregulated personal consumption, creating distinct sales motion and margin architectures.
- Professional Use:Salon and cosmetology service environments where durability under lighting and climate stress determines product selection. India's tier-2 cities present underpenetrated channels for dual-use formulations adapted to humid operating conditions.
- Personal Use:Direct consumer purchase through retail and social commerce platforms. Gen Z discovery behavior on short-form video platforms compresses traditional awareness-to-purchase funnels, elevating formulation transparency as a non-negotiable criterion.
- Spa:Institutional wellness environments requiring GMP certification for gift shop and amenity procurement. ISO 22716 accreditation opens airline duty-free and hospital retail networks where compliance documentation gates market access.
- Cosmetology:Licensed practitioner channels emphasizing blendability across lip and facial skin pH differentials. Formulation chemist scarcity in this specialized competency commands salary premiums that strain mid-tier R&D budgets.
Volume concentration sits with Personal Use; margin expansion favors Professional Use.
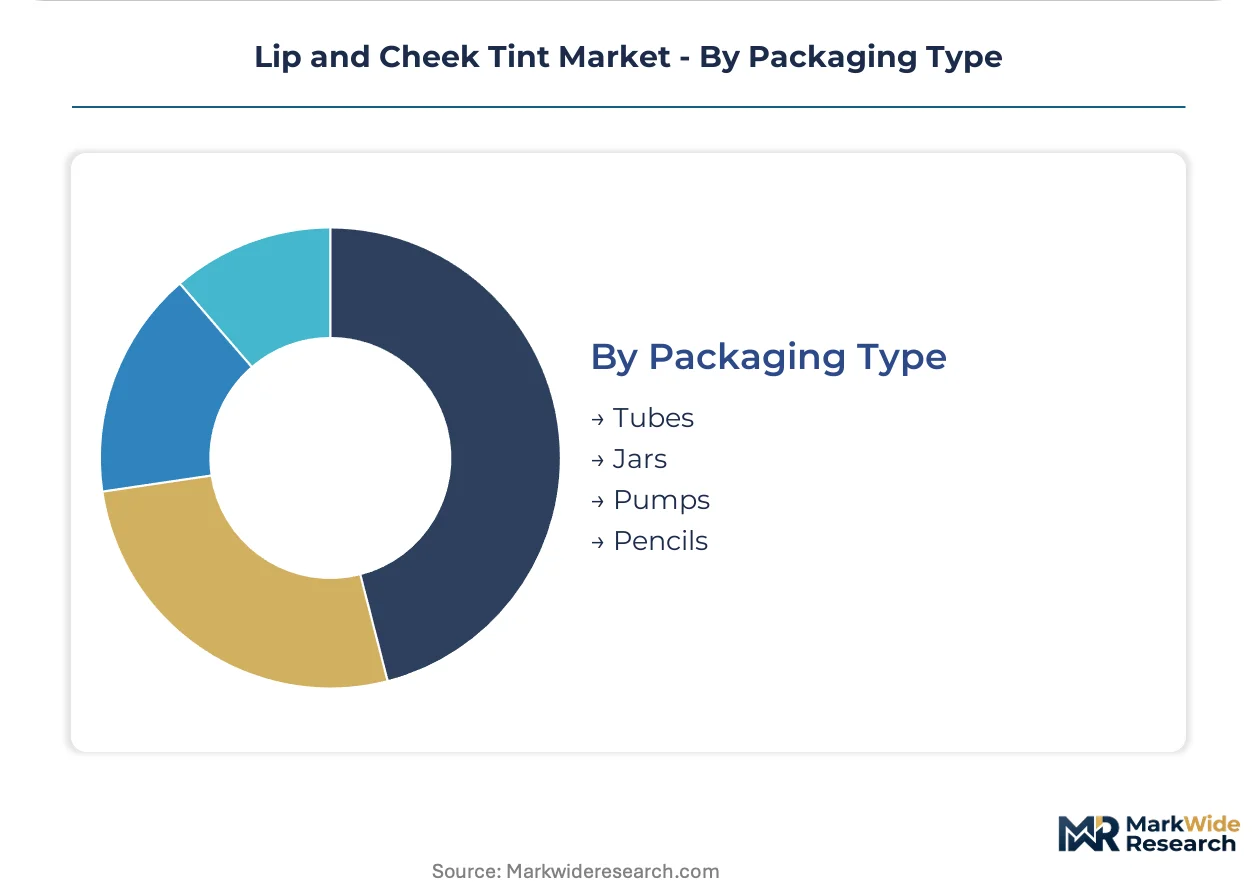
Packaging Type:
Supply concentration in molded plastic and aluminum components shapes cost structures, with sustainability mandates in the EU and South Korea accelerating material transition timelines.
- Tubes:Flexible laminated or mono-material structures for liquid and cream dispensing. The format dominates mass-market volume through compatibility with automated filling lines and minimal shipping cube.
- Pumps:Metered-dose systems for controlled product release in professional settings. Precision mechanics add per-unit cost that restricts adoption to premium salon and spa positioning.
- Jars:Wide-mouth rigid containers for balm and cream access with finger or spatula application. EU Single-Use Plastics Directive pressure is forcing material transitions to glass and post-consumer recycled content.
- Pencils:Extruded or molded stick formats with built-in applicator precision. The configuration reduces packaging mass for sustainability scoring but limits formula flexibility to anhydrous systems.
Operational scale favors Tubes; sustainability alignment favors Jars.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional cosmetology buyers concentrate procurement decisions in Seoul's Gangnam beauty cluster, where formulation innovation diffuses through Southeast Asian distributor networks within 18-month cycles. Social commerce discovery behavior among Gen Z consumers in Los Angeles and London compresses traditional retail intermediaries, elevating ingredient transparency as a purchase threshold.
South Korea
Seoul's Gangnam district anchors global K-beauty formulation trends, with professional spa channels driving dual-use tint adoption. MFDS maintains stringent pre-market safety assessments that simultaneously elevate export credibility for EU and US entry. Busan-Ulsan manufacturing corridors concentrate biotechnology-derived pigment scale-up for vegan formulation lines.
United States
Los Angeles and New York Metro social commerce ecosystems concentrate Gen Z discovery behavior through algorithmic video platforms. FDA cosmetic labeling enforcement under the Federal Food, Drug, and Cosmetic Act governs colorant safety claims. California's clean beauty regulatory pressure exceeds federal baselines, forcing reformulation timelines that cascade to national distribution.
Germany
Scandinavian-exporting clean beauty retailers in Hamburg and Berlin accelerate procurement of REACH-compliant vegan formulations. ECHA authorization requirements for nanomaterial colorants constrain new pigment introductions, compressing supplier relationships toward ISO-certified contract manufacturers. Bavaria's pharmaceutical-grade manufacturing heritage transfers GMP discipline to cosmetic production.
India
Tier-2 city salon channels in Maharashtra and Karnataka present underpenetrated demand for humidity-adapted dual-use formulations. BIS cosmetic standards alignment with EU REACH frameworks facilitates export positioning for domestic manufacturers. Mumbai's specialty chemical cluster supplies natural pigment extraction from annatto and turmeric harvest cycles.
France
Parisian pharmacy channels command certification premiums for COSMOS-standard organic formulations, with Île-de-France distribution networks penetrating EU-wide specialty retail. ANSM cosmetic safety surveillance maintains post-market vigilance that shapes formulation conservatism among domestic manufacturers. Lyon-based biotech startups pioneer microalgae-derived colorant fermentation for luxury positioning.
Lip and Cheek Tint Market Competitive Landscape
Player mix skews toward multinational conglomerates with captive R&D infrastructure and ISO-certified manufacturing footprints. Mid-tier specialists compete through biotechnology-derived ingredient positioning and social commerce-native distribution. Three archetypes dominate: vertically integrated luxury houses controlling pigment sourcing through finished goods, clean beauty specialists leveraging vegan certification premiums, and platform-native brands capturing Gen Z trial via algorithmic discovery. Competitive moves concentrate on M&A for biotech pigment capabilities and strategic partnerships with MFDS-registered Korean contract manufacturers.
Within the vertically integrated luxury tier, Charlotte Tilbury and Benefit Cosmetics occupy positions emphasizing supply chain control from raw material procurement through retail distribution. Fenty Beauty anchors the inclusive-shade innovation vector, representing intensive R&D investment in expanded color-matching capabilities. These three entities exemplify divergent strategic postures: captive manufacturing discipline, dual-use formulation specialization, and demographic-expansion product architecture.
| Leading Market Players |
|---|
| Charlotte Tilbury |
| Benefit Cosmetics |
| L'Oréal Paris |
| Glossier |
| Fenty Beauty |
| MAC Cosmetics |
| Etude House |
| NYX Professional Makeup |
| Maybelline New York |
| Others |
Supply & Pricing Matrix
Biotechnology-derived pigments displacing petroleum-based colorants are redrawing procurement geography from China's iron oxide clusters toward South Korean microalgae fermentation facilities, compressing legacy supply margins while elevating certification premiums for REACH-compliant vegan formulations.
Pricing Analysis
Cost-plus contracts with iron oxide indexation dominate synthetic pigment procurement, though biotech colorants trade on fixed-price agreements reflecting R&D amortization. Price differentiation separates ISO 22716-certified professional grades from mass-market personal use tiers. Pricing pressure intensifies in the synthetic segment as REACH authorization costs cascade to smaller manufacturers. Professional spa channels exhibit lowest price sensitivity due to durability requirements, while Gen Z direct-to-consumer buyers prioritize transparency over unit cost.
Supply Chain Analysis
Strategic stockpiling of carmine and annatto harvests buffers formulators against Peru's seasonal supply variability, whereas just-in-time logistics govern synthetic iron oxide flows from China. Raw material sourcing draws from Chinese petroleum-derived colorants, Peruvian cochineal extraction, and South Korean microalgae fermentation. Single-source vulnerability concentrates in China's iron oxide production clusters. Distribution runs through Seoul's Gangnam beauty innovation cluster for professional channels and algorithmic social commerce platforms for Gen Z personal use segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH nanomaterial authorization requirements are compressing new pigment introductions by forty percent, creating a regulatory inflection that rewards early compliance investment and captive biotech supply.
For Market Incumbents: Fortify supply chain control through backward integration into microalgae fermentation capacity in South Korea's Busan-Ulsan corridor. Secure ISO 22716 certification to gate institutional procurement channels against mid-tier competitors lacking regulatory affairs infrastructure. Prioritize formulation chemist retention as specialized emulsion expertise commands escalating salary premiums. For New Entrants and Emerging Players: Lead with vegan certification and biotechnology-derived pigment positioning to capture premium shelf space in German and Scandinavian clean beauty retail. India's tier-2 city salon channels present underpenetrated white space for humidity-adapted dual-use formulations. Deploy algorithmic creator partnerships on short-form video platforms to compress customer acquisition costs versus legacy department store counter strategies. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors biotech pigment capability acquisition over brand aggregation. Five-to-ten year viability hinges on REACH-compliant supply chain positioning rather than conventional synthetic scale. Monitor ECHA authorization timelines for nanomaterial colorants as the critical inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Pigment Scale-Up | South Korean microalgae fermentation capacity captures REACH-compliant premium positioning in EU specialty retail. |
| ISO 22716 Certification Investment | Good Manufacturing Practice accreditation opens airline duty-free and hospital gift shop procurement channels. |
| Social Commerce Platform Integration | Algorithmic video discovery collapses awareness-to-purchase funnels for Gen Z demographic capture. |
| India Tier-2 Distribution Expansion | Maharashtra and Karnataka salon channels offer first-mover positioning for humidity-adapted formulations. |
| REACH Compliance Preemption | Early nanomaterial authorization submission creates competitive separation as regulatory barriers tighten. |
Research Methodology
A standing panel of formulation chemists, professional cosmetology buyers, clean beauty retail procurement managers, and MFDS regulatory consultants provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA authorization databases, MFDS pre-market safety filings, EU customs trade data, and social commerce platform transaction disclosures. Bottom-up volume modeling triangulated against top-down value projections across product type, ingredient category, and application segment dimensions.
Consistency checks validated volume and value outputs against external benchmarks including regional production cluster capacity filings and retail audit data from German pharmacy channels. The analytical framework modeled liquid, balm, cream, and stick formats across natural, vegan, synthetic, and organic ingredient types through professional use, personal use, spa, and cosmetology applications over the projection horizon. CAGR derivation incorporated biotechnology pigment scale-up curves, REACH compliance cost trajectories, and social commerce penetration rates by demographic cohort.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement intensity or biotech pigment cost parity achievement would require recalibration. Forecasts reflect documented assumptions regarding regulatory timeline adherence and K-beauty trend diffusion velocity. Revision becomes warranted when ECHA nanomaterial authorization backlogs exceed eighteen-month processing thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Hair Conditioner Market
Beauty & Personal Care
UAE Beauty Industry Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
GCC Hair Styling Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Scalp Massager Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market