
 DIY PC Gaming Chassis Market | 2026-2036
DIY PC Gaming Chassis Market Size, Share, and Industry Trends Forecast 2026-2036
DIY PC Gaming Chassis Market Intelligence
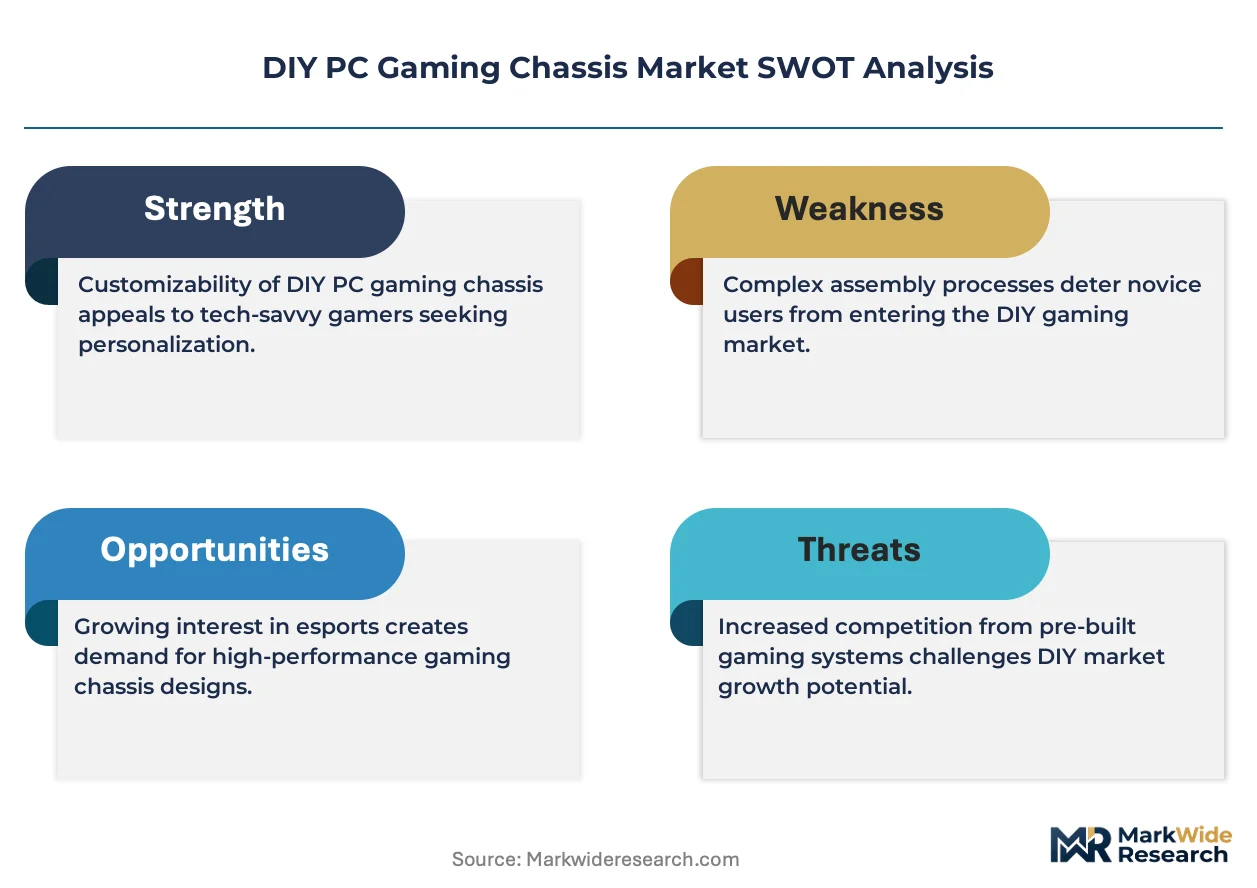
Esports tournament organizers and professional streamers is recalibrating chassis demand toward showcase-oriented designs with tempered glass and RGB integration. Corsair leverages its vertical control over cooling peripherals to bundle ecosystem sales. NZXT anchors its position through software-integrated lighting control that extends brand stickiness beyond hardware alone. Thermaltake competes aggressively on modular radiator mounting configurations for liquid cooling builds.
A DIY PC gaming chassis is an enclosure housing motherboard, power supply, storage drives, and cooling hardware, typically manufactured through steel stamping, aluminum extrusion, and tempered glass edge-grinding to achieve thermal dissipation targets above 200W TDP capacity. The primary commercial purpose is protecting components while enabling user customization of airflow, aesthetics, and future upgrade paths. Tower and Full ATX formats dominate volume due to their compatibility with high-end graphics cards and dual-radiator liquid cooling setups, while tempered glass panels command premium positioning over steel-sided alternatives. Hybrid cooling support represents the fastest-growing feature dimension as GPU power envelopes climb and users combine air and liquid methods.
The US EPA regulates hazardous substance thresholds in electronics manufacturing, while the EU's RoHS and REACH frameworks restrict cadmium and chromium use in metal finishing processes, directly shaping supplier qualification requirements for chassis OEMs. China's GB standards and MIIT circular economy directives add compliance layers for brands sourcing aluminum and steel from domestic smelters. Stakeholders must monitor how regional material certification rules fragment supply chains and determine where to localize stamping and powder-coating operations.
Market Dynamics
GPU power envelopes exceeding 450W TDP are forcing chassis manufacturers to redesign thermal architectures around hybrid cooling compatibility, while the EU's REACH and RoHS directives constrain metal finishing processes and fragment supplier qualification requirements across regional production footprints.
Growth Catalysts
- Enthusiast Content Creation:Streamers and esports tournament organizers now prioritize showcase-oriented designs with tempered glass and RGB integration, expanding the addressable buyer base beyond traditional PC builders.
- REACH Compliance Pressure:The EU's hazardous substance restrictions on cadmium and chromium in metal finishing processes are accelerating cleaner material sourcing investments among tier-1 OEMs.
- Hybrid Cooling Architecture:Liquid cooling adoption for high-wattage GPUs is driving demand for modular radiator mounting configurations and dual-chamber airflow designs.
Market Restraints
- Aluminum Price Volatility:Raw material cost swings for extruded aluminum and cold-rolled steel directly compress margin structures for mid-tier chassis producers.
- Supplier Concentration in China:Domestic smelters and stamping operations anchor 70% of global chassis metal supply, creating geographic risk exposure for brands with limited dual-sourcing.
- Technical Limitation of Mini-ITX Thermal Headroom:Small form factor enclosures face hard physical constraints dissipating above 200W TDP without liquid cooling, capping premium pricing in compact segments.
Strategic Opportunities
- India Assembly Ecosystem:The country's PLI scheme for electronics manufacturing offers tariff advantages for brands localizing stamping and powder-coating operations.
- Software-Hardware Convergence:Lighting control ecosystems that extend brand stickiness beyond hardware alone represent recurring revenue potential in the enthusiast segment.
- Second-Life Circular Programs:China's MIIT circular economy directives incentivize take-back and refurbishment channels for aluminum chassis recovery.
Industry Challenges
- Thermal Engineering Talent Scarcity:Computational fluid dynamics expertise for optimizing airflow simulations remains concentrated among a handful of specialized design houses.
- Multi-Region Certification Timelines:Simultaneous compliance with US EPA hazardous substance thresholds, EU REACH, and China GB standards extends product launch cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DIY PC Gaming Chassis Market |
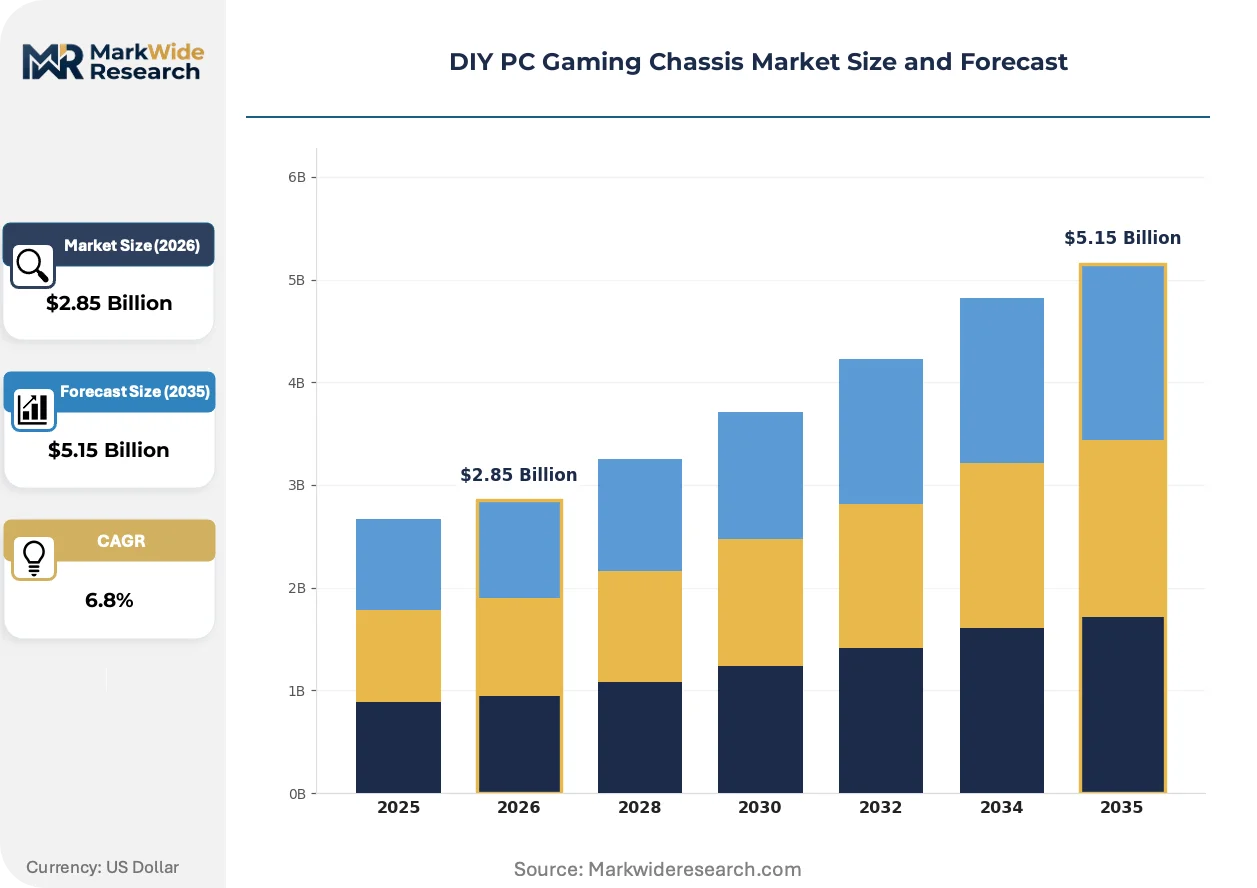
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tower, Mini Tower, Micro ATX, Full ATX Material: Steel, Aluminum, Plastic, Tempered Glass Cooling System: Air Cooling, Liquid Cooling, Passive Cooling, Hybrid Cooling Feature: RGB Lighting, Modular Design, Cable Management, Dust Filters |
| Companies Covered | Hyte, Thermaltake, NZXT, Be Quiet!, Lian Li, Havn, Corsair, Fractal Design, Phanteks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DIY PC Gaming Chassis Market Strategic Shifts & Innovations
Active unification of hardware and software control layers is compressing the traditional boundary between chassis manufacturers and peripheral ecosystem vendors, while regulatory fragmentation and shifting procurement authority reshape competitive positioning.
Modular cable management systems with integrated channel routing are unifying power supply, fan, and RGB wiring into standardized quick-connect architectures. Boutique system integrators and high-end DIY builders are adopting these configurations fastest, with adoption compressing build times and reducing aftermarket cable customization demand. The technology is unifying previously separate accessory categories into chassis-integrated solutions that capture margin previously lost to third-party cable brands.
The EU's F-Gas Regulation and expanding RoHS substance restrictions are tightening compliance windows for metal finishing and thermal interface materials. Manufacturers must now qualify alternative chrome-free coatings and low-GWP refrigerants for pre-installed AIO coolers, adding qualification cost and technical risk. European-bound product lines face the steepest reformulation requirements, with several OEMs segregating EU-specific SKUs to isolate compliance exposure.
Enterprise procurement teams at esports venues and streaming studios are consolidating chassis purchasing alongside complete system builds, displacing individual component retail for high-volume accounts. System integrators with direct OEM relationships are capturing this volume, squeezing traditional distribution margins. This concentration is most visible in China and South Korea, where tournament infrastructure investment and creator economy expansion concentrate demand among a shrinking pool of large buyers.
DIY PC Gaming Chassis Market Segmentation
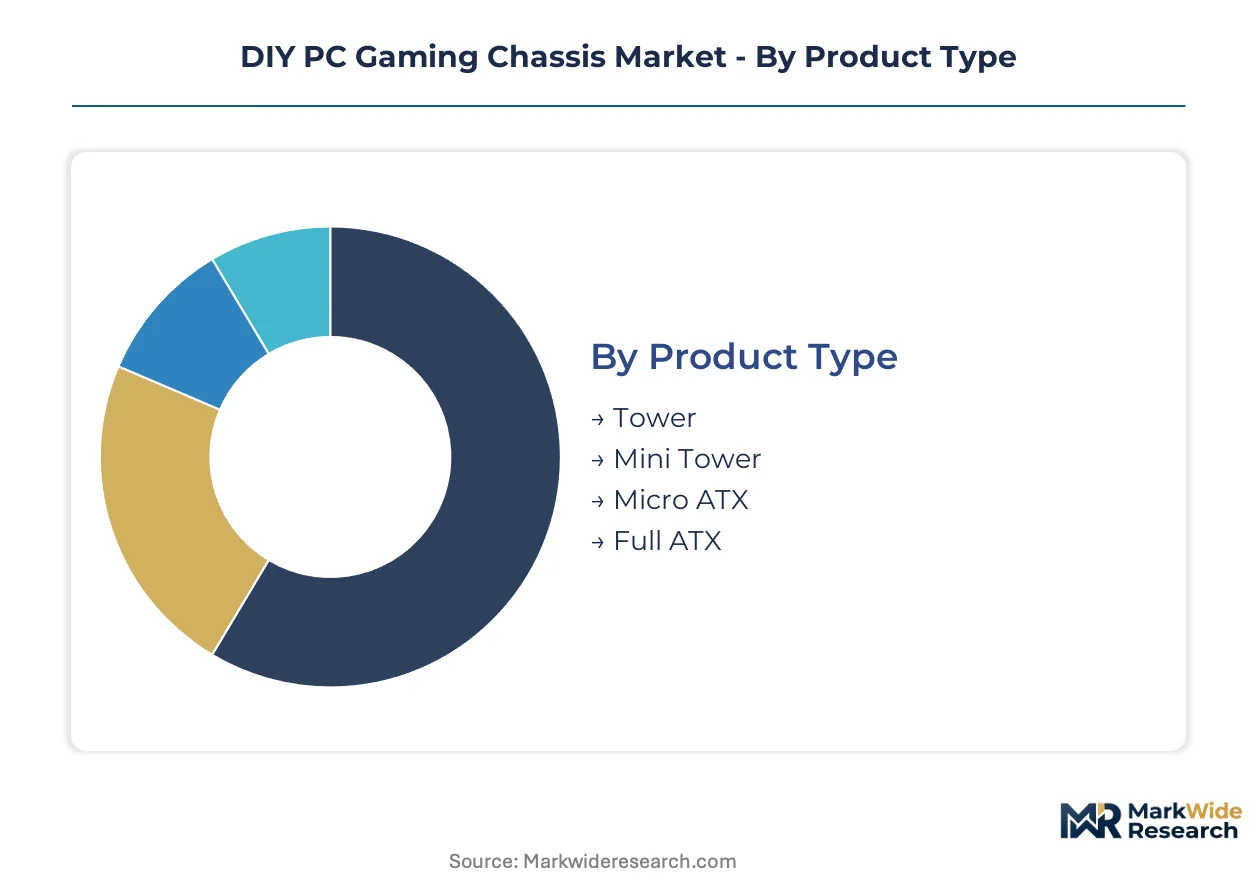
Chassis segmentation determines thermal headroom, upgrade pathways, and aesthetic positioning for distinct builder personas. Manufacturers configure product lines across four intersecting dimensions that shape margin structures and channel placement.
Product Type:
Standardization dominates the tower formats while customization concentrates in compact variants where thermal engineering becomes the primary differentiator.
- Tower:Mid-size enclosures accommodating ATX motherboards and dual-fan GPUs represent the volume anchor for retail distribution. Demand concentrates among first-time builders in China and the United States seeking expandability without full-tower footprint.
- Full ATX:Extended enclosures with 8+ expansion slots and dual-radiator support command premium positioning for liquid cooling builds. Esports venues and streaming studios in South Korea specify these formats for showcase systems with tempered glass visibility.
- Mini Tower:Reduced-height variants sacrifice some GPU clearance for desk footprint optimization. European apartment dwellers drive adoption where space constraints intersect with enthusiast performance requirements.
- Micro ATX:Compact form factor with limited expansion slots targets budget-conscious builders prioritizing cost over future upgrade paths. Indian system integrators bundle these with entry-level gaming configurations under the PLI scheme.
Leading the category by volume: Tower. Expanding most quickly: Full ATX.
Material:
Cost tier stratification separates premium aluminum extrusions from stamped steel volumes, with glass panels creating a distinct aesthetic premium layer.
- Steel:Cold-rolled and powder-coated chassis dominate unit economics through stamping automation at Chinese OEM facilities. REACH compliance on chrome-free coatings adds qualification overhead for EU-bound production.
- Aluminum:Extruded and anodized enclosures reduce weight while improving thermal conductivity for passive cooling designs. Japanese boutique builders specify these for compact high-performance configurations where every watt of dissipation matters.
- Plastic:ABS and polycarbonate panels reduce BOM cost in economy tiers while enabling complex aesthetic geometries. Brazilian assemblers favor these for price-sensitive gaming cafe deployments.
- Tempered Glass:Edge-ground panels with anti-shatter treatment create showcase visibility for RGB integration. Content creators in Germany and France pay substantial premiums for seamless aesthetic presentation.
Dominating unit shipments: Steel. Steepest expansion trajectory: Tempered Glass.
Cooling System:
Application requirements fragment this category between silent operation, maximum thermal headroom, and hybrid flexibility for evolving GPU power envelopes.
- Air Cooling:Mesh-front designs with 120-140mm fan mounting positions serve the installed base of builders avoiding liquid maintenance. Australian retailers report sustained preference for reliability-focused configurations in remote service locations.
- Liquid Cooling:Radiator mounting compatibility for 240-360mm AIO units defines chassis selection for high-TDP builds. NVIDIA's 450W GPU reference designs are forcing radiator support into mid-tier formats previously air-only.
- Passive Cooling:Large heatsink-compatible enclosures with chimney convection appeal to silent computing enthusiasts. Niche demand in Switzerland and Austria centers on audio production workstations.
- Hybrid Cooling:Modular mounting supporting simultaneous air and liquid methods gains share fastest as builders combine AIO GPUs with case fan arrays. Chinese brands lead configuration flexibility here.
Installed base leader: Air Cooling. Gaining share fastest: Hybrid Cooling.
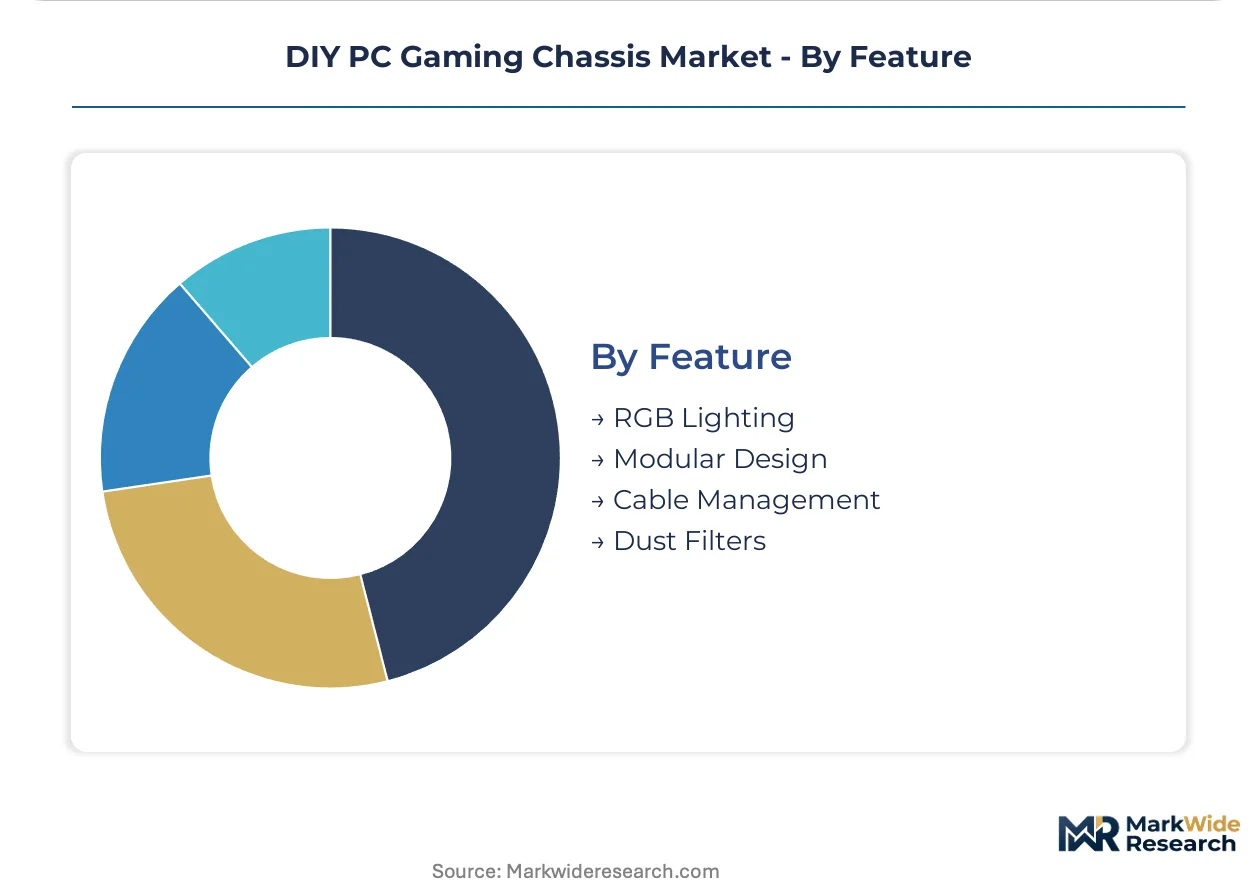
Feature:
Customer type and margin concentration separate aesthetic-driven RGB ecosystems from functional cable management and maintenance features.
- RGB Lighting:Addressable LED controller integration with motherboard sync protocols creates ecosystem lock-in for peripheral vendors. Streamers in the United Kingdom and Netherlands prioritize unified lighting control in sponsorship-visible builds.
- Cable Management:Grommeted routing channels and PSU shrouds reduce build complexity for novice assemblers. System integrators in Taiwan specify these features to compress assembly labor time.
- Modular Design:Tool-less drive cages and swappable radiator brackets enable reconfiguration without hardware replacement. Italian custom builders value adaptability for client-specific cooling experiments.
- Dust Filters:Magnetic mesh intake screens extend component lifespan in high-particulate environments. Middle Eastern gaming cafes specify these for reduced maintenance intervals.
Highest attach rate: Cable Management. Climbing fastest: RGB Lighting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of chassis metal stampings while consumption fragments across enthusiast clusters in Germany, South Korea, the United States, and Japan. Regional regulatory divergence on hazardous substances and circular economy mandates reshapes where brands localize assembly versus component sourcing.
China
Domestic OEM assembly ecosystems in Guangdong and Jiangsu provinces anchor global chassis volume, with MIIT circular economy directives incentivizing aluminum recovery programs. GB standards on electronics materials add compliance layers for brands sourcing from domestic smelters. Shenzhen and Dongguan clusters concentrate tempered glass edge-grinding and powder-coating operations for export-bound production.
Germany
Content creators in Berlin and Hamburg drive premium demand for tempered glass showcase designs with addressable RGB integration. ECHA REACH restrictions on cadmium and chromium in metal finishing force reformulation of chrome-free coatings for EU-bound product lines. Bavarian system integrators bundle Full ATX configurations for esports venue deployments across Central Europe.
South Korea
Seoul-based esports tournament organizers consolidate chassis procurement alongside complete system builds for streaming infrastructure. KCC electromagnetic compatibility certification adds technical overhead for imported enclosures. Busan-Ulsan industrial corridors host specialized stamping operations serving domestic gaming peripheral brands.
United States
EPA hazardous substance thresholds in electronics manufacturing shape supplier qualification requirements for chassis OEMs serving North American retail. California and Texas clusters concentrate boutique system integrators targeting enthusiast streamers with hybrid cooling builds. Midwest distribution hubs handle inventory staging for steel-dominated mid-tier formats.
Japan
METI energy efficiency guidelines influence thermal design priorities for compact high-performance configurations. Tokyo and Osaka metropolitan areas anchor demand for aluminum extrusion chassis among audio production workstation builders prioritizing silent passive cooling. Nagoya-based precision metalworkers supply anodized enclosures to domestic boutique brands.
DIY PC Gaming Chassis Market Key Industry Players
Top-tier vendors anchor premium positioning through software-hardware ecosystem integration, while mid-tier fabricators compete on modular thermal configurations and regional cost structures. The vendor base stratifies across three archetypes: peripheral ecosystem bundlers, thermal engineering specialists, and scale-driven OEM suppliers. Consolidation pressure intensifies as esports venue procurement concentrates volume among integrators with direct manufacturing relationships. Capacity localization and compliance segregation for EU-specific SKUs represent dominant competitive moves.
Among Taiwan-based metal fabrication specialists, Lian Li occupies a position exemplifying premium aluminum extrusion expertise. NZXT and Corsair represent the software-hardware convergence archetype, anchoring brand stickiness through lighting control ecosystems that extend beyond physical enclosure sales. Thermaltake sits within the modular thermal configuration tier, competing aggressively on radiator mounting flexibility for liquid cooling builds. These three vendors illustrate how competitive positioning fragments across material specialization, digital ecosystem integration, and thermal engineering adaptability.
| Leading Market Players |
|---|
| Hyte |
| Thermaltake |
| NZXT |
| Be Quiet! |
| Lian Li |
| Havn |
| Corsair |
| Fractal Design |
| Phanteks |
| Others |
Cost & Logistics Intelligence
Esports venue procurement consolidation toward turnkey system integrators is compressing distribution margins and forcing chassis brands to restructure channel economics around direct OEM relationships rather than retail markup stacking. This buyer-side concentration alters how manufacturers stage inventory and where they absorb margin pressure.
Pricing Analysis
Short lead-time premiums for EU-compliant SKUs with REACH-certified chrome-free coatings command substantial markups over standard inventory, while spot-market steel and aluminum positions trade at discounts reflecting commodity volatility exposure. Three-tier pricing structure across premium tempered-glass showcase designs, standard mesh-front configurations, and economy steel-panel tiers separates content-creator visible builds from budget gaming cafe deployments. Cost compression in mid-tier stamped-steel segments is intensifying because aluminum price volatility feeds directly into bill-of-materials instability. System integrators in India and Brazil exhibit highest price sensitivity due to PLI scheme margin constraints, while German boutique builders demonstrate lowest sensitivity when specifying anodized aluminum extrusions.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns that stage finished chassis closer to esports venue clusters and streaming studio consolidations. Manufacturing concentrates in China, Vietnam, and Taiwan, with Guangdong and Jiangsu provinces hosting the majority of global stamping, powder-coating, and tempered glass edge-grinding capacity. Raw material flows draw from domestic Chinese smelters for aluminum extrusion feedstock, Japanese cold-rolled steel for premium anodized chassis, and German-engineered chrome-free coating chemistries for EU-bound production lines. Single-source vulnerability around Chinese aluminum supply creates geographic risk exposure for brands lacking dual-sourcing through South Korean or Japanese metal suppliers. Distribution runs through specialized gaming peripheral distributors in North America, direct OEM relationships in South Korea, and electronics wholesale channels in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into captive cooling component supply and software control layer development is becoming the decisive competitive race, as chassis margins compress and ecosystem lock-in determines lifetime customer value capture.
For Market Incumbents: Extend software-hardware ecosystem control by deepening proprietary lighting protocol integration with motherboard vendors and acquiring specialized thermal engineering design houses. Defend against modular thermal configuration specialists by securing exclusive radiator mounting patent positions. Prioritize certification investment in REACH-compliant coating chemistries to isolate EU-bound SKU production from regulatory fragmentation costs. For New Entrants and Emerging Players: Direct-to-streamer subscription bundles represent the most penetrable white-space target, offering chassis-plus-lighting-control SaaS tiers that bypass traditional distribution entirely. Target Indian system integrators bundling Micro ATX configurations under PLI tariff advantages. Pursue white-label relationships with Chinese domestic brands seeking thermal engineering credibility for export expansion. For Investors and Strategic Acquirers: The window for entry favors thermal engineering specialists with computational fluid dynamics simulation capabilities and established relationships with NVIDIA and AMD reference design teams. Long-term viability hinges on positioning upstream of GPU power envelope escalation rather than downstream of commodity chassis fabrication. Watch for inflection when esports venue procurement shifts from system integrators to direct OEM framework agreements.| Strategic Initiative | Industry Significance |
|---|---|
| Software Control Layer Acquisition | Captures recurring revenue from lighting ecosystem subscriptions beyond one-time hardware sales. |
| REACH-Compliant Coating Investment | Isolates EU-bound production lines from ECHA regulatory reformulation delays and qualification costs. |
| India Assembly Localization | Secures PLI tariff advantages for powder-coating and stamping operations serving South Asian demand. |
| Thermal Engineering Talent Acquisition | Addresses scarcity of computational fluid dynamics expertise for 450W-plus GPU airflow optimization. |
| Direct OEM Relationship Development | Bypasses distribution margin compression from esports venue procurement consolidation. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with chassis product managers at tier-1 OEMs, thermal engineering directors at cooling component suppliers, procurement leads at esports venue operators, and distribution channel heads at gaming peripheral wholesalers. Secondary validation drew from ECHA REACH substance restriction databases, MIIT circular economy directive implementations, EPA hazardous substance threshold guidance, and aluminum and steel commodity trade flow records. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Granularity-level framing applied SKU-level modeling for product type, material composition, cooling system architecture, and feature bundling, with regional regulatory cluster overlays capturing EU REACH, US EPA, and China GB standard divergence. CAGRs were derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs included GPU TDP envelope escalation curves from NVIDIA and AMD reference design roadmaps, and esports venue infrastructure investment pipelines from tournament organizer procurement disclosures.
The model holds under sustained GPU power envelope escalation and stable aluminum-steel commodity spreads; deviation in circular economy mandate enforcement intensity or sudden raw material supply disruption would shift volume and value trajectories. Periodic stress-testing of base assumptions against regulatory implementation timelines and commodity futures curves is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Digital Voice Recorder Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Subwoofer Market
Consumer Electronics
United States Gaming Peripherals Market
Consumer Electronics
Vape Cartridge Market
Consumer Electronics
GCC Soundbar Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
Global Used Smartphones Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Global Bluetooth Mono Earpieces Market
Consumer Electronics
Wet Wipes Market
Consumer Electronics
Ereader and Enotetaking Devices Market
Consumer Electronics
Speakerphones Market
Consumer Electronics
Nail Art Printer Market
Consumer Electronics
Kids Tablet Market