
 Computing Mouse Market | 2026-2036
Computing Mouse Market Size, Share, and Industry Trends Forecast 2026-2036
Computing Mouse Market Analysis
E-commerce fulfillment networks is reconfiguring how computing mice reach end users, with direct-to-consumer platforms displacing traditional retail shelf space. Logitech International S.A. leverages its established logistics infrastructure to sustain premium positioning across multiple continents. Razer Inc. anchors its revenue in enthusiast gaming communities through specialized product ecosystems. Microsoft Corporation competes in enterprise procurement channels with standardized input devices bundled under volume licensing agreements.
A computing mouse is a handheld electro-mechanical pointing device that translates two-dimensional physical motion into digital cursor control through optical or laser sensor arrays with typical resolutions ranging from 800 to 25,000 DPI. It serves as the primary human-computer interface for navigation, selection, and manipulation tasks across consumer and professional computing environments. Wireless connectivity now leads volume growth as lithium-polymer batteries and low-latency radio protocols eliminate historical performance gaps with wired alternatives. Gaming end users command the highest per-unit margins, while office deployments generate predictable replacement-driven revenue at lower price points.
The US FCC governs radio frequency emissions for wireless mouse transmitters operating in the 2.4 GHz and 5 GHz bands, ensuring electromagnetic compatibility with adjacent consumer electronics. The EU RoHS directive restricts hazardous substances in printed circuit board assemblies and cable insulation, compelling component suppliers to certify lead-free solder processes and halogen-free plastics. China MIIT enforces national standard GB 4943.1 for peripheral electrical safety, creating a separate compliance pathway for products entering its domestic market. Stakeholders must monitor evolving battery transport regulations and right-to-repair legislation that could mandate user-replaceable cells and standardized fastening schemes.
Market Dynamics
Wireless connectivity standards and low-latency radio protocols are compressing replacement cycles while EU REACH compliance costs are redrawing material sourcing maps for peripheral housings.
Growth Catalysts
- Esports formalization:Tournament organizers mandate hardware refresh schedules that accelerate enterprise procurement of competition-grade peripherals.
- REACH substitution mandates:Restricted phthalate plasticizers in EU markets are forcing manufacturers toward bio-based polymer alternatives with equivalent durability profiles.
- Optical sensor density:Laser arrays reaching 25,000 DPI resolution are hybridizing professional design workflows with gaming performance requirements.
Market Restraints
- Lithium-polymer cost volatility:Battery cell pricing fluctuations directly compress margins on wireless SKUs targeting sub-fifty-dollar price bands.
- Optical encoder supply concentration:Precision sensor fabrication clusters in Taiwan and South Korea create single-source vulnerability for tier-one manufacturers.
- Radio frequency congestion:2.4 GHz band saturation in dense urban deployments degrades signal integrity below competitive gaming thresholds.
Strategic Opportunities
- India peripheral penetration:Domestic PC assembly growth under PLI scheme incentives is creating first-time buyer expansion in tier-two cities.
- Right-to-repair tailwinds:Proposed EU battery accessibility mandates would advantage modular designs with user-replaceable cells.
- Gesture control convergence:Integration of capacitive touch surfaces with traditional mechanical switches is opening white-collar productivity segments.
Industry Challenges
- Firmware security certification:Wireless protocol stacks require Common Criteria evaluation timelines that extend product launch windows by eight to fourteen months.
- Legacy port compatibility:USB-A to USB-C transition friction forces dual-cable SKUs that fragment inventory and complicate forecasting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computing Mouse Market |
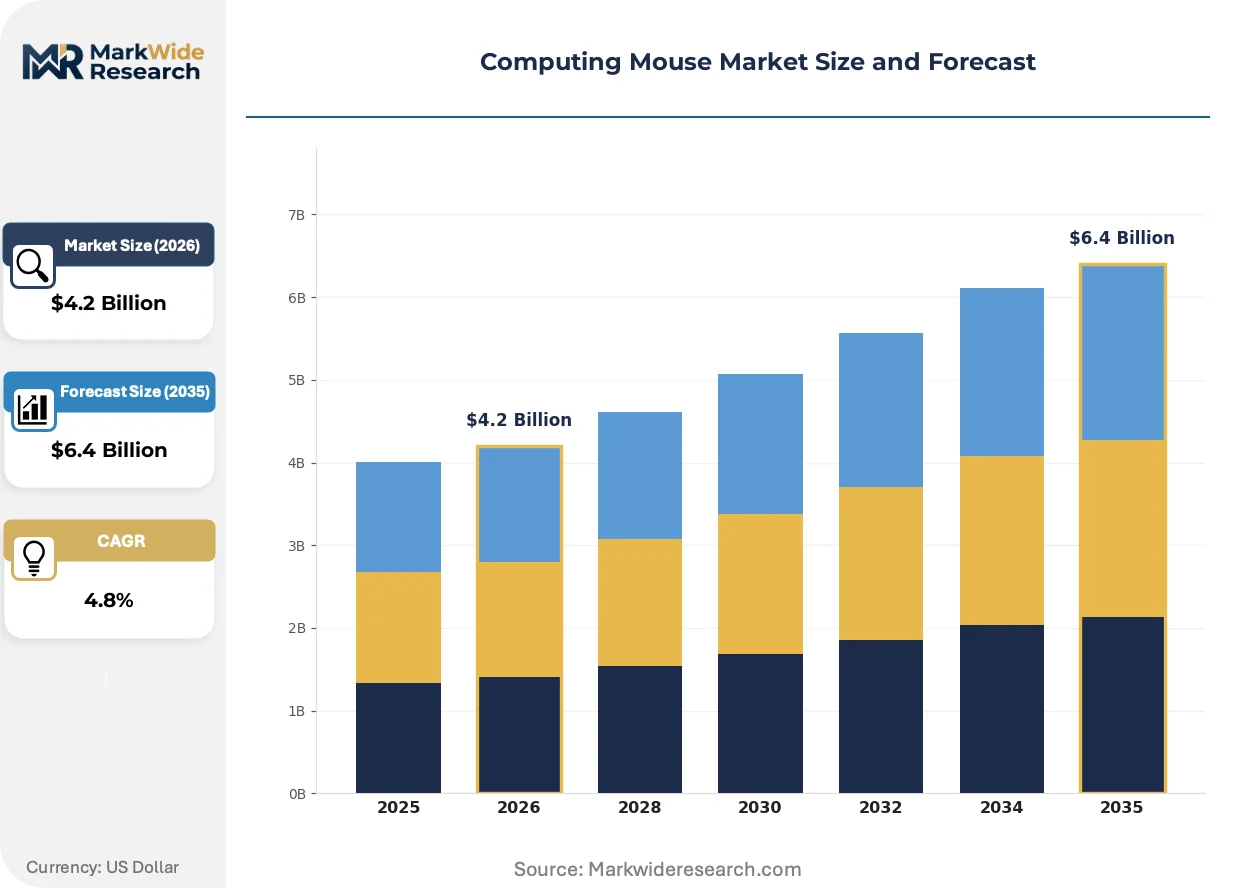
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $6.4 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wired, Wireless, Bluetooth, Ergonomic Technology: Optical, Laser, Trackball, Joystick End User: Gaming, Office, Design, Education Form Factor: Standard, Compact, Vertical, Ambidextrous |
| Companies Covered | Logitech International S.A., Razer Inc., Corsair Gaming, Inc., SteelSeries, Microsoft Corporation, HP Inc., ASUSTeK Computer Inc., Cooler Master Technology Inc., HyperX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computing Mouse Market Emerging Trajectories
Peripheral architecture is fragmenting into specialized sensor, power, and connectivity modules that OEMs recombine across price tiers. This modularization is compressing development timelines while complicating supply chain coordination.
Optical tracking engines are hybridizing photodiode arrays with machine-learned surface detection algorithms. Professional esports organizations are adopting these hybrid systems at three-year refresh intervals. The technology is hybridizing what were previously distinct gaming and workstation product lines into unified SKUs with firmware-differentiated performance profiles.
EU RoHS recast directives are tightening exemptions for cadmium in contact plating. Component suppliers must certify halogen-free substrate materials or forfeit access to public sector procurement frameworks. Gaming peripheral assemblers serving European distribution channels are absorbing compliance costs through supplier qualification programs rather than price premiums.
Enterprise buyers are consolidating peripheral procurement under single-source IT asset management platforms. Traditional value-added resellers are losing shelf space to direct-from-manufacturer subscription models with bundled refresh guarantees. This consolidation is most visible in North American healthcare and financial services verticals where HIPAA and SOX audit trails favor centralized device tracking.
Computing Mouse Market Segmentation
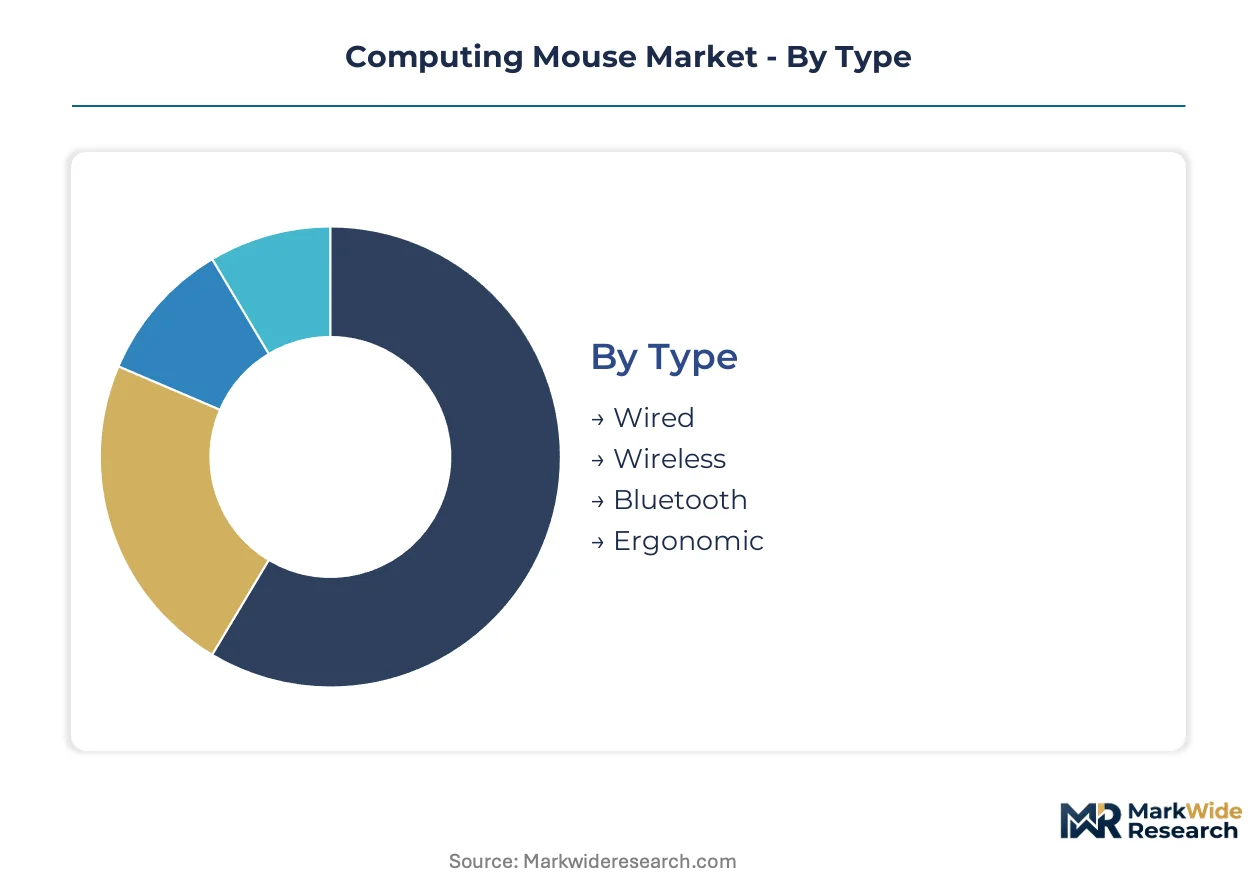
Mouse manufacturers calibrate warranty terms and replacement logistics differently across connectivity types, sensor architectures, and ergonomic specifications. Segmentation reveals where service infrastructure investments yield retention versus where disposable pricing dominates.
Type:
After-sales-service intensity varies sharply by connectivity architecture, with wireless platforms demanding firmware update pipelines and battery logistics that wired alternatives bypass entirely.
- Wired:USB-C and USB-A variants rely on passive connectivity with no power management complexity. Enterprise procurement in healthcare and financial services verticals favors these for predictable replacement cycles under centralized IT asset management.
- Wireless:Radio frequency transmitters operating in 2.4 GHz and 5 GHz bands require FCC certification and lithium-polymer cell logistics. Gaming end users absorb premium pricing for sub-1ms latency protocols that tournament organizers mandate.
- Bluetooth:Low-energy protocols suit mobile workstation deployments where USB port scarcity constrains connectivity options. Microsoft and Apple ecosystem integration drives compatibility testing overhead for peripheral vendors.
- Ergonomic:Sculpted housings with adjustable palm rests command specialized return-handling procedures due to fit variability. Occupational health procurement channels in Germany and the Netherlands evaluate these for repetitive strain injury prevention programs.
By volume, Wired leads. By growth pace, Wireless is ahead.
Technology:
Cost tier stratification separates photodiode-based tracking from precision laser engines, with fabrication concentration in Taiwan and South Korea creating supply-side differentiation.
- Optical:LED-illuminated sensors dominate office deployments with 800-3,200 DPI resolution sufficient for spreadsheet navigation and document editing. Chinese domestic brands compete aggressively on price in this specification band.
- Laser:Infrared coherent light sources achieve 25,000 DPI for professional design workflows and esports competition. Surface detection algorithms now hybridize gaming and workstation requirements into unified firmware-differentiated SKUs.
- Trackball:Stationary ball mechanisms reduce desk surface requirements for constrained workspaces. Specialized industrial and accessibility applications sustain niche manufacturing volumes.
- Joystick:Analog pressure sensing supports 3D navigation in CAD and medical imaging software. Simulation training environments in aviation and surgical education represent concentrated demand pockets.
Optical sensors ship in greatest quantity. Laser arrays are climbing the fastest on gaming and professional design convergence.
End User:
Customer type determines margin structure, with enthusiast gaming communities accepting per-unit premiums that office replacement cycles cannot sustain.
- Gaming:Tournament-grade peripherals with programmable macro arrays and customizable RGB lighting command the highest per-unit margins. Esports hardware refresh schedules compress replacement cycles to three-year intervals.
- Office:Standardized input devices bundled under volume licensing agreements generate predictable revenue at lower price points. HIPAA and SOX audit trail requirements favor centralized device tracking in North American healthcare and financial services.
- Design:High-DPI laser tracking supports precision workflows in architecture, engineering, and digital content creation. Adobe and Autodesk certification programs influence peripheral selection criteria.
- Education:Bulk procurement tenders prioritize durability specifications and theft-deterrence mounting options. India's PLI scheme incentives for domestic PC assembly are expanding first-time buyer penetration in tier-two cities.
Office deployments dominate unit volume. Gaming represents the steepest expansion trajectory on formalized esports infrastructure.
Form Factor:
Volume and margin profiles diverge across hand-size accommodation and dexterity requirements, with ambidextrous designs sacrificing ergonomic optimization for inventory efficiency.
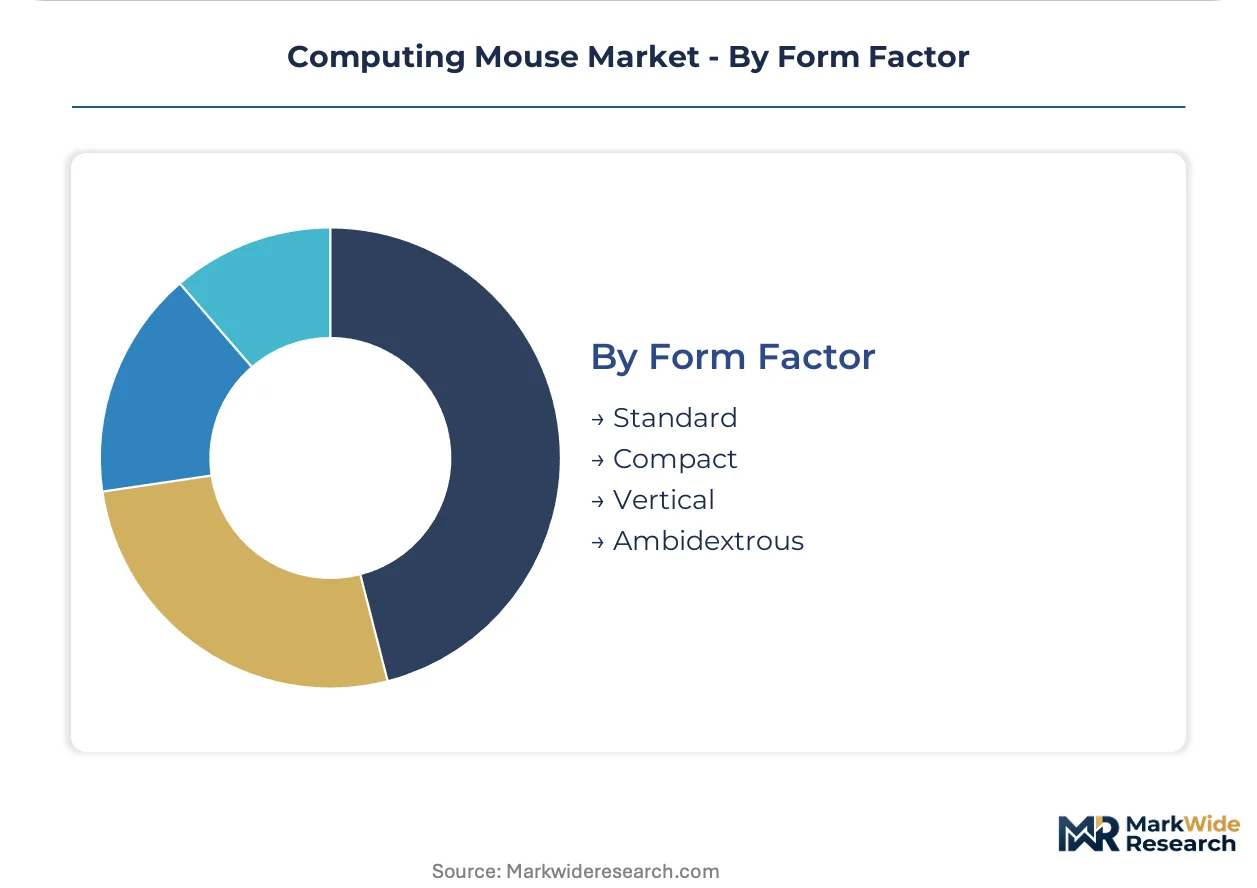
- Standard:Symmetrical housings suit right-handed users with medium hand dimensions. Retail channel distribution concentrates on this specification for inventory turnover velocity.
- Compact:Reduced footprint targets mobile professionals and laptop-bag portability constraints. Travel retail and direct-to-consumer platforms displace traditional shelf space for this category.
- Vertical:Elevated wrist positioning addresses carpal tunnel syndrome prevention in enterprise wellness programs. EU occupational health regulations are expanding reimbursement eligibility for medically prescribed variants.
- Ambidextrous:Mirror-image button layouts accommodate left-handed users without dedicated SKU proliferation. Tournament organizers mandate these for standardized competition equipment pools.
Standard form factors lead in shipment volume. Vertical designs are gaining share fastest on workplace ergonomics regulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German esports tournament organizers extract hardware premiums that Chinese domestic brands undercut by forty percent on comparable specifications. This pricing-power asymmetry shapes procurement patterns across enterprise and consumer channels.
United States
Enterprise IT asset management platforms in healthcare and financial services drive centralized peripheral procurement under HIPAA and SOX audit requirements. FCC Part 15 governs 2.4 GHz and 5 GHz wireless transmitter certification for consumer electronics. Seattle and Austin host gaming peripheral R&D clusters where tournament-grade sensor calibration occurs.
Germany
Occupational health procurement channels evaluate vertical mice for repetitive strain injury prevention in corporate wellness programs. EU REACH restrictions on phthalate plasticizers force housing material substitutions toward bio-based polymers. Munich and Hamburg anchor distribution networks serving Nordic and Benelux enterprise markets.
China
Domestic brands challenge incumbents on price and specification in tier-two city expansion under MIIT's GB 4943.1 electrical safety standard. Shenzhen and Dongguan concentrate optical sensor module assembly with Taiwan-sourced laser diode integration. E-commerce fulfillment networks displace traditional retail shelf space for direct-to-consumer platforms.
India
Domestic PC assembly growth under PLI scheme incentives creates first-time buyer expansion in tier-two cities. BIS certification requirements add compliance timelines for peripheral imports. Bengaluru and Hyderabad host IT services clusters where bulk education and enterprise tenders concentrate procurement volume.
Japan
Precision manufacturing workflows sustain demand for high-DPI laser tracking in automotive and electronics design applications. METI oversees radio equipment certification under technical standards conformity marking. Tokyo and Osaka metropolitan areas concentrate professional content creation studios with Adobe-certified peripheral selection criteria.
Computing Mouse Market Vendor Landscape
Peripheral specialists and diversified electronics conglomerates split the market between enthusiast gaming communities and enterprise procurement channels. The vendor base organizes around three strategic archetypes: gaming-focused specialists with programmable ecosystem integration, enterprise-oriented suppliers with volume licensing infrastructure, and component-integrated OEMs leveraging captive manufacturing scale. Competitive moves center on supplier qualification programs for EU RoHS and REACH compliance, plus direct-to-consumer platform expansion that displaces traditional value-added resellers.
Within the gaming-specialist tier, Logitech International S.A. and Razer Inc. exemplify contrasting geographic anchoring and ecosystem strategies. Logitech represents Swiss-domiciled multinational infrastructure with established logistics networks across multiple continents. Razer occupies a position as Singapore-headquartered enthusiast community anchor with specialized product ecosystem development. Microsoft Corporation sits within the enterprise-diversified archetype, leveraging volume licensing agreements and standardized input device bundling for healthcare and financial services verticals in North America.
| Leading Market Players |
|---|
| Logitech International S.A. |
| Razer Inc. |
| Corsair Gaming, Inc. |
| SteelSeries |
| Microsoft Corporation |
| HP Inc. |
| ASUSTeK Computer Inc. |
| Cooler Master Technology Inc. |
| HyperX |
| Others |
Supply Flow & Price Mechanics
Lithium-polymer cost volatility in battery cell markets compresses margins on wireless SKUs while simultaneously forcing tier stratification across premium tournament-grade and economy office segments. This input price instability redistributes pricing power toward manufacturers with captive cell sourcing or long-term supplier contracts, reshaping competitive boundaries between integrated and modular assembly models.
Pricing Analysis
Configured-to-order pricing for programmable gaming peripherals with customizable RGB arrays and macro configurations commands substantial premiums over standardized office SKUs bundled under volume licensing agreements. Three-tier pricing structure across premium, standard, and economy levels separates esports-certified tournament equipment from enterprise procurement tiers and entry-level consumer offerings. Cost compression in sub-fifty-dollar wireless tiers is intensifying because Chinese domestic brands challenge incumbents on specification-matched pricing. Enterprise buyers in North American healthcare and financial services verticals exhibit lowest price sensitivity due to HIPAA and SOX audit trail requirements that favor centralized device tracking over per-unit cost optimization.
Supply Chain Analysis
Upstream feedstock dependencies center on Taiwan-sourced laser diode arrays and South Korean precision optical encoder fabrication for high-DPI sensor modules. Peripheral assembly draws from Chinese lithium-polymer cell manufacturing, Vietnamese injection-molded housing production, and German-engineered bio-based polymer alternatives for EU REACH compliance. Single-source vulnerability concentrates in Taiwan and South Korea for tier-one sensor suppliers, exposing manufacturers to geopolitical disruption risks. Distribution runs through direct-to-consumer e-commerce platforms that displace traditional value-added resellers, with enterprise procurement consolidating under single-source IT asset management platforms in North American healthcare and financial services verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computing mouse demand follows enterprise hardware refresh cycles that accelerate during post-recession IT modernization waves, positioning the market for cyclical expansion as deferred procurement budgets release.
For Market Incumbents: Entrench tournament-grade ecosystem loyalty through firmware-differentiated performance profiles that hybridize gaming and workstation requirements into unified SKUs. Secure supplier qualification programs for EU RoHS and REACH compliance to defend against Chinese domestic brands undercutting specifications by forty percent. Prioritize backward integration into optical sensor module assembly to reduce Taiwan and South Korean single-source vulnerability. For New Entrants and Emerging Players: Tier-two Indian cities under PLI scheme PC assembly expansion present first-time buyer white space with limited incumbent penetration. Target education bulk procurement tenders prioritizing durability specifications and theft-deterrence mounting options. Leverage direct-to-consumer platform expansion that displaces traditional retail shelf space to bypass established distributor relationships. For Investors and Strategic Acquirers: The market sits at a replacement-cycle acceleration phase that favors modular design specialists with user-replaceable battery architectures positioned for right-to-repair tailwinds. Long-term viability hinges on firmware security certification capabilities and low-latency radio protocol stacks. Acquisition targets should demonstrate established logistics infrastructure across multiple continents or specialized enthusiast community anchoring. Monitor EU battery accessibility mandate legislative progression as inflection indicator for modular design premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Expansion | Bypasses traditional value-added resellers in North American healthcare procurement channels. |
| Supplier Qualification Programs | Absorbs EU RoHS and REACH compliance costs without price premium pass-through. |
| Modular Battery Architecture Development | Positions for right-to-repair mandates with user-replaceable lithium-polymer cells. |
| Optical Sensor Backward Integration | Reduces Taiwan and South Korean single-source fabrication vulnerability. |
| Firmware Security Certification Investment | Accelerates Common Criteria evaluation timelines for wireless protocol stacks. |
Methodological Framework
Operator-level perspectives from peripheral R&D directors, esports tournament organizers, enterprise IT procurement officers, and component supplier quality managers anchored the qualitative base. Primary interviews combined with secondary validation from FCC equipment authorization databases, EU ECHA REACH registration dossiers, China MIIT GB standard filings, and SEC 10-K peripheral segment disclosures. Bottom-up shipment estimates by connectivity type and sensor technology triangulated against top-down market value reconstructions.
Scenario-bracketing framed volume and value outputs across the analysis window, with segmentation modeling by connectivity architecture, sensor technology tier, end-user category, and ergonomic form factor. CAGRs derived from replacement cycle compression rates, esports formalization trajectories, and regional PC penetration curves. Forecast inputs incorporated lithium-polymer cell pricing volatility indices and optical encoder fabrication capacity utilization rates from Taiwan and South Korean supplier clusters.
Practitioners should monitor EU battery accessibility mandate legislative progression, lithium-polymer commodity price movements, and 2.4 GHz spectrum congestion regulatory responses for early signals of forecast revision. Cross-checking against hyperscaler enterprise peripheral procurement disclosures and esports tournament hardware refresh schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
United States Smart TV Market
Consumer Electronics
Smart Television and Set-Top Box Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Portable Stick Market
Consumer Electronics
Dive Computer Market
Consumer Electronics
Middle East and Africa Mobile Phone Accessories Market
Consumer Electronics
Europe Soundbar Market
Consumer Electronics
Asia-Pacific Gaming Keyboard Market
Consumer Electronics
Kid's Wired Earphone and Headphone Market
Consumer Electronics
Europe Mobile Phone Accessories Market
Consumer Electronics
Smart Headphones Market
Consumer Electronics
North America Mobile Phone Accessories Market
Consumer Electronics
Global White Noise Machines Market
Consumer Electronics
Smart DJ Controller Market
Consumer Electronics
North America Gaming Accessories Market