
 Electronic Products Rental Market | 2026-2036
Electronic Products Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Products Rental Market Analysis
Multi-source equipment provisioning is broadening as enterprises diversify beyond single-vendor procurement. Rent-A-Center anchors physical storefront access across suburban markets. Prog Holdings, Inc. leverages digital-first underwriting to extend lease-to-own options. Meeting Tomorrow Inc. specializes in event-centric technology logistics, sustaining high-touch service margins.
Electronic products rental denotes temporary transfer of computing, communications, and audiovisual equipment against periodic fees, typically covering hardware maintenance, logistics, and end-of-life recovery within contract terms. The model eliminates capital expenditure burdens while ensuring access to current specifications for users with variable or project-bound needs. Corporate clients drive the largest revenue pool through standardized fleet refresh programs, while subscription services capture the fastest expansion by embedding automatic upgrade cycles and bundled support. Audio equipment trails in maturity with thinner margins, concentrated in seasonal event peaks.
The Federal Trade Commission monitors lease disclosure practices under consumer protection mandates, while the Securities and Exchange Commission governs lessor financial reporting transparency for publicly traded operators. The EPA's e-waste guidelines increasingly shape recovery obligations, pushing rental providers toward certified refurbishment pipelines. Stakeholders must track how right-to-repair legislation evolves across state jurisdictions, as repair accessibility clauses could compress residual value recovery or alternatively unlock secondary market revenue streams.
Market Dynamics
Right-to-repair mandates in the European Union are rewriting residual value calculations across the equipment rental sector. Lessors must now model extended depreciation curves and secondary market liquidity against stricter refurbishment obligations.
Growth Catalysts
- Remote workforce normalization:Corporate IT departments are expanding rental programs for distributed employee equipment. Enterprise technology refresh cycles favor rental over ownership for cost flexibility.
- EU Circular Economy Action Plan:Extended producer responsibility frameworks strengthen refurbishment incentives. Rental providers gain competitive advantage through certified recovery pipelines.
- Startup ecosystem liquidity constraints:Venture-backed companies prioritize operational expenditure models. Equipment rental eliminates capital lock-up during funding uncertainty.
Market Restraints
- Semiconductor supply volatility:Component shortages disrupt fleet standardization efforts. Rental providers face extended procurement timelines for current-generation hardware.
- Residual value compression:Accelerated technology obsolescence narrows secondary market margins. Lessors absorb depreciation risk on short-cycle computing equipment.
- Cross-border logistics friction:Customs complexity increases turnaround costs for international deployments. Regional warehousing requirements multiply fixed cost bases.
Strategic Opportunities
- Subscription-based automatic upgrades:Bundled support and refresh cycles capture recurring revenue. Corporate clients lock in predictable technology access without procurement burden.
- Event-centric technology logistics:Seasonal audiovisual demand peaks reward specialized service capabilities. High-touch deployment and technical support sustain premium pricing.
- State-level right-to-repair legislation:Repair accessibility clauses unlock secondary market revenue streams. Certified refurbishment capabilities differentiate compliant operators.
Industry Challenges
- Technical certification timelines:EPA e-waste guidelines demand certified recovery infrastructure. Providers must invest in tracking and documentation systems for end-of-life compliance.
- Integration complexity with legacy enterprise systems:Rental fleet management platforms require API connectivity to client procurement software. Mid-market customers lack internal technical resources for seamless onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Products Rental Market |
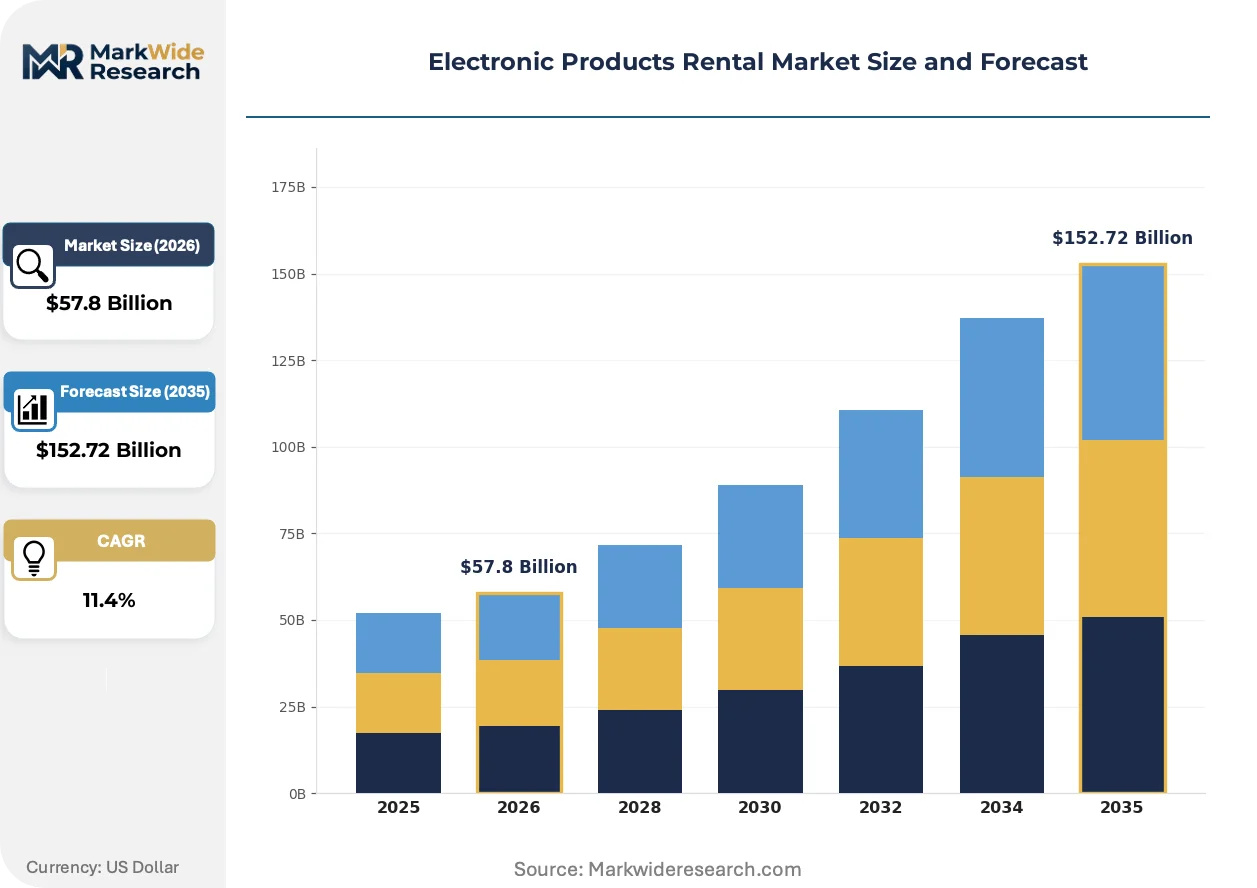
| Market Size in 2026 | $57.8 Billion |
| Market Size in 2035 | $152.72 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computers, Tablets, Smartphones, Audio Equipment End User: Corporate Clients, Educational Institutions, Event Organizers, Individual Consumers Service Model: Short-term Rental, Long-term Rental, Subscription Services, On-demand Leasing Delivery Method: In-store Pickup, Home Delivery, Onsite Installation, Curbside Delivery |
| Companies Covered | Reliance Retail Limited, Rentacomputer.com Inc., Prog Holdings, Inc., Buddy's Home Furnishings Inc., Meeting Tomorrow Inc., Rent-A-Center, FlexShopper Inc., Cort Business Services Corporation, Aaron's Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Products Rental Market Emerging Trajectories
Equipment-as-a-service models are compressing traditional ownership cycles across computing and communications categories. Lessors are embedding predictive maintenance and automatic refresh triggers into contract structures.
Artificial intelligence-driven asset utilization tracking is rewriting fleet optimization economics. Large enterprise clients deploy sensor-enabled equipment monitoring to right-size rental volumes. Lessors leverage usage data to dynamic-price contracts and reduce idle inventory carrying costs.
The EU Green Deal and CSRD disclosure requirements are mandating scope 3 emissions transparency. Rental providers must document circular economy metrics across refurbishment and recovery operations. Corporate procurement teams in Germany and France now weight sustainability credentials in vendor selection criteria.
Project-based procurement is displacing annual capital budgeting for technology acquisition. Marketing agencies and film production houses rent specialized audiovisual equipment for campaign durations. This consumption pattern concentrates demand in coastal metropolitan clusters with rapid logistics infrastructure.
Electronic Products Rental Market Segmentation
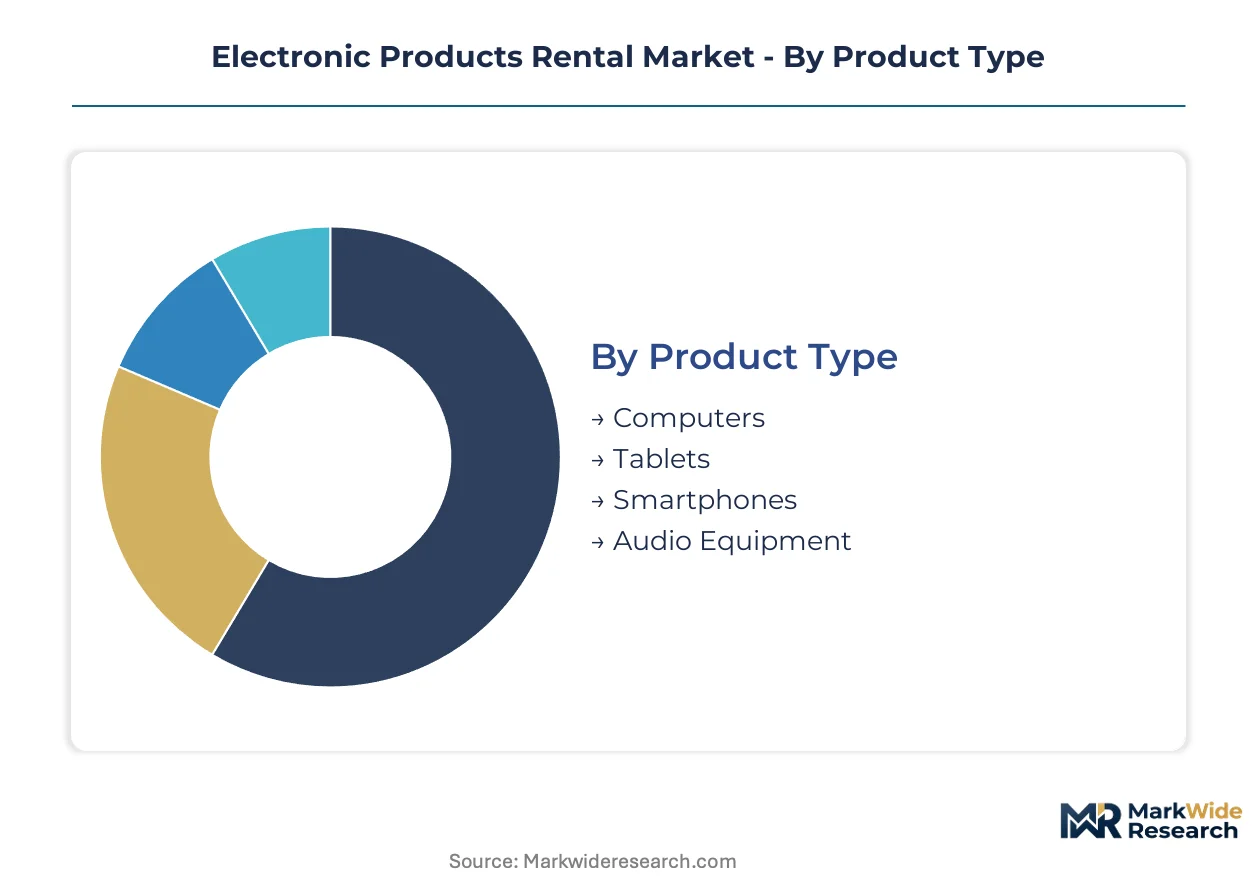
Segmentation in electronic products rental reveals divergent margin structures and operational requirements across equipment categories. Rental providers must configure distinct fleet management, pricing architectures, and logistics protocols for each segment to optimize asset utilization and residual value recovery.
Product Type:
Specification hierarchies and refresh cycles differentiate rental economics across hardware categories, with computing equipment commanding premium rates against shorter depreciation schedules.
- Computers:Desktop and laptop fleets dominate enterprise procurement with standardized configurations for remote workforce deployment. Corporate IT departments in the United States favor rental for technology refresh cycles that outpace capital budgeting timelines.
- Tablets:Mobile computing form factors serve field service teams and educational testing programs. Demand concentrates in K-12 districts and healthcare documentation workflows where device turnover accelerates.
- Smartphones:Enterprise mobility management drives bulk rental agreements with automatic upgrade provisions. Telecom expense management platforms integrate rental billing to simplify procurement for distributed workforces.
- Audio Equipment:Seasonal event peaks and thinner margins characterize this category. Production houses and conference organizers rent specialized microphones, mixers, and PA systems for campaign durations.
Computers lead on scale; subscription services for smartphones gain share fastest through bundled refresh cycles.
End User:
Customer procurement sophistication and contract duration preferences segment the market into distinct service tiers with varying margin profiles.
- Corporate Clients:Standardized fleet refresh programs generate the largest revenue pool with multi-year agreements. Enterprise technology refresh cycles favor rental over ownership for cost flexibility during funding uncertainty.
- Educational Institutions:K-12 districts and universities deploy rental for one-to-one computing initiatives with predictable replacement schedules. Device standardization simplifies technical support across large student populations.
- Event Organizers:Project-based procurement concentrates demand in coastal metropolitan clusters with rapid logistics infrastructure. High-touch deployment and technical support sustain premium pricing for audiovisual equipment.
- Individual Consumers:Lease-to-own options capture liquidity-constrained households through digital-first underwriting. Suburban storefront access remains critical for demographic segments preferring physical inspection.
Corporate clients anchor revenue concentration; educational institutions expand most quickly through one-to-one computing mandates.
Service Model:
Contract structure determines capital commitment, maintenance obligation allocation, and upgrade pathway clarity for rental participants.
- Short-term Rental:Daily or weekly terms serve project-bound needs with premium per-day rates. Film production houses and marketing agencies rent specialized equipment for campaign durations.
- Long-term Rental:Multi-year agreements lock in predictable technology access without procurement burden. Corporate clients eliminate capital expenditure while ensuring access to current specifications.
- Subscription Services:Automatic upgrade cycles and bundled support capture recurring revenue with highest expansion velocity. Providers embed predictive maintenance triggers into contract structures.
- On-demand Leasing:Flexible terms accommodate variable workforce scaling with rapid deployment capabilities. Startup ecosystem liquidity constraints favor operational expenditure models during funding uncertainty.
Long-term rental dominates contract value; subscription services climb the fastest as equipment-as-a-service models compress ownership cycles.
Delivery Method:
Logistics configuration shapes customer acquisition costs and service differentiation in geographically dispersed deployment scenarios.
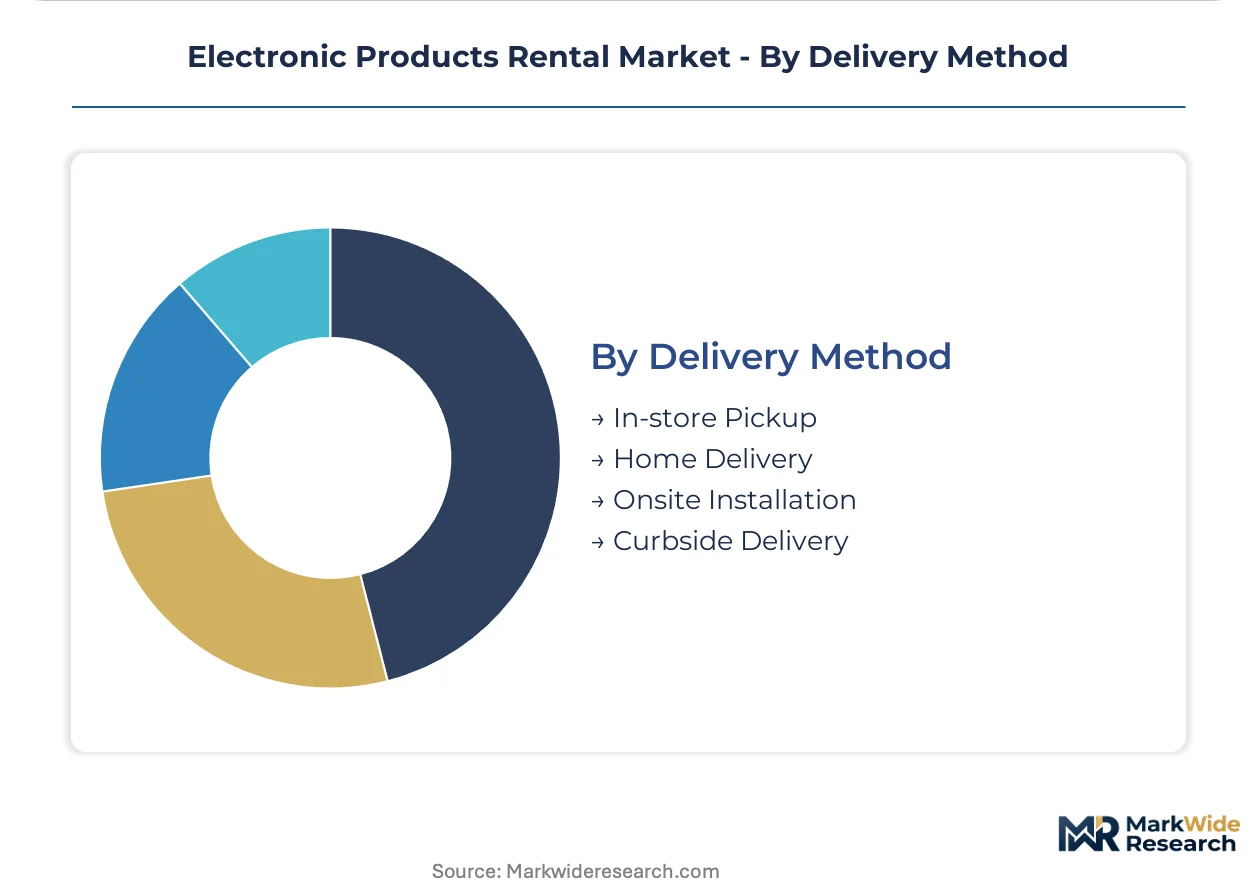
- In-store Pickup:Physical storefront access across suburban markets supports demographic segments preferring equipment inspection. Rent-A-Center anchors this channel with established suburban presence.
- Home Delivery:Direct-to-consumer shipping scales efficiently for standardized computing equipment. Digital-first providers leverage this method for individual consumer and remote workforce segments.
- Onsite Installation:Technical deployment and configuration services sustain premium pricing for complex audiovisual setups. Meeting Tomorrow Inc. specializes in event-centric technology logistics with high-touch service margins.
- Curbside Delivery:Contactless handoff protocols emerged during remote workforce normalization and persist for convenience positioning. Corporate fleet rollouts utilize this method for distributed employee equipment distribution.
Home delivery leads on volume scalability; onsite installation commands the steepest premium through technical specialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage in refurbishment certification costs is redirecting rental fleet servicing toward jurisdictions with streamlined compliance pathways. Equipment lessors optimize residual value recovery by locating refurbishment operations where EPA e-waste guidelines or EU Green Deal obligations impose lighter administrative burdens relative to primary markets.
United States
Enterprise technology refresh cycles and startup ecosystem liquidity constraints concentrate demand in coastal metropolitan clusters. The FTC monitors lease disclosure practices under consumer protection mandates while the SEC governs financial reporting transparency for publicly traded operators. Silicon Valley and New York City anchor project-based procurement from marketing agencies and film production houses.
Germany
Corporate procurement teams weight sustainability credentials in vendor selection criteria under CSRD disclosure requirements. The EU Green Deal and extended producer responsibility frameworks strengthen refurbishment incentives for rental providers. Industrial concentration in the Rhine-Ruhr metropolitan region supports high-volume fleet standardization for manufacturing sector clients.
United Kingdom
Educational institutions deploy rental for one-to-one computing initiatives with predictable replacement schedules. GDPR compliance obligations shape data sanitization protocols for returned computing equipment. London anchors demand from financial services firms prioritizing operational expenditure models during funding uncertainty.
France
Right-to-repair mandates extend product lifecycles and strengthen circular economy incentives for equipment lessors. ANSM and CNIL oversight intersects with consumer protection and data privacy requirements for refurbished device redistribution. The Île-de-France region concentrates enterprise demand from public sector technology refresh programs.
India
Venture-backed companies prioritize operational expenditure models to eliminate capital lock-up during funding uncertainty. BIS certification requirements and DGFT import regulations shape cross-border equipment procurement timelines. Bengaluru and Mumbai anchor startup ecosystem demand for flexible workforce scaling solutions.
Electronic Products Rental Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue digital-first underwriting and subscription-based automatic upgrades. The market structures around three distinct maturity tiers: physical storefront operators with suburban presence, digital-native platforms with lease-to-own capabilities, and specialized event-centric logistics providers. Three strategic archetypes dominate competitive positioning: fleet-scale lessors optimizing asset utilization through predictive maintenance, high-touch service specialists commanding premium pricing for complex deployments, and technology-integrated platforms embedding automatic refresh triggers into contract structures. Competitive intensity concentrates on M&A activity targeting regional warehousing networks and strategic partnerships with enterprise procurement software vendors.
Within the physical storefront tier, Rent-A-Center anchors suburban market access across United States demographic segments preferring equipment inspection. Prog Holdings, Inc. and FlexShopper Inc. exemplify digital-first underwriting architectures extending lease-to-own options to liquidity-constrained households. Meeting Tomorrow Inc. occupies a specialist position in event-centric technology logistics, sustaining premium pricing through high-touch deployment capabilities and technical support services. These three operators collectively represent the dominant service model archetypes shaping competitive dynamics across consumer and enterprise segments.
| Leading Market Players |
|---|
| Reliance Retail Limited |
| Rentacomputer.com Inc. |
| Prog Holdings, Inc. |
| Buddy's Home Furnishings Inc. |
| Meeting Tomorrow Inc. |
| Rent-A-Center |
| FlexShopper Inc. |
| Cort Business Services Corporation |
| Aaron's Company, Inc. |
| Others |
Supply Flow & Price Mechanics
Corporate IT procurement teams in the United States anchor demand concentration for enterprise computing fleets, locking in subscription-based pricing models that bundle refresh cycles with predictive maintenance services. Their multi-year contract volumes create pricing power asymmetries against mid-market rental providers lacking comparable fleet standardization.
Pricing Analysis
Distributor margin compression runs through the audio equipment tier where seasonal demand peaks and thinner margins force project-based rate cards. Three-tier pricing structure across premium event logistics, standard corporate fleet, and economy consumer lease-to-own segments differentiates service bundles. Pricing pressure stems from semiconductor supply volatility extending procurement timelines for current-generation hardware. Individual consumers exhibit highest price sensitivity, while event organizers absorb premium rates for high-touch deployment capabilities.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for advanced semiconductor components, while China anchors refurbishment equipment and Mexico supports nearshore logistics hubs. Raw material dependencies span rare earth elements for display panels, lithium-ion cells for battery systems, and copper wiring for power distribution. Tariff exposure on cross-border equipment flows creates structural risk for international fleet deployments. Distribution runs through regional warehousing networks with last-mile integration to corporate procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory arbitrage between EU Green Deal compliance costs and EPA e-waste guideline enforcement creates geographic differentiation opportunities for refurbishment operations. Lessors optimizing residual value recovery locate certified recovery pipelines where administrative burdens lighten relative to primary markets.
For Market Incumbents: Anchor defensive positioning through backward integration into certified refurbishment capabilities as EU right-to-repair mandates extend product lifecycles. Consolidate regional warehousing networks to reduce cross-border logistics friction threatening turnaround economics. Fleet-scale lessors must embed predictive maintenance triggers into contract structures before digital-native platforms capture subscription service expansion. For New Entrants and Emerging Players: Launch via digital-first underwriting architectures targeting liquidity-constrained startup ecosystems in Bengaluru and Mumbai where operational expenditure models eliminate capital lock-up. White-space concentration sits with educational institutions deploying one-to-one computing initiatives with predictable replacement schedules. Specialized event-centric technology logistics rewards rapid-deployment capabilities in coastal metropolitan clusters. For Investors and Strategic Acquirers: Enterprise software vendors with procurement platform integration capabilities are the most active acquirer in this space, seeking API connectivity to client fleet management systems. Long-term viability hinges on circular economy credential differentiation as CSRD disclosure requirements mature. Watch for state-level right-to-repair legislation passage as inflection indicator for refurbishment infrastructure valuation.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Refurbishment Pipeline Investment | EU Green Deal compliance unlocks competitive positioning in German and French procurement cycles. |
| API Integration with Enterprise Procurement Platforms | Seamless connectivity to client systems reduces mid-market onboarding friction for fleet management. |
| Regional Warehousing Network Expansion | Proximity to coastal metropolitan clusters accelerates turnaround for project-based audiovisual demand. |
| Predictive Maintenance Platform Development | Sensor-enabled utilization tracking enables dynamic contract pricing and idle inventory reduction. |
| Subscription-Based Automatic Upgrade Programs | Bundled refresh cycles capture recurring revenue with highest expansion velocity across corporate segments. |
Methodological Framework
Direct dialogue with rental fleet operations directors, corporate IT procurement officers, refurbishment facility managers, and event logistics coordinators grounded qualitative insights. Secondary validation drew from SEC 10-K filings of publicly traded lessors, EPA e-waste guideline documentation, EU Circular Economy Action Plan regulatory texts, and customs records for cross-border equipment flows. Bottom-up equipment category modeling and top-down macroeconomic triangulation converged on segment-level outputs.
Market size and growth trajectory outputs across the projection horizon reflect equipment-as-a-service adoption curves, remote workforce normalization patterns, and circular economy policy implementation timelines. Segmentation dimensions modeled include product type, end user archetype, service model structure, and delivery method configuration. CAGRs derived from historical fleet deployment data and forward contract pipeline analysis, with semiconductor supply volatility and residual value compression risk factored as scenario weights.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated right-to-repair legislative adoption or sustained component shortage conditions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Mini Bluetooth Shower Speaker Market
Consumer Electronics
Global Earphones and Headphones Market
Consumer Electronics
Soft Support Products Market
Consumer Electronics
Smart Audio Devices Market
Consumer Electronics
Gaming Laptops and Desktops Market
Consumer Electronics
DVD Remote Controls Market
Consumer Electronics
Ereader Market
Consumer Electronics
Smart TV Market
Consumer Electronics
Gaming Computer Market
Consumer Electronics
China Massage Equipment Market
Consumer Electronics
Waterproof Speaker Market
Consumer Electronics
Digital Accessories Market
Consumer Electronics
Europe Stylus Pen Market
Consumer Electronics
Refurbished Computer and Laptop Market
Consumer Electronics
Instant Camera's Consumable Market
Consumer Electronics
Ultraman Peripheral Market