
 Middle East and Africa Mobile Phone Accessories Market | 2026-2036
Middle East and Africa Mobile Phone Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Mobile Phone Accessories Market Foresight
E-commerce platforms across the Middle East and Africa are reshaping how mobile phone accessories reach end buyers, bypassing traditional wholesale layers that once dominated distribution. Samsung Electronics Co., Ltd leverages its established service center network to anchor premium accessory sales alongside device purchases in South Africa and the UAE. Anker Innovations competes aggressively on charging technology, sustaining brand recognition through wattage leadership in multi-port adapters. Tecno Mobile Limited controls bundled accessory flows across Nigeria and Kenya, where its smartphone market presence drives parallel demand for cases and screen protectors.
Middle East and Africa mobile phone accessories encompass protective, power, and audio peripherals engineered to specific device dimensions, connector protocols, and voltage standards, with polymer formulations and lithium-ion cell densities serving as critical technical parameters for durability and charging speed. The primary commercial purpose centers on extending device utility, reducing replacement frequency, and enabling personalization in markets where smartphones represent primary computing and financial transaction tools. Cases and screen protectors occupy the largest volume share due to high replacement rates in dust-prone and physically demanding environments across the region. Chargers represent the fastest-expanding margin pool as USB-C Power Delivery and gallium nitride technology displace legacy adapters. Headphones segment growth concentrates in true wireless formats, with individual consumers driving disproportionate demand relative to corporate clients.
South Africa's National Regulator for Compulsory Specifications enforces safety standards on electrical accessories, while Nigeria's Standards Organisation mandates SONCAP certification for imported chargers and batteries, creating compliance cost barriers for unbranded imports. The UAE's Telecommunications and Digital Government Regulatory Authority coordinates device interoperability standards that shape regional product specifications. Stakeholders must monitor how divergent national certification timelines affect inventory planning and whether harmonization efforts among African economic communities accelerate or complicate cross-border accessory trade.
Market Dynamics
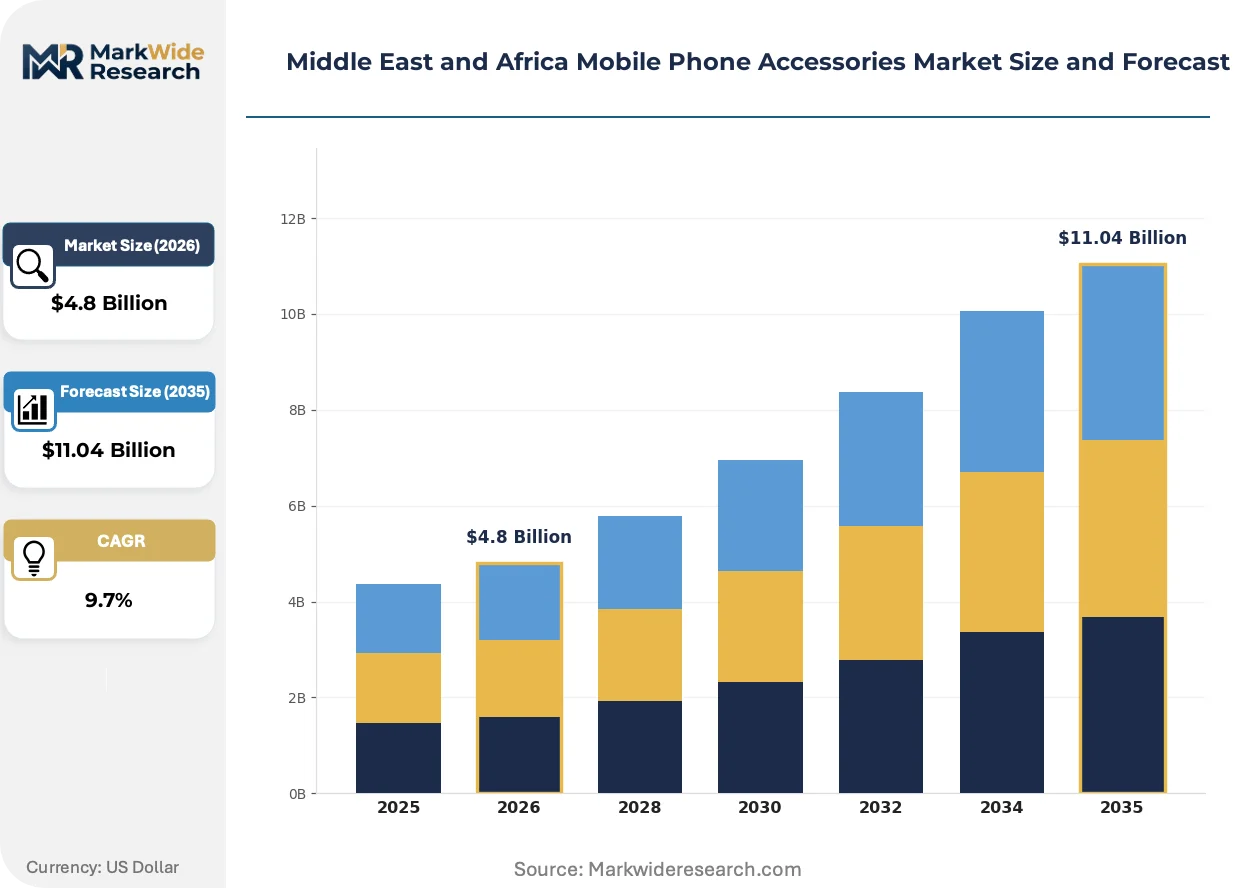
USB-C Power Delivery standardization is compressing charger replacement cycles across the Middle East and Africa, while Nigeria's SONCAP certification mandates and South Africa's NRCS safety enforcement are restructuring import compliance costs for accessory vendors.
Growth Catalysts
- Gallium nitride semiconductors:These materials enable smaller, cooler-running adapters that satisfy space-constrained urban consumers in Lagos and Nairobi. Wattage density improvements support multi-device charging from single outlets.
- Nigeria's consumer protection directives on e-waste:These rules mandate recyclable packaging and certified charging standards, pushing established brands to capture share from unbranded competitors.
- Smartphone penetration in middle-income demographics:Device ownership expansion across Nigeria and South Africa creates parallel pull for protective cases, screen protectors, and audio peripherals.
Market Restraints
- Lithium-ion cell price volatility:Power bank and wireless charging pad margins compress when battery raw material costs spike, squeezing mid-tier vendors without forward contracts.
- Import concentration through Dubai's Jebel Ali port:Regional distribution gravity creates single-point vulnerability for landlocked African markets dependent on UAE transshipment.
- Legacy Micro-USB inventory drag:Sub-Saharan retail channels still carry substantial obsolete connector stock, delaying full USB-C transition and fragmenting adapter demand.
Strategic Opportunities
- Kenya's mobile money infrastructure:M-Pesa integration with e-commerce platforms enables direct-to-consumer accessory sales bypassing traditional wholesale layers.
- True wireless earbuds for fitness applications:Sweat-resistant IP ratings and biometric sensor convergence open premium positioning among health-conscious urban professionals.
- UAE's device interoperability standards:TDRA-coordinated regional specifications create scale advantages for vendors certifying once for multiple Gulf markets.
Industry Challenges
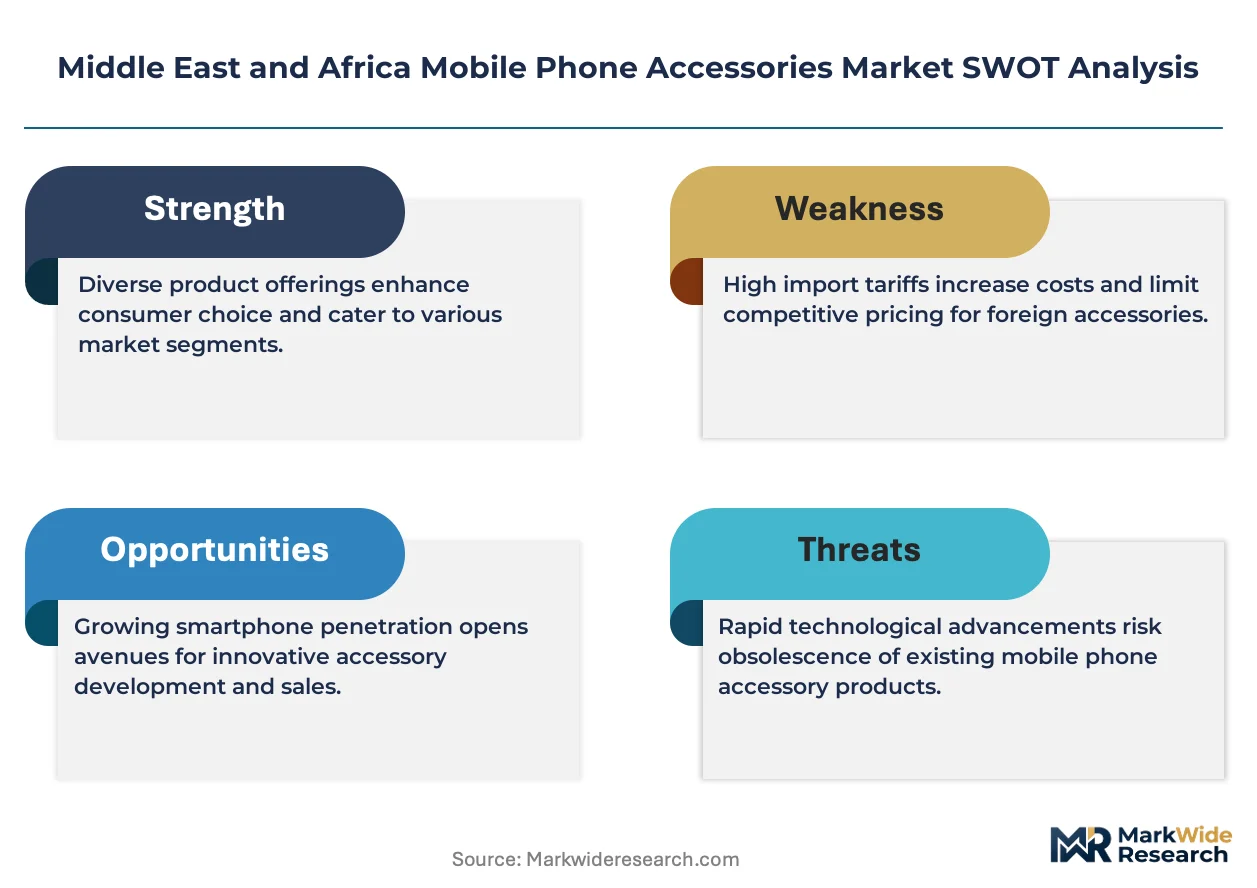
- Divergent national certification timelines:Nigeria's SONCAP, South Africa's NRCS, and UAE's TDRA operate on non-harmonized review schedules, complicating inventory planning for cross-border vendors.
- Counterfeit detection capability gaps:Customs authorities in secondary African markets lack technical equipment to identify substandard lithium-ion cells in imported power banks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Mobile Phone Accessories Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Accessory Type: Cases, Screen Protectors, Chargers, Headphones Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Customer Type: Individual Consumers, Corporate Clients, Retailers, Resellers Material: Plastic, Leather, Metal, Fabric |
| Companies Covered | G-Mobile Devices Pvt. Ltd. (Infinix), Huawei Technologies Co., Ltd., Samsung Electronics Co., Ltd, Anker Innovations, Ascendeo France SAS (Muvit), Apple Inc., Xiaomi Inc., Safaricom Plc, Tecno Mobile Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Mobile Phone Accessories Market Shifts & Advancements
Accessory functionality is converging with device management software, while regulatory pressure on electronic waste and safety certification is elevating compliance from cost center to competitive differentiator across Middle East and Africa markets.
Gallium nitride power electronics is migrating from premium laptop chargers toward smartphone and tablet adapters across Dubai and Johannesburg retail channels. Urban professionals and small business owners are adopting these compact, high-wattage units for travel and workspace consolidation. The technology is migrating from niche enthusiast segments toward mass-market replacement cycles, compressing average selling prices for legacy silicon-based adapters.
South Africa's National Regulator for Compulsory Specifications now mandates thermal runaway testing for all imported lithium-ion battery accessories. This enforcement eliminates uncertified power bank and wireless charging pad imports previously common in informal retail channels. Vendor response concentrates on pre-shipment laboratory certification in Shenzhen and Hong Kong to avoid port-of-entry rejection.
Young professionals in Lagos, Nairobi, and Dubai are unbundling accessory purchases from device replacement cycles, treating protective cases and audio peripherals as independent fashion and productivity statements. E-commerce platforms capture this behavior through installment payment integration and social commerce features, displacing traditional electronics bazaar channels. Kenya and Nigeria exhibit the most pronounced channel shift, where Instagram and WhatsApp commerce now accounts for substantial premium accessory volume.
Middle East and Africa Mobile Phone Accessories Market Segmentation
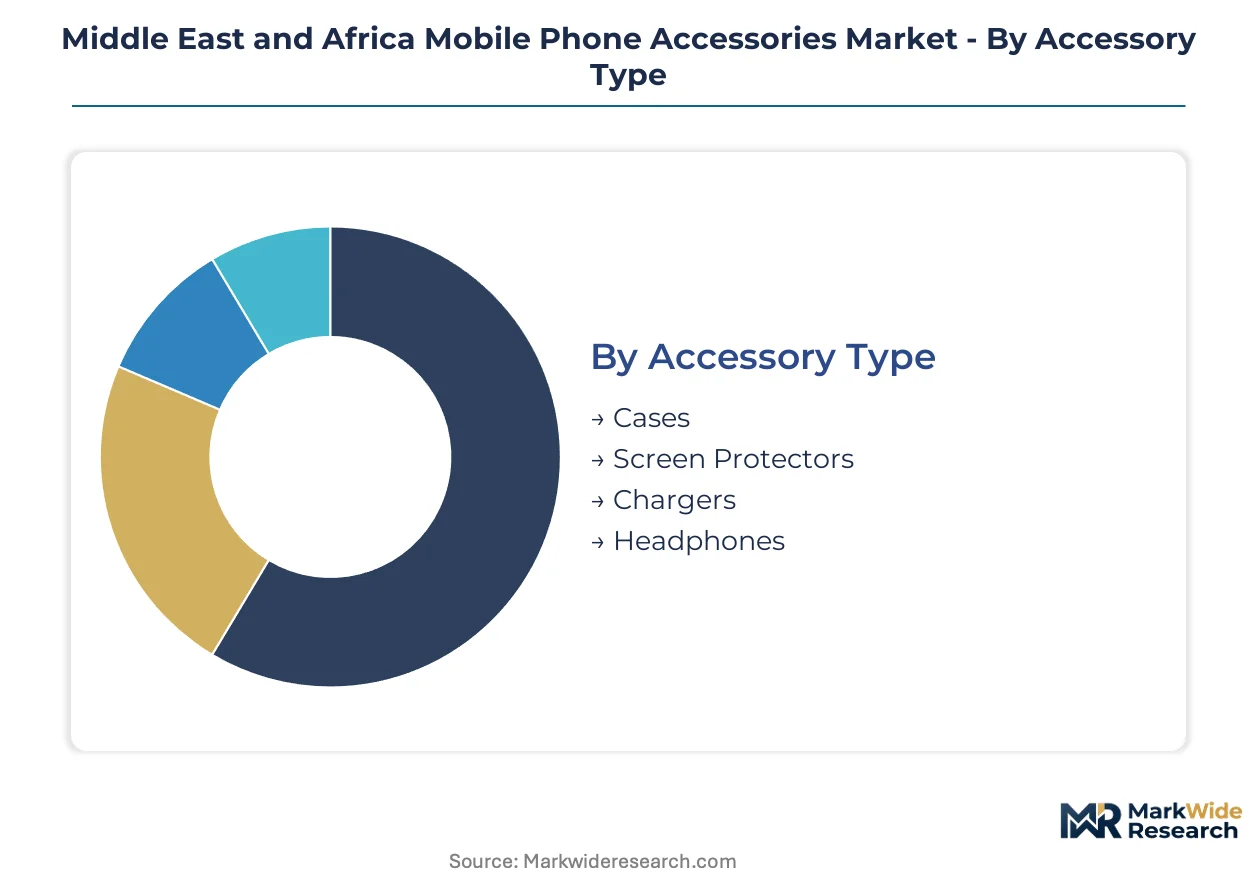
Mobile phone accessories in the Middle East and Africa exhibit distinct replacement cycles and margin profiles across each segment. Understanding these patterns reveals where after-sales-service intensity drives vendor profitability and customer retention.
Accessory Type:
After-sales-service intensity varies sharply across accessory categories, with power products demanding technical support while protective items rely on visual merchandising.
- Cases:Polymer and thermoplastic polyurethane formulations dominate, with anti-yellowing additives critical for UV-exposed climates. Demand concentrates in Lagos and Nairobi, where dust exposure and physical handling accelerate replacement cycles among young professionals.
- Screen Protectors:Tempered glass with oleophobic coating provides scratch resistance and fingerprint reduction. Nigerian and South African middle-income demographics drive volume, treating frequent replacement as cost-effective device insurance.
- Chargers:Gallium nitride semiconductors enable compact multi-port USB-C Power Delivery units.
- Headphones:True wireless formats with IP sweat resistance expand fastest among fitness-conscious urban consumers.
Cases hold the largest share; momentum sits with chargers as USB-C standardization compresses replacement cycles.
Distribution Channel:
Cost tier stratification determines channel viability, with premium products requiring trust-building touchpoints and commodity accessories flowing through high-velocity outlets.
- Online Retail:Jumia and noon.com anchor e-commerce volume, with M-Pesa integration in Kenya enabling installment purchases. Lagos and Nairobi professionals drive premium earbud and fast-charger sales through social commerce features.
- Supermarkets:Mass-market cases and basic cables stock alongside electronics sections in Shoprite and Carrefour hypermarkets. South African and Nigerian urban centers favor convenience purchasing for sub-premium tiers.
- Specialty Stores:Samsung service centers and independent mobile repair shops anchor certified accessory sales.
- Wholesale:Dubai's Jebel Ali port feeds landlocked African markets through distributor networks.
Online retail is expanding most quickly; wholesale retains volume leadership in sub-Saharan supply chains.
Customer Type:
Application context separates customer segments, with individual purchases driven by personalization and corporate procurement governed by standardization mandates.
- Individual Consumers:Unbundled accessory purchases now outpace device-bundled sales across Lagos, Nairobi, and Dubai. Fashion-forward case designs and fitness-integrated earbuds dominate this segment.
- Corporate Clients:Bulk charger and headset procurement for field workforce deployment. South African mining and logistics firms drive ruggedized case demand with enterprise durability specifications.
- Retailers:Electronics bazaar vendors and mall kiosks stock high-velocity protective accessories.
- Resellers:Cross-border traders source certified products through UAE transshipment for Nigerian and Kenyan redistribution.
Individual consumers generate the steepest expansion trajectory; retailers maintain the deepest volume base.
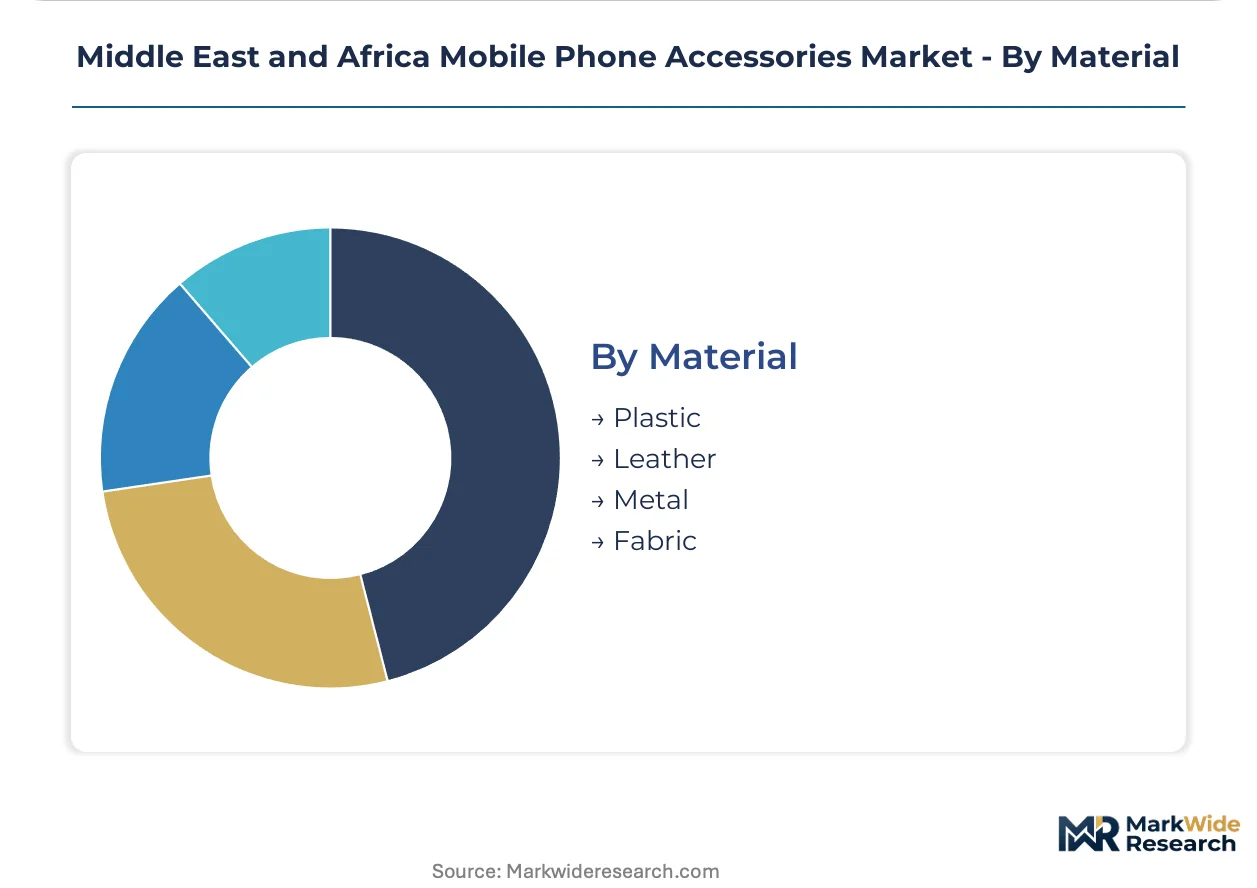
Material:
Supply concentration shapes material availability, with petroleum-derived polymers dominating and premium alternatives constrained by leather finishing capacity and metal fabrication costs.
- Plastic:Polycarbonate and TPU formulations offer impact absorption at lowest unit cost. Nigerian and Kenyan mass markets prioritize affordability over premium feel.
- Leather:Genuine and synthetic leather cases target Dubai and Johannesburg premium segments. South African ostrich leather finishing provides regional differentiation for luxury positioning.
- Metal:Aluminum alloy frames and magnesium charging station housings.
- Fabric:Woven textile cases with antimicrobial treatment for humid climates.
Plastic commands the largest share; leather gains share fastest as Gulf premium segments expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium accessory pricing in Dubai commands margins double those achievable in Lagos street markets, yet Nigerian volume throughput exceeds UAE dealer shipments by a factor of three. This asymmetry shapes vendor portfolio decisions across the region.
United Arab Emirates
Dubai's Jebel Ali port anchors transshipment for landlocked African markets, with TDRA-coordinated interoperability standards enabling single-certification access across Gulf Cooperation Council states. MOHAP-aligned product safety protocols elevate compliance costs for unbranded imports. The Dubai Silicon Oasis cluster concentrates regional distribution headquarters for premium charging and audio brands serving Saudi and Qatari secondary markets.
Nigeria
Lagos and Abuja drive West African demand for protective cases and fast-charging solutions, with young professionals unbundling accessory purchases from device replacement cycles. Standards Organisation of Nigeria mandates SONCAP certification for all imported chargers and batteries, eliminating informal channel competitors. The Alaba International Market electronics cluster in Lagos remains the continent's largest informal redistribution hub, though certified brands now capture increasing shelf space.
South Africa
Johannesburg and Cape Town anchor sub-Saharan premium consumption, with middle-income demographics sustaining replacement cycles for screen protectors and true wireless earbuds. National Regulator for Compulsory Specifications enforces thermal runaway testing for lithium-ion battery accessories, restructuring import compliance costs. The Centurion electronics manufacturing corridor hosts regional assembly operations for select charging product lines.
Kenya
Nairobi's young urban professionals drive East African demand for fitness-integrated audio peripherals, with M-Pesa integration enabling direct-to-consumer e-commerce bypassing traditional wholesale layers. Communications Authority of Kenya coordinates device interoperability standards shaping regional product specifications. The Konza Technology City cluster attracts logistics investments supporting cross-border redistribution to Uganda and Tanzania.
Saudi Arabia
Riyadh and Jeddah concentrate Gulf demand for luxury-positioned leather cases and premium charging stations, with SFDA-aligned safety standards converging with UAE protocols. The country's national telecommunications regulator coordinates 5G device accessory specifications. The King Abdullah Economic City logistics zone near Jeddah serves as secondary transshipment point for Red Sea access to Egyptian and Sudanese markets.
Middle East and Africa Mobile Phone Accessories Market Competitive Landscape
Device-anchored incumbents and specialized charging specialists split the market along bundling-versus-unbundling fault lines. Samsung Electronics Co., Ltd leverages service center networks to capture premium accessory attach rates alongside smartphone purchases. Tecno Mobile Limited controls bundled flows across Nigeria and Kenya through parallel smartphone market presence. Anker Innovations competes on wattage leadership in multi-port adapters. Dominant competitive moves include portfolio diversification into adjacent power categories and geographic expansion through UAE certification anchoring Gulf market access.
Among Asia-Pacific headquartered electronics conglomerates, Huawei Technologies Co., Ltd and Xiaomi Inc. occupy positions spanning device and accessory verticals, with regional distribution calibrated to TDRA and SONCAP compliance timelines. Samsung Electronics Co., Ltd anchors the device-anchored archetype through integrated retail presence. These three exemplify how scale advantages in certification and logistics reshape competitive positioning across fragmented African retail channels.
| Leading Market Players |
|---|
| G-Mobile Devices Pvt. Ltd. (Infinix) |
| Huawei Technologies Co., Ltd. |
| Samsung Electronics Co., Ltd |
| Anker Innovations |
| Ascendeo France SAS (Muvit) |
| Apple Inc. |
| Xiaomi Inc. |
| Safaricom Plc |
| Tecno Mobile Limited |
| Others |
Supply & Pricing Matrix
Dubai's Jebel Ali port capacity expansions and transshipment bottlenecks directly compress margin capture for downstream vendors serving Lagos and Nairobi retail channels. SONCAP certification costs and NRCS thermal testing mandates add fixed compliance layers that unbranded competitors cannot absorb, shifting price power toward certified incumbents.
Pricing Analysis
The customization-premium spread between configured-to-order gallium nitride chargers and standard silicon adapters runs wide across Middle East and Africa retail channels. Pricing stratifies across premium, standard, and economy tiers, with USB-C Power Delivery wattage ratings and SONCAP certification status serving as primary price differentiation drivers. Cost compression in economy-tier Micro-USB legacy stock is intensifying because Nigerian distributors are liquidating obsolete inventory ahead of full USB-C transition. Corporate procurement teams in South African mining and logistics sectors show least price sensitivity, prioritizing thermal runaway certification and enterprise durability specifications over unit cost.
Supply Chain Analysis
Upstream lithium-ion cell production draws from China, South Korea, and Japan, with gallium nitride semiconductor wafer fabrication concentrated in Taiwan and the United States. Polymer resin and thermoplastic polyurethane formulations for protective cases rest on petrochemical feedstocks from Saudi Arabia and the UAE. Single-source vulnerability runs through Jebel Ali port congestion, where transshipment delays cascade to landlocked East and West African markets. Distribution runs through three-tier structures: Shenzhen and Hong Kong pre-certification laboratories, Dubai redistribution hubs, and Lagos or Nairobi last-mile electronics bazaar networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification regimes and channel structures creates niche entry points for specialized players. Unbundled accessory purchasing among young urban professionals is splintering demand away from device-bundled flows, opening positioning for independent audio and charging brands.
For Market Incumbents: Build certification moats through pre-shipment laboratory partnerships in Shenzhen and Hong Kong that guarantee SONCAP and NRCS port-of-entry clearance. Defensive moves center on captive supply of gallium nitride semiconductors to secure wattage leadership against Anker Innovations, plus service center network densification in South Africa and Nigeria to capture attach rates. The threat of counterfeit lithium-ion cells flooding informal channels through customs detection gaps demands investment in holographic packaging and traceability systems. For New Entrants and Emerging Players: Establish a beachhead in Kenya's M-Pesa-integrated direct-to-consumer channel, where installment payment infrastructure bypasses traditional wholesale layers entirely. White-space targets include fitness-integrated true wireless earbuds with biometric sensors for Nairobi's health-conscious professionals, and recyclable packaging-compliant charging products for Nigeria's e-waste directive environment. The go-to-market angle leverages Instagram and WhatsApp commerce features that already account for substantial premium accessory volume in Lagos and Nairobi. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors gallium nitride power electronics specialists with established UAE TDRA certification anchoring Gulf market access. Long-term viability hinges on USB-C Power Delivery standardization completing its displacement of legacy adapters across the analysis window, with backward integration into lithium-ion cell supply or upstream semiconductor partnerships determining margin sustainability. The signal to watch is harmonization progress among African economic communities on cross-border certification recognition, which would collapse inventory complexity and favor scaled regional distributors.| Strategic Initiative | Industry Significance |
|---|---|
| Gallium Nitride Product Line Expansion | Wattage leadership in multi-port USB-C Power Delivery chargers captures replacement cycle compression in Dubai and Johannesburg. |
| Pre-Shipment Certification Partnership | Shenzhen and Hong Kong laboratory relationships eliminate SONCAP and NRCS port-of-entry rejection risk for Nigerian and South African shipments. |
| M-Pesa Integration for Direct Sales | Kenya's mobile money infrastructure enables installment purchases bypassing traditional wholesale margin extraction. |
| Recyclable Packaging Compliance | Nigeria's e-waste directives push certified brands to capture shelf space from unbranded competitors at Alaba International Market. |
| Service Center Network Densification | Samsung-style integrated retail presence in South Africa and Nigeria drives premium accessory attach rates alongside smartphone sales. |
Research Methodology
A spread of perspectives from accessory product managers at device-anchored incumbents, procurement leads at South African mining firms, e-commerce platform category heads at Jumia and noon.com, and regulatory affairs specialists at SONCAP and NRCS converged on the working assumptions driving this analysis. Primary interview insights combined with secondary validation from customs and trade data, TDRA and SONCAP certification filings, and SEC 10-K disclosures from listed electronics conglomerates. Bottom-up demand modeling across Lagos, Nairobi, Dubai, and Johannesburg retail channels triangulated against top-down smartphone penetration and replacement cycle estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning accessory type, distribution channel, customer archetype, and material formulation. CAGRs derived from installed base dynamics, replacement frequency assumptions, and unbundled purchase behavior shifts among young urban professionals. Industry-specific forecast inputs included gallium nitride semiconductor cost curves and lithium-ion cell raw material price volatility patterns.
Macroeconomic conditions sit as an overlay; deviation in Nigerian naira exchange rates, South African rand stability, or UAE dirham peg sustainability would shift the trajectory of import-dependent supply chains. Forecasts reflect assumptions around USB-C Power Delivery standardization pace and African economic community harmonization progress. Cross-checking against smartphone shipment data from regional distribution hubs and e-commerce platform transaction volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Consumer Electronics
Global Speaker Market
Consumer Electronics
Handheld Device Accessories Market
Consumer Electronics
US Refurbished and Used Mobile Phones Market
Consumer Electronics
Keycap Market
Consumer Electronics
Tattoo Stencil Printer Market
Consumer Electronics
Vertical Ergonomic Optical Mouse Market
Consumer Electronics
Global 4K TV Market
Consumer Electronics
Consumer Electronic Biometrics Market
Consumer Electronics
Instant Camera Market
Consumer Electronics
Education PC Market
Consumer Electronics
Blu Ray Players Market
Consumer Electronics
Global Monitor Headphones (in-Ear Monitors) Market
Consumer Electronics
Kids Tablet Market
Consumer Electronics
United States Soundbar Market
Consumer Electronics
Universal Remote Controls Market
Consumer Electronics
Pet Monitoring Camera Market