
 Consumerware Market | 2026-2036
Consumerware Market Size, Share, and Industry Trends Forecast 2026-2036
Consumerware Market Insights
Premium-grade smart connectivity is bifurcating the consumerware landscape into performance-tier and value-tier camps. Groupe SEB leverages its European manufacturing base to sustain leadership in precision-engineered home appliances. Hawkins Cookers anchors the South Asian market through specialized pressure-cooker metallurgy and localized distribution networks. Meyer Corporation differentiates via in-house clad-metal technology and direct-to-consumer channel control across North American retail.
Consumerware encompasses durable and semi-durable goods designed for household or personal use, typically incorporating electronic interfaces, polymer or metal-composite housings, and power ratings from milliwatts for wearables to kilowatts for major appliances; these products serve domestic convenience, entertainment, health management, and connectivity functions. Home automation applications command the widest margin pools as Wi-Fi-enabled ecosystems integrate with utility management platforms. Smart gadgets represent the fastest-expanding product type, driven by sensor miniaturization and falling semiconductor costs. Personal accessories remain mature, with NFC-enabled payment and identity devices now standard rather than differentiating.
FCC Part 15 emissions rules in the United States and ETSI EN 300 328 radio standards in Europe dictate wireless product certification timelines and testing costs, directly influencing which connectivity technologies manufacturers prioritize. MIIT in China enforces GB national standards for electromagnetic compatibility and energy efficiency, creating a dual-compliance burden for brands seeking cross-border market access. Stakeholders must monitor evolving interoperability mandates between regional certification regimes to avoid product redesign cycles that erode development budgets.
Market Dynamics
Bluetooth and Wi-Fi connectivity maturation under divergent regional certification regimes is fragmenting product development roadmaps and forcing parallel engineering tracks for manufacturers seeking cross-border market access.
Growth Catalysts
- MIIT GB standards compliance:China's mandatory electromagnetic compatibility and energy efficiency certifications accelerate domestic manufacturing scale and create captive supply advantages for certified producers serving adjacent Asian markets.
- Sensor miniaturization:Falling semiconductor lithography costs enable milliwatt-scale biometric and environmental sensors to proliferate across personal accessories and home automation endpoints.
- Utility management platform integration:Wi-Fi-enabled smart home ecosystems are capturing margin pools through demand-response contracts with electricity retailers and water utilities in deregulated markets.
Market Restraints
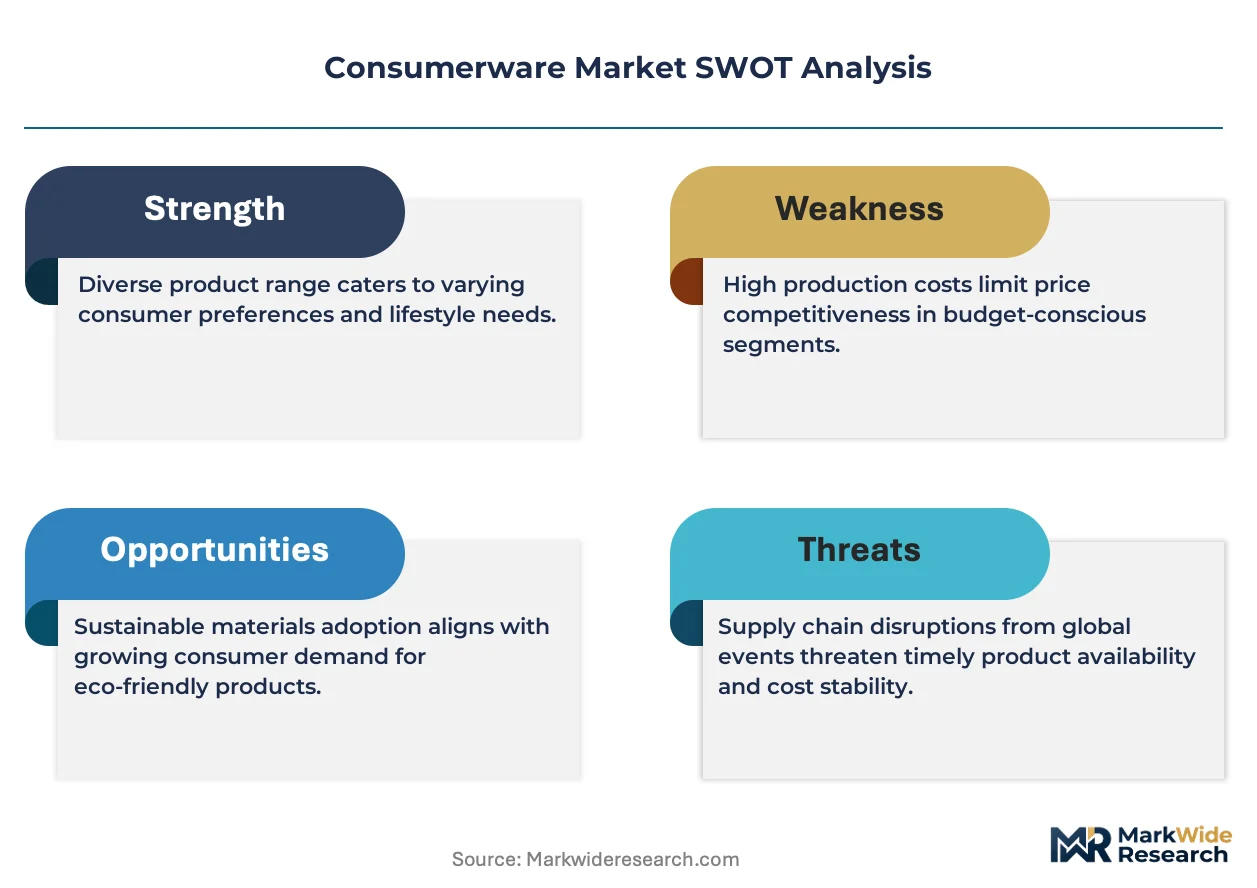
- Dual-certification burden:FCC Part 15 emissions rules in the United States and ETSI EN 300 328 radio standards in Europe impose redundant testing cycles that compress development budgets and delay product launches.
- Rare earth magnet supply concentration:Neodymium and dysprosium processing capacity clusters in China's Jiangxi and Inner Mongolia provinces, exposing motor and speaker manufacturers to export quota volatility.
- Polymer feedstock cost volatility:Engineering-grade polycarbonate and ABS resin prices fluctuate with benzene and propylene derivative markets, squeezing margin on injection-molded housings.
Strategic Opportunities
- India PLI scheme for white goods:Production-linked incentives for air conditioners and LED lighting create localized manufacturing footholds with reduced import duty exposure for component suppliers.
- Matter protocol convergence:The unified smart home interoperability standard backed by Apple, Google, and Amazon collapses fragmented hub requirements and opens retrofit opportunities in legacy installed bases.
- Direct-to-consumer channel control:Bypassing traditional retail intermediaries through owned e-commerce and subscription service models captures lifetime value data and reduces working capital intensity.
Industry Challenges
- RF engineering talent scarcity:Embedded antenna design and electromagnetic compatibility testing expertise concentrates in Shenzhen, Munich, and San Diego clusters, forcing remote hiring or outsourced certification management.
- Legacy system integration friction:Retrofitting Wi-Fi modules into decades-old appliance architectures requires firmware abstraction layers that complicate warranty liability and field service protocols.
- Interoperability mandate fragmentation:Diverging regional requirements for data localization, encryption standards, and cloud connectivity architectures multiply firmware variants and complicate over-the-air update pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumerware Market |
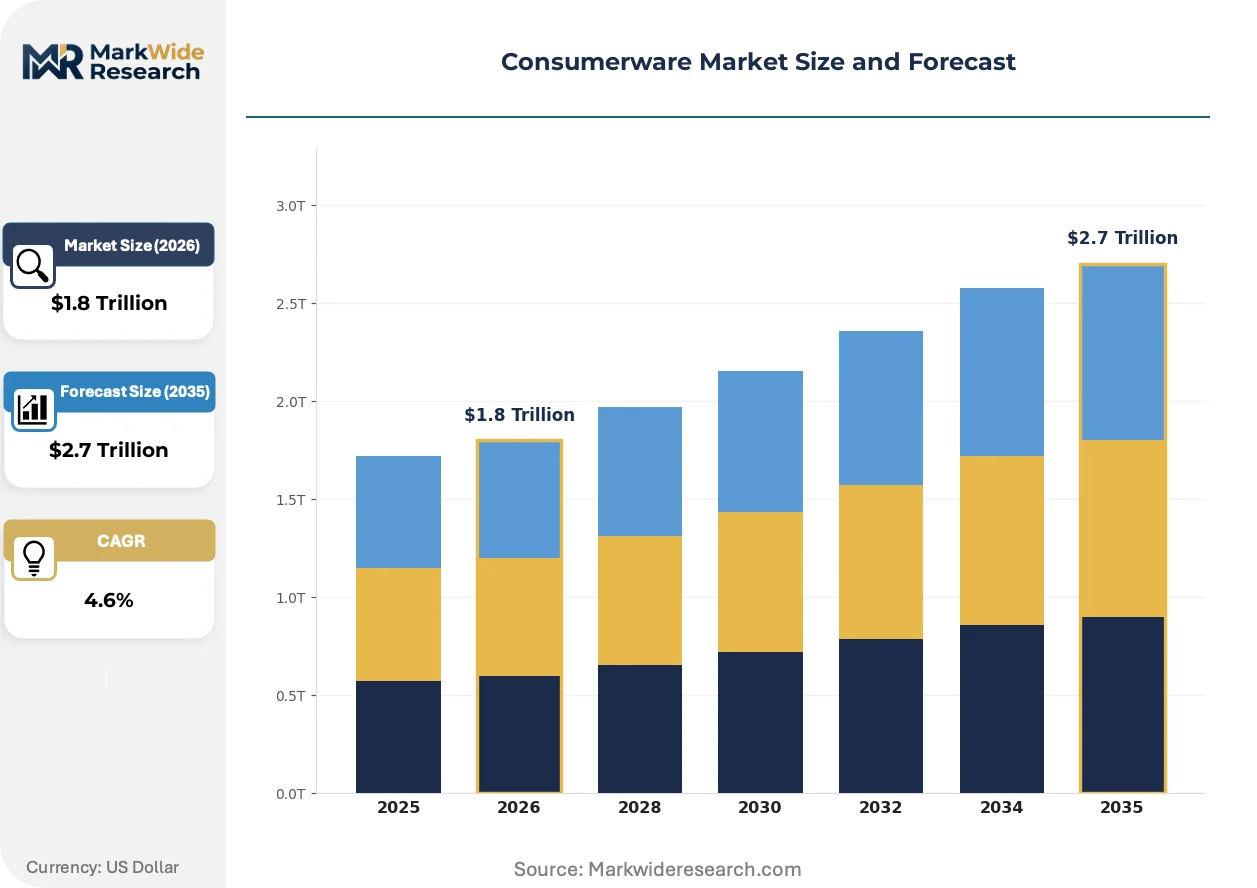
| Market Size in 2026 | $1.8 Trillion |
| Market Size in 2035 | $2.7 Trillion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
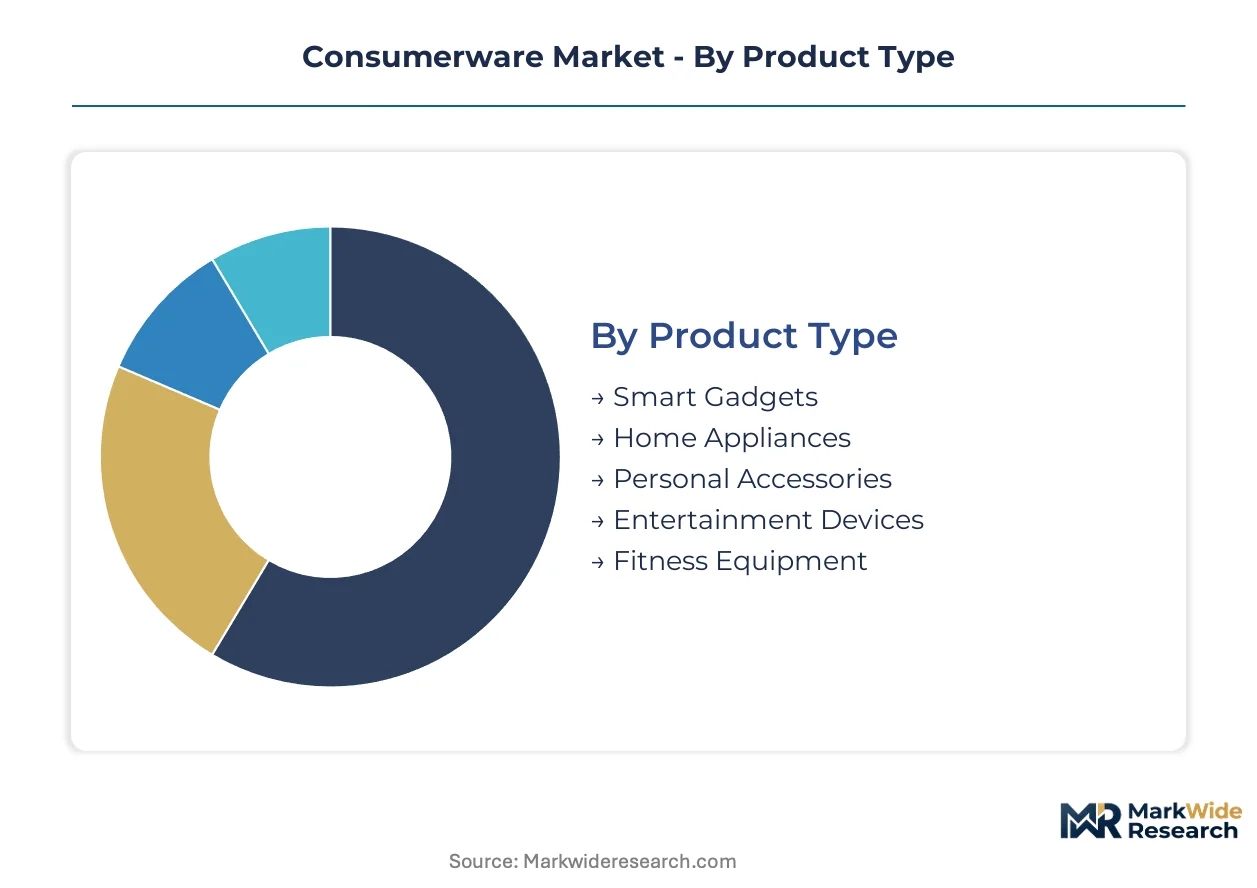
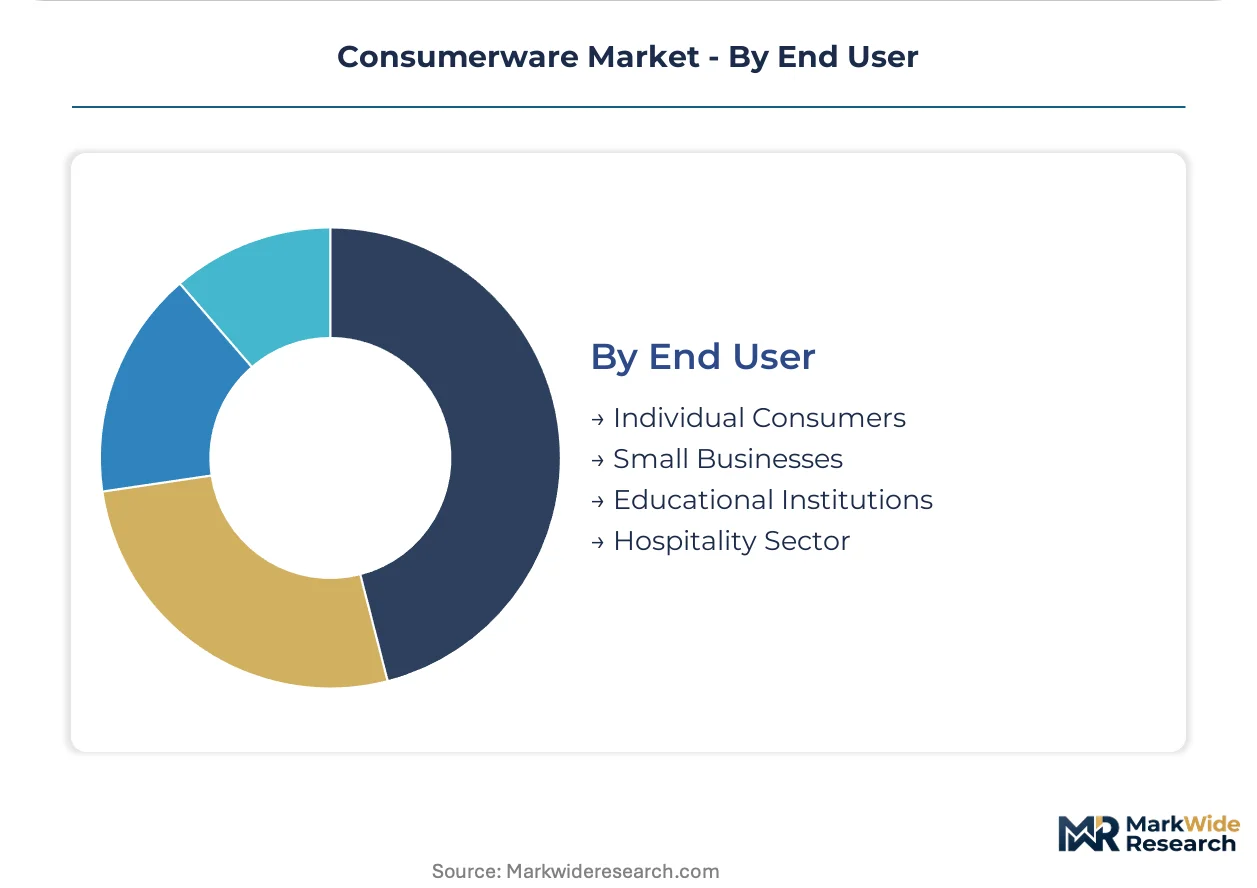
| Segmentation | Product Type: Smart Gadgets, Home Appliances, Personal Accessories, Entertainment Devices, Fitness Equipment Technology: Bluetooth, Wi-Fi, NFC, Infrared, Ultrasonic Application: Health Monitoring, Home Automation, Communication, Leisure, Security Systems End User: Individual Consumers, Small Businesses, Educational Institutions, Hospitality Sector |
| Companies Covered | Groupe SEB, Borosil, Cello, Cuisinart, Fissler, Hamilton Housewares, Hawkins Cookers, Meyer Corporation, Tramontina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumerware Market Trends and Innovations
Connectivity standard convergence and regulatory pressure on energy consumption are compressing product lifecycles while opening new service revenue models around predictive maintenance and usage-based insurance.
Matter-over-Thread is bifurcating the smart home protocol landscape. The low-power mesh networking standard enables battery-operated sensors to operate for years without replacement. Appliance manufacturers in South Korea and Taiwan are adopting Thread radios for kitchen and climate control endpoints. This technology is bifurcating the market into IP-native devices that command premium positioning versus legacy hub-dependent products facing accelerated obsolescence.
EU F-Gas Regulation phase-down mandates are forcing refrigerant transitions in cooling appliances. Hydrofluoroolefin blends and hydrocarbon alternatives require compressor redesigns and safety system investments. European manufacturers with captive compressor production are absorbing retooling costs faster than import-dependent competitors, reshaping competitive positioning in the region's major appliance segment.
Subscription bundling is displacing transactional hardware sales in premium smart home categories. Buyers increasingly expect continuous software feature updates, cloud storage, and priority support wrapped into annual fees. This pattern concentrates in North American and Nordic markets where household technology spending per capita exceeds $800 annually and financing infrastructure supports recurring payment models.
Consumerware Market Segmentation
Consumerware segmentation reveals how connectivity standards and certification regimes fragment product development across geographies. Manufacturers must align portfolio priorities with where demand concentrates versus where production costs optimize.
Product Type:
Domestic manufacturing clusters in China dominate home appliances and smart gadgets for regional supply, while European precision engineering sustains export-led premium positioning in fitness equipment and entertainment devices.
- Smart Gadgets:Sensor-embedded wearables and portable electronics with milliwatt-scale power draw and polymer-composite housings. Demand clusters in North American and Nordic markets where household technology spending per capita exceeds $800 annually, driven by subscription bundling expectations and continuous software update requirements.
- Home Appliances:Kilowatt-rated durable goods incorporating Wi-Fi modules and motor assemblies dependent on rare earth magnets. Chinese domestic absorption under MIIT GB standards compliance creates captive supply advantages for certified producers serving adjacent Asian markets through reduced cross-border certification friction.
- Personal Accessories:NFC-enabled payment and identity devices with standardized rather than differentiating connectivity features.
- Entertainment Devices:Streaming hardware and audio systems requiring FCC Part 15 or ETSI EN 300 328 radio certification.
- Fitness Equipment:Biometric-tracking hardware with Bluetooth Low Energy interfaces and cloud synchronization capabilities.
Home appliances command the established base. The steepest expansion runs through smart gadgets.
Technology:
Cost tier stratification separates premium IP-native protocols from legacy connectivity requiring hub intermediation, with certification burden directly determining which technologies manufacturers prioritize for cross-border market access.
- Bluetooth:Short-range wireless standard with mature certification pathways under FCC and ETSI frameworks. Sensor miniaturization and falling semiconductor lithography costs enable proliferation across personal accessories and home automation endpoints in battery-constrained form factors.
- Wi-Fi:High-throughput protocol commanding widest margin pools in home automation through utility management platform integration and demand-response contracts with electricity retailers.
- NFC:Proximity-based connectivity standard for payment authentication and device pairing.
- Infrared:Legacy line-of-sight protocol persisting in entertainment device remote controls.
- Ultrasonic:Niche positioning detection and ranging technology for spatial awareness applications.
Wi-Fi anchors the revenue base. Bluetooth climbs the fastest as sensor integration accelerates across portable categories.
Application:
Volume concentration in home automation reflects utility integration opportunities, while margin capture in health monitoring depends on regulatory clearance timelines for biometric data processing.
- Health Monitoring:Continuous physiological tracking systems with cloud data pipelines. FCC and HIPAA compliance requirements in the United States create dual-certification complexity for wearable manufacturers seeking clinical-adjacent positioning.
- Home Automation:Climate control, lighting, and security endpoint networks. Matter protocol convergence backed by Apple, Google, and Amazon collapses fragmented hub requirements and opens retrofit opportunities in legacy installed bases across North America.
- Communication:Voice and video calling hardware with embedded antenna design requirements.
- Leisure:Gaming peripherals and recreational electronics with seasonal demand patterns.
- Security Systems:Surveillance and access control devices with data localization mandates varying by jurisdiction.
Home automation commands the established base. Health monitoring gains share fastest through preventive care reimbursement trends.
End User:
Customer type determines channel structure, with individual consumers driving direct-to-commerce migration while hospitality and education sectors maintain procurement through specialized distributors with installation service bundling.
- Individual Consumers:Household purchasers acquiring through retail or owned e-commerce channels. Subscription bundling expectations in premium categories concentrate in markets with financing infrastructure supporting recurring payment models.
- Small Businesses:Commercial operators requiring scaled deployments with warranty and field service protocols.
- Educational Institutions:Bulk procurement with extended payment terms and interoperability requirements.
- Hospitality Sector:Property-wide system integration with brand standard compliance and centralized management platforms.
Individual consumers anchor the volume base. The hospitality sector expands most quickly through smart room retrofit programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances reshape competitive positioning across the consumerware sector. Nations with captive manufacturing scale and streamlined certification pathways capture disproportionate value in cross-border trade. Regulatory divergence between FCC, ETSI, and MIIT frameworks fragments product development roadmaps.
United States
Subscription bundling expectations drive premium smart home demand in coastal metropolitan markets. FCC Part 15 emissions rules dictate wireless product certification timelines and testing costs for manufacturers. San Diego and Austin clusters concentrate RF engineering talent for embedded antenna design and electromagnetic compatibility testing.
China
Domestic manufacturing scale under MIIT GB standards compliance creates captive supply advantages for certified producers. Dual carbon goals and energy efficiency mandates accelerate refrigerant transitions in cooling appliances. Shenzhen anchors global sensor miniaturization and semiconductor lithography cost reduction.
Germany
EU F-Gas Regulation phase-down mandates force compressor redesign investments in major appliances. REACH and RoHS compliance requirements shape polymer feedstock selection for injection-molded housings. Bavaria and Baden-Württemberg sustain precision engineering clusters for premium home appliance production.
India
Production-linked incentive schemes for white goods attract localized manufacturing for air conditioners and LED lighting. BIS certification requirements and DGFT import duty structures reshape component supplier strategies. Maharashtra and Gujarat industrial corridors develop captive supply networks for pressure-cooker metallurgy and distribution infrastructure.
Japan
METI efficiency standards and JIS certification frameworks govern smart home ecosystem integration. Matter protocol adoption accelerates retrofit opportunities in legacy installed bases. Tokyo-Osaka industrial belt concentrates biometric sensor integration expertise for health monitoring applications.
Consumerware Market Competitive Landscape
Listed leaders compete with private specialists across certification burden absorption and channel control dimensions. The vendor base stratifies into three tiers: multinational conglomerates with captive regulatory affairs teams, regional specialists leveraging localized distribution, and private-label fabricators serving price-sensitive segments. Two dominant competitive moves define current positioning: direct-to-consumer channel migration to capture lifetime value data, and backward integration into rare earth magnet and polymer compound supply to hedge feedstock volatility.
Within the premium-tier precision engineering segment, Groupe SEB exemplifies European manufacturing base sustainability through specialized metallurgy capabilities. Meyer Corporation anchors North American positioning via in-house clad-metal technology and retail channel control. Hawkins Cookers occupies a distinctive position in South Asian market penetration through localized distribution networks and specialized pressure-cooker manufacturing expertise.
| Leading Market Players |
|---|
| Groupe SEB |
| Borosil |
| Cello |
| Cuisinart |
| Fissler |
| Hamilton Housewares |
| Hawkins Cookers |
| Meyer Corporation |
| Tramontina |
| Others |
Pricing and Supply Chain Analysis
MIIT GB standards compliance gates both supplier qualification and price differentiation simultaneously in the consumerware sector, as manufacturers absorbing electromagnetic compatibility and energy efficiency certification costs capture premium positioning while uncertified competitors face margin compression in adjacent Asian markets.
Pricing Analysis
Individual consumers anchor a three-tier pricing structure across premium, standard, and economy levels in the consumerware market. Price differentiation hinges on certification grade—FCC Part 15 versus ETSI EN 300 328 versus MIIT GB tiers—and after-sales service bundling including subscription software updates. Cost compression in the economy tier is intensifying because polymer feedstock volatility squeezes injection-molded housing margins. Hospitality sector buyers exhibit lowest price sensitivity due to smart room retrofit program budgets, while small businesses show highest sensitivity to upfront hardware costs.
Supply Chain Analysis
Inventory lead times for rare earth magnets extend procurement cycles as neodymium and dysprosium processing capacity clusters in China's Jiangxi and Inner Mongolia provinces. The supply chain draws from China for sensor miniaturization and semiconductor lithography, South Korea for Thread radio module production, and Taiwan for Wi-Fi chipset fabrication. Raw material dependencies include engineering-grade polycarbonate and ABS resin, rare earth magnet alloys, and clad-metal substrates. Single-source vulnerability in Chinese rare earth processing exposes motor and speaker manufacturers to export quota volatility. Distribution runs through owned e-commerce platforms, traditional retail intermediaries, and specialized distributors with installation service bundling for hospitality and education sectors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consumerware hardware margins are compressing while subscription bundling for continuous software updates, cloud storage, and priority support expands faster than transactional device sales, creating a service-attach opportunity that concentrates lifetime value capture in North American and Nordic markets.
For Market Incumbents: Fortify backward integration into rare earth magnet supply to hedge feedstock volatility from Chinese export quota restrictions. Deepen channel control through direct-to-consumer platform investments that capture usage data for predictive maintenance services. Matter protocol convergence threatens hub-dependent product obsolescence—accelerate IP-native device certification to defend premium positioning.
For New Entrants and Emerging Players: India's BIS certification fast-track for white goods under PLI schemes creates localized manufacturing footholds with reduced import duty exposure. Target hospitality sector smart room retrofits in Southeast Asian markets where procurement runs through specialized distributors lacking technical integration capabilities. Pursue white-label Thread radio module partnerships with South Korean appliance manufacturers seeking cost-competitive sensor endpoints.
For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down mandates reshape the acquisition landscape by forcing compressor redesign investments that favor European manufacturers with captive production. Five-to-ten year viability favors targets with in-house clad-metal technology or specialized pressure-cooker metallurgy expertise. Monitor refrigerant transition timelines as inflection indicators for major appliance segment consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Bypasses retail intermediaries to capture subscription lifetime value data in North American markets. |
| Matter Protocol Certification Investment | Collapses fragmented hub requirements and opens retrofit opportunities in legacy installed bases. |
| Backward Integration into Rare Earth Supply | Hedges neodymium and dysprosium export quota volatility from Chinese processing concentration. |
| India PLI Manufacturing Footprint | Creates localized air conditioner and LED lighting production with reduced DGFT import duty exposure. |
| Subscription Service Bundling | Displaces transactional hardware sales through continuous software updates and cloud storage annual fees. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, FCC equipment authorization records, and ETSI certification registries. Primary interviews engaged product development executives at smart home ecosystem platforms, regulatory affairs leads managing MIIT GB compliance, category buyers at North American retail chains, and aftermarket service heads at appliance manufacturers. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the consumerware value chain.
Segmentation dimensions modeled include product type, connectivity technology, application use case, end-user category, and regional certification regime across the projection horizon. CAGRs derive from installed base penetration curves, replacement cycle analysis, and utility management platform integration adoption rates. Forecast inputs incorporate semiconductor lithography cost reduction trajectories and refrigerant transition timelines under EU F-Gas Regulation mandates.
Decision-makers should treat outputs as directional under assumptions of stable FCC, ETSI, and MIIT regulatory frameworks; material divergence in interoperability mandate fragmentation or rare earth export policy would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Ironing Boards Market
Household Items
Germany Induction Hobs Market
Household Items
Chest Freezers Market
Household Items
Portable Iron Market
Household Items
Global Residential Robotic Vacuum Cleaner Market
Household Items
Qatar Gas Hobs Market
Household Items
Smart Faucets Market
Household Items
Desktop Air Purifier Market
Household Items
Smart Fork Market
Household Items
Europe Handheld Fans Market
Household Items
Saudi Arabia Cookware Market
Household Items
Smart Drying Racks Market
Household Items
Soap Tablet Market
Household Items
Asia-Pacific Handheld Vacuum Cleaner Market
Household Items
Dishwasher Tablets Market
Household Items
South Korea Cookware Market