
 Home Use Air Purifiers Market | 2026-2036
Home Use Air Purifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Home Use Air Purifiers Market Insights
The capital-intensity divergence between integrated filter manufacturers and assembly-focused brands is reorganizing competitive tiers in the home use air purifiers space. Daikin Industries Ltd. leverages captive compressor and filtration component production to control input costs across premium lines. Honeywell International Inc. anchors its position through deep HVAC channel relationships that extend into residential retrofit markets. Dyson differentiates via proprietary air multiplier mechanics and cyclonic separation patents that command price premiums in direct-to-consumer channels.
Home use air purifiers are electromechanical devices designed to remove particulate matter, volatile organic compounds, and biological contaminants from indoor air through forced filtration, electrostatic precipitation, or photocatalytic oxidation, typically rated by clean air delivery rate and particle size capture efficiency down to 0.3 microns. HEPA-based units dominate installed base volumes due to decades of clinical validation, while hybrid systems combining filtration with UV-C sterilization are capturing the fastest growth in premium residential segments. Photocatalytic technology occupies niche positioning among chemically sensitive homeowners seeking VOC reduction beyond particulate capture.
EPA ENERGY STAR certification, California Air Resources Board ozone emission limits, and EU Ecodesign requirements collectively determine market access thresholds and product development budgets for manufacturers serving multiple jurisdictions. These frameworks push stakeholders toward third-party validated performance claims and filter replacement transparency as baseline competitive requirements. Stakeholders must monitor evolving state-level VOC restrictions and emerging particulate standards in Asian certification regimes to anticipate compliance-driven redesign cycles.
Market Dynamics
Filter media supply concentration in East Asia is compressing margin structures for assembly-focused brands while rewarding backward-integrated manufacturers with captive nonwoven and activated carbon production.
Growth Catalysts
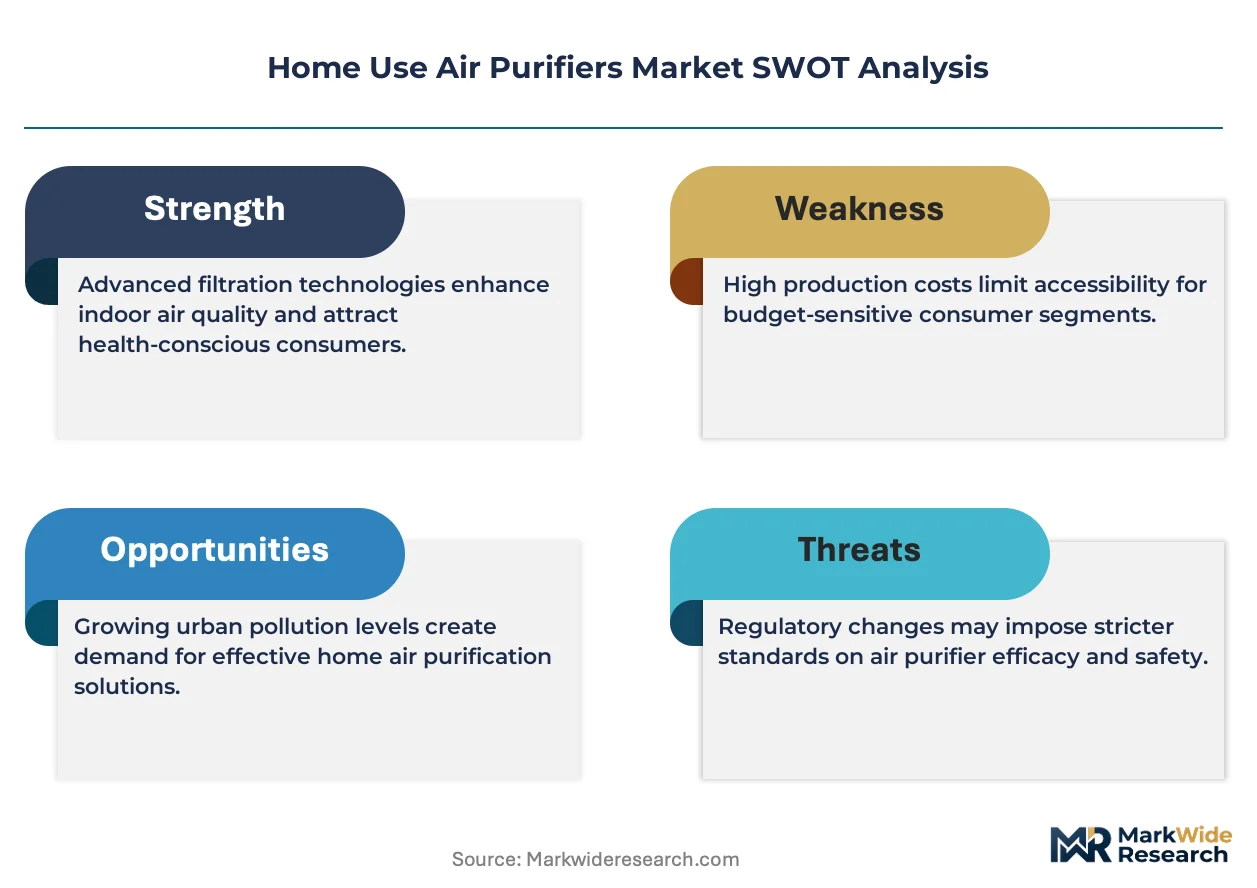
- EPA ENERGY STAR certification thresholds:Rising efficiency benchmarks force filter redesign cycles that favor manufacturers with in-house R&D facilities. Certification momentum pulls replacement demand forward in North American households.
- Photocatalytic oxidation convergence:Hybrid systems combining titanium dioxide coatings with UV-LED arrays capture chemically sensitive homeowners seeking formaldehyde and benzene reduction beyond HEPA particulate capture.
- Urban household formation in China:Middle-class expansion in tier-2 and tier-3 cities drives first-time purchase cycles and compressed replacement intervals for filter consumables.
Market Restraints
- Electronics-grade HEPA membrane concentration:Premium glass microfiber supply clusters in Japan and Germany, exposing mid-tier brands to input cost volatility and extended lead times during capacity constraints.
- California Air Resources Board ozone limits:Electrochemical emission caps disqualify ionizer-dominant architectures from the largest US state market, forcing architecture abandonment or costly redesign.
- Activated carbon price sensitivity:Coconut shell and coal-based feedstock costs fluctuate with agricultural yields and energy markets, compressing gross margins on VOC-focused premium units.
Strategic Opportunities
- India BIS certification pathway:Mandatory quality standards for electronic goods create first-mover advantage for brands establishing local testing partnerships and distribution infrastructure before enforcement hardens.
- Direct-to-consumer filter subscription:Consumables replenishment via app-integrated IoT sensors locks in lifetime value and displaces third-party aftermarket suppliers in premium residential segments.
- EU Ecodesign directive expansion:Repairability and recyclability mandates favor modular filter architectures that enable component-level replacement rather than full unit discard.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous EPA, CARB, and EU Ecodesign validation stretches product launch windows and strains regulatory affairs staffing at mid-cap manufacturers.
- Sensor calibration drift:Laser particle counters and TVOC detectors require field recalibration protocols that inflate warranty costs and erode brand trust when accuracy degrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Use Air Purifiers Market |
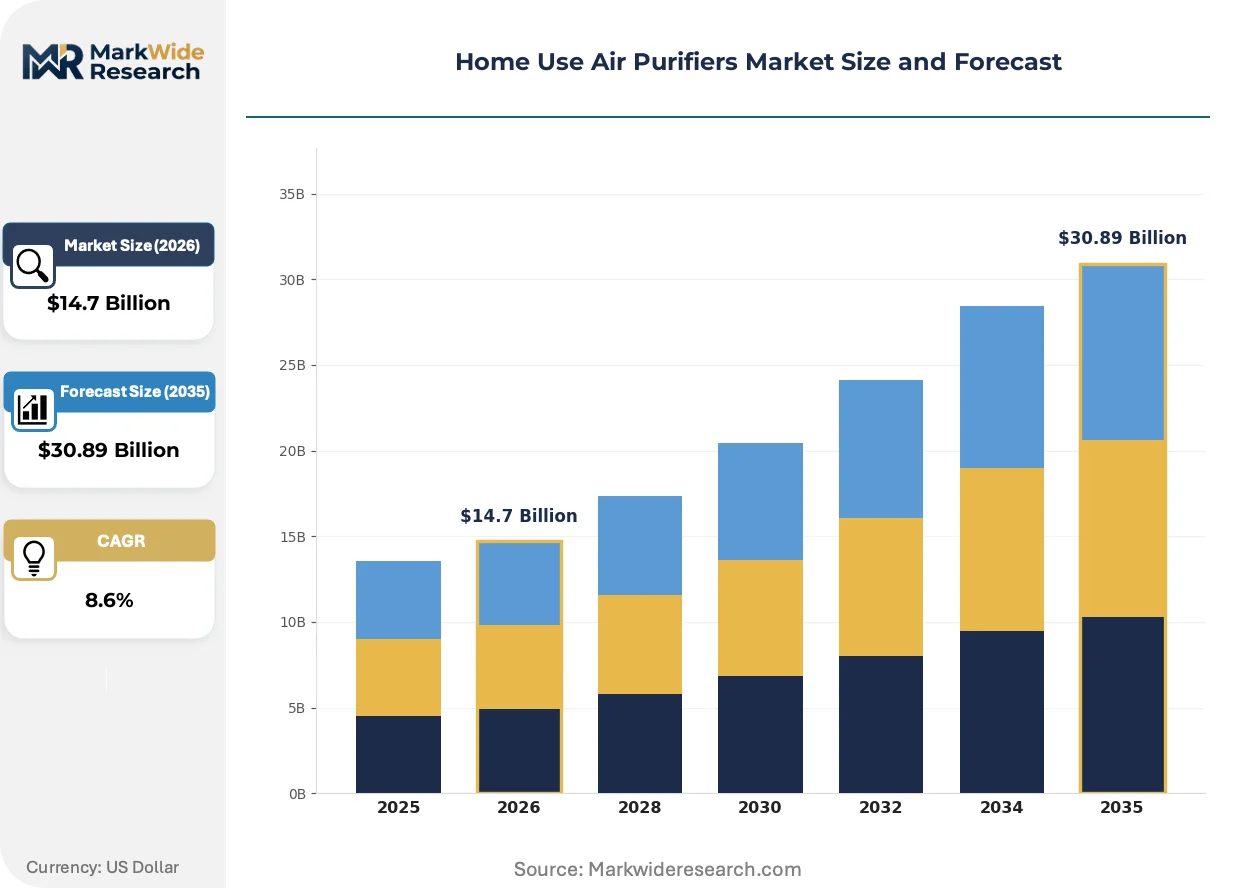
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $30.89 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA, Activated Carbon, Ionizers, UV-C Application: Residential, Office, Industrial, Healthcare Technology: Filtration, Photocatalytic, Electrostatic, Hybrid End User: Homeowners, Renters, Property Managers, Organizations |
| Companies Covered | Daikin Industries Ltd., Honeywell International Inc., Panasonic Corporation, Sharp Corporation, LG Electronics Inc., Koninklijke Philips N.V., Samsung Electronics Co. Ltd., Dyson, Blueair, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Use Air Purifiers Market Trends and Innovations
Electrochemical and photocatalytic purification architectures are fragmenting the long-dominant HEPA-centric product landscape, creating parallel premium tiers while compressing legacy assembly margins.
UV-C LED sterilization modules are fragmenting the upper residential segment as homeowners with immunocompromised family members or newborn infants adopt hybrid filtration-irradiation systems. Medical-grade 265-280 nanometer arrays, previously confined to clinical settings, now integrate into countertop and console units priced above standard HEPA alternatives. This convergence is fragmenting the premium tier into sterilization-focused and filtration-purists subcategories with divergent marketing claims and certification requirements.
REACH restrictions on perfluorinated compounds in nonwoven media are forcing European manufacturers to reformulate hydrophobic filter coatings and validate alternative oleophobic treatments. The industrial consequence is extended qualification timelines for new membrane suppliers and accelerated obsolescence of legacy product lines. Germany and France, with the strictest national implementations, are seeing the fastest brand turnover as non-compliant imports face customs detention.
Certification-driven preference shifts are shortening replacement cycles among affluent homeowners who treat ENERGY STAR and AHAM Verifide labels as minimum hygiene factors rather than differentiators. Retail buyers in coastal US cities and Shanghai now demand third-party validated CADR claims and filter transparency documentation before purchase consideration. This behavior concentrates volume with brands maintaining dedicated testing facilities and published filter specification sheets, marginalizing generic competitors.
Home Use Air Purifiers Market Segmentation
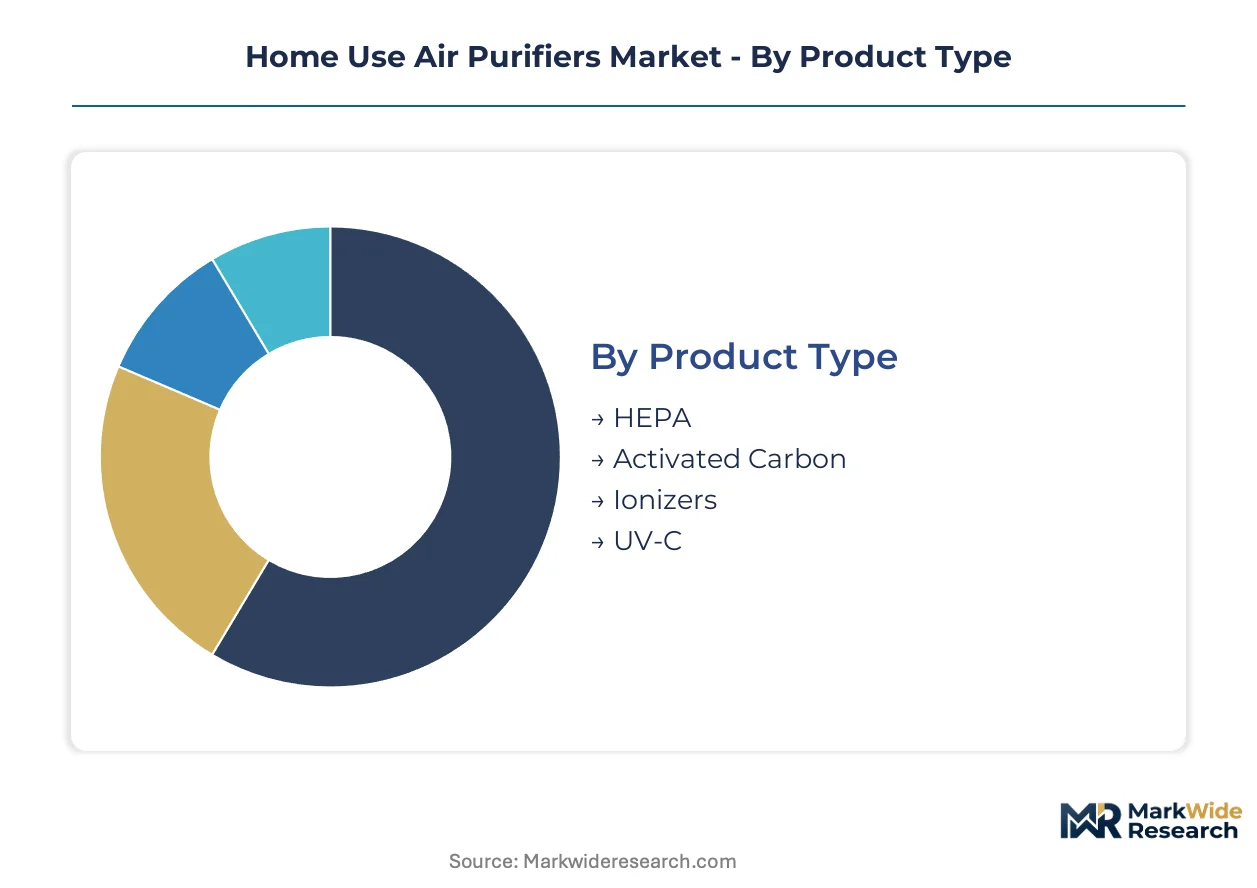
Home use air purifiers fragment across four intersecting dimensions that reshape procurement patterns and margin structures. Product type and technology choices determine certification pathways and filter replacement economics, while end-user categories dictate channel strategy and pricing tolerance.
Product Type:
HEPA and activated carbon systems dominate domestic manufacturing footprints, while ionizer architectures face export restrictions in key Western markets.
- HEPA:Glass microfiber membranes rated at 99.97% efficiency for 0.3-micron particles anchor clinical validation and ENERGY STAR eligibility. Demand concentrates in US coastal metros and Shanghai households where EPA guidelines and local pollution alerts drive premium positioning.
- Activated Carbon:Coconut shell and coal-based adsorbent beds target volatile organic compound removal beyond particulate capture. Procurement clusters in Southeast Asian feedstock markets expose manufacturers to agricultural yield volatility and margin compression.
- Ionizers:Electrochemical precipitation architectures face California Air Resources Board disqualification, limiting viable markets to Asia-Pacific and Middle East jurisdictions with looser ozone emission frameworks.
- UV-C:Mercury-vapor and LED sterilization arrays integrate into hybrid systems for immunocompromised households, commanding price premiums in direct-to-consumer medical-grade positioning.
HEPA holds the largest share; momentum sits with UV-C as sterilization claims penetrate residential segments.
Application:
Cost tier stratification separates high-velocity residential replacement cycles from capital-intensive industrial deployments.
- Residential:Single-family and multi-unit dwelling installations generate recurring filter consumable revenue through 6-12 month replacement intervals. China's tier-2 and tier-3 cities drive volume expansion as middle-class household formation accelerates first-time purchase penetration.
- Office:Commercial building retrofits and new construction specifications prioritize CADR-per-watt efficiency metrics and centralized building management system integration.
- Industrial:Heavy particulate environments require pre-filter stages and extended surface area configurations that extend replacement cycles but demand higher upfront capital commitment.
- Healthcare:Hospital-grade HEPA and UV-C hybrid systems face FDA 510(k) clearance pathways and infection control committee procurement protocols that elongate sales cycles.
Residential commands absolute volume; healthcare delivers the steepest expansion trajectory as sterilization convergence accelerates.
Technology:
Supply concentration in East Asian filter media production favors filtration-dominant architectures over electrochemical alternatives.
- Filtration:Mechanical particle capture through fibrous nonwoven media remains the cost-optimized baseline for mass-market penetration and regulatory compliance across multiple jurisdictions.
- Photocatalytic:Titanium dioxide coatings activated by UV-LED arrays oxidize formaldehyde and benzene at room temperature, appealing to chemically sensitive homeowners in high-VOC new construction markets.
- Electrostatic:Ionization-based precipitation without filter media replacement faces structural decline as CARB and EU Ecodesign restrictions tighten ozone emission thresholds.
- Hybrid:Stacked architectures combining HEPA, activated carbon, and UV-C stages capture premium positioning through multi-contaminant validation claims and higher filter bundle pricing.
Filtration retains installed base dominance; hybrid configurations gain share fastest as homeowners consolidate purification functions into single units.
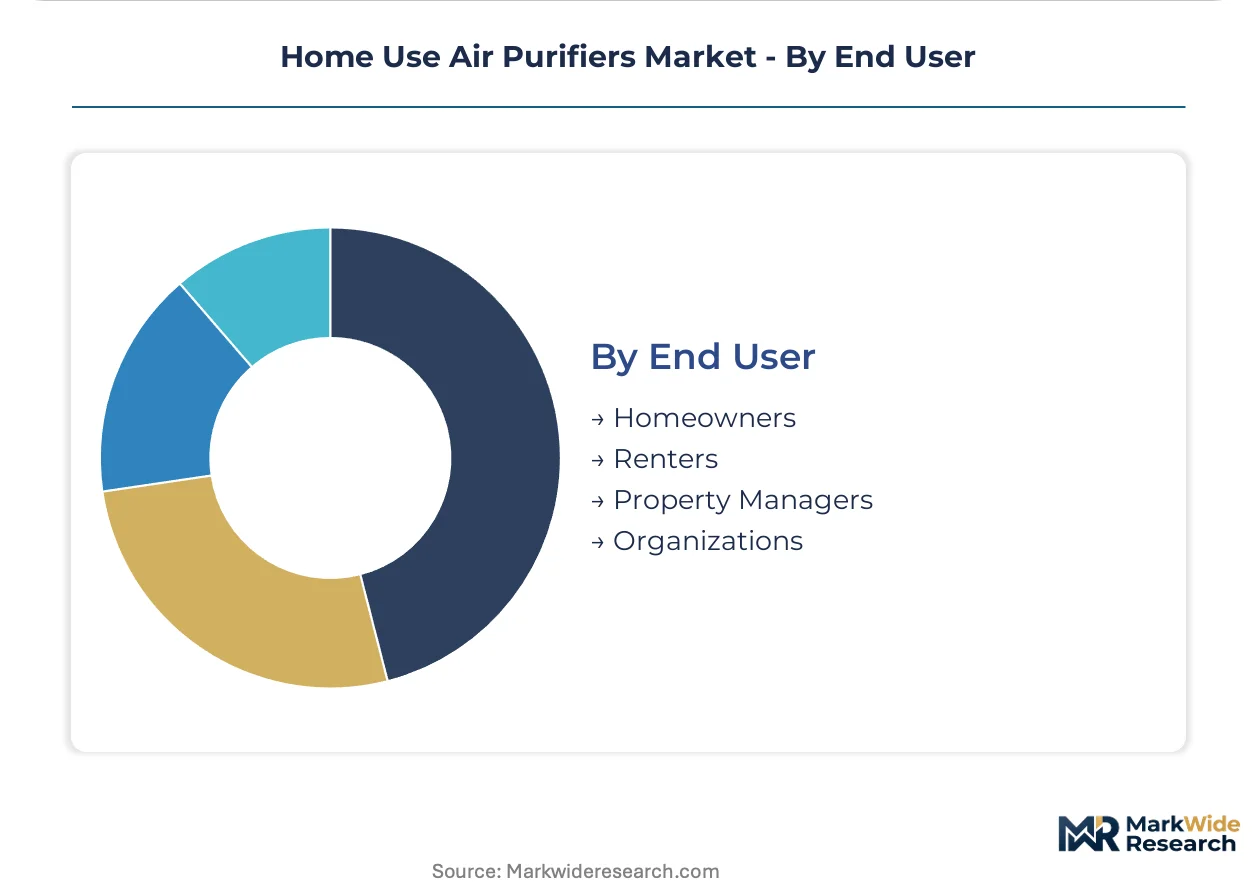
End User:
Customer type determines channel mix and subscription attach rates for consumable replenishment services.
- Homeowners:Permanent residents exhibit highest lifetime value through brand loyalty and IoT-enabled filter subscription adoption, particularly in US and Chinese metropolitan markets.
- Renters:Transient occupancy drives portable unit preference and lower price point tolerance, with purchase decisions influenced by landlord-provided HVAC quality and lease duration expectations.
- Property Managers:Multi-unit residential and commercial portfolio operators prioritize bulk procurement terms, standardized maintenance protocols, and warranty aggregation across installed bases.
- Organizations:Corporate facilities and institutional buyers mandate third-party performance validation, sustainability reporting compatibility, and multi-year service contracts with predictive maintenance integration.
Homeowners generate the highest per-unit profitability; property managers represent the fastest-climbing volume segment as rental housing stock professionalizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Chinese buyers prioritize performance-per-yuan in tier-2 cities, while German and US coastal consumers absorb 40-60% price premiums for certified efficiency. This divergence reshapes regional go-to-market strategies and filter replacement economics.
United States
Coastal metropolitan households drive premium positioning through EPA ENERGY STAR and AHAM Verifide certification demands. California Air Resources Board ozone emission limits disqualify ionizer-dominant architectures from the largest state market. Austin and Seattle clusters concentrate direct-to-consumer brands targeting allergy-sensitive homeowners with IoT-enabled subscription models.
China
Urban household formation in tier-2 and tier-3 cities compresses first-time purchase cycles and accelerates filter replacement intervals. GB standards and MEE indoor air quality guidelines tighten product entry requirements. The Yangtze River Delta manufacturing corridor dominates HEPA membrane and activated carbon feedstock production, rewarding backward-integrated domestic brands.
Germany
REACH restrictions on perfluorinated compounds force reformulation of hydrophobic filter coatings and extended supplier qualification timelines. EU Ecodesign repairability mandates favor modular architectures enabling component-level replacement. Bavaria and Baden-Württemberg host the densest concentration of HVAC-integrated system manufacturers serving residential retrofit markets.
India
BIS mandatory quality standards for electronic goods create certification bottlenecks for unvalidated imports while rewarding early local testing partnerships. Delhi-NCR and Mumbai pollution alerts drive seasonal demand spikes for HEPA-based units. Gujarat and Karnataka industrial corridors attract assembly operations seeking proximity to Southeast Asian activated carbon feedstock markets.
Japan
Electronics-grade glass microfiber supply concentration supports premium HEPA membrane production for domestic and export markets. METI energy efficiency guidelines and JIS standards maintain high technical barriers to entry. Osaka-Kobe and Nagoya manufacturing clusters specialize in compact, high-CADR units optimized for space-constrained urban apartments.
Home Use Air Purifiers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Integrated manufacturers with captive filtration component production control input costs and certification timelines, while assembly-focused brands compete on channel access and marketing efficiency. Three archetypes dominate: HVAC-integrated system suppliers, direct-to-consumer premium specialists, and mass-market electronics conglomerates. Capacity expansion in East Asian filter media and strategic partnerships for IoT platform integration represent the dominant competitive moves reshaping market boundaries.
Among diversified electronics conglomerates, Panasonic Corporation, Sharp Corporation, and Samsung Electronics Co. Ltd. exemplify scale-driven positioning that spans multiple appliance categories. These Osaka and Seoul-based Co., Ltd. structures leverage existing distribution infrastructure and brand recognition to capture volume in replacement-driven markets. Their presence anchors the mid-tier segment where certification breadth and procurement scale determine competitive viability.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Honeywell International Inc. |
| Panasonic Corporation |
| Sharp Corporation |
| LG Electronics Inc. |
| Koninklijke Philips N.V. |
| Samsung Electronics Co. Ltd. |
| Dyson |
| Blueair |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements for electronics-grade HEPA membranes lock in supply access and price visibility for backward-integrated manufacturers serving EPA ENERGY STAR and CARB-compliant product lines. These contractual structures insulate captive producers from coconut shell activated carbon volatility while exposing assembly-focused brands to spot-market margin compression.
Pricing Analysis
Filter subscription revenue tiers drive lifetime value differentiation across the installed base. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and IoT sensor integration. Cost compression in mid-tier HEPA units is intensifying because East Asian filter media supply concentration rewards scale procurement. Property managers exhibit highest price sensitivity due to bulk procurement mandates, while immunocompromised homeowners absorb premiums for UV-C sterilization validation.
Supply Chain Analysis
China and Japan anchor global HEPA membrane and activated carbon feedstock production for residential purification systems. Manufacturing draws from coconut shell agricultural yields in Southeast Asia, coal-based carbon feedstocks, and glass microfiber precursor chemicals. Single-source vulnerability concentrates in Japanese electronics-grade membrane suppliers during capacity constraints. Distribution runs through HVAC channel partnerships in North America and direct-to-consumer platforms in Chinese tier-2 cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as sterilization convergence and REACH-driven coating reformulation create technology niches. Chemically sensitive homeowner demand for VOC reduction beyond particulate capture splinters the premium tier.
For Market Incumbents: Shield installed base loyalty through IoT-enabled filter subscription lock-in and predictive replenishment algorithms. Defensive consolidation moves center on acquiring captive activated carbon production to offset agricultural yield volatility. Priority lever rests on CARB and EPA certification maintenance as regulatory barriers harden against ionizer architectures. For New Entrants and Emerging Players: Anchor in India's BIS certification pathway before enforcement hardens and local testing partnerships become scarce. White-space targets include Delhi-NCR seasonal demand spikes and tier-3 Chinese city first-time purchase cycles. Direct-to-consumer medical-grade positioning with UV-C sterilization claims offers penetrable premium positioning against established filtration-purist incumbents. For Investors and Strategic Acquirers: Modular filter architecture specialists with EU Ecodesign repairability compliance represent acquisition targets with defensible positioning. Long-term viability over the coming decade hinges on regulatory anticipation capacity and multi-jurisdiction certification bandwidth. Signal to watch involves CARB ozone limit tightening timelines and Asian particulate standard harmonization announcements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Filter Media | Captive HEPA membrane production insulates Daikin and Honeywell from Japanese supply concentration risks. |
| IoT Platform Integration | App-connected particle sensors enable Dyson's subscription filter replenishment and displace aftermarket suppliers. |
| Multi-Jurisdiction Certification Investment | Simultaneous EPA, CARB, and EU Ecodesign validation stretches product launch windows but locks out mid-cap competitors. |
| Photocatalytic Technology Licensing | Titanium dioxide coating patents capture chemically sensitive homeowners seeking formaldehyde reduction beyond HEPA capture. |
| Direct-to-Consumer Channel Expansion | Austin and Seattle clusters concentrate allergy-sensitive homeowner acquisition through bypass of retail markup structures. |
Research Methodology
The analysis maps HEPA filtration, activated carbon adsorption, UV-C sterilization, and photocatalytic oxidation sub-sectors, each validated through product managers at integrated manufacturers, regulatory affairs specialists, HVAC channel partners, and procurement leads at property management firms. Primary interview intelligence triangulates against EPA ENERGY STAR certification databases, CARB ozone emission compliance listings, EU Ecodesign repairability documentation, and AHAM Verifide CADR test reports. Bottom-up unit shipment modeling and top-down value reconciliation ensure cross-validation consistency.
Consistency-check validation against external benchmarks confirms projection alignment across the analysis window. Segmentation dimensions include product type, application, technology architecture, and end-user category with regional regulatory cluster overlays. CAGRs derive from replacement cycle velocity, household formation rates, and certification-driven preference shift elasticity. Industry-specific inputs incorporate filter media supply lead times and seasonal pollution alert frequency patterns.
Decision-makers should treat outputs as directional under stable regulatory enforcement and supply concentration assumptions; material deviation would warrant model refresh. Specific risk factors include REACH coating reformulation delays, BIS certification timeline extensions, and activated carbon agricultural yield shocks. Recalibration cycles align with material shifts in multi-jurisdiction standard harmonization and East Asian manufacturing capacity announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Electric Soap Dispenser Market
Household Items
Desktop Air Purifier Market
Household Items
Luxury Massage Chair Market
Household Items
Canada Digital Showers Market
Household Items
LAMEA Robotic Pool Cleaner Market
Household Items
Europe Electric Cordless Lawn and Garden Tools Market
Household Items
Portable Iron Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Portable Steam Cleaners Market
Household Items
Sanitary Metal Ware Market
Household Items
Toilet Care Wipes Market
Household Items
Toilet Paper Market
Household Items
Commercial Lawnmower Market
Household Items
US Air Purifier Market
Household Items
Alarm Clocks Market
Household Items
Global Sports Bottle Market