
 Office Chairs Market | 2026-2036
Office Chairs Market Size, Share, and Industry Trends Forecast 2026-2036
Office Chairs Market Intelligence
Modular chair configurations with swappable seat pans, adjustable lumbar systems, and interchangeable armrest kits is hardening as the default purchasing architecture for enterprise buyers. Steelcase leverages its integrated research and manufacturing footprint to control specification-setting conversations with Fortune 500 procurement teams. Herman Miller anchors its premium positioning through sustained investment in biomechanical research and designer licensing partnerships. Haworth competes aggressively in the co-working and startup segment with rapid-configure product lines that minimize installation lead times.
An office chair is a seating apparatus engineered for sustained use at workstations, typically incorporating pneumatic height adjustment, tilt mechanisms, and load-bearing frames rated for eight-plus hours of daily operation. Mesh-back construction with elastomeric suspension layers dominates contemporary technical specifications due to thermal regulation advantages over fully upholstered alternatives. Ergonistic chairs command the fastest expansion trajectory as occupational health guidelines tighten across jurisdictions, while task chairs retain the largest volume footprint due to universal deployment in open-plan environments. Leather-upholstered executive chairs occupy a mature margin pool sustained by C-suite replacement cycles rather than net-new demand.
OSHA workplace ergonomics guidelines in the United States, EU machinery directives through CE marking requirements, and BIS furniture safety standards in India collectively shape product certification burdens and market access conditions. Compliance with these frameworks determines eligibility for government and institutional procurement channels, effectively filtering out uncertified manufacturers. Stakeholders must monitor evolving material disclosure rules around flame retardants and recycled content mandates as these specifications increasingly appear in formal tender documents.
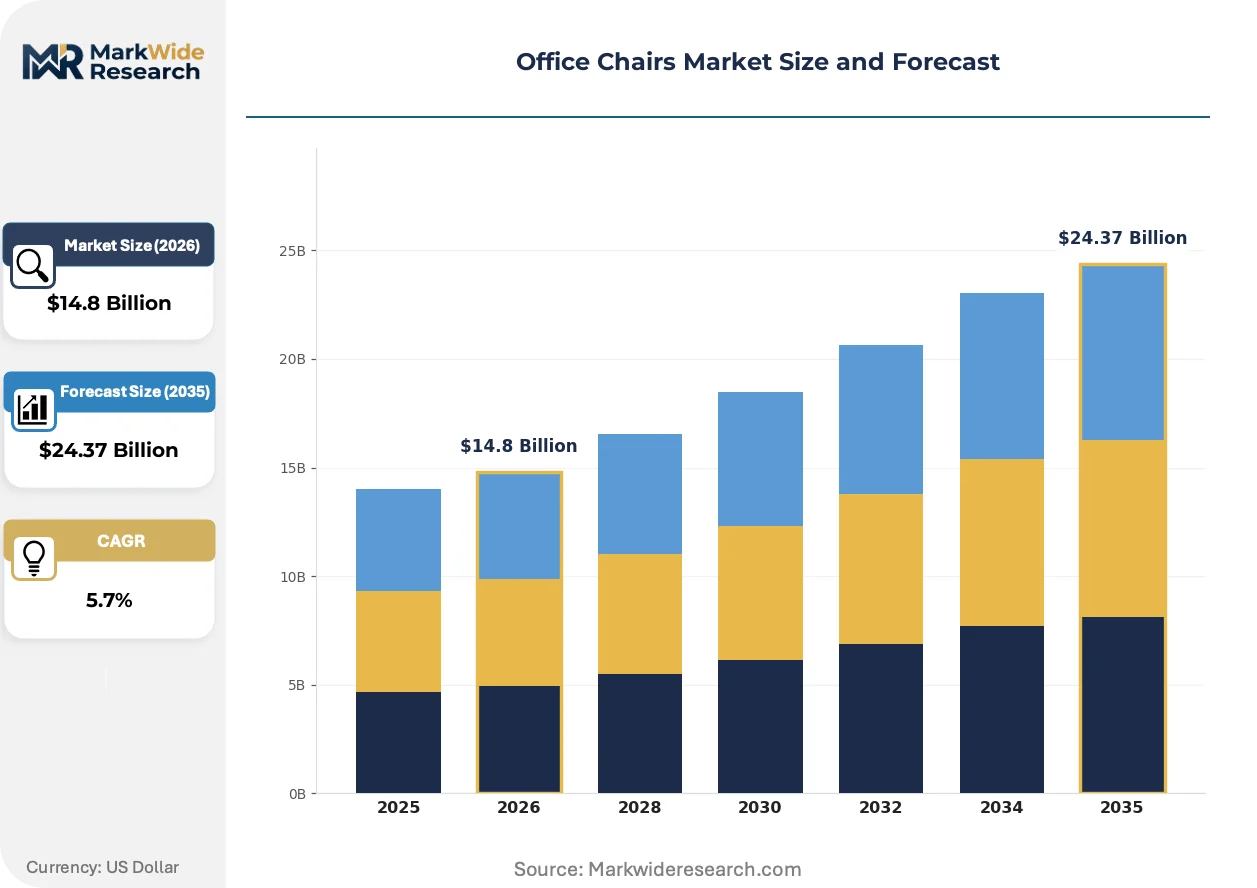
Market Dynamics
Hybrid work permanence is restructuring enterprise procurement from bulk standardized orders to distributed, specification-heavy purchasing coordinated across home and corporate locations.
Growth Catalysts
- OSHA Ergonomics Guidelines:Mandatory workplace assessments in the United States are forcing employers to replace non-compliant seating, creating replacement pull across Fortune 500 facilities and mid-market offices alike.
- Elastomeric Mesh Suspension:Thermal regulation advantages over foam upholstery are driving specification switches in warm-climate markets and high-density call centers where eight-hour heat retention degrades productivity.
- India:BIS furniture safety standards are filtering uncertified imports from Southeast Asian suppliers, creating procurement volume concentration among domestic and approved international manufacturers.
Market Restraints
- Steel and Aluminum Input Volatility:Base metal price swings compress margin predictability for frame manufacturers locked into annual enterprise contracts with fixed pricing clauses.
- Guangdong Component Concentration:Pneumatic cylinder and caster wheel production clusters in southern China create single-source vulnerability for brands without dual-qualified secondary suppliers.
- REACH Chemical Disclosure:European upholstery flame retardant documentation requirements add six-to-eight week certification delays that disqualify manufacturers from fast-turn government tenders.
Strategic Opportunities
- Brazil:Underpenetrated ergonomic seating in São Paulo and Rio de Janeiro corporate towers offers first-mover positioning as ANVISA workplace health guidelines tighten enforcement.
- Leasing-as-a-Service:Subscription models bundling chairs with maintenance and refresh cycles are capturing co-working operators seeking to convert capex to opex and reduce asset management overhead.
- Sensor-Embedded Seating:Convergence of pressure-mapping textiles with Bluetooth connectivity enables posture analytics services sold to self-insured employers seeking workers compensation reduction.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:Shortage of occupational health researchers capable of translating clinical data into commercial product specifications limits R&D velocity for mid-tier manufacturers.
- Multi-Jurisdiction Certification Parallel Processing:Simultaneous pursuit of CE marking, BIS registration, and OSHA-aligned testing stretches quality assurance teams and extends time-to-revenue for new product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Chairs Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Executive Chairs, Task Chairs, Ergonomic Chairs, Conference Chairs Material: Leather, Mesh, Fabric, Plastic End User: Corporations, Home Offices, Educational Institutions, Co-working Spaces Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Knoll, Okamura, Steelcase, Nowy Styl, Kokuyo, Herman Miller, HNI Corporation, Global Furniture Group, Haworth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Chairs Market Strategic Shifts & Innovations
Material science breakthroughs and procurement digitization are compressing product lifecycles while elevating baseline performance expectations across price tiers.
Elastomeric suspension layers with variable tension zones are rewriting thermal comfort benchmarks for sustained seated work. High-volume call center operators in Arizona and Texas are specifying mesh-back configurations exclusively, abandoning foam-upholstered alternatives that trap body heat beyond six-hour thresholds. This material shift is compressing the viable product architecture for mid-market task chairs toward breathable, non-upholstered constructions.
EU machinery directives through CE marking requirements are mandating load-testing documentation for pneumatic height cylinders that previously escaped formal certification. Manufacturers serving European institutional buyers must now submit third-party burst-test reports and cycle-fatigue data with every tender response. German and French healthcare procurement channels have responded by pre-qualifying only suppliers with in-house testing laboratories, filtering out trading companies and specification-only brands.
Enterprise buyers are consolidating vendor relationships from fragmented regional distributors to direct manufacturer partnerships with national installation and service capabilities. Facility management teams at U.S. technology campuses are replacing three-tier supplier networks with single-source contracts covering specification, white-glove delivery, and refresh cycling. This concentration is most visible in Seattle and Austin, where corporate real estate teams manage distributed home-office stipend programs alongside central campus seating refreshes.
Office Chairs Market Segmentation
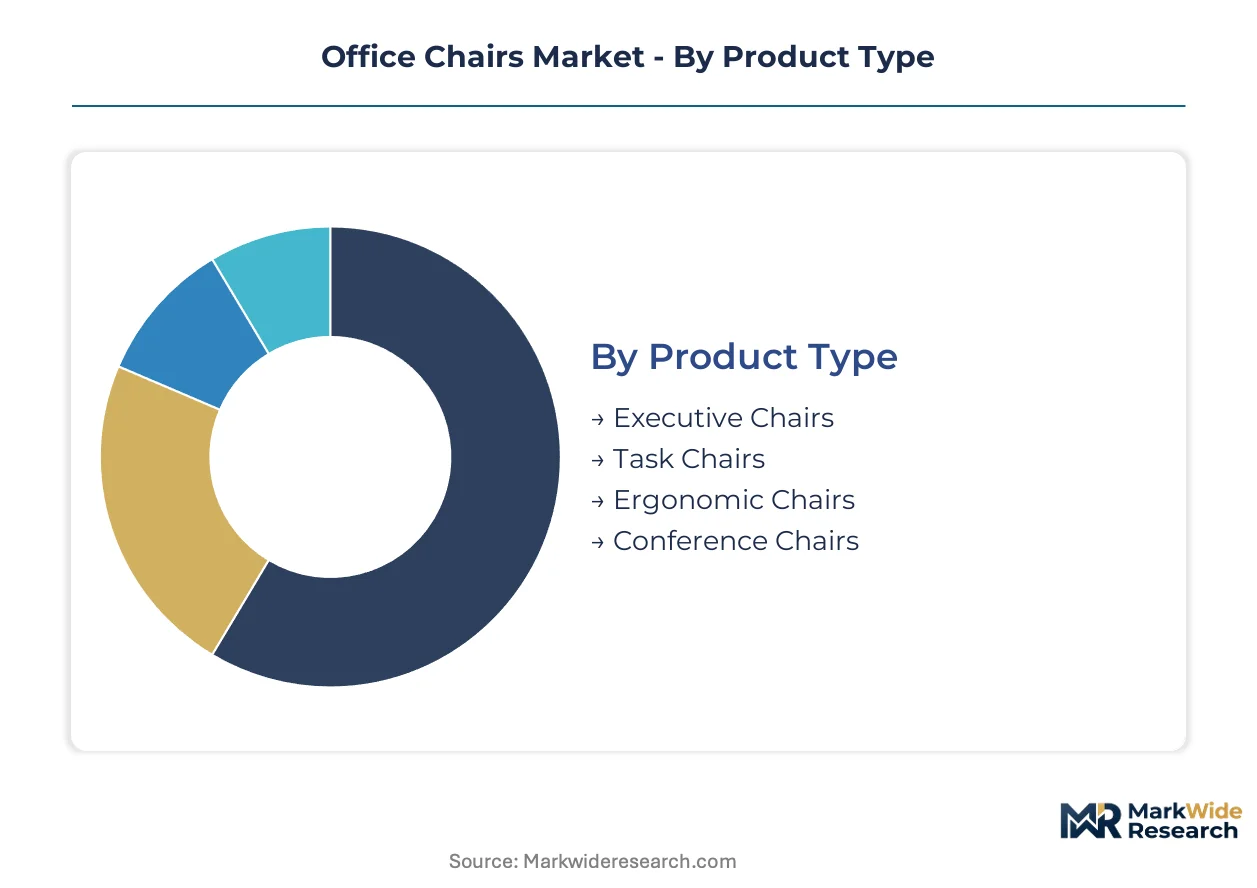
Office chair procurement patterns diverge sharply across use cases, with certification requirements and thermal performance specifications filtering vendor eligibility. Enterprise buyers segment purchases by workstation intensity, while residential buyers prioritize configurability over compliance documentation.
Product Type:
OSHA workplace ergonomics guidelines in the United States mandate lumbar support and adjustability documentation for task-intensive seating, while CE marking requirements in Europe impose load-testing standards on pneumatic mechanisms across all commercial categories.
- Task Chairs:Open-plan workstations deploy these universally. Eight-hour duty ratings and pneumatic height adjustment are baseline specifications. Demand concentrates in United States technology campuses and Indian IT parks where OSHA-aligned assessments and BIS furniture safety standards respectively filter procurement pools.
- Ergonomic Chairs:Biomechanical engineering differentiates this tier through adjustable lumbar systems and armrest kits. United States healthcare and insurance sectors drive specification intensity as workers compensation reduction programs mandate posture-supporting seating for claims-sensitive roles.
- Executive Chairs:Leather-upholstered configurations dominate C-suite replacement cycles rather than net-new demand.
- Conference Chairs:Visitor-duration ratings and aesthetic coordination with boardroom fixtures define this segment.
Leading the category by volume: Task Chairs. Growing fastest: Ergonomic Chairs.
Material:
Cost tiers separate breathable performance constructions from traditional upholstery, with thermal regulation properties commanding specification premiums in climate-stressed deployments.
- Mesh:Elastomeric suspension layers with variable tension zones dominate high-density call centers in Arizona and Texas. Thermal regulation advantages over foam drive exclusive specification where eight-hour heat retention degrades productivity.
- Leather:Premium positioning persists in executive suites and formal meeting spaces. REACH chemical disclosure requirements in Europe add six-to-eight week certification delays for flame retardant documentation.
- Fabric:Mid-market task seating relies on woven upholstery for cost-controlled bulk procurement.
- Plastic:Injection-molded shells serve visitor chairs and educational institutions with limited duty-cycle requirements.
Widest deployment: Mesh in warm-climate commercial zones. Steepest specification climb: Elastomeric suspension variants.
End User:
Customer type determines procurement coordination complexity, from centralized facilities management to distributed individual purchasing with stipend oversight.
- Corporations:Fortune 500 facilities teams consolidate vendor relationships toward direct manufacturer partnerships with national installation capabilities. Seattle and Austin campuses manage hybrid programs coordinating central refreshes with home-office stipends.
- Home Offices:Individual buyers prioritize modular configurability and rapid delivery over compliance documentation. United States residential workspace conversion sustains replacement cycles independent of corporate procurement calendars.
- Educational Institutions:Budget-constrained volume purchasing favors plastic and fabric constructions with institutional durability ratings.
- Co-working Spaces:Rapid-configure product lines with minimal installation lead times capture this segment. Leasing-as-a-Service subscription models convert capex to opex for operators reducing asset management overhead.
Dominant procurement volume: Corporations. Expanding most quickly: Home Offices.
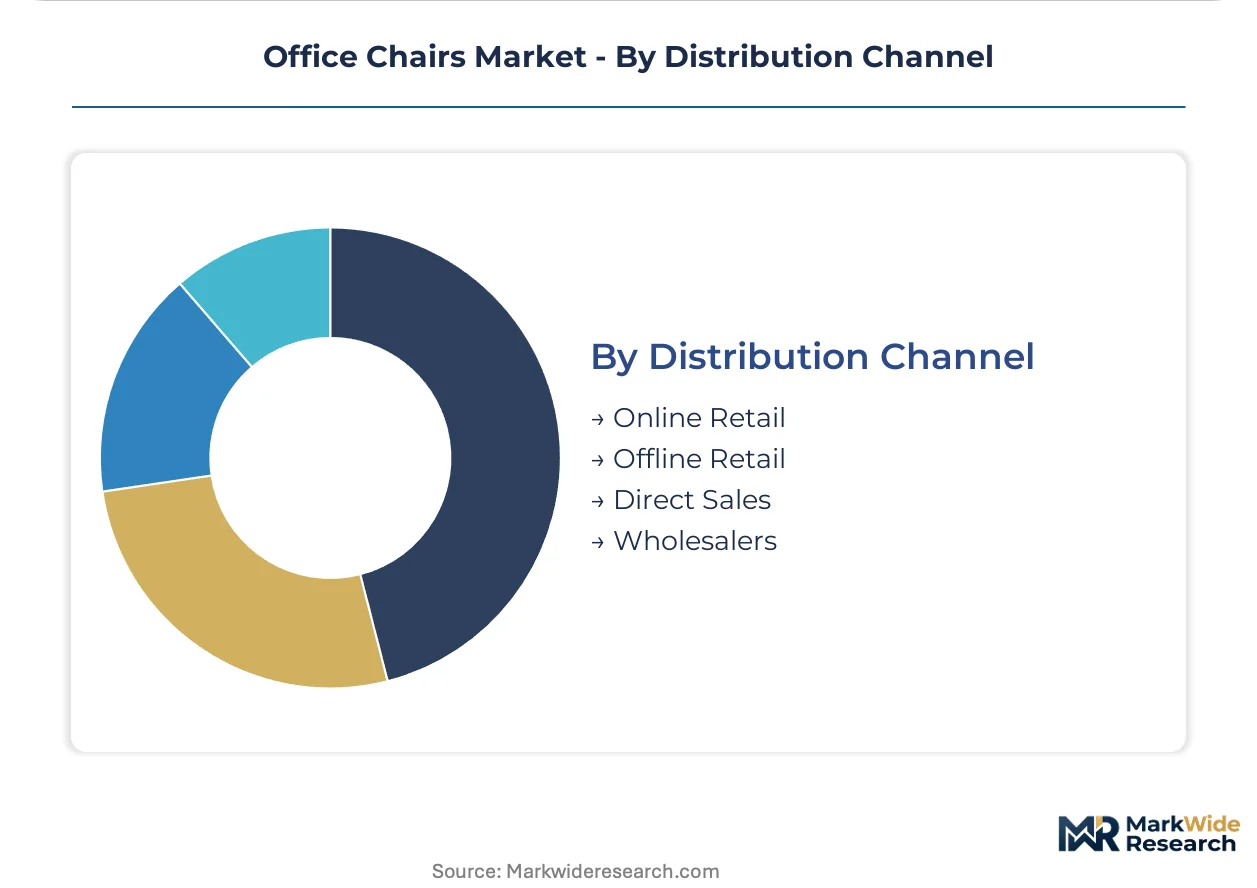
Distribution Channel:
Supply concentration in Guangdong pneumatic cylinder clusters shapes fulfillment reliability across channel types, with dual-qualified secondary suppliers differentiating resilient vendors.
- Direct Sales:Enterprise buyers in Germany and France pre-qualify only suppliers with in-house testing laboratories, filtering out trading companies. National installation and service capabilities secure single-source contracts.
- Online Retail:Home office buyers in the United States drive specification-heavy purchasing through digital configurators with white-glove delivery options.
- Offline Retail:Showroom-based selection persists for executive and conference seating where tactile evaluation influences specification.
- Wholesalers:Regional distributors serve mid-market offices with fragmented procurement patterns, though enterprise consolidation pressures this channel.
Channel commanding margin premiums: Direct Sales. Gaining share fastest: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Chinese component clusters while consumption disperses across North American and European corporate headquarters. The United States absorbs the largest procurement volumes through hybrid work infrastructure spending. India and Brazil emerge as regulatory-driven replacement markets as workplace safety enforcement tightens.
United States
Fortune 500 facilities teams in Seattle and Austin coordinate distributed home-office stipends with central campus refreshes. OSHA workplace ergonomics guidelines mandate lumbar support documentation for task-intensive seating, filtering procurement pools toward certified suppliers. Commercial real estate turnover in Sun Belt metros sustains replacement cycles independent of net-new construction.
Germany
Healthcare and automotive corporate campuses drive specification intensity for eight-hour duty-rated seating. EU machinery directives through CE marking requirements mandate third-party burst-test reports for pneumatic cylinders, pre-qualifying only manufacturers with in-house testing laboratories. The Rhine-Ruhr industrial corridor concentrates facility management procurement for integrated European operations.
China
Guangdong Province hosts pneumatic cylinder and caster wheel production clusters supplying global assembly networks. GB standards and MIIT industrial policy shape domestic product specifications while export-oriented manufacturers dual-qualify for CE marking and BIS registration. Shenzhen and Dongguan anchor component sourcing for brands seeking supply chain redundancy.
India
Bangalore and Hyderabad IT parks deploy high-volume task chair procurement under BIS furniture safety standards that filter uncertified Southeast Asian imports. CDSCO-aligned workplace health assessments in pharmaceutical and technology sectors elevate ergonomic specifications above baseline commercial offerings. Domestic manufacturers capture institutional volume previously served by trading companies.
Brazil
São Paulo and Rio de Janeiro corporate towers present first-mover positioning as ANVISA workplace health guidelines tighten enforcement. Underpenetrated ergonomic seating relative to North American benchmarks creates specification upgrade potential among financial services and legal sector employers. Local assembly operations avoid import duty burdens that compress margins on fully finished goods.
Office Chairs Market Key Industry Players
The competitive structure tilts toward integrated research-to-manufacturing specialists capable of controlling specification-setting conversations with enterprise procurement teams. Three archetypes dominate: biomechanical research-led premium brands, rapid-configure specialists serving co-working operators, and scale-driven manufacturers optimizing for institutional volume procurement. Consolidation pressures fragment regional distributors as facility management teams pursue single-source national contracts. Strategic moves center on direct manufacturer partnerships with installation capabilities and sensor-embedded seating development for posture analytics services.
Among research-integrated manufacturers, Steelcase, Herman Miller, and Haworth exemplify distinct positioning vectors within the premium tier. Steelcase anchors specification-setting influence through Fortune 500 direct relationships. Herman Miller occupies designer-licensing and biomechanical research positioning. Haworth sits within the rapid-configure segment targeting co-working and startup procurement with minimized installation lead times. These three represent the dominant competitive anchors against which mid-tier manufacturers and trading companies benchmark capability claims.
| Leading Market Players |
|---|
| Knoll |
| Okamura |
| Steelcase |
| Nowy Styl |
| Kokuyo |
| Herman Miller |
| HNI Corporation |
| Global Furniture Group |
| Haworth |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists across Italy and Poland anchor European upholstery sourcing, their conservative balance sheets limiting capacity expansion despite enterprise demand pull. This ownership structure concentrates pricing power with component manufacturers while constraining downstream brands' ability to negotiate volume discounts or secure preferential allocation during input crunches.
Pricing Analysis
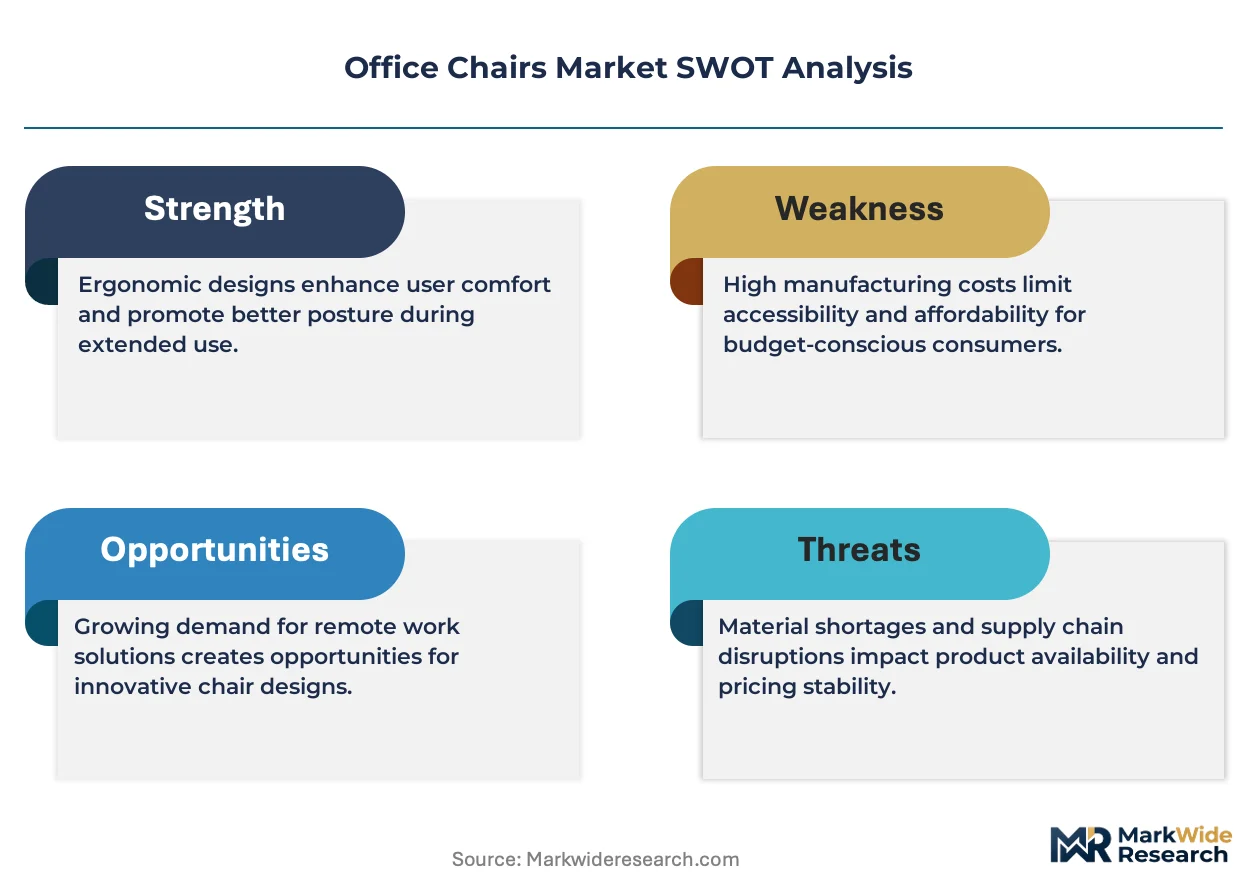
Margin tightening in mid-market task seating reflects steel and aluminum input volatility compressing predictability for frame manufacturers locked into annual enterprise contracts with fixed pricing clauses. Three-tier pricing structure across premium ergonomic, standard task, and economy visitor levels separates certification-grade seating with OSHA documentation from uncertified imports. Pricing pressure intensifies as REACH chemical disclosure requirements add six-to-eight week certification delays that disqualify manufacturers from fast-turn government tenders. Home office buyers exhibit highest price sensitivity, while Fortune 500 facilities teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Pneumatic cylinder supply rests on Guangdong Province production clusters feeding global assembly networks for height-adjustable mechanisms. Steel frame stamping and elastomeric mesh weaving concentrate in China, Taiwan, and Vietnam, with dual-qualified secondary suppliers differentiating resilient vendors from single-source-dependent brands. Single-source vulnerability in southern Chinese component clusters creates fulfillment risk for brands without backup qualification. Distribution runs through direct manufacturer partnerships with national installation capabilities for enterprise accounts, while online retail captures home office volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Guangdong component concentration props pricing by constraining qualified supply expansion faster than hybrid work demand growth. This bottleneck sustains margin pools for manufacturers with redundant sourcing.
For Market Incumbents: Hedge against pneumatic cylinder supply disruption by qualifying secondary suppliers in Taiwan and Vietnam before input crunches trigger allocation fights. Capture specification-setting influence through in-house testing laboratories that pre-qualify brands for German and French healthcare procurement channels. Defend against rapid-configure specialists by embedding sensor-embedded seating development for posture analytics services sold to self-insured employers. For New Entrants and Emerging Players: Launch via Leasing-as-a-Service subscription models bundling chairs with maintenance and refresh cycles to convert co-working operator capex to opex. Target São Paulo and Rio de Janeiro corporate towers where ANVISA workplace health guideline enforcement creates first-mover positioning in underpenetrated ergonomic seating. Enter through rapid-configure product lines with minimized installation lead times that incumbent manufacturers with legacy distribution cannot match. For Investors and Strategic Acquirers: BIS furniture safety standard tightening in India is the leading indicator that domestic manufacturers will consolidate institutional volume previously served by uncertified Southeast Asian trading companies. Five-to-ten year viability favors research-integrated specialists with biomechanical engineering capabilities rather than specification-only brands. Watch for ANVISA enforcement acceleration in Brazil as the signal that Latin American ergonomic upgrade cycles are commencing.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Source Supplier Qualification | Taiwan and Vietnam backup capacity insulates against Guangdong disruption for pneumatic cylinder-dependent brands. |
| In-House Testing Laboratory Investment | CE marking and BIS pre-qualification filters out trading companies from German, French, and Indian institutional tenders. |
| Sensor-Embedded Seating Development | Pressure-mapping textiles with Bluetooth connectivity enable posture analytics services sold to workers compensation-focused employers. |
| Leasing-as-a-Service Model Launch | Subscription bundling converts co-working operator capex to opex while capturing refresh cycle revenue. |
| Rapid-Configure Product Line Expansion | Minimized installation lead times capture startup and co-working procurement that legacy manufacturers cannot fulfill. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs combining with primary interviews across facility management directors, procurement leads at Fortune 500 campuses, biomechanical engineering specialists, co-working space operators, and pneumatic cylinder manufacturers. OSHA guideline documentation, BIS certification registries, EU machinery directive filings, and import-export customs databases supplied validation layers. Bottom-up shipment data triangulated against top-down enterprise furniture spending estimates.
Data-stream reconciliation across product type, material construction, end-user category, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs derived from segment-level volume trajectories weighted by replacement cycle intensity and regulatory enforcement timelines. Pneumatic cylinder burst-test certification rates and elastomeric mesh adoption curves in warm-climate call centers informed industry-specific forecast inputs.
Steel and aluminum commodity swings, REACH chemical disclosure timeline extensions, and ANVISA enforcement acceleration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about hybrid work permanence and regulatory harmonization trajectories. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Luxury Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Desk Chairs Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
India Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
Europe Office Furniture Market