
 Home Office Desk Market | 2026-2036
Home Office Desk Market Size, Share, and Industry Trends Forecast 2026-2036
Home Office Desk Market Insights
EU Ecodesign requirements and the EU Green Deal are consolidating demand around sustainably sourced home office furniture across Europe. Steelcase Inc. leverages certified supply chains to anchor its position in premium ergonomic seating and desk systems. Herman Miller sustains design leadership through its Living Office platform, while Haworth Inc. competes on modular architecture that adapts to shrinking residential footprints.
A home office desk is a purpose-built workstation, typically comprising a load-bearing surface between 0.7 and 1.5 meters in length, supported by legs or a pedestal frame, designed for computer-based tasks, document handling, and video conferencing in residential environments. Standing desk configurations dominate commercial procurement due to documented ergonomic benefits, while L-shaped desks occupy the largest share of consumer-direct revenue by maximizing corner space utilization. Composite materials represent the fastest-growing material segment as manufacturers balance cost efficiency against sustainability credentials.
EPA formaldehyde emission standards, California Air Resources Board (CARB) Phase 2 compliance, and EU REACH chemical restrictions collectively shape material selection and market access for wood-based desk components. FSC and PEFC chain-of-custody certification is becoming a baseline requirement for entry into corporate direct-purchase programs. Stakeholders must monitor evolving extended producer responsibility frameworks and building certification schemes that increasingly encompass home office furniture within their scope.
Market Dynamics
Hybrid work permanence has restructured residential workspace investment, converting temporary pandemic setups into permanent ergonomic infrastructure. This shift concentrates purchasing power among technology firms and freelance professionals who now treat home offices as primary productivity environments rather than secondary accommodations.
Growth Catalysts
- EU Green Deal procurement mandates:Corporate purchasing programs now require FSC chain-of-custody certification for furniture vendors, elevating sustainably sourced desks into competitive procurement rounds across Germany and France.
- Standing desk ergonomic documentation:Occupational health studies linking sit-stand configurations to reduced musculoskeletal claims are accelerating replacement cycles in remote-first technology firms.
- China's dual carbon goals:Domestic manufacturers are retooling composite material lines to capture low-emission credentials, expanding export capacity for eco-certified home office furniture.
Market Restraints
- Formaldehyde compliance costs:EPA emission standards and CARB Phase 2 requirements force particleboard suppliers into costly resin reformulation, compressing margins for mid-tier producers.
- Southeast Asian supply concentration:Malaysian and Vietnamese hardwood component sourcing creates vulnerability to shipping rate volatility and port congestion.
- Modular system incompatibility:Proprietary connector designs across major manufacturers prevent component interchangeability, locking buyers into single-vendor ecosystems.
Strategic Opportunities
- India's PLI scheme for furniture:Production-linked incentives are attracting contract manufacturers to establish domestic assembly for export-oriented ergonomic desk production.
- Extended producer responsibility frameworks:EU member states are drafting take-back mandates for home office furniture, creating first-mover advantage for circular-design specialists.
- Smart sensor integration:Convergence of occupancy detection with height-adjustment motors enables posture coaching subscriptions, opening recurring revenue streams.
Industry Challenges
- REACH chemical disclosure timelines:ECHA substance database updates require continuous reformulation tracking, straining smaller manufacturers' regulatory compliance functions.
- Ergonomic certification backlog:BIFMA testing facility capacity constraints are extending product launch timelines by four to six months for standing desk mechanisms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Office Desk Market |
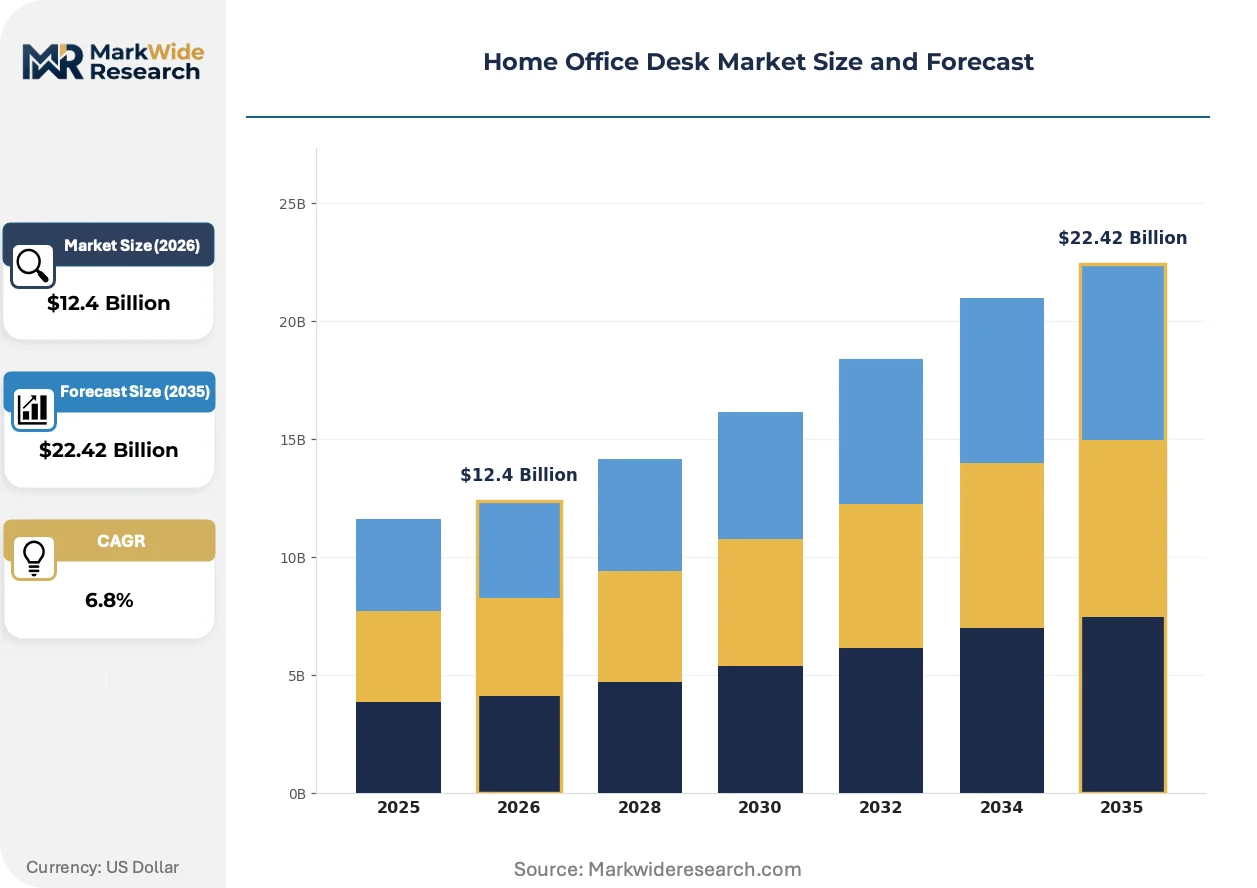
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standing Desk, L-Shaped Desk, Writing Desk, Corner Desk Material: Wood, Metal, Glass, Composite Size: Small, Medium, Large, Adjustable Functionality: Height Adjustable, Fixed Height, Convertible, Foldable |
| Companies Covered | Steelcase Inc., Herman Miller, Haworth Inc., HNI Corporation, IKEA, Ashley Furniture Industries, La-Z-Boy Incorporated, Wayfair Inc., UPLIFT Desk, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Office Desk Market Trends and Innovations
Material science advances and embedded connectivity are redefining desk functionality beyond passive surfaces. Manufacturers now compete on adaptive ergonomics and environmental credentials rather than dimensional specifications alone.
Biophilic surface treatments incorporating mycelium-based composites are converging with traditional wood veneer aesthetics. Premium residential buyers and boutique coworking operators are specifying these materials at 15-20% price premiums. This convergence is compressing the market position of conventional MDF laminates in design-forward segments.
REACH chemical restriction expansions are forcing adhesive reformulation across European supply chains. Manufacturers substituting soy-based binders for urea-formaldehyde resins report 8-12 month validation cycles with notified bodies. Wood-based desk components destined for corporate direct-purchase programs face the steepest compliance burden, with German and Dutch buyers leading enforcement scrutiny.
Direct-to-employee stipend models are displacing centralized corporate furniture procurement. Technology firms and professional services partnerships now issue annual workspace allowances rather than managing bulk orders. This pattern is most pronounced in United States coastal metros, where individual purchasers prioritize same-day delivery and white-glove assembly over volume discounts.
Home Office Desk Market Segmentation
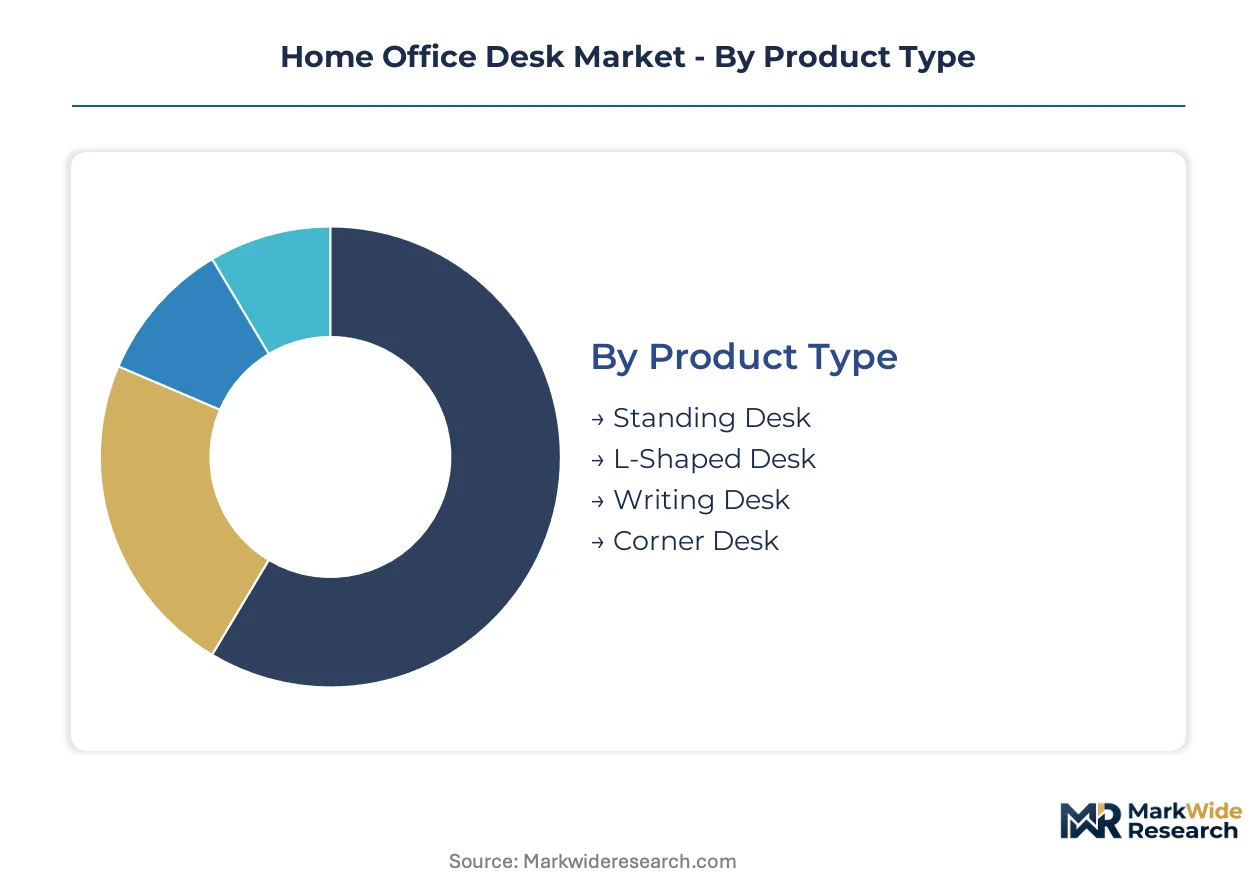
Segmentation in home office desk procurement reveals how purchasing power concentrates around ergonomic functionality and material compliance. Buyers now prioritize certified supply chains and adaptive configurations over traditional dimensional specifications.
Product Type:
Supply concentration in motorized actuator manufacturing favors vendors with captive electromechanical production, tilting procurement toward height-adjustable configurations.
- Standing Desk:Electromechanical lift systems with dual-motor columns support 80-150kg dynamic loads. Demand concentrates among remote-first technology firms in the United States seeking BIFMA-certified ergonomic configurations to reduce occupational health claims.
- L-Shaped Desk:Corner-optimized surface geometry maximizes residential floor plate efficiency through perpendicular work zones. German and Dutch buyers lead procurement of FSC-certified variants for corporate direct-purchase programs under EU Green Deal mandates.
- Writing Desk:Fixed-height traditional construction with minimal under-desk clearance requirements. Compact footprint suits urban residential constraints in Paris and London.
- Corner Desk:Triangular or pentagonal surface profiles designed for alcove installation. Budget-tier imports from Vietnam dominate mass-market distribution.
Today's leader: Standing Desk. Tomorrow's challenger: L-Shaped Desk.
Material:
Cost tier stratification separates premium certified hardwoods from commodity particleboard, with mid-market buyers gravitating toward composite alternatives that balance emission compliance against price points.
- Wood:Solid hardwood and engineered veneer construction with CARB Phase 2 or E1 emission certification. Premium residential buyers in California and New York specify FSC chain-of-custody documentation.
- Metal:Powder-coated steel or aluminum frame systems with recycled content verification. Industrial aesthetic preferences drive specification in converted loft spaces across Chicago and Berlin.
- Glass:Tempered safety glass surfaces with beveled edge treatment. Limited thermal mass makes this segment climate-sensitive; demand clusters in temperate coastal metros.
- Composite:Engineered substrates incorporating agricultural fiber or recycled polymer binders. Chinese manufacturers retooling for dual carbon goals are expanding export capacity for low-emission certified variants.
Composite materials are climbing the fastest as REACH-compliant adhesive reformulation accelerates.
Size:
Application-driven sizing reflects divergent use cases: compact residential nooks versus dedicated home office suites with multi-monitor arrays.
- Small:Surface dimensions below 1.0 meter length, typically 0.6-0.8 meter depth. Urban apartment dwellers in Tokyo and Singapore drive volume for space-constrained installations.
- Medium:Standard 1.2-1.4 meter length accommodating single monitor and peripheral array. Balances footprint against functionality for freelance professionals.
- Large:Extended 1.6-2.0 meter surfaces supporting dual-monitor or collaborative configurations. Executive home office installations in suburban United States markets.
- Adjustable:Modular frame systems permitting surface reconfiguration. Commercial procurement favors this segment for standardized fleet deployment across variable residential footprints.
Medium dimensions anchor current revenue. Adjustable systems are gaining share fastest through corporate stipend programs.
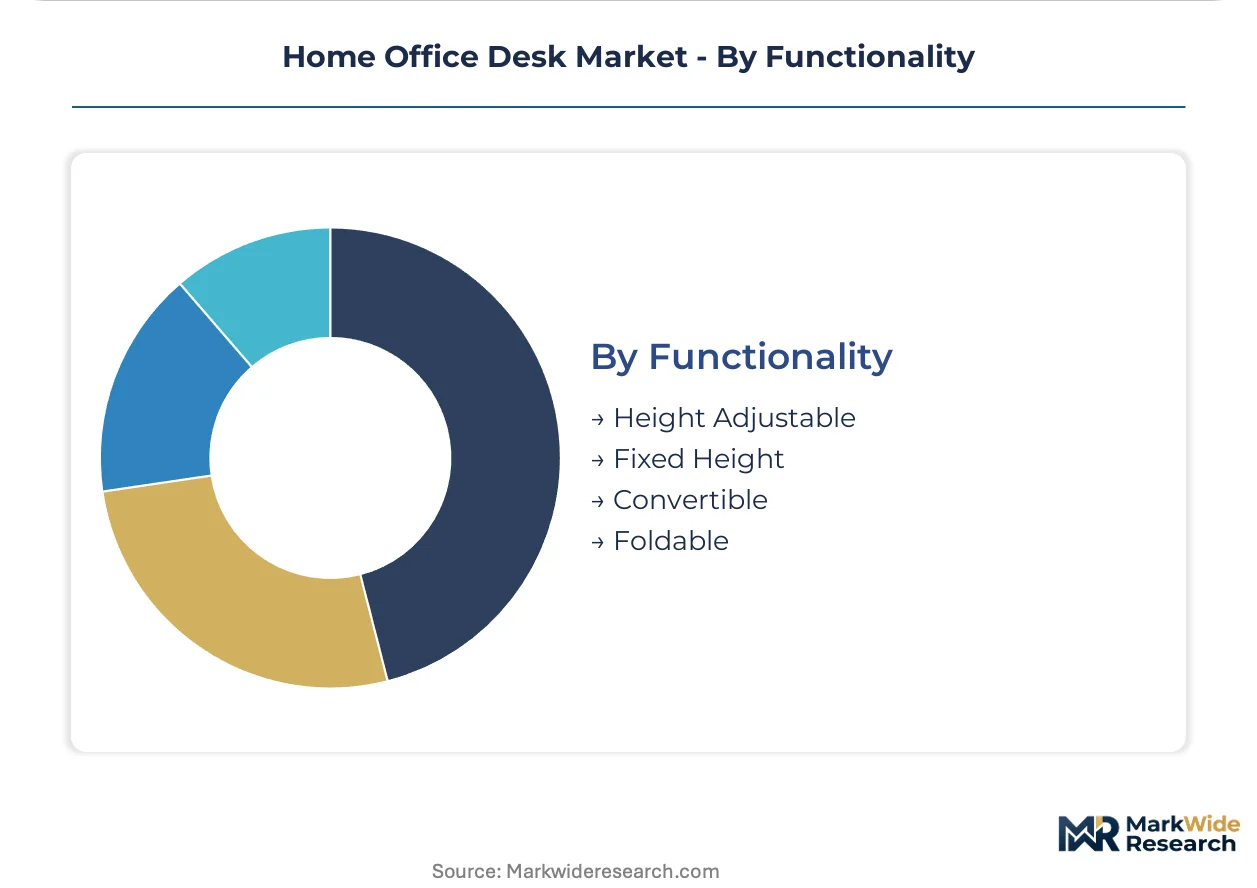
Functionality:
Customer type bifurcation separates enterprise procurement seeking fleet standardization from individual buyers prioritizing installation flexibility.
- Height Adjustable:Motorized or counterbalanced mechanisms enabling seated-to-standing transition. Technology sector stipend programs in Seattle and Austin concentrate demand for programmable memory presets.
- Fixed Height:Static frame construction at conventional 0.73-0.76 meter work surface elevation. Cost-sensitive volume procurement for temporary or secondary workspace installations.
- Convertible:Manual or assisted transformation between desk and alternative configurations. Murphy-bed integration and dining surface dual-use suit studio apartment constraints.
- Foldable:Collapsible frame systems with hinged legs or scissor mechanisms. Same-day delivery preference among individual purchasers in United States coastal metros favors flat-pack distribution economics.
Height Adjustable commands premium positioning. Foldable configurations are expanding most quickly through direct-to-employee procurement models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The home office desk industry traces its modern mass-market origins to post-war American suburban expansion, when dedicated residential workspaces first became standard in new housing stock. European ergonomic research subsequently shaped height-adjustable mechanisms, while East Asian manufacturing clusters later scaled cost-efficient production for global distribution.
United States
Technology sector stipend programs and freelance professional procurement drive sustained demand for BIFMA-certified standing desk configurations. EPA formaldehyde emission standards and CARB Phase 2 compliance requirements elevate material disclosure burdens for wood-based component suppliers. Seattle and Austin metropolitan clusters concentrate remote-first technology firm headquarters, anchoring premium ergonomic workstation procurement.
Germany
Corporate direct-purchase programs under EU Green Deal mandates consolidate procurement around FSC-certified L-shaped desk variants. ECHA REACH chemical restrictions and evolving Ecodesign requirements force continuous adhesive reformulation across domestic supply chains. The Rhine-Ruhr industrial corridor hosts specialized electromechanical actuator manufacturing, supporting captive supply for height-adjustable desk producers.
China
Dual carbon goals and domestic emission reduction targets accelerate retooling of composite material production lines for low-credential export capacity. MIIT industrial standards and GB certification requirements shape quality benchmarks for manufacturers serving international procurement channels. The Yangtze River Delta manufacturing cluster dominates global supply of motorized lift columns and engineered substrate components.
India
Production-linked incentive schemes attract contract manufacturers establishing domestic assembly for export-oriented ergonomic desk production. BIS quality certification and DGFT trade facilitation measures support integration into international corporate supply chains. The Delhi-NCR region concentrates emerging furniture manufacturing investment targeting European and North American procurement programs.
United Kingdom
London-based financial and professional services firms issue direct-to-employee workspace allowances, displacing centralized furniture procurement. CSRD sustainability disclosure requirements and evolving extended producer responsibility frameworks elevate circular design credentials in vendor selection. The Midlands manufacturing belt retains specialized hardwood component production for premium residential installations.
Home Office Desk Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and ergonomic functionality, creating a tiered structure where FSC chain-of-custody documentation and BIFMA testing separate price bands. The vendor base spans captive electromechanical producers, modular architecture specialists, and flat-pack volume distributors. Three archetypes dominate: integrated workstation systems providers, component-scale specialists, and direct-to-consumer platform operators. Competitive moves concentrate on strategic partnerships with technology sector procurement programs and portfolio diversification into sensor-enabled adaptive furniture.
Within the integrated systems tier, Steelcase Inc. and Herman Miller exemplify premium-positioned archetypes anchored in certified supply chains and ergonomic research lineage. Haworth Inc. occupies a position emphasizing modular architecture for variable residential footprints. Among scale-driven distributors, IKEA represents the flat-pack volume archetype, while Wayfair Inc. anchors platform-based marketplace positioning. UPLIFT Desk exemplifies the specialized standing desk configuration segment. These named entities illustrate strategic positioning across margin tiers without exhausting the competitive set.
| Leading Market Players |
|---|
| Steelcase Inc. |
| Herman Miller |
| Haworth Inc. |
| HNI Corporation |
| IKEA |
| Ashley Furniture Industries |
| La-Z-Boy Incorporated |
| Wayfair Inc. |
| UPLIFT Desk |
| Others |
Pricing and Supply Chain Analysis
Dual-motor electromechanical lift system adoption is compressing cost curves for height-adjustable configurations while simultaneously concentrating procurement power among vendors with captive actuator manufacturing in China and Germany. This technological transition simultaneously elevates entry barriers for component-dependent assemblers and rewards integrated producers with pricing power across premium ergonomic segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified hardwood configurations from CARB-compliant particleboard alternatives and uncertified import tiers. Price differentiation rests on BIFMA ergonomic certification depth and after-sales assembly service bundling. Cost compression in economy-tier laminate surfaces is intensifying because Chinese composite producers are absorbing REACH-compliant adhesive reformulation expenses to maintain export share. Freelance professionals purchasing through direct-to-employee stipend programs exhibit highest price sensitivity, while technology sector procurement officers prioritize certified supply chains over unit cost.
Supply Chain Analysis
Ocean freight rate volatility between Southeast Asian hardwood component ports and North American distribution centers is reshaping inventory carrying strategies for mid-tier assemblers. Manufacturing gravity centers on China's Yangtze River Delta for motorized lift columns, Vietnam's Binh Duong province for hardwood desktop fabrication, and Germany's Rhine-Ruhr corridor for precision electromechanical actuators. Raw material sourcing draws from Malaysian rubberwood plantations, Chinese engineered substrate facilities, and European steel recycling streams. Single-source vulnerability concentrates in dual-motor column supply from Yangtze Delta producers. Distribution runs through direct-to-employee platform fulfillment, white-glove assembly networks, and traditional furniture retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where hybrid work permanence has shifted procurement criteria toward certified ergonomic specifications rather than temporary accommodation pricing. Premium positioning now depends on documented supply chain transparency and adaptive functionality rather than dimensional attributes alone.
For Market Incumbents: Cement market position by deepening captive supply of electromechanical actuators through backward integration into Rhine-Ruhr manufacturing corridors or joint ventures with Yangtze Delta specialists. Invest in FSC chain-of-custody documentation depth to defend margin position against emerging composite material entrants from India's PLI-supported production bases. Prioritize BIFMA certification maintenance as testing facility capacity constraints extend competitor launch timelines.
For New Entrants and Emerging Players: EU Green Deal procurement mandates in Germany and France open a window for circular-design specialists offering take-back program integration and mycelium-based composite surfaces at 15-20% price premiums. Target Netherlands and UK professional services firms issuing direct-to-employee stipends rather than competing for centralized corporate procurement. Pursue same-day delivery partnerships with coastal metro logistics networks to bypass incumbent distribution relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier particleboard assemblers facing formaldehyde compliance cost compression without captive electromechanical supply. Long-term viability favors targets with validated REACH-compliant adhesive formulations and established technology sector procurement relationships. Watch BIFMA testing facility expansion announcements as an inflection indicator for standing desk mechanism supply capacity normalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Electromechanical Manufacturing | Backward integration into Yangtze Delta or Rhine-Ruhr actuator production secures supply priority during BIFMA certification backlogs. |
| FSC Chain-of-Custody Certification | Documentation depth satisfies EU Green Deal corporate procurement mandates across Germany and Dutch direct-purchase programs. |
| Smart Sensor Integration | Occupancy detection convergence with height-adjustment motors enables posture coaching subscription revenue streams. |
| Circular Design Certification | Take-back program readiness positions vendors for extended producer responsibility frameworks drafting across EU member states. |
| Direct-to-Employee Platform Partnerships | Stipend model alignment captures United States coastal metro procurement shifting from centralized bulk orders. |
Research Methodology
Direct dialogue with furniture manufacturing executives, electromechanical component suppliers, corporate procurement officers at technology firms, ergonomic certification laboratory directors, and logistics platform operators grounded qualitative assessment. Secondary validation drew from EPA formaldehyde emission filings, ECHA REACH substance database updates, FSC chain-of-custody registry records, and BIFMA testing facility capacity reports. Bottom-up demand modeling across product type, material, size, and functionality segments triangulated against top-down macroeconomic indicators for hybrid work infrastructure investment.
Bottom-up volume estimation built from segment-level procurement patterns across remote-first technology firms, freelance professional stipend programs, and corporate direct-purchase initiatives. Top-down constraints applied GDP-correlated workspace investment elasticity and residential construction permit data across the analysis window. CAGRs derived from logistic curve fitting to technology adoption patterns for standing desk configurations and composite material substitution rates. Modeled inputs included REACH chemical restriction expansion timelines and India's PLI scheme capacity buildout assumptions.
Revisions become necessary when BIFMA testing facility capacity constraints extend beyond modeled normalization assumptions, when ECHA substance database updates trigger unanticipated adhesive reformulation requirements, or when shipping rate volatility between Southeast Asian component ports and North American distribution centers exceeds historical bands. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Canada Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
United States Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Rental Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Japan Office Furniture Market